
 Global High Temperature Thermoplastics (Htts) Market | 2026-2036
Global High Temperature Thermoplastics (Htts) Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Thermoplastics (Htts) Market Intelligence
The AS9100 certification cycle for aerospace components is rotating qualification requirements towards materials with superior thermal and chemical resistance. Victrex plc specializes in PEEK-based solutions for demanding environments where such qualifications are mandatory. Solvay leverages its extensive portfolio of specialty polymers to serve multiple high-performance sectors, including aerospace and healthcare. Meanwhile, DuPont competes with a wide range of engineering plastics and polymer solutions for automotive and electronics applications, navigating different qualification pathways like IATF 16949.
High temperature thermoplastics are a class of polymers capable of maintaining mechanical properties at continuous service temperatures exceeding 150°C. These materials, including PEEK and Polyimide, offer exceptional chemical resistance and dimensional stability, making them suitable for metal replacement in harsh operating conditions. Among product types, Polyetheretherketone (PEEK) commands a premium due to its best-in-class performance profile. In terms of application, automotive parts represent a significant volume segment, driven by under-the-hood and electric vehicle battery component needs.
Material selection is heavily influenced by sector-specific regulations, such as the FAA's flammability standards for aerospace components in the United States. The European Chemicals Agency (ECHA) governs substance use under REACH, impacting polymer formulations available in the EU. In Asia, China's NMPA enforces strict biocompatibility requirements for medical-grade polymers used in devices. Stakeholders must therefore navigate a complex matrix of performance requirements and regional compliance mandates to secure market position.
Market Dynamics
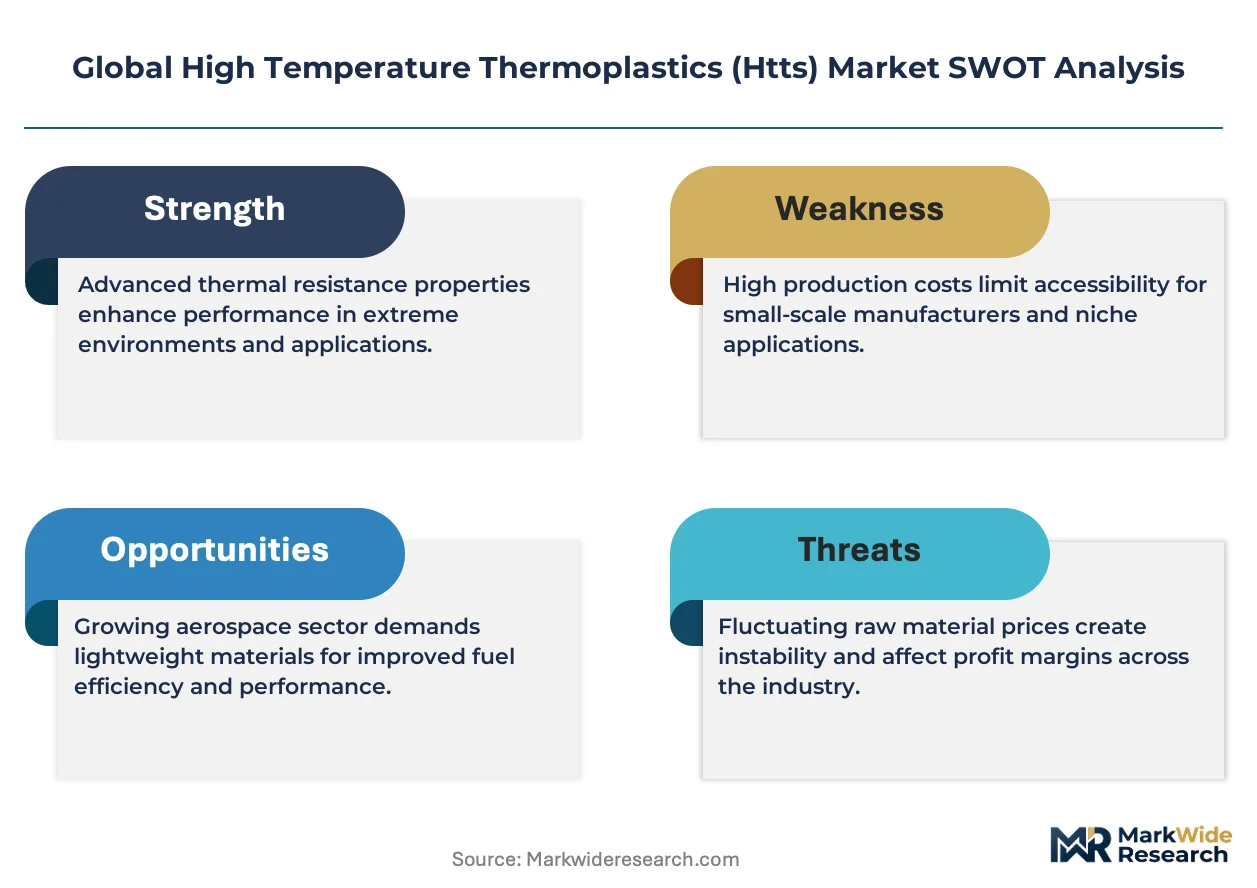
The central force shaping the high temperature thermoplastics market is the regulatory-driven mandate for lightweighting in the automotive and aerospace sectors. Stricter emissions standards from the EPA in the United States and the EU Green Deal are compelling a direct replacement of metals in harsh, high-temperature environments.
Growth Catalysts
- Automotive Electrification:The transition to electric vehicles creates substantial demand for HTTs in battery components, connectors, and busbars, where high thermal stability, electrical insulation, and chemical resistance are critical for safety and performance.
- Aerospace Modernization:Demand for lightweight components to improve fuel efficiency and reduce emissions in new aircraft programs drives the adoption of HTTs like PEEK, which meet stringent AS9100 qualification requirements for thermal and chemical resistance.
- Stringent Environmental Regulations:Policies such as the EU's REACH framework and emission targets in China are pushing industries to adopt materials that enable more efficient, lighter, and durable final products, directly benefiting high-performance polymers.
Market Restraints
- High Material and Processing Costs:The premium pricing of base resins like PEEK and Polyimide, combined with the energy-intensive processing required, presents a significant cost barrier compared to conventional engineering plastics and metals like aluminum.
- Specialized Manufacturing Requirements:Processing HTTs demands high-temperature molding equipment and specific tooling expertise, limiting adoption to well-capitalized manufacturers and creating a barrier for smaller component fabricators.
- Competition from Thermosets:In certain ultra-high-performance applications, advanced thermoset composites and ceramics offer superior dimensional stability or higher temperature ceilings, presenting a substitution threat in niche segments.
Strategic Opportunities
- Medical Device Innovation:Strict biocompatibility standards from regulators like China's NMPA and the US FDA create opportunities for medical-grade HTTs in sterilizable surgical instruments, implantables, and diagnostic equipment.
- Industrial Process Downsizing:The chemical processing and oil and gas industries offer an opportunity for HTTs to replace corrosion-prone metal components in pumps, seals, and valves, reducing maintenance downtime and extending service life.
- Additive Manufacturing Integration:The development of HTT filaments and powders for 3D printing enables the rapid prototyping and production of complex, low-volume parts for aerospace and custom medical applications, opening new design possibilities.
Industry Challenges
- Lengthy Qualification Cycles:The extensive testing and validation timelines required to meet sector-specific certifications, such as IATF 16949 for automotive and FAA standards for aerospace, create long lead times and high development costs.
- Complex Regulatory Matrix:Manufacturers must navigate a fragmented landscape of regional chemical regulations, including REACH in Europe and various GB standards in China, which impacts polymer formulation and global supply chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Thermoplastics (Htts) Market |
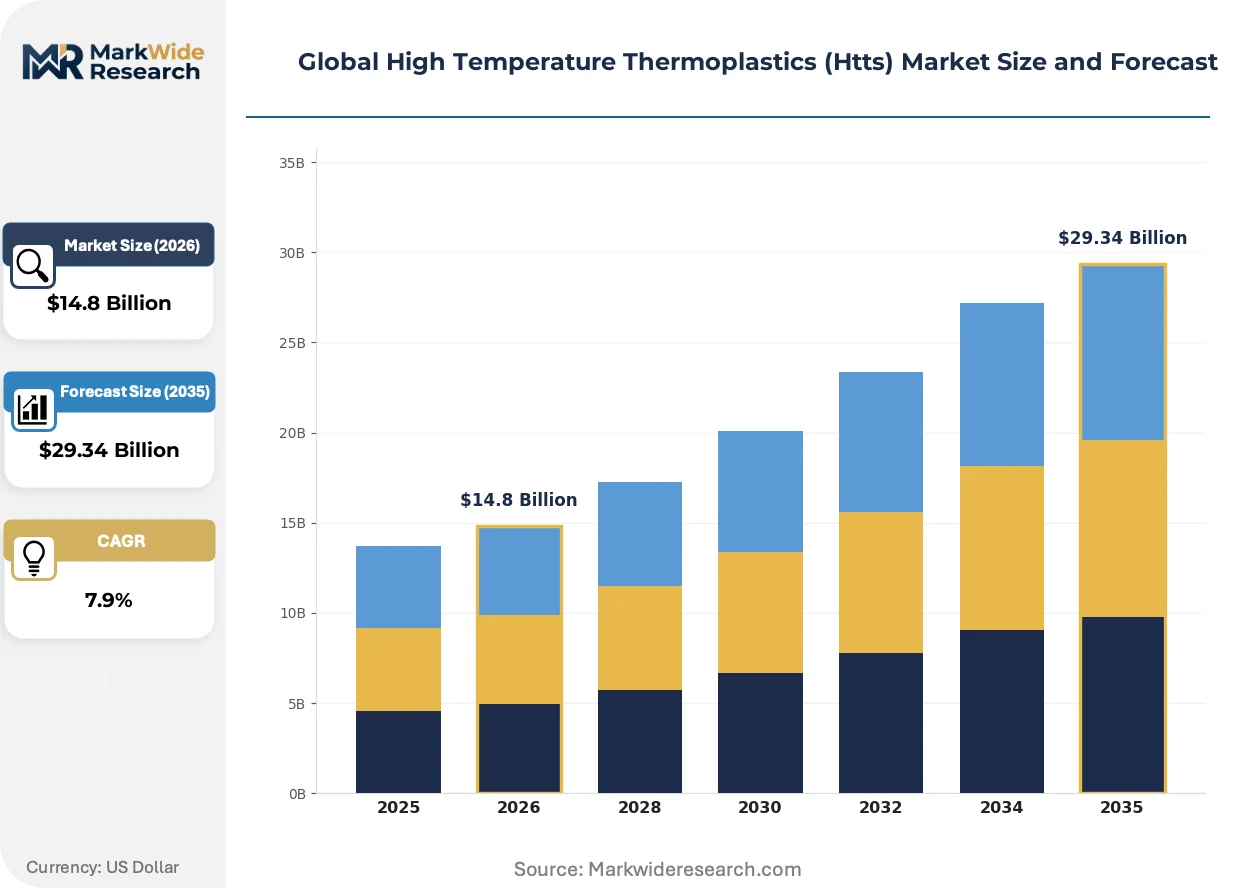
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyetheretherketone, Polyphenylene Sulfide, Polyimide, Polysulfone, Polyetherimide Application: Aerospace Components, Electrical Insulation, Automotive Parts, Medical Devices, Industrial Machinery End User Industry: Electronics Manufacturers, Aircraft Builders, Vehicle Assemblers, Healthcare Equipment Providers, Heavy Equipment Fabricators Processing Technology: Injection Molding, Extrusion, Compression Molding, 3D Printing, Blow Molding |
| Companies Covered | Solvay, DuPont, Celanese Corporation, Victrex plc, SABIC, BASF, Arkema, Evonik Industries, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Thermoplastics (Htts) Market Strategic Shifts & Innovations
Material science advancements are enabling HTTs to penetrate applications previously dominated by metals. This shift is driven by a convergence of new composite formulations and manufacturing techniques that unlock superior strength-to-weight ratios, meeting intense performance demands from regulated industries.
Reinforced thermoplastic composites, incorporating carbon or glass fibers, are engineered to deliver strength and stiffness comparable to metals. The aerospace and defense sectors are rapidly adopting these materials for structural and semi-structural components, moving beyond their traditional use in interior parts. This technological evolution is decomposing the established boundary between polymers and load-bearing metals like aluminum in critical, high-stress designs.
The European Union's REACH regulation governs the registration, evaluation, and authorization of chemical substances, directly impacting polymer formulations. Its strict requirements can restrict or ban certain additives and monomers, forcing material suppliers to invest in R&D for compliant alternatives. The specialty polymers segment is most affected, as producers must ensure their entire portfolio for the EU market avoids substances of very high concern (SVHCs).
A notable behavioral shift is the move from material-specific blueprints to performance-based procurement in component design. This change disrupts the legacy engineering practice of defaulting to known metals, empowering material selectors to propose novel HTT solutions that satisfy functional targets like thermal cycling, weight, and chemical inertness. This trend is most prominent in the North American and European automotive sectors, especially for developing next-generation electric vehicle platforms.
Global High Temperature Thermoplastics (Htts) Market Segmentation
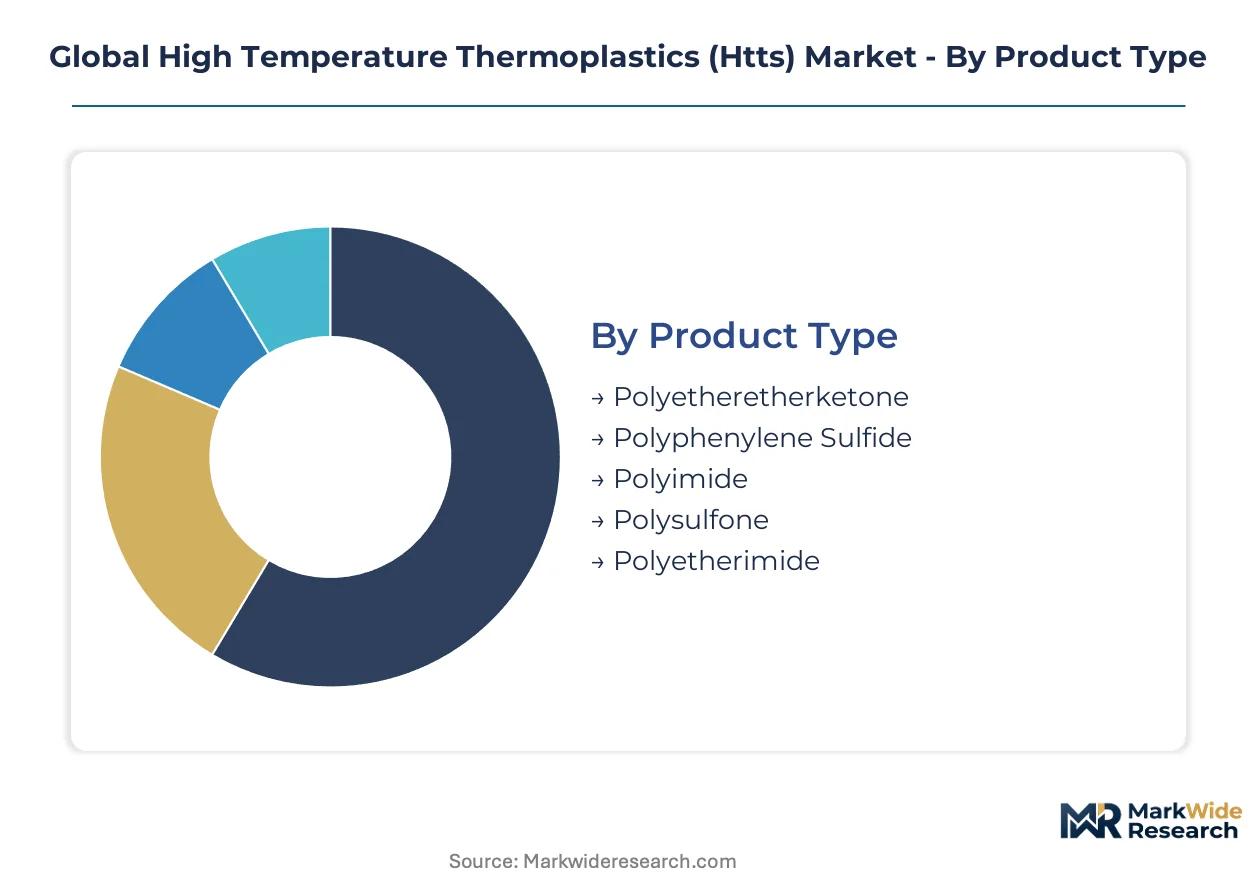
Understanding the market's segmentation reveals how specific material properties and processing methods address distinct industrial requirements. Each segment reflects unique performance demands, regulatory compliance pathways, and cost sensitivities across various end-use sectors.
Product Type:
Margin pools in high temperature thermoplastics are influenced by material performance and manufacturing complexity.
- Polyetheretherketone (PEEK):Polyetheretherketone offers superior mechanical strength, chemical resistance, and continuous service temperatures up to 260°C. Aerospace and medical devices drive demand, with AS9100 qualifications and China's NMPA biocompatibility standards.
- Polyimide (PI):Polyimide offers exceptional thermal stability, creep resistance, and inherent flame retardancy, maintaining properties above 300°C. Aerospace modernization and advanced electronics in the US and Germany drive adoption.
- Polyphenylene Sulfide (PPS):PPS provides excellent chemical resistance, high stiffness, and dimensional stability. Automotive under-the-hood components and industrial process equipment utilize PPS.
- Polysulfone (PSU):Amorphous polysulfones offer transparency, high heat deflection, and good hydrolytic stability. Medical instruments and food contact applications in Europe utilize PSU.
- Polyetherimide (PEI):PEI combines high strength, stiffness, chemical resistance, and good electrical insulation. Electronics manufacturers and aircraft builders in Asia specify PEI for connectors and interior components.
The dominant share belongs to Polyetheretherketone, while Polyimide is closing the gap fastest.
Application:
Application scope shapes material selection, dictating required performance attributes and regulatory adherence for HTTs.
- Automotive Parts:HTTs are critical for under-the-hood components, EV battery systems, and structural elements needing high thermal stability and chemical resistance. EPA and EU Green Deal emissions standards compel vehicle assemblers in Germany and Japan to adopt these materials.
- Aerospace Components:These materials are used in structural brackets, interior parts, and engine components to reduce weight and improve fuel efficiency. FAA flammability standards and AS9100 drive material innovation for aircraft builders in the US and France.
- Electrical Insulation:HTTs provide robust electrical properties, thermal stability, and chemical inertness for connectors, circuit boards, and wire coatings. Chinese electronics manufacturers rely on these polymers.
- Medical Devices:Sterilizable surgical instruments, implantable devices, and diagnostic equipment use HTTs for biocompatibility and chemical resistance. US FDA and China's NMPA enforce standards.
- Industrial Machinery:HTTs replace corrosion-prone metals in pumps, valves, and seals within chemical processing and oil and gas industries. Heavy equipment fabricators in the Middle East adopt these.
Automotive Parts is central to volume, while Aerospace Components drives innovation.
End User Industry:
Customer type influence determines qualification pathways and supply chain dynamics for HTTs.
- Vehicle Assemblers:Automotive manufacturers integrate HTTs into EV battery components, engine parts, and structural elements. IATF 16949 certification is mandatory for suppliers to major automotive brands in Germany and the US.
- Aircraft Builders:Aerospace companies utilize HTTs for lightweight structural components, interior panels, and engine parts to enhance fuel efficiency. AS9100 and FAA flammability standards are paramount for aircraft builders in France and the UK.
- Electronics Manufacturers:HTTs serve in connectors, circuit boards, and insulation for high-performance electronic devices. South Korean and Taiwanese manufacturers require stringent electrical and thermal specifications.
- Healthcare Equipment Providers:Medical device companies specify biocompatible HTTs for sterilizable instruments, implantable devices, and diagnostic equipment. US FDA and European EMA govern material selection.
- Heavy Equipment Fabricators:HTTs are incorporated into components for industrial pumps, valves, and seals. Oil and gas companies in Saudi Arabia and Canada use these for chemical resistance and high temperature.
Vehicle Assemblers dictate material specifications, while Aircraft Builders focus on durability.
Processing Technology:
Cost efficiency and design complexity dictate the preferred processing technology for HTTs.
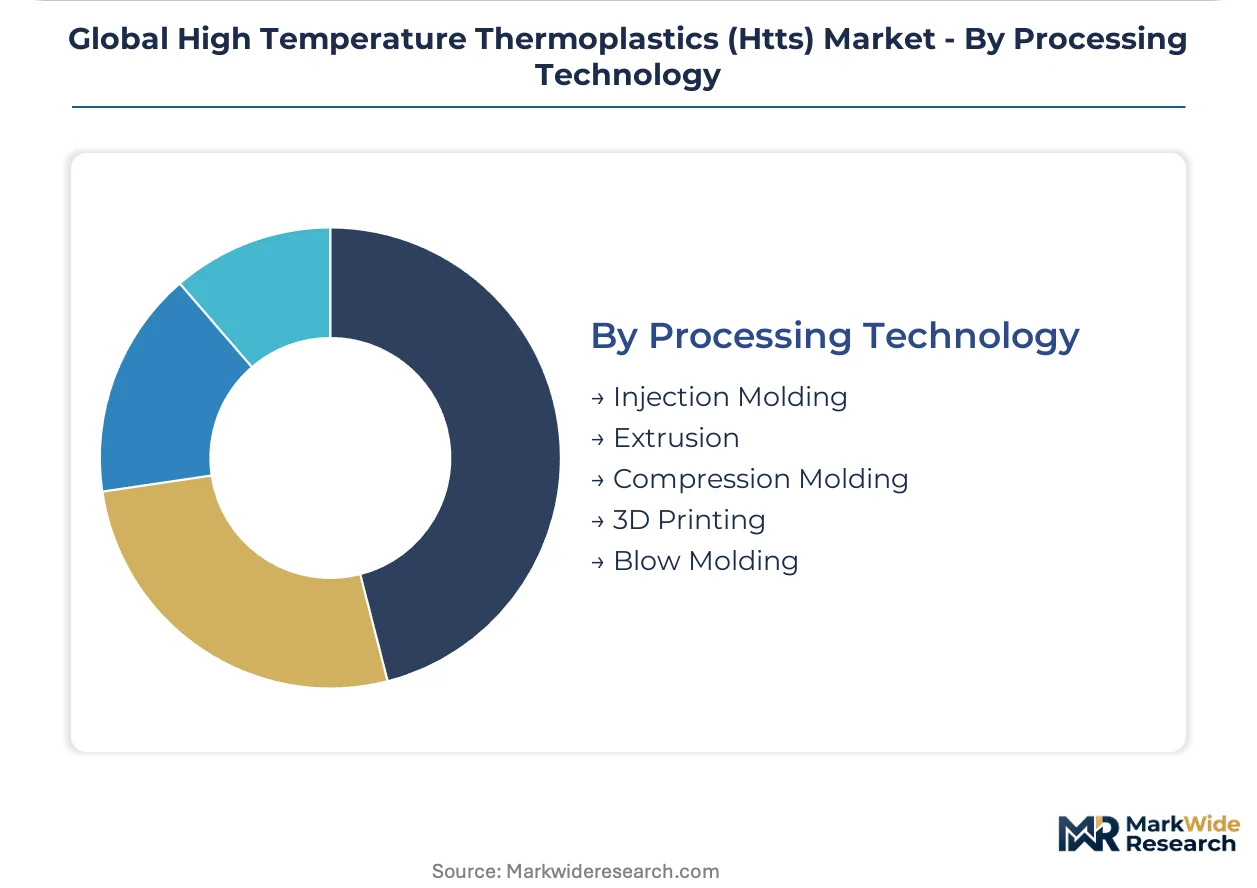
- Injection Molding:Injection molding, a high-volume manufacturing method, produces complex, intricate parts with excellent dimensional accuracy. Automotive components and electrical connectors in China and Mexico leverage it for HTTs.
- 3D Printing:Additive manufacturing enables rapid prototyping and production of complex, customized geometries for low-volume, high-value applications. Aerospace and medical device sectors in the US and Germany increasingly adopt 3D printing for HTT parts.
- Extrusion:Extrusion creates continuous profiles like rods, sheets, and films, used for stock shapes. Industrial applications and electrical insulation benefit from extruded HTT forms.
- Compression Molding:Compression molding suits large, thick-walled parts and composite structures, offering good mechanical properties. Aerospace structural components and industrial seals use compression molded HTTs.
- Blow Molding:Blow molding is employed for hollow parts like containers, ducts, and complex shapes. Automotive fluid reservoirs and industrial piping utilize blow-molded HTTs.
Injection Molding enables mass production, while 3D Printing facilitates complex geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter emissions standards from regulatory bodies like the EPA and the EU Green Deal are driving the adoption of high temperature thermoplastics globally. These policies compel automotive and aerospace manufacturers to integrate lightweight, high-performance materials. This shift is particularly evident in regions with significant manufacturing bases for these industries.
China
Demand for high temperature thermoplastics in China stems from its expansive electronics and automotive sectors. China's NMPA enforces strict biocompatibility standards for medical-grade polymers, influencing material selection. The Yangtze River Delta region drives HTT consumption for EV battery components and consumer electronics manufacturing.
United States
The United States market for HTTs is driven by aerospace component manufacturing and medical device innovation. The FAA's flammability standards mandate specific HTT use in aircraft interiors and structural parts. Silicon Valley and the aerospace clusters in Seattle and Wichita integrate advanced HTTs for next-generation designs.
Germany
European environmental policies, such as the EU Green Deal, accelerate HTT adoption in the automotive sector. KBA regulations for vehicle safety and performance influence material choices for under-the-hood applications. Bavaria's automotive industry and the mechanical engineering hub in Baden-Württemberg are key consumers of high-performance polymers.
Japan
Japanese automotive manufacturers increasingly specify HTTs for lightweighting and thermal management in advanced vehicles. METI industrial policies encourage material innovation for high-performance components across various sectors. Tokyo's electronics manufacturing and Nagoya's automotive cluster drive demand for advanced HTTs in connectors and engine parts.
France
Aerospace component manufacturing and high-speed rail applications are significant demand drivers for HTTs in France. EASA certification requirements for aircraft materials ensure stringent performance and safety standards for polymer use. Toulouse, a major aerospace hub, integrates advanced HTTs into structural brackets and interior panels for new aircraft programs.
Global High Temperature Thermoplastics (Htts) Market Key Industry Players
Listed leaders compete with private specialists across the high temperature thermoplastics market, which exhibits a tiered structure based on product complexity and application focus. The market is moderately consolidated at the base resin production level, where a few large chemical companies dominate. These dominant players often engage in strategic partnerships and capacity expansions to reinforce their market positions and broaden their product portfolios. Mid-sized and niche players, conversely, focus on specialized formulations and downstream processing, often targeting specific high-value applications.
Among established material suppliers, Solvay, DuPont, and Victrex plc exemplify the diverse approaches to market penetration. Solvay, a global chemical company, anchors its position through a broad portfolio of specialty polymers across multiple high-performance sectors. DuPont, an American multinational, competes with a wide range of engineering plastics, often targeting automotive and electronics applications. Victrex plc, a UK-based specialist, focuses primarily on PEEK-based solutions for demanding environments like aerospace and medical devices. These entities collectively shape product innovation and market standards.
| Leading Market Players |
|---|
| Solvay |
| DuPont |
| Celanese Corporation |
| Victrex plc |
| SABIC |
| BASF |
| Arkema |
| Evonik Industries |
| Toray Industries |
| Others |
Cost & Logistics Intelligence
Large-scale production of high temperature thermoplastics, particularly PEEK, drives significant capital expenditure, creating barriers to entry. This concentration in manufacturing capacity directly influences pricing power and establishes high price floors for advanced polymer solutions.
Pricing Analysis
Certification level, such as AS9100 for aerospace or NMPA biocompatibility for medical devices, creates the primary spread in high temperature thermoplastics pricing. The dominant pricing structure is value-based, reflecting performance profiles where PEEK commands a premium over PPS. Price differentiation stems from material grade, brand reputation, and the extensive qualification costs associated with these polymers. Pricing softness affects volume segments like automotive parts due to competition from conventional engineering plastics, while aerospace and medical device sectors exhibit lower price sensitivity.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized monomers and additives, significantly impact the high temperature thermoplastics supply chain. Production of base resins concentrates in Germany and the United States, with significant downstream processing in China and Japan. The supply chain relies on specialized chemical intermediates and high-performance fibers for reinforced composites. Lengthy qualification cycles required by regulators like the FAA and ECHA create single-source vulnerabilities for highly specified materials. Distribution runs primarily through direct sales to large OEMs and specialized technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high temperature thermoplastics market presents a service-attach opportunity, particularly in technical support and application engineering. This recurring revenue layer, critical for navigating complex regulatory compliance and material selection, expands faster than base resin sales.
For Market Incumbents:Consolidate market share through strategic acquisitions of niche formulators specializing in additive manufacturing filaments or medical-grade compounds. This defends against emerging competition from advanced thermosets and mitigates margin pressure from high material costs. Invest in vertical integration into processing capabilities, particularly high-temperature injection molding, to control quality and reduce lead times for aerospace components. Strengthen R&D efforts in compliant alternatives for EU REACH-restricted substances.
For New Entrants and Emerging Players:Differentiate on rapid prototyping capabilities and custom formulation services for additive manufacturing applications. Target the nascent market for complex, low-volume medical implantables and customized aerospace parts in the United States and Germany. A focused go-to-market angle involves direct engagement with design engineers at early-stage product development, offering specialized material solutions.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized formulators offering comprehensive material qualification and ongoing technical support for aerospace and medical applications. The long-term viability of high temperature thermoplastics remains strong over the next decade, driven by regulatory mandates for lightweighting and electrification. Acquisition targets should prioritize mid-sized companies with proprietary processing expertise or strong intellectual property in niche PEEK or Polyimide formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in PEEK Production | Addresses growing demand from aerospace modernization and electric vehicle battery components in China. |
| Investment in Additive Manufacturing R&D | Unlocks rapid prototyping and customized production for complex medical devices and aerospace parts in the US. |
| Partnership for Regulatory Compliance | Navigates the complex matrix of ECHA REACH and China NMPA standards, ensuring market access for new formulations. |
| Development of Reinforced Composites | Expands HTT application into structural components, displacing metals in automotive and aerospace sectors. |
| Geographic Expansion into Southeast Asia | Captures new electronics manufacturing demand and automotive growth in emerging markets like Vietnam. |
Research Approach
Operator-level perspectives from R&D directors, OEM procurement leads, application engineers, and regulatory specialists anchored the qualitative base for this analysis. Primary interviews were combined with extensive secondary validation from EPA and ECHA regulatory documents, company financial filings, and industry association reports. A rigorous bottom-up and top-down triangulation process ensured data consistency.
Sensitivity analysis was applied to key variables, evaluating potential impacts on market projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, and processing technology. Forecasted CAGRs were derived integrating historical trends with anticipated regulatory shifts. Industry-specific inputs included projected demand for EV battery components and new aircraft build rates.
The analysis sits within stated boundaries; outcomes outside the anticipated regulatory landscape or material science breakthroughs would require recalibration. Forecasts reflect assumptions regarding global supply chain stability and the pace of automotive electrification. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Mono Methyl Ether of Hydroquinone (MEHQ) Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
High-Purity Nitrogen Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market