
 High Molecular Weight Polyisobutylene Market | 2026-2036
High Molecular Weight Polyisobutylene Market Size, Share, and Industry Trends Forecast 2026-2036
High Molecular Weight Polyisobutylene Market Analysis
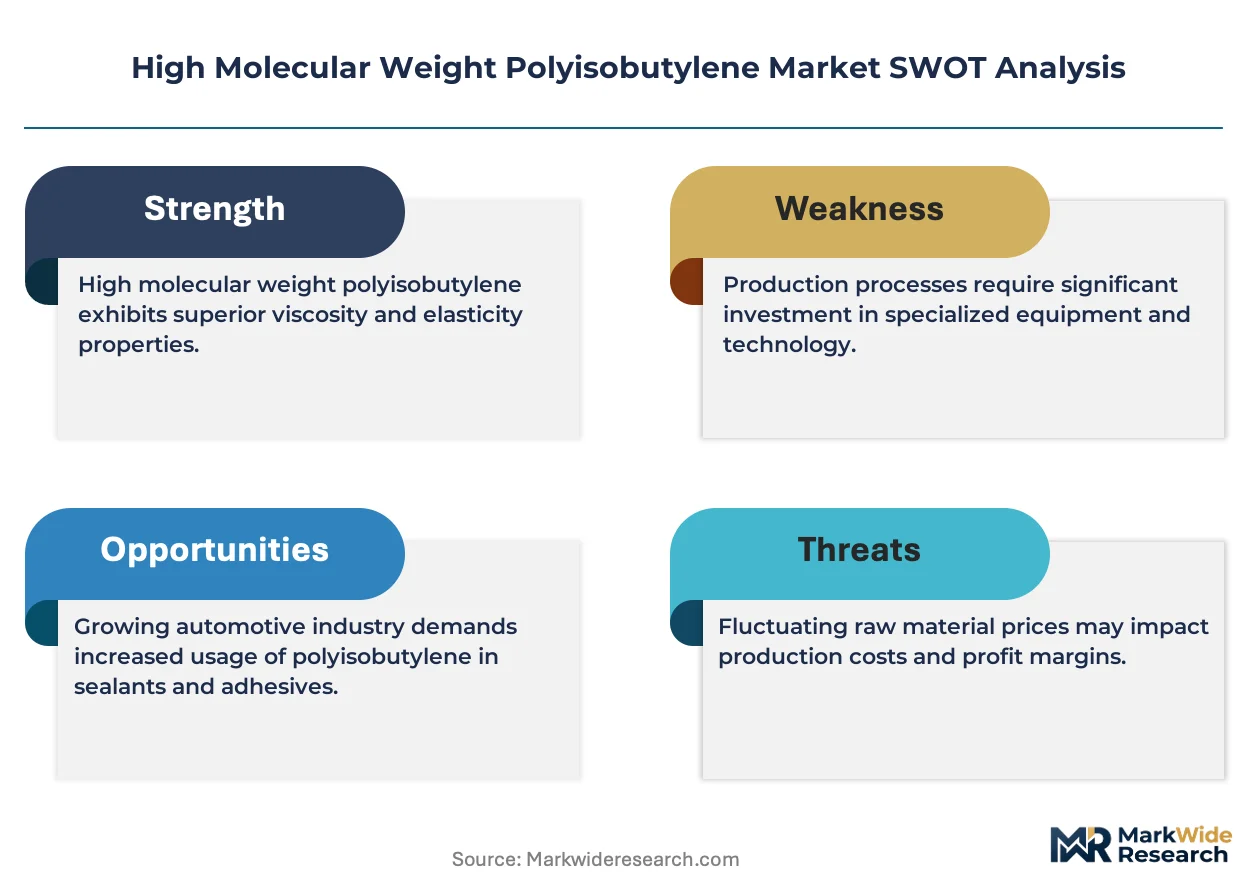
Capital-intensity divergence between integrated petrochemical giants and specialty additive blenders is reorganizing competitive tiers in high molecular weight polyisobutylene supply. INEOS Oligomers leverages its backward integration into C4 feedstock streams to sustain margin resilience against raw material volatility. BASF SE anchors its position through proprietary polymerization catalyst technology that differentiates viscosity-grade portfolios for lubricant formulators.
High molecular weight polyisobutylene denotes a synthetic elastomer with molecular weights exceeding 1000 kg/mol, produced via cationic polymerization of isobutylene using Lewis acid catalysts, valued chiefly for impermeability, damping, and oxidative stability in industrial formulations. The lubricants category dominates volume absorption due to long-drain engine oil specifications that demand shear-stable viscosity modifiers. Sealants represent a structurally attractive growth pocket where fuel tank and window bonding applications in automotive assembly command formulation premiums over commodity adhesives.
EPA fuel economy standards and REACH Annex XVII restrictions on persistent organic pollutants jointly constrain formulation chemistry while redirecting R&D spending toward low-VOC, high-performance grades. ECHA substance evaluation protocols and FDA indirect food contact clearances under 21 CFR 177 further segment market access by end-use certification burden. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate product registration pipelines against regional compliance timelines.
Market Dynamics
Automotive electrification is restructuring demand profiles across polyisobutylene applications, as battery encapsulation adhesives displace conventional engine-bay sealants in procurement specifications. This shift concentrates purchasing power among EV-dedicated tier-one suppliers while degrading legacy lubricant additive volumes.
Growth Catalysts
- REACH Annex XVII VOC limits:Tightening European emission thresholds accelerate solvent-free adhesive adoption in automotive assembly lines, expanding high-purity grade requirements.
- Electric vehicle battery encapsulation:Thermal management demands in lithium-ion packs drive specialized sealant procurement from polymer compounders serving EV platforms.
- German industrial corridor concentration:Ludwigshafen and Leverkusen polymer clusters anchor regional supply security for tier-one automotive suppliers.
Market Restraints
- C4 feedstock volatility:Crude-derived isobutylene supply swings compress margins for non-integrated blenders lacking captive refinery streams.
- Supply concentration in integrated petrochemicals:Backward-integrated producers control critical polymerization catalyst technology, limiting specialty blender market access.
- Shear stability limitations in high-temperature formulations:Molecular weight degradation above 150°C restricts deployment in next-generation engine oils.
Strategic Opportunities
- India automotive manufacturing expansion:Domestic EV production incentives under the PLI scheme create localized demand for battery-grade sealant compounds.
- Food-contact barrier films:FDA 21 CFR 177 clearances enable migration into modified atmosphere packaging applications beyond traditional industrial uses.
- Reactive hot-melt convergence with UV-curing:Hybrid adhesive technologies open formulation partnerships between polyisobutylene suppliers and radiation-cure equipment manufacturers.
Industry Challenges
- Cationic polymerization expertise scarcity:Lewis acid catalyst handling and molecular weight control require specialized chemical engineering talent concentrated at legacy production sites.
- ECHA substance evaluation timelines:Extended registration dossier reviews delay market entry for new viscosity-grade variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Molecular Weight Polyisobutylene Market |
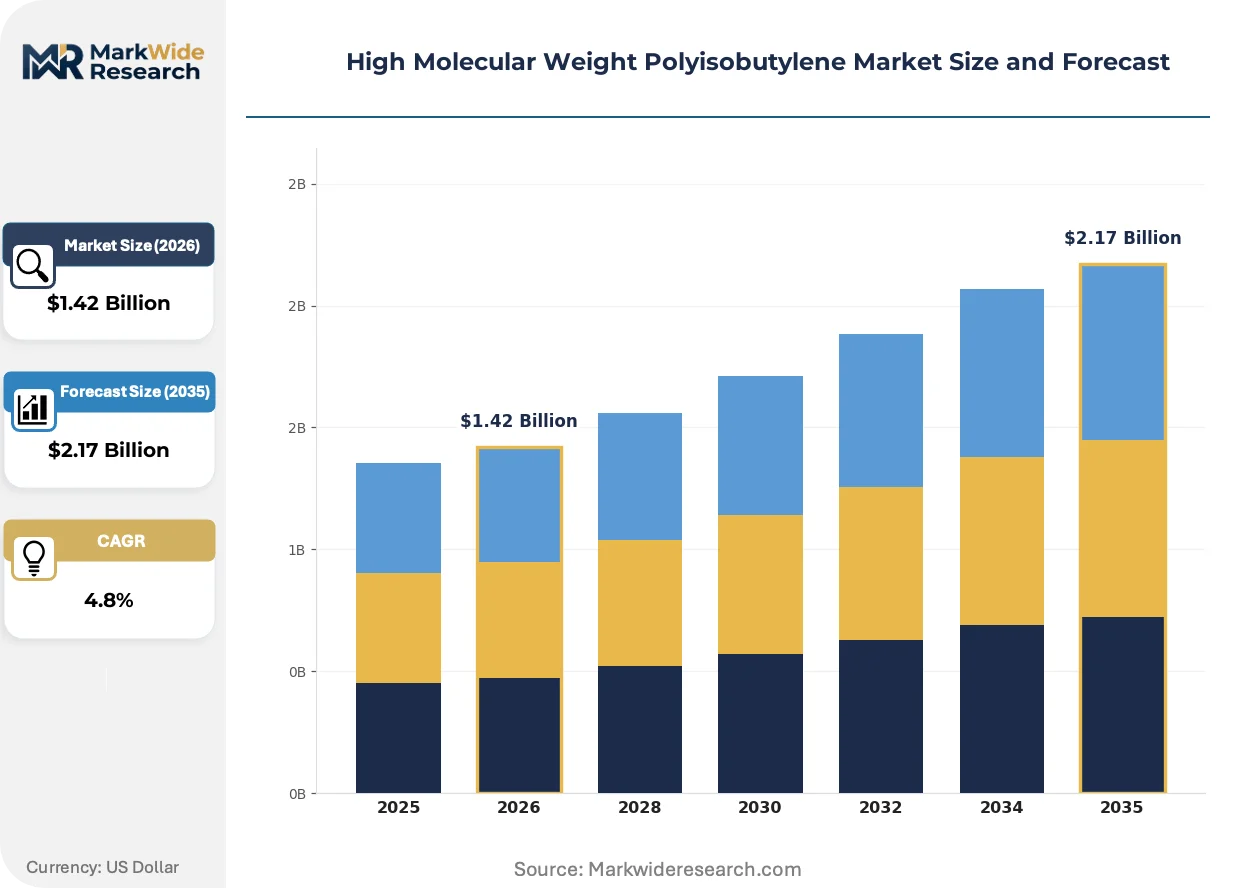
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Sealants, Coatings, Lubricants End User: Automotive, Adhesive Manufacturers, Construction, Oil & Gas Application: Fuel Additives, Engine Oils, Tire Manufacturing, Rubber Products Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | INEOS Oligomers, TRiiSO, BASF SE, Daelim, CHEMSPEC, LTD., ExxonMobil Chemical, TPC Group, Lanxess AG, Lubrizol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Molecular Weight Polyisobutylene Market Emerging Trajectories
Formulation chemistry is pivoting toward reactive and hybrid systems that merge polyisobutylene's damping properties with rapid-cure capabilities demanded by automated assembly lines.
Metallocene-catalyzed polymerization is fragmenting the conventional cationic production landscape. This technology delivers narrower molecular weight distribution for precision viscosity targeting. Specialty lubricant formulators in Germany and Japan are adopting metallocene grades for long-drain engine oils. The shift is fragmenting supplier tiers between commodity cationic producers and premium metallocene specialists.
EPA fuel economy standards are compressing formulation windows for viscosity modifiers. The regulations mandate lower high-temperature high-shear viscosity without sacrificing wear protection. North American lubricant blenders are responding with shear-stable polymer architectures that maintain film strength across extended drain intervals.
Automotive OEMs are consolidating adhesive procurement through direct specification agreements with compounders. Tier-two distributors are losing share to technical service partnerships where suppliers co-develop application-specific grades. This pattern is most pronounced in German and South Korean EV battery supply chains where just-in-sequence delivery requires embedded formulation support.
High Molecular Weight Polyisobutylene Market Segmentation
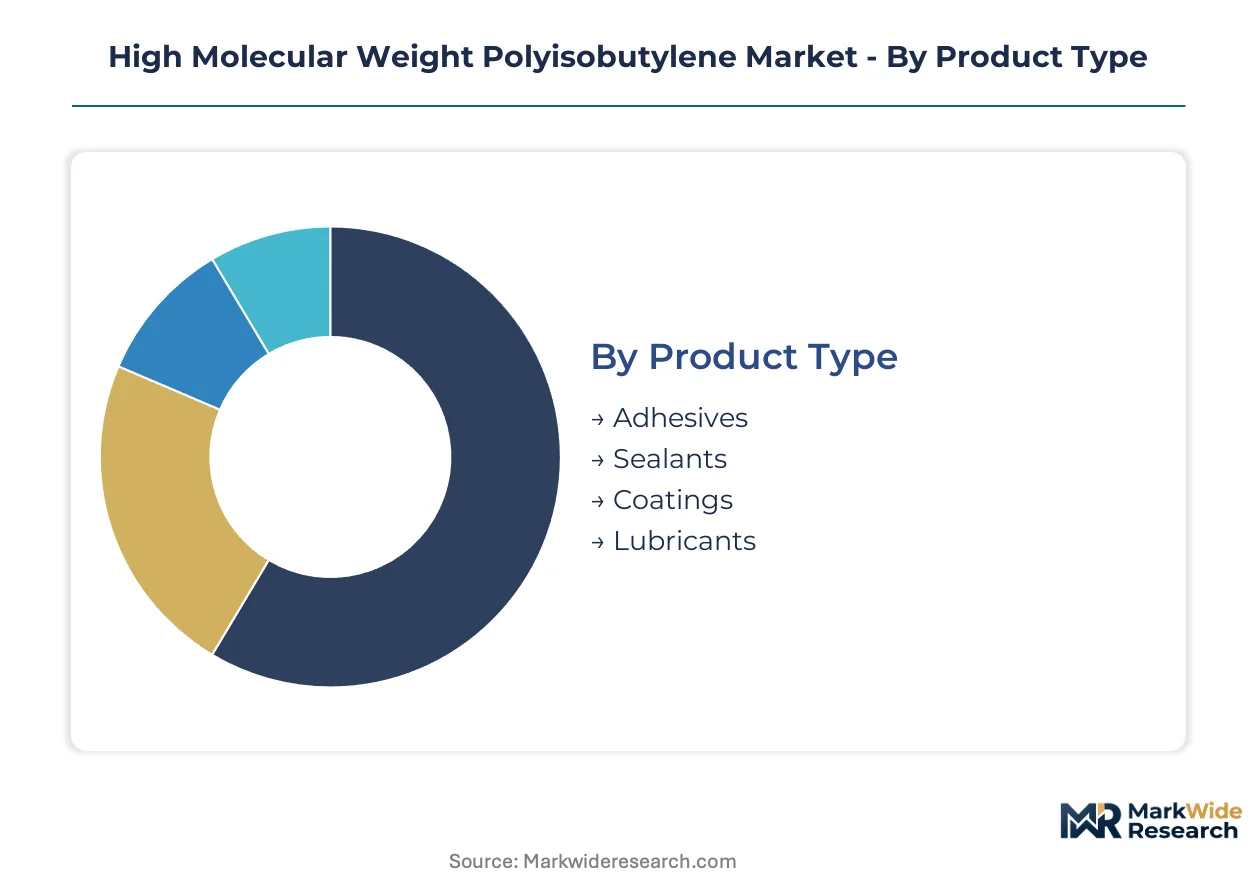
High molecular weight polyisobutylene serves functionally distinct roles across formulation chemistry, with each segment facing unique substitution pressures from synthetic rubber alternatives and bio-based sealant technologies. Segmentation clarity enables suppliers to align molecular weight specifications with end-use certification requirements and procurement consolidation patterns.
Product Type:
Sealants face the most acute substitution threat from silicone and polyurethane formulations in automotive weatherstripping, while lubricant additives benefit from regulatory lock-in through OEM qualification protocols.
- Lubricants:Viscosity modifiers for engine oils and transmission fluids require shear-stable molecular architectures above 1000 kg/mol. Demand concentrates in Germany's automotive corridor where BASF and INEOS supply directly to lubricant blenders meeting ACEA and API specifications. EPA fuel economy standards compress formulation windows, favoring polymers with precise viscosity index response.
- Sealants:Impermeable elastomeric compounds for fuel tank bonding and battery encapsulation command formulation premiums over commodity adhesives. Procurement is shifting toward EV-dedicated tier-one suppliers in South Korea and Germany requiring just-in-sequence delivery with embedded technical service.
- Adhesives:Pressure-sensitive and structural bonding formulations leverage polyisobutylene's tack and oxidative stability. REACH Annex XVII VOC limits accelerate solvent-free grade adoption in European automotive assembly.
- Coatings:Protective films and barrier layers exploit low gas permeability for corrosion prevention. FDA 21 CFR 177 clearances enable limited penetration into food-contact applications.
Lubricants anchors the volume base while sealants gains share at the steepest rate.
End User:
Cost tier stratification separates specification-grade automotive procurement from price-sensitive construction purchasing, with adhesive manufacturers occupying an intermediate technical-service tier.
- Automotive:OEM direct specifications dominate, with battery encapsulation adhesives displacing conventional engine-bay sealants in procurement volumes. German and South Korean EV supply chains concentrate purchasing power among dedicated tier-one compounders.
- Adhesive Manufacturers:Formulation houses blend base polymers with tackifiers and curing agents for industrial and consumer markets. Technical partnerships with raw material suppliers determine competitive access.
- Construction:Waterproofing membranes and roofing sealants prioritize cost efficiency over performance differentiation. Regional distributors serve fragmented contractor bases.
- Oil & Gas:Pipeline coatings and downhole sealants demand extreme-pressure stability. Specification compliance with NACE and API standards limits supplier pools.
Automotive commands the highest margin tier while adhesive manufacturers deliver the most stable volume throughput.
Application:
Application maturity varies sharply, with engine oils representing a saturated replacement market and tire manufacturing offering technology refresh opportunities through air-retention inner liners.
- Engine Oils:Long-drain specifications in passenger and commercial vehicles consume the largest polymer volumes. Shear stability limitations above 150°C constrain deployment in next-generation formulations.
- Tire Manufacturing:Halobutyl rubber blends for inner liners reduce air permeation versus natural rubber. Japanese and German tire makers qualify suppliers through extended compound testing protocols.
- Fuel Additives:Deposit control and lubricity enhancement in diesel and gasoline formulations. Regulatory approval through EPA and ECHA substance evaluation determines market access.
- Rubber Products:General industrial goods including conveyor belts and vibration dampers. Price competition from styrene-butadiene and ethylene-propylene alternatives limits growth.
Engine oils maintains the installed base while tire manufacturing offers the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect customer scale and technical complexity, with direct sales capturing specification-grade accounts and distributors serving fragmented regional demand.
- Direct Sales:Integrated petrochemical producers supply automotive OEMs and multinational lubricant blenders through long-term offtake agreements. Technical service teams co-develop application-specific grades.
- Distributors:Regional chemical distributors inventory standard viscosity grades for mid-tier adhesive manufacturers and construction formulators. Inventory carrying costs favor high-turnover SKUs.
- Online Sales:E-procurement platforms serve small-volume researchers and specialty compounders. Limited to catalog grades with established safety documentation.
- Retail:Consumer packaged goods for DIY sealant and adhesive applications. Minimal relevance for high molecular weight grades requiring industrial handling.
Direct sales captures the value concentration while distributors extend geographic coverage most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while Indian procurement remains cost-sensitive under PLI scheme constraints. The United States and China compete for EV battery sealant volumes through divergent regulatory pathways. Japan maintains specialty-grade premiums through tire-maker qualification protocols.
Germany
BASF SE and INEOS Oligomers anchor European supply from Ludwigshafen and Leverkusen polymer clusters. REACH Annex XVII VOC thresholds accelerate solvent-free adhesive adoption across automotive assembly lines. The Rhine-Neckar metropolitan region concentrates tier-one supplier technical service partnerships for EV battery encapsulation.
United States
EPA fuel economy standards compress viscosity modifier specifications for long-drain engine oils. Gulf Coast petrochemical infrastructure feeds integrated producers with C4 feedstock security. Texas and Louisiana host the dominant domestic polymerization capacity serving North American lubricant blenders.
China
Domestic EV production scales drive battery-grade sealant procurement from local compounders. MIIT industrial policy prioritizes import substitution in high-performance polymer segments. The Yangtze River Delta manufacturing belt concentrates automotive adhesive formulation capacity near Shanghai.
India
PLI scheme incentives for domestic EV manufacturing create localized demand for specialized sealant compounds. BIS certification requirements segment market access between industrial and automotive grades. Maharashtra and Gujarat host emerging polymer compounding clusters serving tier-one suppliers.
Japan
Japanese tire manufacturers qualify polyisobutylene suppliers through extended halobutyl inner liner testing protocols. METI energy efficiency standards favor low-permeability rubber products in automotive applications. The Nagoya industrial corridor concentrates precision polymer formulation expertise.
High Molecular Weight Polyisobutylene Market Vendor Landscape
Concentration sits with backward-integrated petrochemical giants controlling C4 feedstock streams and proprietary catalyst technology. The vendor base stratifies between commodity cationic producers and premium metallocene specialists serving precision viscosity applications. Two dominant archetypes emerge: integrated refinery-polymer operators and specialty additive blenders lacking captive raw material supply. Competitive moves center on catalyst technology licensing partnerships and direct OEM specification agreements that bypass traditional distribution channels.
Among integrated European operators, BASF SE and INEOS Oligomers exemplify the refinery-anchored archetype through their Rhine corridor production bases. Specialty distribution and formulation services are represented by TRiiSO and CHEMSPEC, LTD., which occupy intermediate positions between raw material producers and end-use compounders. ExxonMobil Chemical anchors the Gulf Coast supply position, while Daelim represents Asian integrated production capacity. The competitive dynamic pits feedstock security against formulation proximity to automotive OEMs.
| Leading Market Players |
|---|
| INEOS Oligomers |
| TRiiSO |
| BASF SE |
| Daelim |
| CHEMSPEC, LTD. |
| ExxonMobil Chemical |
| TPC Group |
| Lanxess AG |
| Lubrizol |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between integrated petrochemical producers and automotive OEMs lock in C4 feedstock supply visibility while insulating contract holders from spot market volatility in isobutylene pricing. These arrangements concentrate purchasing power among backward-integrated suppliers in Germany and the Gulf Coast, compressing margin flexibility for specialty blenders lacking captive refinery streams.
Pricing Analysis
Configured-to-order pricing for battery-grade sealant compounds commands substantial premiums over standard viscosity-grade base polymers sold through distributors. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification burden — FDA 21 CFR 177 clearances and REACH Annex XVII compliance tiers separate specification-grade automotive procurement from construction-industry commodity purchases. Cost compression in mid-tier lubricant additives is intensifying because metallocene-catalyzed alternatives are fragmenting the conventional cationic production landscape. Adhesive manufacturers serving European automotive assembly lines exhibit the highest price sensitivity due to REACH-driven reformulation costs, while EV-dedicated tier-one suppliers in Germany and South Korea prioritize technical service partnerships over unit economics.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for non-integrated blenders sourcing catalyst precursors and specialty additives. Production gravity centers on Germany, the United States, and China — with the Rhine corridor and Gulf Coast petrochemical infrastructure anchoring integrated supply and the Yangtze River Delta manufacturing belt concentrating automotive adhesive formulation capacity. The supply chain draws from crude-derived C4 feedstock streams, Lewis acid catalyst systems, and halobutyl rubber blending capacity. Single-source vulnerability in metallocene catalyst technology creates structural risk as specialty lubricant formulators adopt narrower molecular weight distribution grades. Distribution runs through direct sales channels for specification-grade automotive accounts, with regional chemical distributors serving fragmented construction and industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards proprietary control over cationic polymerization expertise and catalyst handling capabilities that remain concentrated at legacy production sites. Talent scarcity in Lewis acid molecular weight control creates durable competitive moats for incumbent operators with established technical workforces.
For Market Incumbents: Compound feedstock security through capacity reservation agreements with C4 stream operators in the Rhine corridor and Gulf Coast, while deepening technical service partnerships with EV-dedicated tier-one suppliers in Germany and South Korea. Invest in metallocene catalyst licensing to defend against substitution threats from precision viscosity-grade specialists. Prioritize ECHA registration dossier preparation for new viscosity variants to preempt regulatory delays. For New Entrants and Emerging Players: Lead with localized compounding capacity in India under PLI scheme incentives, targeting domestic EV battery sealant procurement as the most penetrable white-space opportunity. Establish formulation partnerships with radiation-cure equipment manufacturers for reactive hot-melt convergence applications. Pursue technical service embedding with mid-tier adhesive manufacturers losing share to direct OEM specification agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated petrochemical operators with long-term offtake agreements and captive C4 feedstock streams, suggesting superior cash-flow quality versus specialty blenders exposed to raw material volatility. Over the medium-term horizon, acquisition targets should display backward integration into refinery streams or proprietary catalyst technology licensing positions. Monitor ECHA substance evaluation timeline extensions as a signal for regulatory-driven consolidation pressure among non-integrated compounders lacking registration infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | Captive isobutylene supply insulates margin resilience against crude-derived raw material volatility. |
| Metallocene Catalyst Licensing | Narrow molecular weight distribution technology captures precision lubricant formulator demand in Germany and Japan. |
| Long-term Supply Agreement | Direct OEM specifications with EV tier-one suppliers in South Korea bypass distributor channel compression. |
| Capacity Expansion in India | PLI scheme incentives for domestic EV manufacturing create localized sealant compound demand. |
| Joint Venture for Reactive Hot-melt | Hybrid adhesive partnerships with UV-curing equipment manufacturers open automated assembly line applications. |
Methodological Framework
A standing panel of polymer plant managers, lubricant blender procurement leads, automotive tier-one supplier technical directors, and specialty chemical distribution partners provided ongoing calibration against operational realities. This primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated petrochemical operators, and REACH registration dossiers maintained analytical rigor. Bottom-up segment sizing across viscosity grades, end-use industries, and regional production hubs triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, end user, application, and distribution channel, with additional dimensioning by regional regulatory cluster and certification tier. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity parameters incorporated automotive electrification penetration curves and REACH Annex XVII compliance timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EV production scaling, stable C4 feedstock availability, and current ECHA evaluation protocols would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and substitution dynamics. Specific risks that could revise projections include extended ECHA substance evaluation delays, breakthrough bio-based sealant technologies, and abrupt shifts in automotive OEM adhesive procurement consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Mono Methyl Ether of Hydroquinone (MEHQ) Market
High-Value Chemicals
High-Purity Nitrogen Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Global Hydrofluoric Acid Market