
 Hydroxylamine Sulfate Market | 2026-2036
Hydroxylamine Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxylamine Sulfate Market Foresight
Specialized chemical engineering talent is unwinding capacity constraints across hydroxylamine sulfate purification and crystallization operations. BASF leverages its Ludwigshafen integrated site to sustain captive production of high-purity grades for internal polymerization chemistry. UBE Corporation anchors Asian supply through its Japanese nitrile-derived process chain, while Nouryon Chemicals International competes on REACH-compliant material for European pharmaceutical intermediates.
Hydroxylamine sulfate is an inorganic salt with formula (NH₃OH)₂SO₄, typically manufactured via catalytic hydrogenation of nitric oxide or nitrous acid reduction followed by sulfuric acid neutralization; it functions primarily as a selective reducing agent in organic synthesis and as an oxygen scavenger in polymerization systems. Industrial grade material dominates volume throughput due to agrochemical and water treatment demand, while pharmaceutical grade commands premium positioning through CDMO qualification requirements. Research grade segments show accelerated expansion as academic institutions scale peptide synthesis and radiolabeling protocols.
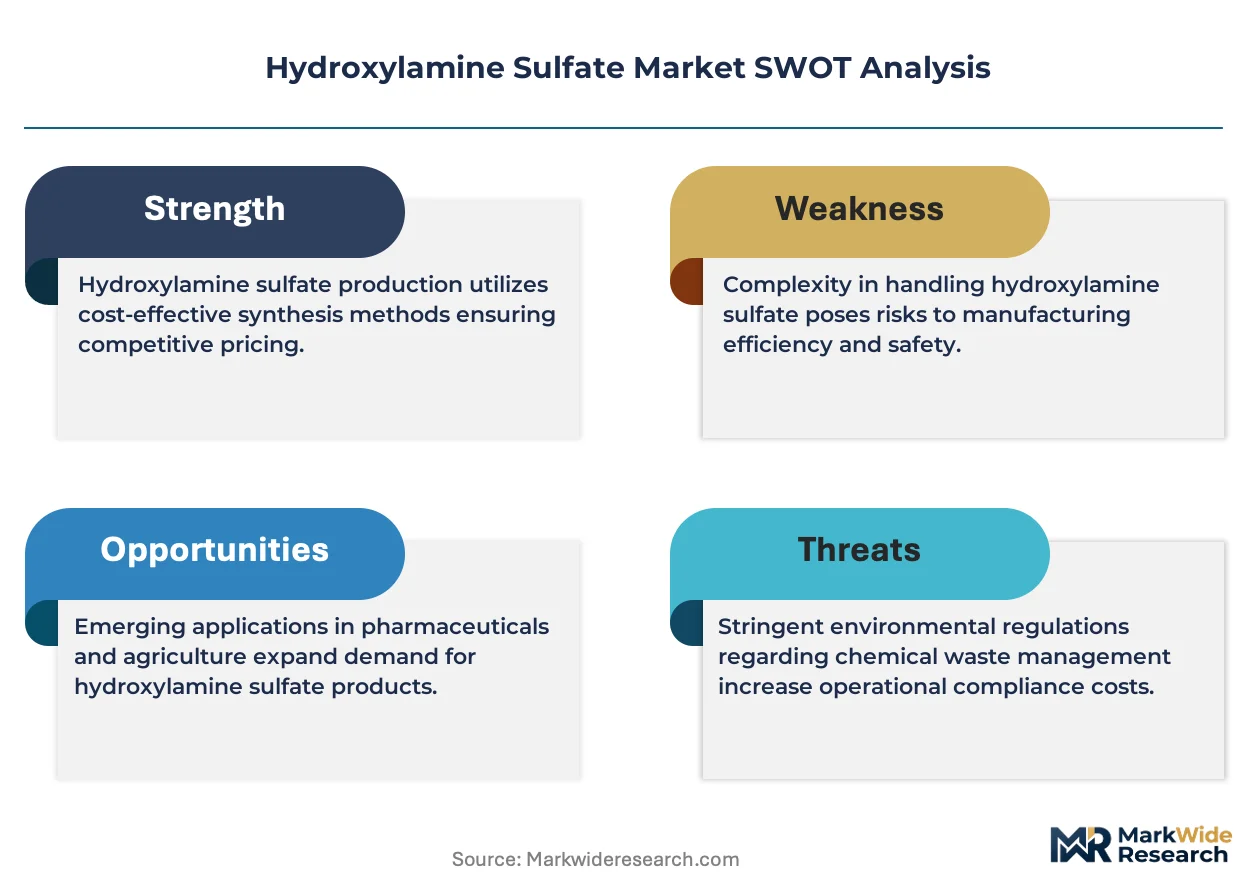
EMA pharmaceutical impurity guidelines and EPA TSCA chemical data reporting requirements shape purity thresholds and documentation burdens for cross-border suppliers. China's MEE hazardous chemical registration mandates and India's CDSCO active pharmaceutical ingredient import specifications further fragment compliance architectures. Stakeholders must monitor regulatory divergence between pharmaceutical and industrial grade specifications to optimize product slate allocation and certification investments.
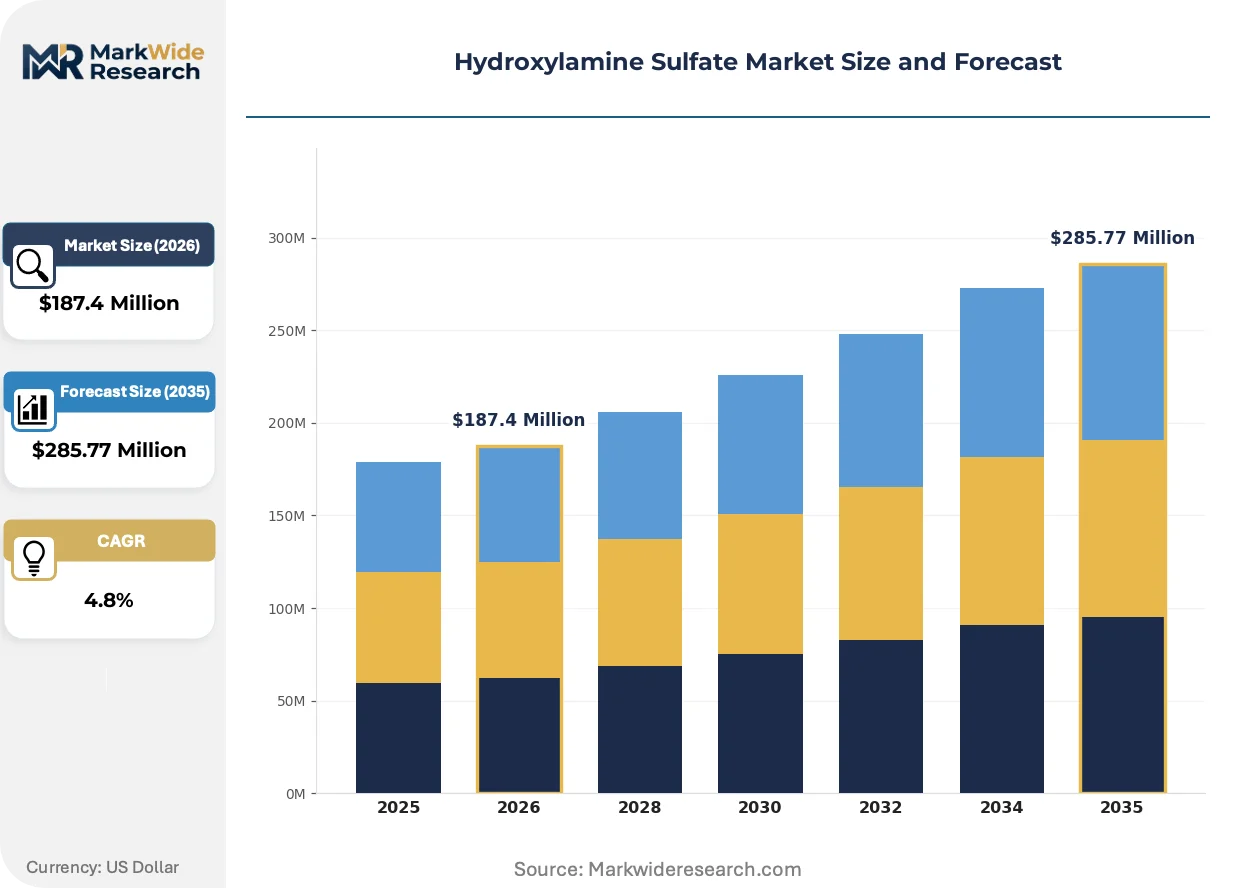
Market Dynamics
REACH compliance deadlines and China's GB standard revisions are compressing certification timelines for hydroxylamine sulfate suppliers, forcing simultaneous investments in pharmaceutical-grade purification and industrial-grade cost optimization.
Growth Catalysts
- EMA pharmaceutical impurity guidelines:Tightening purity thresholds for active pharmaceutical ingredient synthesis are pulling demand toward certified pharmaceutical-grade material across European CDMO networks.
- Peptide synthesis scale-up:Academic radiolabeling protocols and institutional research budgets are expanding consumption of research-grade hydroxylamine sulfate in North American and European laboratories.
- East China chemical corridor:Agrochemical and polymerization feedstock buyers clustering near Shanghai and Ningbo port infrastructure are concentrating procurement volumes in this manufacturing zone.
Market Restraints
- Nitrile feedstock volatility:Hydrogenation catalyst costs and nitric oxide supply fluctuations transmit directly into hydroxylamine sulfate production economics, compressing margin buffers for non-integrated producers.
- Japanese supply concentration:UBE Corporation's nitrile-derived process chain anchors Asian high-purity supply, creating geographic single-point vulnerability for pharmaceutical-grade procurement.
- Aqueous ammonia substitution:Selective reduction applications in certain agrochemical intermediates face displacement risk from lower-cost ammonia-based reductants in price-sensitive industrial segments.
Strategic Opportunities
- India CDSCO API import specifications:Formalization of active pharmaceutical ingredient purity documentation is creating first-mover advantage for REACH-compliant suppliers establishing Indian regulatory dossiers.
- Continuous flow hydrogenation:Convergence of microreactor engineering with catalytic nitric oxide reduction is enabling modular capacity expansion without crystallization bottleneck investments.
- Water treatment oxygen scavenging:Boiler feedwater and industrial cooling systems in Southeast Asian manufacturing zones represent underpenetrated demand for technical-grade material.
Industry Challenges
- Crystallization engineering expertise:Specialized talent for pharmaceutical-grade particle size distribution control remains concentrated in German and Japanese chemical engineering programs, constraining new entrant qualification timelines.
- Dual-grade certification complexity:Simultaneous maintenance of pharmaceutical and industrial grade quality systems under divergent audit protocols stretches quality assurance bandwidth at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxylamine Sulfate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Research Grade, Technical Grade Application: Reducing Agent, Chemical Intermediate, Photographic Chemicals, Polymerization Agent End User: Chemical Manufacturers, Pharmaceutical Companies, Research Laboratories, Academic Institutions Packaging Type: Bag, Drum, Bulk, Bottle |
| Companies Covered | Zhejiang Jinhua New Material, Merck, BASF, Shandong Jinan Chemical, Nouryon Chemicals International, UBE Corporation, Gujarat State Fertilizers & Chemicals Limited, Jiangshan Taige Chemical, Jiangsu Ecoway Science Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxylamine Sulfate Market Shifts & Advancements
Process intensification and regulatory documentation automation are compressing the traditional gap between industrial commodity production and pharmaceutical-grade certification economics.
Membrane-based purification cascades are miniaturizing the footprint of pharmaceutical-grade hydroxylamine sulfate crystallization trains. CDMO qualification teams in Germany and Switzerland are piloting these systems to reduce solvent recovery costs. The technology is compressing capital requirements for entry into high-purity segments previously reserved to integrated chemical majors.
China's MEE hazardous chemical registration mandates are tightening substance identity documentation across export channels. Industrial-grade suppliers face retroactive dossier compilation for legacy production volumes. Pharmaceutical-grade exporters with pre-established registration infrastructure are capturing displaced demand from non-compliant industrial producers.
Specification-driven vendor consolidation is concentrating procurement decisions at fewer qualified suppliers per end-use vertical. Agrochemical formulators in East China are reducing approved supplier lists from multiple sources to dual-source arrangements with documented REACH or GB compliance. This pattern is most visible in polymerization feedstock purchasing near Ningbo port infrastructure.
Hydroxylamine Sulfate Market Segmentation
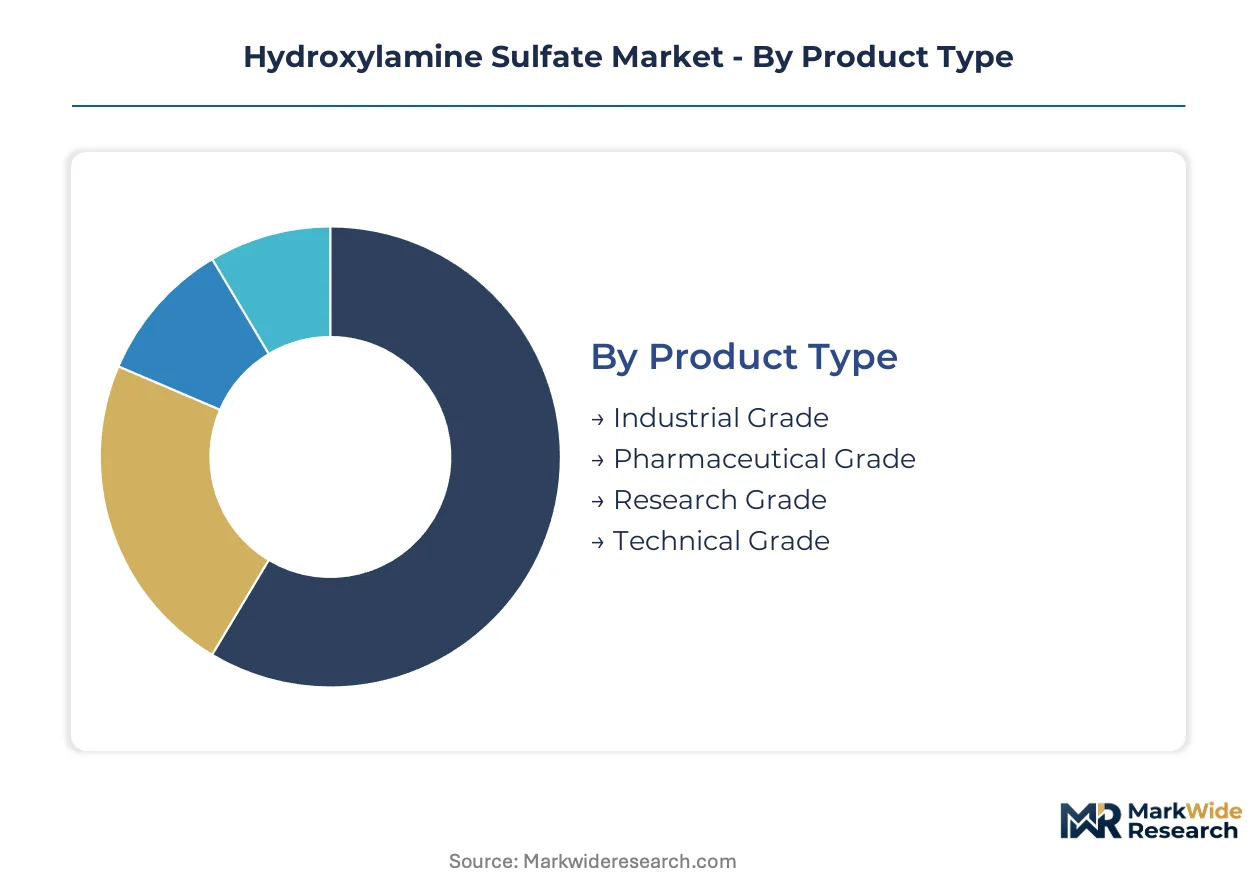
Segmentation in hydroxylamine sulfate tracks a critical tension between commoditized industrial volumes and certified pharmaceutical premiums. Specification divergence across grades determines supplier qualification timelines and margin architecture.
Product Type:
Industrial grade faces the most acute substitution pressure from aqueous ammonia reductants in price-sensitive agrochemical applications, while pharmaceutical grade maintains defensive positioning through CDMO qualification barriers.
- Industrial Grade:Standard purity material manufactured via catalytic hydrogenation of nitric oxide serves agrochemical synthesis and water treatment oxygen scavenging. East China's chemical corridor near Shanghai and Ningbo concentrates procurement volumes for polymerization feedstock applications.
- Pharmaceutical Grade:High-purity material meeting EMA impurity guidelines and CDSCO API specifications commands premium positioning through documented crystallization protocols. REACH-compliant European CDMO networks and Indian regulatory dossier requirements drive qualification investments.
- Research Grade:Ultra-pure material for peptide synthesis and radiolabeling protocols in North American and European academic institutions.
- Technical Grade:Intermediate purity material for boiler feedwater treatment and industrial cooling systems in Southeast Asian manufacturing zones.
Industrial grade anchors the volume base while pharmaceutical grade gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity chemical intermediate demand from specialized reducing agent premiums in pharmaceutical synthesis.
- Reducing Agent:Selective reduction functionality in organic synthesis requires precise stoichiometric control and documented purity certificates for pharmaceutical manufacturing.
- Chemical Intermediate:Feedstock consumption in agrochemical and polymer production chains concentrates in East China's manufacturing corridor near port infrastructure.
- Photographic Chemicals:Niche demand from legacy film processing and specialty imaging applications.
- Polymerization Agent:Oxygen scavenging in polymer production systems, particularly for synthetic rubber and polymerization feedstock manufacturing.
Chemical intermediate applications dominate volume throughput while reducing agent applications command the highest purity premiums.
End User:
Customer type determines procurement specification stringency, with pharmaceutical companies imposing the most extensive documentation requirements.
- Chemical Manufacturers:Volume purchasers of industrial and technical grades for downstream synthesis operations, concentrated in East China and German chemical clusters.
- Pharmaceutical Companies:CDMO networks and API manufacturers requiring REACH-compliant or CDSCO-registered material with full impurity profiling.
- Research Laboratories:Institutional buyers scaling peptide synthesis and radiolabeling protocols in North American and European facilities.
- Academic Institutions:Grant-funded procurement of research-grade material for synthetic chemistry programs.
Chemical manufacturers anchor the volume base while pharmaceutical companies expand specification requirements fastest.
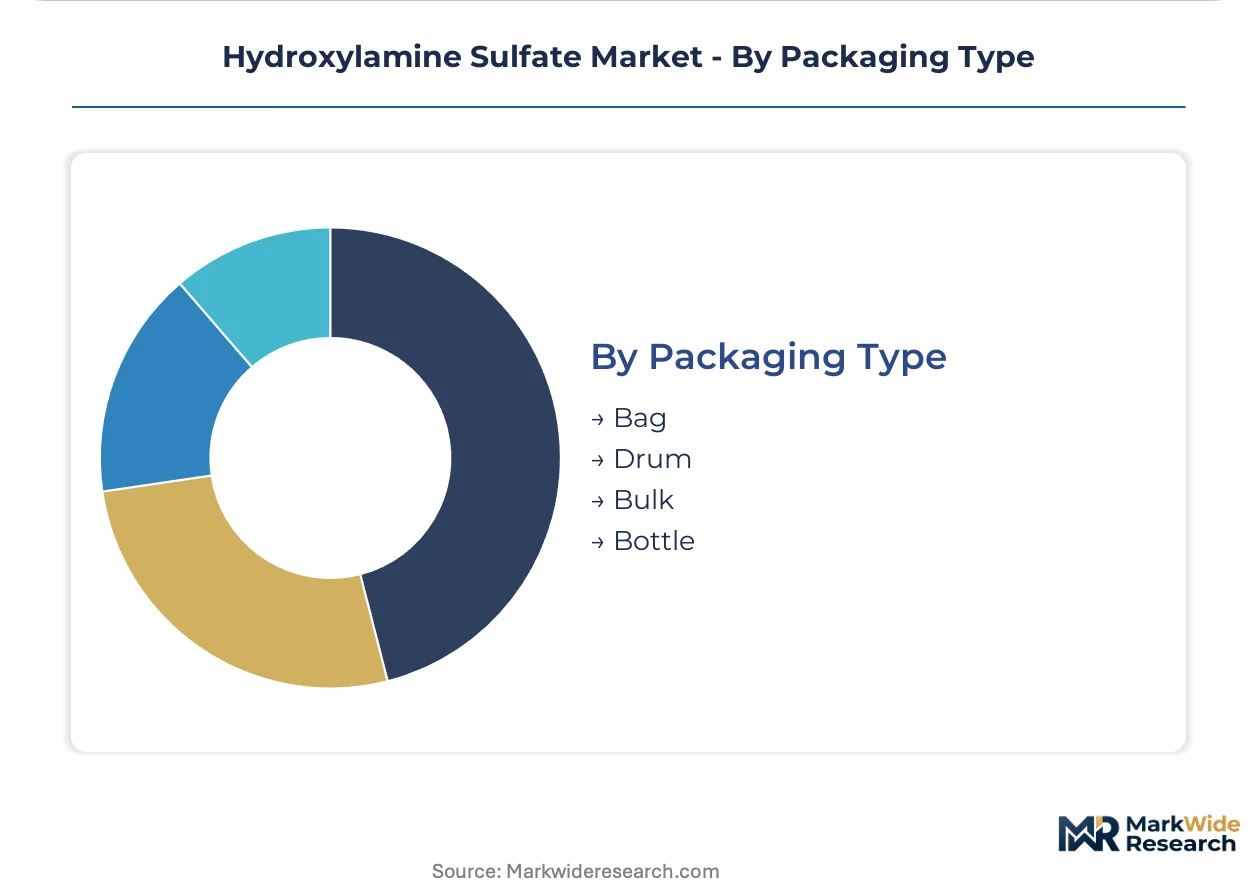
Packaging Type:
Supply chain configuration determines packaging economics, with bulk shipments offering cost advantages for integrated chemical majors.
- Bag:Standard 25-50kg packaging for industrial grade shipments to agrochemical formulators.
- Drum:Steel or fiber drums for pharmaceutical grade material requiring moisture protection during transit.
- Bulk:Tanker or hopper car deliveries for integrated polymerization facilities and large-scale water treatment operations.
- Bottle:Laboratory-scale packaging for research grade and analytical standard applications.
Drum packaging anchors the pharmaceutical grade base while bulk deliveries expand most quickly in integrated manufacturing sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese pharmaceutical-grade supply chains while Chinese industrial-grade producers compete on volume economics near coastal port infrastructure. EMA impurity guidelines and REACH compliance deadlines compress certification timelines for European CDMO networks. China's GB standard revisions and MEE hazardous chemical registration mandates fragment export channel requirements across specification tiers.
Germany
BASF's Ludwigshafen integrated site sustains captive production of high-purity grades for internal polymerization chemistry. ECHA REACH compliance deadlines force simultaneous investments in pharmaceutical-grade purification documentation. The Rhine-Neckar chemical cluster anchors European CDMO procurement decisions for certified reducing agent material.
China
Agrochemical and polymerization feedstock buyers cluster near Shanghai and Ningbo port infrastructure in East China's chemical manufacturing corridor. MEE hazardous chemical registration mandates tighten substance identity documentation across export channels. Zhejiang and Shandong province producers face retroactive dossier compilation for legacy industrial-grade volumes.
Japan
UBE Corporation anchors Asian high-purity supply through its nitrile-derived process chain for pharmaceutical intermediate applications. METI chemical management regulations shape purity threshold documentation for cross-border shipments. The Chubu region around Nagoya concentrates specialized hydrogenation catalyst engineering talent.
India
CDSCO active pharmaceutical ingredient import specifications formalize purity documentation requirements for hydroxylamine sulfate used in generic drug synthesis. Gujarat State Fertilizers & Chemicals Limited occupies a position within domestic industrial-grade supply. The Gujarat chemical corridor near Vadodara and Ahmedabad clusters agrochemical formulators seeking dual-source arrangements with documented compliance.
United States
EPA TSCA chemical data reporting requirements shape documentation burdens for research-grade material consumed in academic radiolabeling protocols. Peptide synthesis scale-up at North American institutions expands consumption of ultra-pure grades. The Gulf Coast petrochemical corridor maintains technical-grade demand for polymerization oxygen scavenging applications.
Hydroxylamine Sulfate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hydroxylamine sulfate market. German and Japanese integrated chemical majors dominate pharmaceutical-grade purification and crystallization engineering, while Chinese producers compete on nitrile feedstock access and coastal logistics efficiency. Three archetypes define competitive positioning: integrated multinational chemical conglomerates with captive demand, regional industrial-grade specialists serving agrochemical formulators, and research-grade distributors qualifying academic procurement channels. Capacity expansion and regulatory dossier compilation represent the dominant competitive moves as certification timelines compress.
Within the integrated multinational tier, BASF and UBE Corporation exemplify technology leadership through in-house polymerization chemistry demand and nitrile-derived process chains respectively. Nouryon Chemicals International occupies a position on the REACH-compliant European vector. Among China-based producers, Zhejiang Jinhua New Material and Shandong Jinan Chemical represent regional industrial-grade supply archetypes serving East China chemical corridor procurement. Gujarat State Fertilizers & Chemicals Limited anchors Indian domestic production. These named entities illustrate the geographic fragmentation between pharmaceutical-grade certification leaders and volume-driven industrial suppliers.
| Leading Market Players |
|---|
| Zhejiang Jinhua New Material |
| Merck |
| BASF |
| Shandong Jinan Chemical |
| Nouryon Chemicals International |
| UBE Corporation |
| Gujarat State Fertilizers & Chemicals Limited |
| Jiangshan Taige Chemical |
| Jiangsu Ecoway Science Technology |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles for pharmaceutical-grade material tie pricing power directly to crystallization engineering scarcity and the geographic concentration of qualified producers. This lead-time band compresses margin buffers for non-integrated buyers while amplifying premiums for REACH-certified supply.
Pricing Analysis
Pharmaceutical-grade customization premiums over industrial-grade spot pricing widen with each additional certification layer. Three-tier pricing structure across pharmaceutical, industrial, and research grades reflects crystallization protocol complexity and CDMO qualification depth. Cost compression in industrial tiers intensifies because aqueous ammonia substitutes erode price floors for standard-purity material. Agrochemical formulators in East China exhibit highest price sensitivity, while European CDMO networks absorb premium spreads for documented impurity profiles.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane amplify inbound logistics costs for nitrile feedstock and hydrogenation catalyst shipments. Supply concentrates in Germany, Japan, and China, with UBE Corporation's Chubu-region facilities and BASF's Ludwigshafen site anchoring high-purity output. Raw material dependencies draw from nitric oxide supply, sulfuric acid neutralization capacity, and specialized hydrogenation catalysts. Single-source vulnerability permeates Asian pharmaceutical-grade procurement due to UBE's process-chain dominance. Distribution runs through bulk tanker deliveries for integrated polymerization facilities and steel-drum shipments for moisture-sensitive pharmaceutical consignments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized crystallization engineering talent scarcity constrains new entrant qualification timelines and sustains incumbent pricing power in pharmaceutical-grade segments. This capability gap separates certified suppliers from commodity producers.
For Market Incumbents: Shield pharmaceutical-grade margin architecture by deepening captive nitrile feedstock access through backward integration into hydrogenation catalyst supply chains. Accelerate REACH dossier pre-registration for Indian CDSCO compliance ahead of formalized API import specifications. Aqueous ammonia substitution in agrochemical intermediates represents the primary margin threat requiring defensive specification tightening.
For New Entrants and Emerging Players: Anchor in Southeast Asian water treatment oxygen scavenging demand, where technical-grade specifications remain underpenetrated and certification barriers sit lowest. Modular continuous-flow hydrogenation systems enable capacity entry without crystallization engineering bottlenecks. Technical-grade boiler feedwater applications in Vietnamese and Indonesian manufacturing zones offer the most penetrable entry vector.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded pharmaceutical-grade capacity lacking standalone CDMO qualification infrastructure. Long-term viability hinges on regulatory dossier depth rather than feedstock cost position. Watch for EMA impurity guideline revision announcements as inflection signals for qualification investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Feedstock | BASF's Ludwigshafen captive supply secures margin insulation against hydrogenation catalyst volatility. |
| Continuous Flow Hydrogenation Scale-Up | Microreactor engineering convergence enables modular pharmaceutical-grade expansion without crystallization bottlenecks. |
| REACH-Compliant Indian Dossier Registration | CDSCO formalization creates first-mover advantage for European suppliers establishing regulatory infrastructure. |
| Membrane Purification Cascade Deployment | CDMO pilot programs in Germany and Switzerland compress solvent recovery costs for high-purity crystallization. |
| Dual-Source Supplier Consolidation | East China agrochemical formulators near Ningbo port reduce approved vendor lists to documented compliance holders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pharmaceutical CDMO procurement directors, agrochemical formulator technical managers, hydrogenation catalyst suppliers, and crystallization engineering specialists. Secondary validation drew from EMA impurity guideline documentation, China's MEE hazardous chemical registration databases, CDSCO API import circulars, customs trade flow records, and SEC filings from disclosed chemical producers. Bottom-up volume modeling triangulated against top-down market sizing across grade tier and end-use segments.
Across the analysis window, forecasts reflect segmented modeling of pharmaceutical-grade, industrial-grade, research-grade, and technical-grade consumption patterns by application intensity and regional regulatory cluster. CAGRs were derived from trend extrapolation of peptide synthesis scale-up, polymerization feedstock demand, and water treatment oxygen scavenging penetration. Nitrile feedstock cost trajectories and hydrogenation catalyst availability assumptions shaped production economics sensitivity.
Material uncertainties — nitrile feedstock volatility, EMA guideline revision timing, and Chinese GB standard enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about crystallization engineering talent availability and CDMO qualification cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Hydrogen Cyanide Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Hexafluoropropylene Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
High Performance Mercury Sorbent Market