
 Energy Dispersive X-Ray Spectrometer Market | 2026-2036
Energy Dispersive X-Ray Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Dispersive X-Ray Spectrometer Market Analysis
The EU Green Deal's material traceability mandates is hardening requirements for elemental analysis across battery supply chains. Bruker Corporation leverages its cryogen-free detector portfolio to anchor European laboratory demand. Oxford Instruments competes through specialized semiconductor metrology configurations. Thermo Fisher Scientific dominates handheld deployments for mining and environmental field screening.
An energy dispersive X-ray spectrometer detects characteristic X-rays emitted from a sample under electron beam excitation, identifying elemental composition from boron through uranium with detection limits typically reaching 0.1 weight percent. Its primary purpose spans materials characterization, failure analysis, and regulatory compliance verification across manufacturing and research environments. Laboratory systems capture the deepest margin pools due to detector cooling infrastructure and software customization, while handheld units represent the fastest-growing configuration for on-site mining and environmental enforcement. Silicon drift detector technology leads unit shipments for its count-rate performance, though hybrid architectures are gaining traction where simultaneous light-element and heavy-element sensitivity matters.
The EPA enforces TCLP metals testing protocols that shape environmental spectrometer specifications in the United States, while China's MEE implements GB standards for soil contamination screening that drive portable unit procurement. REACH and RoHS compliance in Europe mandates supplier-level elemental certification, embedding EDX systems into electronics and automotive quality workflows. Stakeholders must weigh detector technology roadmaps against evolving regulatory detection thresholds to preserve analytical competitiveness.
Market Dynamics
Detector cooling infrastructure costs and elemental purity thresholds are compressing margins for laboratory-grade configurations while semiconductor fabs in Taiwan and South Korea accelerate inline metrology deployment.
Growth Catalysts
- REACH and RoHS compliance:The EU chemicals framework mandates supplier-level elemental certification for electronics and automotive components, embedding EDX systems into quality workflows across European manufacturing.
- Silicon drift detector technology:Its superior count-rate performance is displacing traditional Si(Li) architectures in high-throughput semiconductor fabs requiring real-time process control.
- Battery supply chains:The EU Green Deal's material traceability mandates harden requirements for elemental analysis across lithium-ion cathode and anode production facilities.
Market Restraints
- Liquid nitrogen dependency:Laboratory-grade systems require continuous cryogenic cooling, creating operational friction and supply vulnerability for facilities without captive infrastructure.
- Detector fabrication concentration:High-purity germanium and silicon crystal production clusters in Japan and Germany, exposing buyers to single-source risk and extended lead times.
- X-ray fluorescence substitution:Benchtop XRF instruments compete for non-destructive elemental screening in mining and environmental applications where electron beam precision is unnecessary.
Strategic Opportunities
- India's PLI scheme:Domestic semiconductor and battery manufacturing incentives create greenfield demand for inline metrology systems in fabs under construction in Gujarat and Tamil Nadu.
- Cryogen-free architectures:Thermoelectric and Stirling-cycle cooling convergence with silicon drift detectors enables field-deployable laboratory-grade performance without infrastructure constraints.
- Soil contamination enforcement:China's MEE GB standards for environmental screening drive portable unit procurement by provincial environmental monitoring stations.
Industry Challenges
- Spectroscopy technician scarcity:Universities in Germany and Japan produce insufficient graduates trained in electron optics and X-ray physics to match replacement cycle demand from materials science institutes.
- EPA TCLP protocol compliance:Environmental testing laboratories face extended certification timelines for metals analysis workflows, delaying revenue recognition on new instrument deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Dispersive X-Ray Spectrometer Market |
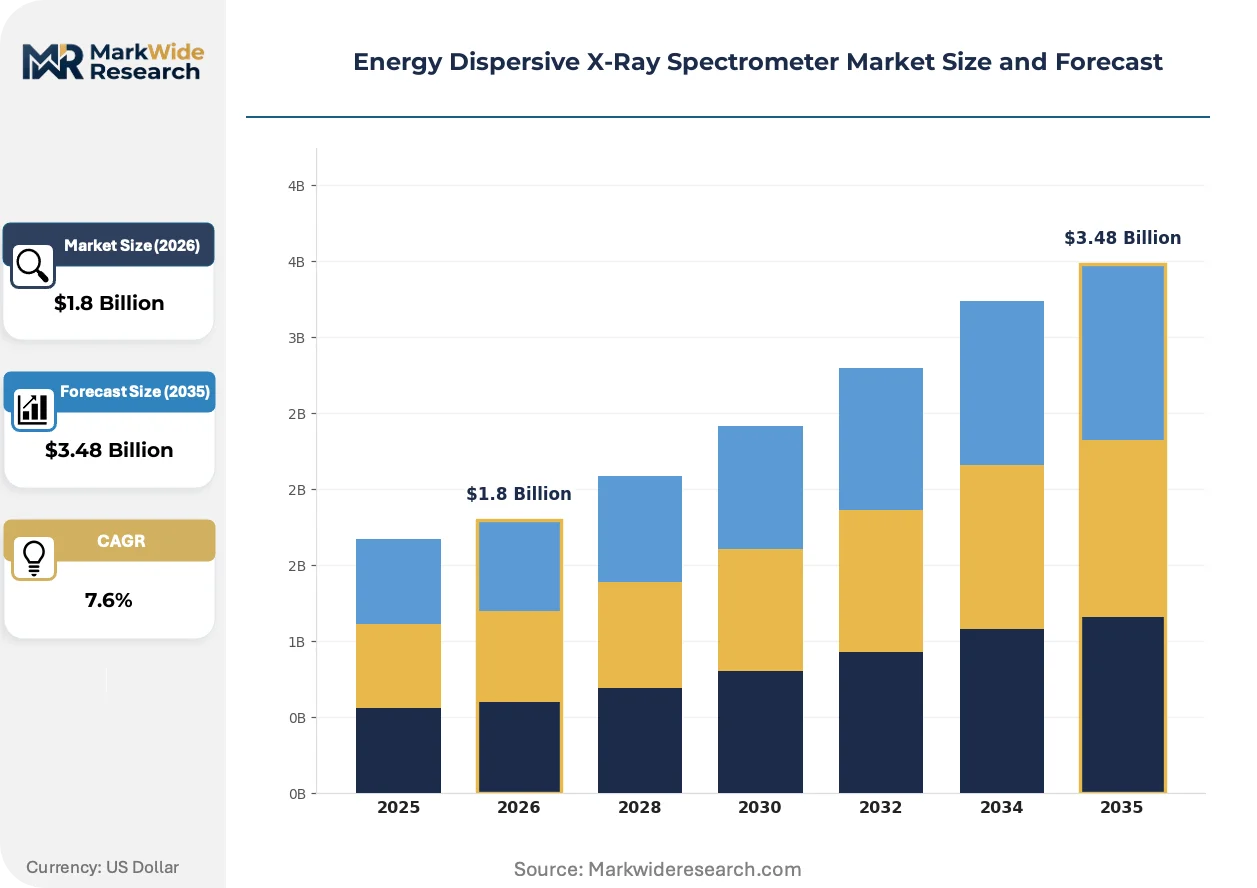
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Laboratory, Industrial Technology: Silicon Drift Detector, Ge Detector, Hybrid Detector, CCD Detector Application: Materials Analysis, Environmental Testing, Mining, Quality Control End User: Research Laboratories, Manufacturing, Universities, Government Agencies |
| Companies Covered | Thermo Fisher Scientific, Bruker Corporation, Oxford Instruments, JEOL Ltd., Hitachi High-Tech, Shimadzu Corporation, HORIBA, AMETEK, EDAX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Dispersive X-Ray Spectrometer Market Emerging Trajectories
Hybrid detector architectures and regulatory detection threshold compression are forcing simultaneous investments in light-element sensitivity and heavy-element throughput across instrument portfolios.
Cryogen-free silicon drift detectors are rewriting field-deployable performance standards. Mining operations in Australia and environmental enforcement agencies in the United States are adopting thermoelectrically cooled configurations for on-site screening. This shift is compressing the traditional boundary between laboratory precision and portable convenience, enabling real-time decision-making at extraction and remediation sites.
The EU Green Deal's material traceability mandates are tightening elemental certification requirements across battery supply chains. Cathode precursor producers must document lithium, nickel, and cobalt purity at multiple processing stages. European automotive OEMs are responding by mandating supplier EDX verification, embedding spectrometry into contractual quality agreements.
After-sales service unbundling is fragmenting traditional instrument procurement models. Semiconductor fabs in South Korea now separate hardware acquisition from detector maintenance contracts and software update subscriptions. This pattern is most pronounced in Hsinchu and Seoul, where dedicated metrology service providers compete against manufacturer-captive service organizations for calibration and repair revenue.
Energy Dispersive X-Ray Spectrometer Market Segmentation
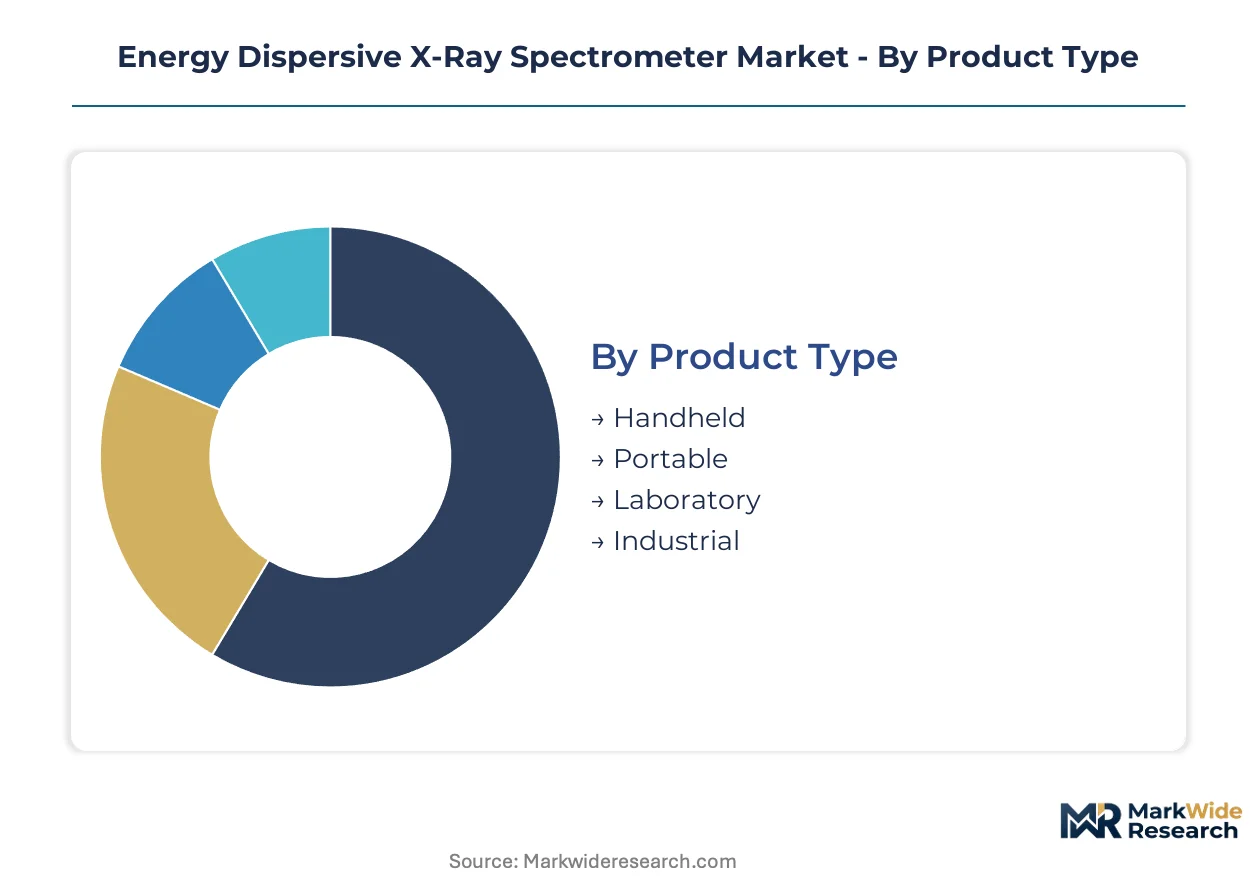
EDX spectrometer procurement splits across four distinct axes: physical configuration, detector physics, analytical purpose, and institutional buyer type. Each axis carries different margin structures, replacement cycles, and service attachment rates that shape vendor portfolio strategy.
Product Type:
Detector cooling infrastructure and mobility requirements create sharp performance boundaries between field-deployable and fixed-installation systems.
- Laboratory:Cryogenic cooling infrastructure anchors the deepest margin pool, with liquid nitrogen or mechanical cooling systems enabling sub-0.1% detection limits. Materials science institutes in Germany and Japan anchor replacement demand for these configurations.
- Handheld:Thermoelectric cooling convergence with silicon drift detectors is compressing the traditional precision-portability boundary. Mining operations in Australia and environmental enforcement agencies in the United States are adopting these for on-site screening.
- Portable:Intermediate configurations serve provincial environmental monitoring stations in China under MEE GB standards compliance mandates.
- Industrial:Inline metrology systems integrate directly with semiconductor fabrication lines in Taiwan and South Korea for real-time process control.
Mature deployment sits with Laboratory systems. Newer deployment is concentrated in Handheld configurations.
Technology:
Count-rate performance and light-element sensitivity determine detector selection for specific analytical workflows.
- Silicon Drift Detector:Superior count-rate performance is displacing traditional Si(Li) architectures in high-throughput semiconductor fabs. Taiwan and South Korean fabs require real-time process control that only SDD technology delivers.
- Hybrid Detector:Simultaneous light-element and heavy-element sensitivity matters for battery cathode precursor analysis under EU Green Deal traceability mandates.
- Ge Detector:High-purity germanium crystal production clusters in Japan and Germany, exposing buyers to single-source risk and extended lead times.
- CCD Detector:Legacy architectures persist in cost-constrained educational installations where elemental range requirements are narrower.
Established volume sits with Silicon Drift Detector. Steepest expansion trajectory belongs to Hybrid Detector architectures.
Application:
Regulatory detection thresholds and sample preparation requirements fragment demand across analytical disciplines.
- Quality Control:REACH and RoHS compliance mandates supplier-level elemental certification for electronics and automotive components. European automotive OEMs embed EDX verification into contractual quality agreements.
- Materials Analysis:Failure analysis workflows in semiconductor packaging and metallurgical laboratories drive high-margin detector customization.
- Environmental Testing:EPA TCLP metals testing protocols shape specifications in the United States, with extended certification timelines delaying revenue recognition.
- Mining:Benchtop XRF instruments compete aggressively for non-destructive screening where electron beam precision is unnecessary.
Contractual entrenchment sits with Quality Control. Regulatory enforcement is expanding fastest in Environmental Testing.
End User:
Procurement authority and funding stability create distinct sales cycle dynamics across institutional categories.
- Research Laboratories:Materials science institutes anchor replacement cycles through competitive grant funding. Detector maintenance contracts and software update subscriptions increasingly unbundle from hardware acquisition.
- Manufacturing:Semiconductor fabs in South Korea now separate hardware acquisition from service contracts, fragmenting traditional procurement models.
- Government Agencies:China's MEE implements GB standards for soil contamination screening that drive portable unit procurement by provincial monitoring stations.
- Universities:Spectroscopy technician scarcity in Germany and Japan constrains utilization rates for advanced configurations.
Service unbundling sits with Research Laboratories. Procurement acceleration is concentrated in Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu anchors semiconductor metrology demand through Taiwan Semiconductor Manufacturing Company's fab expansion, while Seoul's Samsung and SK Hynix operations drive inline process control procurement across the Korean peninsula.
United States
EPA TCLP metals testing protocols shape environmental spectrometer specifications for remediation contractors and analytical laboratories. The agency's enforcement of leachate protocols embeds EDX systems into hazardous waste characterization workflows. Houston's petrochemical corridor and Denver's mining headquarters anchor industrial procurement clusters.
Germany
Materials science institutes in Munich and Stuttgart anchor replacement cycles for laboratory-grade configurations with cryogenic cooling infrastructure. ECHA's REACH enforcement mandates supplier-level elemental certification for automotive OEMs in Stuttgart and Wolfsburg. Fraunhofer research networks sustain detector customization demand.
China
MEE GB standards for soil contamination screening drive portable unit procurement by provincial environmental monitoring stations. The ministry's enforcement protocols in the Yangtze River Delta and Pearl River Delta concentrate demand for field-deployable systems. Shenzhen's electronics manufacturing belt embeds EDX verification into RoHS compliance workflows.
Japan
High-purity germanium and silicon crystal production clusters in Osaka and Tokyo expose buyers to single-source risk and extended lead times. METI's support for advanced materials research sustains laboratory system demand in Tsukuba and Osaka. JEOL and Hitachi High-Tech anchor domestic supply chains.
South Korea
Semiconductor fabs in Pyeongtaek and Yongin accelerate inline metrology deployment for real-time process control. The government's K-Semiconductor Belt initiative concentrates capital equipment investment in Gyeonggi Province. Samsung and SK Hynix unbundle hardware acquisition from service contracts.
Energy Dispersive X-Ray Spectrometer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across detector cooling infrastructure and software customization depth. Laboratory-grade configurations concentrate among cryogen-free specialists and liquid nitrogen system incumbents. Three archetypes dominate: diversified analytical instrument conglomerates, electron microscopy specialists, and detector technology pure-plays. Capacity expansion in silicon drift detector fabrication and strategic partnerships for semiconductor fab integration represent the dominant competitive vectors.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Bruker Corporation occupy positions spanning laboratory and handheld configurations. Oxford Instruments exemplifies the electron microscopy specialist archetype through its focused semiconductor metrology positioning. JEOL Ltd. anchors the Japanese industrial equipment segment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bruker Corporation |
| Oxford Instruments |
| JEOL Ltd. |
| Hitachi High-Tech |
| Shimadzu Corporation |
| HORIBA |
| AMETEK |
| EDAX |
| Others |
Supply Flow & Price Mechanics
Family-owned detector fabrication specialists in Japan and Germany anchor supply-side discipline through captive silicon and germanium crystal production, translating raw material concentration into pricing power for laboratory-grade configurations while semiconductor fabs in Taiwan and South Korea negotiate volume-based service unbundling.
Pricing Analysis
Throughput-linked value pricing dominates semiconductor metrology contracts, where fabs pay per-wafer-inspected rates tied to yield improvement rather than capital expenditure. Price differentiation rests on detector cooling infrastructure and software customization depth, with cryogen-free systems commanding premiums over liquid nitrogen-dependent alternatives. Cost compression in handheld configurations is intensifying because thermoelectric cooling convergence erodes traditional precision-portability boundaries. Environmental enforcement agencies exhibit highest price sensitivity due to budget-constrained procurement protocols, while materials science institutes show lowest sensitivity given grant-funded replacement cycles.
Supply Chain Analysis
Refurbishment flows for silicon drift detectors create secondary supply channels serving cost-constrained educational installations in India and Southeast Asia. High-purity germanium and silicon crystal production concentrates in Japan and Germany, with JEOL and Hitachi High-Tech anchoring domestic fabrication. Raw material dependencies include zone-refined silicon ingots, high-purity germanium boules, and cryogenic cooling compressors. Single-source vulnerability runs through germanium crystal supply given limited global production capacity. Distribution runs through manufacturer-direct sales for laboratory systems and specialized metrology distributors for industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a detector technology transition phase, with silicon drift detector architectures displacing legacy Si(Li) configurations across high-throughput semiconductor fabs.
For Market Incumbents: Anchor laboratory-grade margins through cryogen-free detector portfolio expansion while accelerating service contract unbundling to capture recurring revenue from semiconductor fabs in Hsinchu and Seoul. Threat from benchtop XRF substitution in mining applications demands counter-positioning through light-element sensitivity differentiation. Backward integration into silicon crystal production reduces exposure to Japanese and German supply concentration. For New Entrants and Emerging Players: Launch via detector refurbishment and remanufacturing channels targeting India's PLI-scheme semiconductor fabs under construction in Gujarat and Tamil Nadu. Provincial environmental monitoring stations in China's Yangtze River Delta represent the most penetrable buyer segment given MEE GB standards enforcement. Go-to-market angle: thermoelectrically cooled portable configurations with localized Mandarin service support. For Investors and Strategic Acquirers: Distressed-cycle entries favor cryogen-free detector technology pure-plays with established European laboratory relationships during replacement cycle troughs. Long-term viability hinges on semiconductor fab integration partnerships rather than standalone instrument sales. Watch for EPA TCLP protocol amendments tightening metals detection thresholds as inflection indicator for environmental testing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Detector Portfolio Expansion | Bruker Corporation leverages thermoelectric cooling to eliminate liquid nitrogen infrastructure dependency for European laboratories. |
| Semiconductor Fab Integration Partnership | Oxford Instruments embeds metrology configurations directly into TSMC and Samsung inline process control workflows. |
| Detector Refurbishment Channel Development | Secondary supply channels serve cost-constrained educational installations across India and Southeast Asia. |
| Localized Service Unbundling | South Korean fabs separate hardware acquisition from calibration contracts, fragmenting traditional procurement models. |
| Hybrid Detector Architecture Investment | Simultaneous light-element and heavy-element sensitivity captures battery cathode precursor analysis demand under EU Green Deal mandates. |
Methodological Framework
Independent corroboration across semiconductor fab metrology directors, environmental testing laboratory managers, and materials science institute procurement officers underwrites the qualitative findings. Primary interviews with electron microscopy specialists, detector technology R&D heads, and aftermarket service providers combined with secondary validation from SEC 10-K filings, ECHA REACH enforcement databases, and MEE GB standards documentation. Bottom-up unit shipment estimates triangulate against top-down value projections derived from replacement cycle analysis and capital equipment budget disclosures.
Comparable-period anchoring to historical laboratory system replacement cycles and semiconductor fab construction timelines structures the projection horizon. Segmentation dimensions modeled include detector cooling architecture, mobility configuration, analytical application, and institutional buyer type. CAGRs derive from unit-volume trajectory analysis weighted by average selling price evolution across configuration tiers. Industry-specific inputs encompass silicon drift detector fabrication capacity expansion schedules and EU Green Deal material traceability implementation timelines.
Regulatory detection threshold revisions, semiconductor capital expenditure cycles, and cryogenic cooling supply disruptions are the dominant revision risks. Forecasts reflect assumptions regarding REACH and RoHS enforcement continuity and MEE soil contamination screening mandate persistence. Practitioners should monitor EPA TCLP protocol amendments and India's PLI scheme disbursement schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Flame Spectrometers Market