
 Small Pitch LED Display Market | 2026-2036
Small Pitch LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Small Pitch LED Display Market Analytics
Broadcast media control rooms is restructuring demand toward sub-2mm pixel pitch cabinets for 24/7 operational reliability. Leyard anchors Chinese supply through captive SMD packaging lines in Shenzhen. Samsung Electronics differentiates with semiconductor-level MicroLED transfer expertise for premium fixed installations. Unilumin competes on rental fleet scale across Asia-Pacific live events.
Small Pitch LED Display denotes direct-view LED panels with pixel pitch below 2.5 millimeters, utilizing surface-mounted device (SMD) or chip-on-board (COB) packaging with black mask treatment to enhance contrast ratio and viewing angle performance for close-proximity commercial visualization. Fixed LED Display occupies the dominant margin pool in broadcast control rooms and corporate lobbies where installation permanence justifies premium pricing. Rental LED Display sustains faster volume growth through lightweight die-cast aluminum cabinet designs that accelerate stage assembly cycles. Transparent LED Display captures niche architectural integration opportunities in retail flagship stores where glass facade permeability must persist.
China's MIIT enforces GB energy efficiency standards that disqualify high-power consumption cabinets from government procurement tenders. The EU Ecodesign Directive and RoHS substance restrictions shape import compliance costs for Asian manufacturers serving European broadcast media clients. Stakeholders must monitor COB versus SMD process economics as yield rates determine which packaging technology achieves cost parity for sub-1mm pitch production.
Market Dynamics
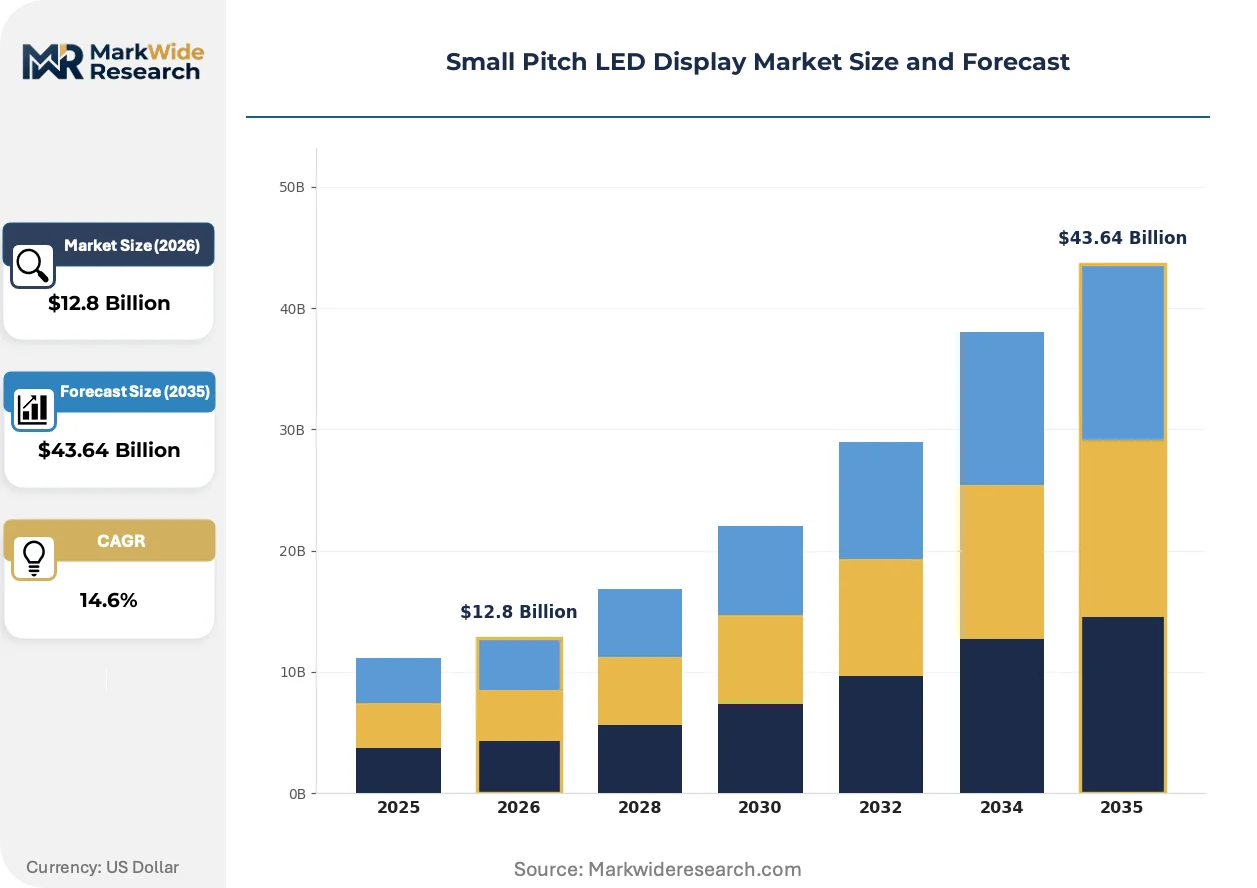
China's MIIT is enforcing GB energy efficiency standards that disqualify high-power consumption cabinets from government procurement tenders, tightening certification requirements while Guangdong province's LED manufacturing cluster concentrates fine-pitch module production.
Growth Catalysts
- Sub-2mm pixel pitch migration:Broadcast media control rooms in the United States are upgrading legacy video walls to sub-2mm pixel pitch cabinets for 24/7 operational reliability and enhanced close-proximity visualization.
- EU Ecodesign Directive compliance:European broadcast media clients now require RoHS substance restriction adherence, creating import compliance differentiation for certified Asian manufacturers.
- GB standards enforcement:China's MIIT energy efficiency mandates are accelerating product certification upgrades across Shenzhen-based supplier networks.
Market Restraints
- COB yield rate volatility:Chip-on-board packaging processes for sub-1mm pitch production suffer from yield rate instability that elevates unit economics above SMD alternatives.
- Guangdong supply concentration:Fine-pitch module production concentrates in Shenzhen, creating geographic single-point vulnerability for global cabinet assembly.
- MicroLED transfer cost barrier:Semiconductor-level mass transfer equipment for MicroLED fabrication requires capital intensity that excludes mid-tier manufacturers.
Strategic Opportunities
- India broadcast infrastructure:Control room modernization programs present underpenetrated demand for sub-2mm fixed installations in national media networks.
- Transparent LED architectural integration:Retail flagship stores in the United Arab Emirates require glass facade permeability solutions for premium brand visualization.
- Dual carbon policy alignment:China's MEE carbon neutrality targets create regulatory tailwinds for low-power COB cabinet certification in government tenders.
Industry Challenges
- Black mask treatment expertise gap:Specialized coating technicians for contrast ratio enhancement remain scarce across die-cast aluminum cabinet assembly lines.
- Multi-standard certification timelines:Simultaneous GB, CE marking, and FCC compliance testing extends product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Pitch LED Display Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed LED Display, Rental LED Display, Transparent LED Display, Curved LED Display Technology: RGB LED, DLP, OLED, MicroLED Application: Stage Shows, Advertising, Sports Events, Corporate Events End User: Broadcast Media, Retail Chains, Venues, Trade Shows |
| Companies Covered | Absen, Barco, Leyard, Daktronics, Planar Systems, Samsung Electronics, LG Electronics, Liantronics, Unilumin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Pitch LED Display Market Evolving Landscape
Surface-mounted device packaging architectures are fragmenting as chip-on-board processes gain traction for sub-1mm applications, while regulatory energy mandates and procurement model evolution reshape competitive positioning.
Chip-on-board LED packaging is modularizing fine-pitch display architecture by integrating driver ICs directly onto the PCB substrate. Broadcast control room operators in Germany and France are specifying COB cabinets for 0.9mm pitch installations where SMD black mask limitations degrade viewing angles. This technology is modularizing supply chain relationships by collapsing the traditional SMD封装-to-cabinet assembly tier.
The EU Ecodesign Directive's 2024 substance restriction amendments are tightening RoHS thresholds for cadmium and lead in LED driver components. Asian manufacturers serving European broadcast clients must reformulate solder alloys and phosphor compositions to maintain CE marking eligibility. Fine-pitch rental display segments face the steepest compliance cost escalation due to shorter product replacement cycles.
Outcome-based service contracts are displacing traditional hardware-only transactions in North American corporate lobby installations. Systems integrators now bundle content management software, remote monitoring, and predictive maintenance into multi-year subscriptions. This shift is most visible in United States financial services headquarters where facilities managers prioritize uptime guarantees over capital expenditure minimization.
Small Pitch LED Display Market Segmentation
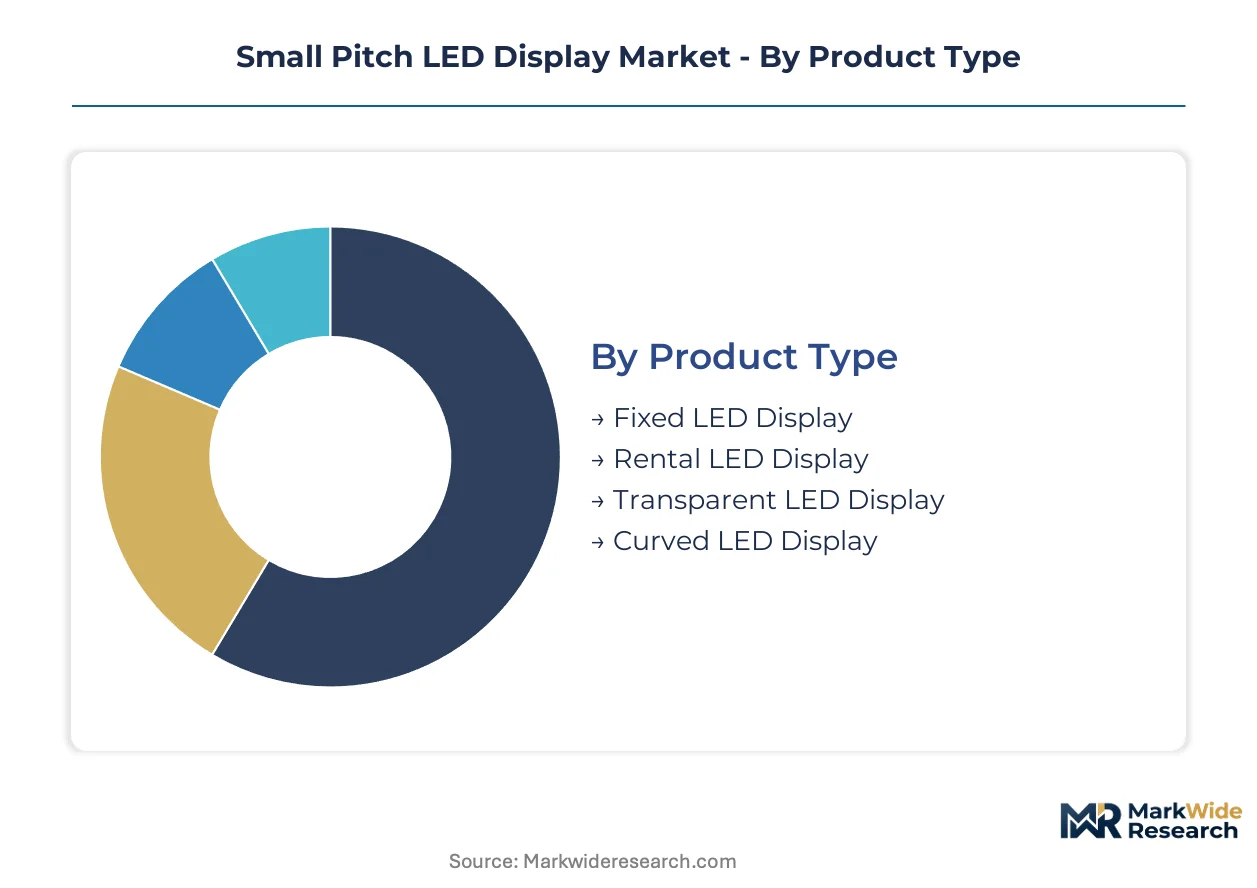
Small pitch LED displays fragment across installation permanence, packaging architecture, and proximity to content creation workflows. Each segment carries distinct margin profiles and certification requirements that reshape supplier positioning.
Product Type:
Standardization dominates at the cabinet level, yet mounting systems and control electronics diverge sharply by deployment duration and structural load requirements.
- Fixed LED Display:Permanent installations utilize steel-frame mounting with redundant power supplies for 24/7 broadcast control room duty. Demand concentrates in United States media headquarters where facilities managers prioritize decade-long operational lifespans over capital cost minimization.
- Rental LED Display:Lightweight die-cast aluminum cabinets with quick-lock mechanisms dominate live event logistics. Asia-Pacific concert touring and exhibition circuits drive volume, with Shenzhen suppliers controlling fleet manufacturing scale.
- Transparent LED Display:Glass-facade integration requires specialized PCB transparency ratios and vertical mounting hardware. United Arab Emirates retail flagship stores generate niche demand for permeable architectural visualization.
- Curved LED Display:Flexible cabinet joints enable immersive 180-degree wraparound configurations for experiential marketing installations.
Most installed capacity flows through Fixed LED Display. Expansion is steepest in Rental LED Display.
Technology:
Cost tiers separate mature packaging from frontier semiconductor processes, with yield economics determining which architectures reach commercial viability.
- RGB LED:Surface-mounted device and chip-on-board packaging variants deliver sub-2mm pitch through established SMD lines or emerging COB integration. China's GB energy efficiency standards now disqualify high-power consumption SMD cabinets from government procurement, accelerating COB migration in Shenzhen manufacturing clusters.
- MicroLED:Semiconductor-level mass transfer enables sub-0.5mm pitch without black mask limitations, though capital intensity restricts production to premium fixed installations. Samsung Electronics and select consortium partners control transfer equipment access.
- DLP:Rear-projection cubes persist in legacy control room refresh cycles where pixel pitch requirements exceed 1.5mm.
- OLED:Organic electroluminescence competes in sub-55-inch close-proximity applications where LED cabinet seams prove unacceptable.
RGB LED carries the dominant installed base. MicroLED claims the steepest expansion trajectory among frontier technologies.
Application:
Content refresh frequency and ambient lighting conditions differentiate technical specifications across use cases.
- Stage Shows:Rapid assembly demands dominate, with touring productions specifying IP65-rated cabinets for outdoor festival deployment.
- Advertising:Digital out-of-home networks in transit hubs require 5,000+ nit brightness for daylight visibility and remote content management integration.
- Sports Events:Stadium perimeter and center-hung installations prioritize impact resistance and quick module replacement protocols.
- Corporate Events:Temporary boardroom and exhibition configurations emphasize 4K resolution at sub-3-meter viewing distances.
Advertising applications absorb the greatest installed square footage. Stage Shows demonstrate the most rapid volume expansion.
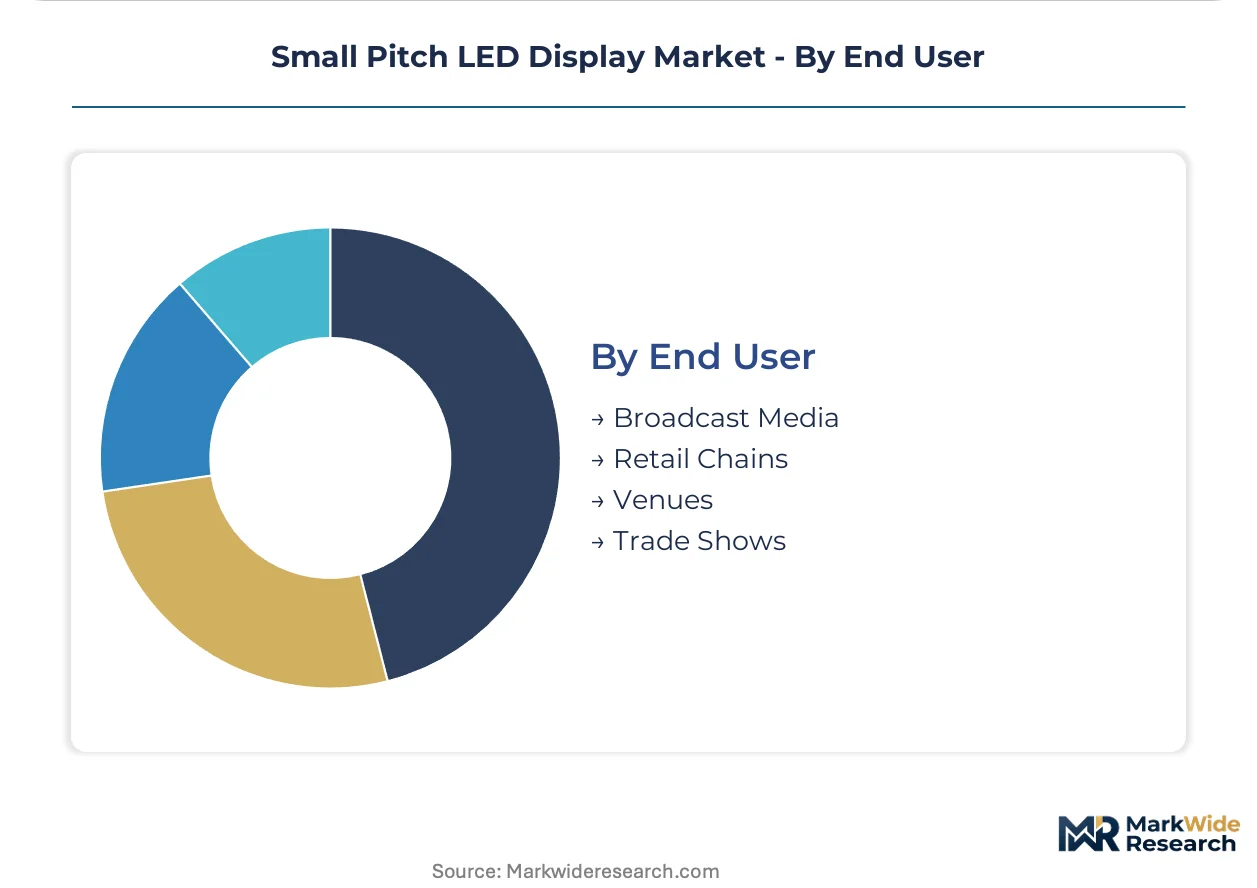
End User:
Procurement sophistication varies from centralized broadcast engineering specifications to decentralized retail facilities management.
- Broadcast Media:Control room operators specify sub-2mm pitch with 99.999% uptime guarantees and redundant signal pathing. North American network upgrades and India's national media infrastructure modernization programs concentrate demand.
- Retail Chains:Flagship store concepts in luxury segments drive transparent and curved form factors, with content management software bundled into hardware procurement.
- Venues:Concert halls and convention centers balance rental fleet partnerships against captive fixed installations for recurring programming.
- Trade Shows:Exhibition contractors prioritize rapid deployment speed and international shipping compatibility over pixel density.
Broadcast Media commands the premium tier of fixed installations. Retail Chains are gaining share fastest in architectural integration segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's LED manufacturing cluster anchors global fine-pitch module production, with Shenzhen-based suppliers controlling sub-2mm cabinet assembly for broadcast media and corporate visualization markets.
United States
Broadcast media control rooms in New York and Los Angeles are upgrading legacy video walls to sub-2mm pixel pitch cabinets for 24/7 operational reliability. FCC certification requirements shape import compliance timelines for Asian manufacturers. Texas-based systems integrators bundle remote monitoring services into multi-year corporate lobby contracts.
China
MIIT enforcement of GB energy efficiency standards disqualifies high-power consumption cabinets from government procurement tenders. Shenzhen's manufacturing cluster concentrates captive SMD packaging lines and emerging COB capacity for sub-1mm pitch production. Beijing-Tianjin-Hebei corridor demand centers on dual carbon policy alignment for low-power certification.
Germany
Broadcast control room operators in Berlin and Munich specify COB cabinets for 0.9mm pitch installations where SMD black mask limitations degrade viewing angles. EU Ecodesign Directive substance restrictions tighten RoHS thresholds for cadmium and lead in driver components. Bavaria-based engineering firms modularize supply chain relationships by collapsing traditional封装-to-cabinet assembly tiers.
India
National media infrastructure modernization programs present underpenetrated demand for sub-2mm fixed installations in Mumbai and Delhi broadcast centers. BIS certification timelines extend product launch cycles for imported cabinet assemblies. Maharashtra-based systems integrators partner with Guangdong suppliers for rental fleet deployment across Asia-Pacific live events.
United Arab Emirates
Retail flagship stores in Dubai require transparent LED solutions for glass facade permeability in premium brand visualization. MOHAP-adjacent procurement frameworks emphasize energy efficiency compliance for government-backed retail developments. Abu Dhabi-based architectural integrators specify curved form factors for immersive experiential marketing installations.
Small Pitch LED Display Market Competitive Landscape
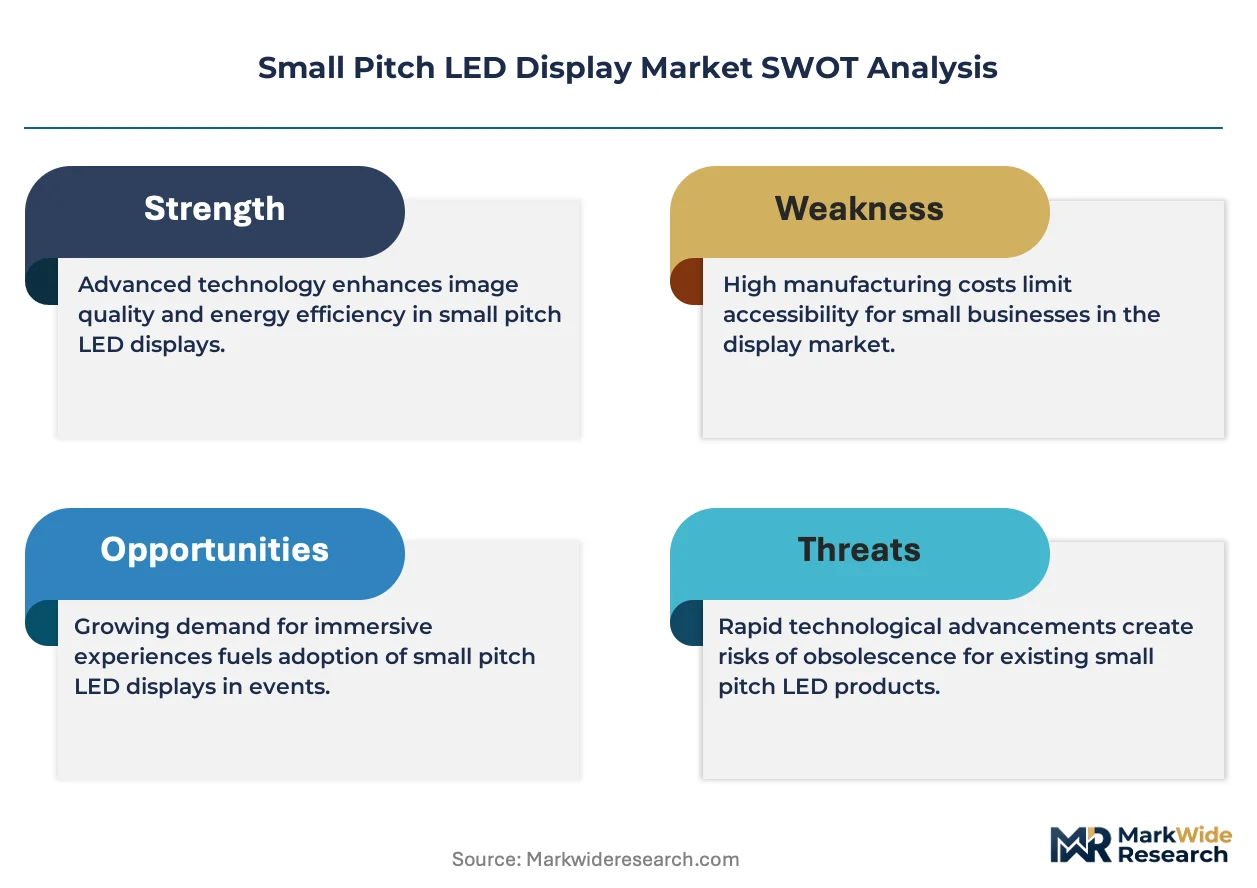
Capacity expansion dominates the current landscape as manufacturers scale COB lines for sub-1mm pitch production. The vendor base stratifies across three tiers: integrated semiconductor specialists with mass transfer expertise, Shenzhen-based module assemblers with captive packaging, and regional systems integrators bundling software services. Strategic archetypes include technology licensors extracting royalties from transfer equipment, scale-driven rental fleet operators, and outcome-based service providers. M&A activity concentrates on COB yield optimization startups, while strategic partnerships bridge gap between SMD legacy capacity and MicroLED frontier processes.
Among Chinese manufacturers, Leyard and Unilumin exemplify the integrated module assembly archetype, with Shenzhen headquarters positioning them within Guangdong's manufacturing cluster. Samsung Electronics represents the semiconductor-level specialist tier, leveraging Korean fab ecosystem access for premium fixed installation markets. These three entities anchor competitive positioning across the technology spectrum from established SMD through emerging COB to frontier MicroLED architectures.
| Leading Market Players |
|---|
| Absen |
| Barco |
| Leyard |
| Daktronics |
| Planar Systems |
| Samsung Electronics |
| LG Electronics |
| Liantronics |
| Unilumin |
| Others |
Value Network & Pricing Analysis
Captive SMD packaging integration across Shenzhen-based suppliers anchors both cost position and pricing power for sub-2mm cabinet assembly, with Leyard and Unilumin leveraging in-house LED die bonding to compress module economics while GB energy efficiency standards disqualify outsourced high-power alternatives from government tenders.
Pricing Analysis
Driver IC and black mask coating cost pass-throughs dominate module-level pricing, with three-tier pricing structure across premium MicroLED, standard COB, and economy SMD tiers separating broadcast media specifications from rental fleet procurement. Price differentiation hinges on certification grade—CE marking and FCC compliance add compliance premiums—and volume scale for die-cast aluminum cabinet orders. Cost compression in economy SMD tiers is intensifying because MIIT energy mandates accelerate COB migration, squeezing legacy packaging margins. Rental fleet operators exhibit highest price sensitivity; broadcast control room engineers prioritize uptime guarantees over capital minimization.
Supply Chain Analysis
Freight cost volatility from Guangdong province to North American broadcast clients and European architectural integrators compresses margin on lightweight die-cast aluminum cabinets, with sea-air multimodal routing gaining share for urgent control room deployments. Supply concentrates in China, South Korea, and Taiwan, with LED epitaxial wafers, driver ICs, and PCB substrates drawing from concentrated Asian semiconductor fabrication. Single-source vulnerability in MicroLED mass transfer equipment—controlled by Samsung Electronics and select Korean consortium partners—threatens premium tier expansion. Distribution runs through systems integrators bundling installation and remote monitoring for corporate lobby accounts, while rental fleet deployment flows through event production houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as broadcast infrastructure modernization cycles and regulatory energy mandates create replacement pull-through across installed base upgrades.
For Market Incumbents: Hedge COB yield volatility by maintaining parallel SMD capacity for sub-1.5mm pitch production while GB standards enforcement accelerates certification timelines. Samsung Electronics' semiconductor-level mass transfer expertise threatens premium fixed installation margins; defend through captive driver IC integration and black mask treatment proprietary processes. Prioritize backward integration into LED die packaging to compress module economics against Shenzhen cluster competition. For New Entrants and Emerging Players: Launch via rental fleet partnerships targeting India's national media infrastructure modernization and underpenetrated broadcast control room segments in Mumbai and Delhi. White-space concentrates in transparent LED architectural integration for UAE retail flagships and curved form factors for experiential marketing. Go-to-market should emphasize lightweight cabinet design and rapid assembly protocols for Asia-Pacific concert touring circuits. For Investors and Strategic Acquirers: Roll-up economics work for COB yield optimization specialists because sub-1mm pitch production suffers from technician scarcity and process instability that rewards acquisition-driven capability consolidation. Long-term viability frames around 5-10 year regulatory tailwinds from dual carbon policy alignment and EU Ecodesign Directive compliance cost escalation. Signal to watch: BIS certification timeline compression in India as import compliance barriers shift competitive position toward certified Asian manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| COB Packaging Line Expansion | GB energy efficiency mandates disqualify high-power SMD from government tenders, accelerating migration. |
| MicroLED Mass Transfer Partnership | Samsung Electronics controls equipment access for sub-0.5mm pitch premium fixed installations. |
| Outcome-Based Service Contract Launch | Texas-based systems integrators bundle remote monitoring into multi-year corporate lobby subscriptions. |
| India Broadcast Infrastructure Entry | BIS certification timelines favor early movers in national media control room modernization programs. |
| Transparent LED Architectural Integration | UAE retail flagships require glass facade permeability solutions for premium brand visualization. |
Research Methodology
Bottom-up broadcast media and rental fleet demand modeling reconciled against top-down Guangdong manufacturing cluster capacity tracking forms the analytical core of this study. Primary interviews with LED packaging engineers, broadcast control room operators, systems integrators, and rental fleet managers combined with secondary validation from MIIT GB standard filings, FCC equipment authorization databases, EU Ecodesign Directive amendments, and Shenzhen customs export records. Triangulation across stakeholder input and trade data ensures segmentation integrity.
Historical trendline analysis of SMD-to-COB technology transitions and MicroLED pilot installations informed projection framework development across product type, packaging technology, application, and end-user dimensions. CAGRs derive from segment-level volume and value buildups normalized against macroeconomic anchors and regulatory enforcement timelines. Forecast inputs include yield rate trajectories for sub-1mm COB production and certification timeline compression for multi-standard compliance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT enforcement acceleration or MicroLED transfer cost breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
China LED Market
LED
High Power LED Market
LED
Japan Indoor LED Lighting Market
LED
Arrow LED Displays Market
LED
Bi-Color LED Ring Light Market
LED
LED Chip Market
LED
Outdoor LED Display Market
LED
Europe LED Packaging Market
LED
Mexico LED Lighting Market
LED
LED Lighting Solution Market
LED
LED Mask Market
LED
Dot-Matrix LED Displays Market
LED
Saudi Arabia LED Lights Market
LED
North America Commercial LED Lighting Market
LED
Programmable LED Drivers Market