
 Global Spinal Cord Stimulation Devices Market | 2026-2036
Global Spinal Cord Stimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinal Cord Stimulation Devices Market Foresight
Subscription-based remote monitoring and programming services is decoupling hardware sales from long-term revenue capture in the spinal cord stimulation landscape. Medtronic plc leverages its end-to-end ecosystem of implantable platforms and digital health infrastructure to sustain recurring revenue streams. Boston Scientific Corporation anchors its competitive stance through differentiated waveform portfolios spanning conventional and burst stimulation modalities. Abbott Laboratories specializes in directional lead architectures that compete on targeted neural coverage precision.
Spinal cord stimulation devices are implantable neuromodulation systems that deliver electrical impulses to the dorsal column via percutaneous or paddle leads to interrupt pain signal transmission, typically operating at frequencies from 2 Hz to 10 kHz depending on programming modality. These systems serve primary commercial purpose in reducing opioid dependency among patients with refractory chronic back and limb pain. Implantable pulse generators command the dominant margin pool due to their multi-year replacement cycles and firmware upgradeability, while high-frequency SCS represents the fastest-expanding technology segment as paresthesia-free therapy gains clinical traction. External trial systems retain steady procedural penetration as physicians prioritize predictive patient selection before permanent implantation.
The FDA oversees premarket notification and PMA pathways for neuromodulation hardware, while the EU MDR imposes strengthened clinical evidence requirements on active implantable devices entering European markets. ISO 14708-3 standards govern active implantable medical devices specific to neurostimulators, shaping design verification protocols and post-market surveillance obligations. Stakeholders must monitor evolving CMS national coverage determinations for SCS indications, as reimbursement breadth for peripheral neuropathy and post-surgical pain applications will dictate addressable market expansion trajectories independent of technological capability advances.
Market Dynamics
Subscription-based remote monitoring services are decoupling hardware sales from recurring revenue capture, forcing device manufacturers to build integrated digital ecosystems that sustain long-term patient engagement beyond the initial implant procedure.
Growth Catalysts
- Breakthrough Device Designation:The FDA's accelerated premarket review pathway compresses technology access timelines for novel neuromodulation platforms, reducing regulatory friction for paresthesia-free stimulation modalities entering clinical use.
- Ambulatory Surgery Center Expansion:Outpatient procedural volumes at ASCs are rising as these facilities build dedicated neuromodulation service lines, creating dedicated procedure slots for spinal cord stimulation trials and permanent implants.
- High-Frequency Stimulation:10 kHz therapy is overtaking conventional tonic stimulation in physician preference surveys, eliminating paresthesia mapping requirements and shortening operative time per case.
Market Restraints
- Implantable Pulse Generator Cost Concentration:IPG hardware represents the dominant capital outlay per case, with multi-year replacement cycles creating reimbursement friction when payers challenge medical necessity for generator exchanges.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation imposes strengthened post-market surveillance and clinical data requirements on active implantable neurostimulators, extending market access timelines for new entrants.
- Reimbursement Geography Constraints:Established payment frameworks for chronic pain interventions concentrate in the United States, limiting addressable patient populations in markets where SCS lacks national coverage determination support.
Strategic Opportunities
- Peripheral Neuropathy Indication Expansion:CMS national coverage determination revisions for diabetic peripheral neuropathy would unlock Medicare beneficiary access, expanding the eligible patient pool beyond failed back surgery syndrome.
- Closed-Loop Sensing Convergence:Integration of evoked compound action potential sensing with automated output adjustment creates differentiated positioning against open-loop competitors through personalized therapeutic response optimization.
- Directional Lead Architecture:Multi-column electrode designs enable targeted dorsal column recruitment with reduced off-target stimulation, supporting premium pricing through demonstrable paresthesia reduction in lateralized pain presentations.
Industry Challenges
- Neuromodulation Specialist Workforce Constraints:The limited pipeline of fellowship-trained pain physicians capable of complex lead placement creates procedural capacity bottlenecks that constrain volume growth independent of device availability.
- External Trial-to-Permanent Conversion Optimization:Physicians face operational friction in predicting long-term responders during the temporary screening phase, with suboptimal selection algorithms generating costly permanent implantation in non-responders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinal Cord Stimulation Devices Market |
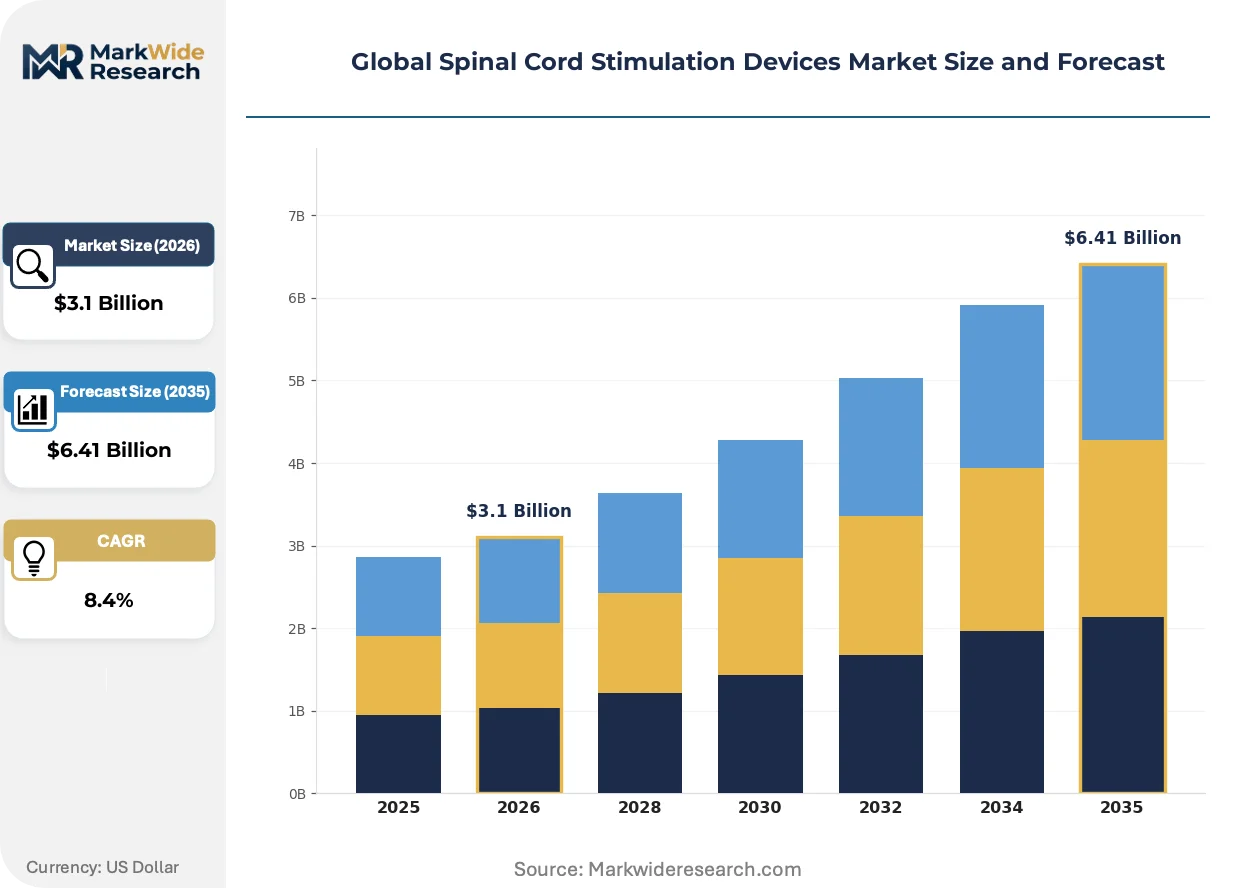
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pulse Generators, Leads, Electrodes, External Trial Systems Technology: Conventional Stimulation, High-Frequency SCS, Burst SCS, Wireless SCS Application: Chronic Pain Management, Peripheral Neuropathy, Ischemic Pain, Post-Surgical Pain End User: Specialty Clinics, Ambulatory Surgery Centers, Pain Management Specialists, Rehabilitation Centers |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Nevro Corp, Saluda Medical, Stimwave Technologies, Nuvectra, Cirtec, Synapse Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinal Cord Stimulation Devices Market Shifts & Advancements
Paresthesia-free stimulation modalities are compressing the competitive window for conventional tonic therapy, while regulatory frameworks on both sides of the Atlantic accelerate differentiation between sensing-enabled and open-loop platforms.
Burst stimulation is overtaking conventional tonic waveforms in new implant preferences across academic medical centers and high-volume private practice pain clinics. The patterned delivery of closely spaced action potentials followed by quiescent periods eliminates the tingling sensation patients associate with older devices. This sensory profile enables simpler programming protocols and reduces the specialist time required for intraoperative paresthesia mapping, compressing procedure duration and facility cost per case.
The EU MDR's strengthened clinical evidence requirements for active implantable devices are forcing manufacturers to generate prospective registry data before European commercialization. This regulatory friction disproportionately burdens smaller entrants lacking established post-market surveillance infrastructure, consolidating competitive advantage with incumbents who can absorb extended validation timelines. Germany's national reimbursement institute and France's ANSM are aligning their evidence expectations with the MDR framework, creating harmonized but elevated barriers across the continent's largest markets.
Patient selection for permanent implantation is migrating toward algorithmic risk stratification using machine learning models trained on screening trial outcomes. Pain management practices are adopting predictive analytics platforms that integrate psychological screening scores, quantitative sensory testing, and historical opioid consumption patterns to identify responders before hardware commitment. This behavioral shift is most visible in United States academic medical centers, where value-based care contracts create financial exposure for non-responder implants and drive investment in preoperative prediction infrastructure.
Global Spinal Cord Stimulation Devices Market Segmentation
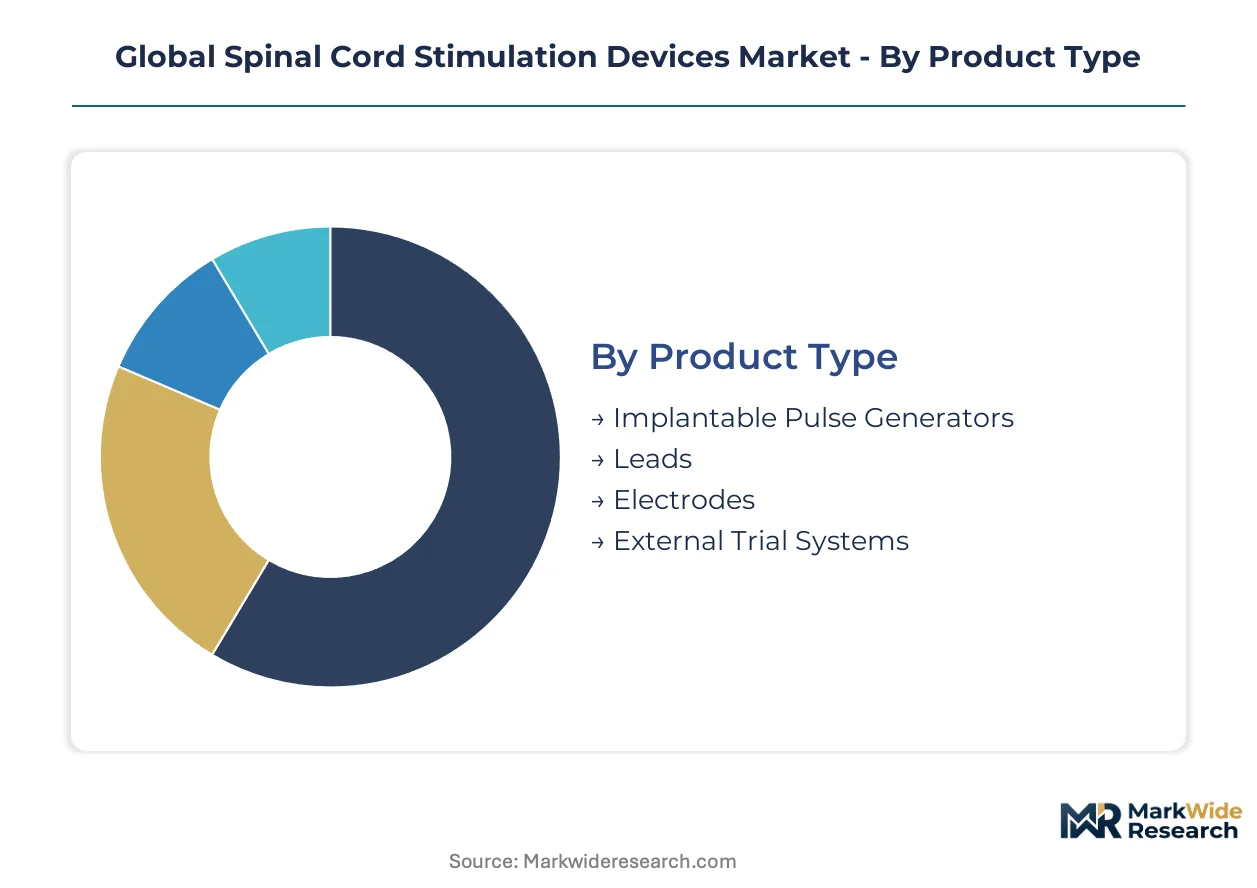
Spinal cord stimulation device segmentation reveals distinct margin profiles and replacement-cycle dynamics across hardware categories. Technology differentiation and application breadth determine pricing power and patient access trajectories.
Product Type:
Upgrade and replacement cycles vary dramatically across hardware categories, with multi-year IPG lifespans creating predictable revenue windows against consumable lead sets.
- Implantable Pulse Generators:Battery-powered or rechargeable implantable units deliver electrical impulses through transcutaneous or paddle leads. Demand concentrates in the United States where Medicare reimbursement supports generator replacement every 4-7 years. Firmware upgradeability extends hardware utility and defers replacement decisions.
- Leads:Percutaneous and paddle configurations establish dorsal column contact with varying electrode densities. Academic medical centers in Germany favor surgical paddle placement for complex anatomical presentations, driving premium pricing for multi-column directional architectures.
- Electrodes:Contact arrays interface directly with neural tissue and determine stimulation field geometry. Japanese pain specialists prioritize electrode durability given constrained revision surgery capacity.
- External Trial Systems:Temporary percutaneous configurations enable predictive patient screening before permanent commitment. ASC adoption in Texas and Florida accelerates trial-to-permanent conversion workflows.
Volume placements concentrate in Implantable Pulse Generators; the faster expansion belongs to External Trial Systems.
Technology:
Cost tier stratification separates established tonic modalities from premium paresthesia-free alternatives commanding reimbursement premiums.
- Conventional Stimulation:Tonic waveform delivery at 2-100 Hz requires intraoperative paresthesia mapping and specialist programming time. Mature reimbursement codes support broad access, though physician preference is shifting toward sensory-neutral alternatives.
- High-Frequency SCS:10 kHz therapy eliminates paresthesia through sustained depolarization without action potential generation. United States academic centers lead adoption, shortening operative time and reducing follow-up programming burden.
- Burst SCS:Patterned pulse trains with quiescent intervals mimic natural neural firing patterns. French pain clinics report superior outcomes in complex regional pain syndrome, driving selective premium uptake.
- Wireless SCS:Lead-only implants with external power transmission eliminate generator pocket complications. Early clinical validation in Switzerland and the Netherlands supports regulatory pathway development.
Procedure volumes still favor Conventional Stimulation; High-Frequency SCS is gaining share fastest among new implants.
Application:
Addressable patient populations expand with indication breadth, though reimbursement authorization lags clinical validation for emerging pain etiologies.
- Chronic Pain Management:Failed back surgery syndrome and persistent limb pain constitute the historical commercial foundation. United States Medicare coverage determinations anchor volume concentration in lumbar radiculopathy and complex regional pain syndrome.
- Peripheral Neuropathy:Diabetic and chemotherapy-induced neuropathies represent substantial unmet need with limited pharmacologic alternatives. CMS national coverage determination expansion would unlock Medicare beneficiary access beyond current off-label utilization.
- Ischemic Pain:Refractory angina and peripheral arterial disease applications demonstrate symptomatic benefit in European registries. German and Italian reimbursement authorities evaluate cost-effectiveness against revascularization alternatives.
- Post-Surgical Pain:Acute-to-chronic transition prevention targets surgical populations before opioid dependency develops. Veterans Health Administration facilities pilot perioperative protocols for high-risk orthopedic procedures.
Patient volumes cluster in Chronic Pain Management; Peripheral Neuropathy shows the steepest expansion trajectory pending coverage expansion.
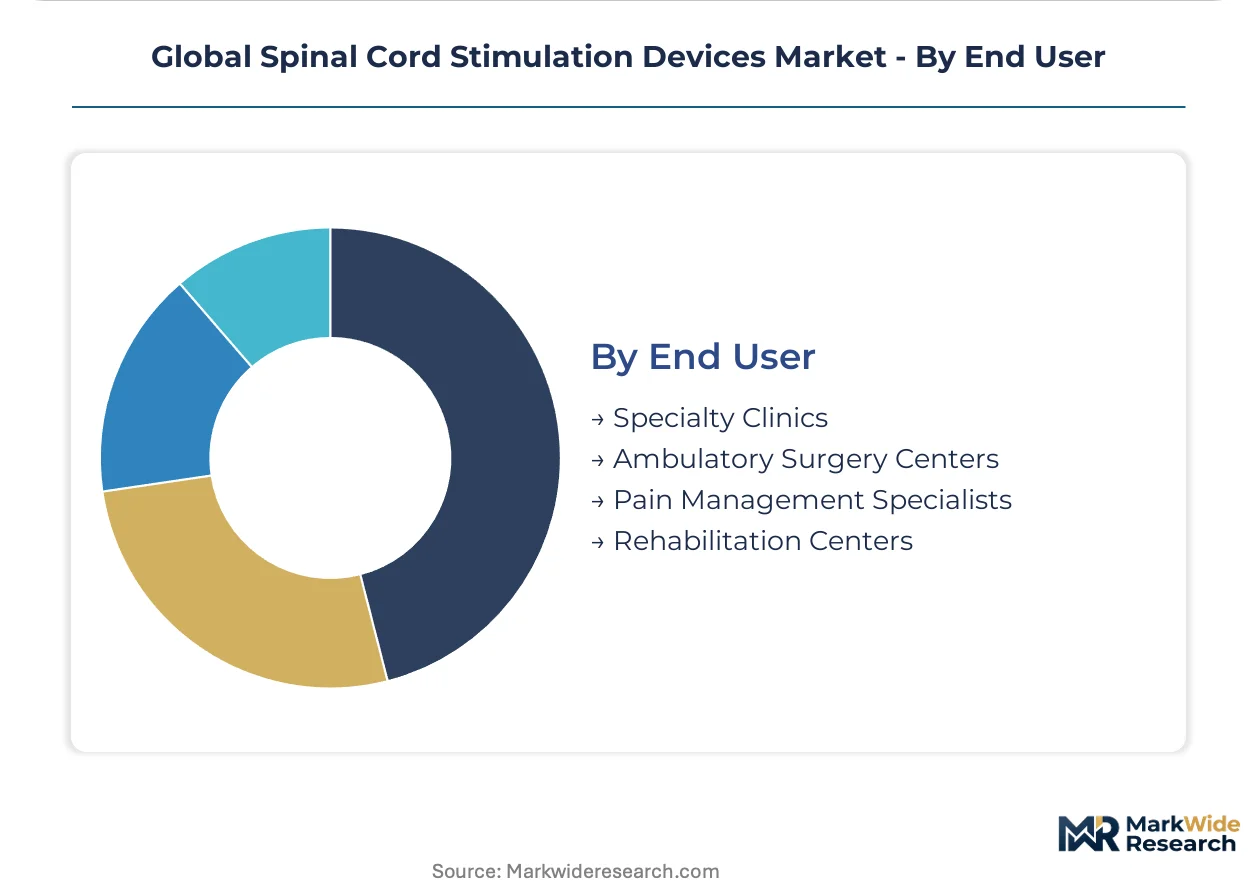
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging volume contracts against specialist practice purchasing autonomy.
- Specialty Clinics:Dedicated pain practices maintain direct manufacturer relationships and device evaluation programs. Independent physician ownership in the United States sustains multi-vendor sourcing flexibility.
- Ambulatory Surgery Centers:Outpatient facilities build dedicated neuromodulation service lines with standardized implant protocols. Florida and Arizona ASC networks achieve economies through high-volume surgeon partnerships.
- Pain Management Specialists:Fellowship-trained physicians control lead placement technique and device selection. Workforce constraints in the United Kingdom limit procedural capacity independent of device availability.
- Rehabilitation Centers:Integrated care settings coordinate SCS with functional restoration programs. German medical rehabilitation facilities combine implantation with multimodal pain management.
Procedure concentration sits with Pain Management Specialists; Ambulatory Surgery Centers are climbing the fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device consumption concentrates in the United States while manufacturing and clinical validation activities distribute across Switzerland, Germany, and Japan. Production of implantable pulse generators and lead assemblies spans multiple regulatory jurisdictions.
United States
Medicare reimbursement frameworks for chronic pain interventions sustain the largest installed base of spinal cord stimulation systems worldwide. The FDA's breakthrough device designation pathway accelerates premarket review for novel neuromodulation platforms. Pain management specialists in Florida and Texas ASC networks drive outpatient procedural volume expansion.
Germany
Academic medical centers in Berlin and Munich favor surgical paddle lead placement for complex anatomical presentations, sustaining premium pricing for multi-column directional architectures. The national reimbursement institute evaluates cost-effectiveness evidence against pharmacologic alternatives. Baden-Württemberg hosts concentrated neuromodulation service line development across integrated hospital networks.
Switzerland
Early clinical validation of wireless spinal cord stimulation systems proceeds through university hospital partnerships in Zurich and Geneva. Swissmedic maintains streamlined review pathways for active implantable devices with existing FDA clearance. Basel-area research clusters coordinate post-market surveillance data generation for EU MDR compliance.
Japan
Pain specialists prioritize electrode durability given constrained revision surgery capacity in metropolitan Tokyo and Osaka. The PMDA's Shonin approval process for active implantable medical devices requires domestic clinical trials. Kansai-region medical device distributors build specialized neuromodulation logistics infrastructure.
France
ANSM aligns post-market surveillance expectations with EU MDR strengthened clinical evidence requirements for neurostimulators. Parisian pain clinics report superior outcomes with burst stimulation modalities in complex regional pain syndrome presentations. Île-de-France academic centers pilot closed-loop sensing integration protocols.
Global Spinal Cord Stimulation Devices Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated digital ecosystems, while mid-tier specialists compete on waveform differentiation and targeted neural coverage. The vendor base stratifies across three archetypes: diversified medtech conglomerates with end-to-end platforms, neuromodulation pure-plays with specialized stimulation modalities, and emerging entrants pursuing wireless and closed-loop architectures. Competitive moves concentrate on strategic partnerships for algorithm development and portfolio diversification into peripheral nerve stimulation adjacencies.
Within the diversified medtech tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven ecosystem strategies that bundle implantable hardware with remote monitoring infrastructure. Abbott Laboratories occupies a position among premium-tier competitors emphasizing directional lead precision. Nevro Corp and Saluda Medical represent the neuromodulation specialist archetype, with Nevro anchoring high-frequency paresthesia-free therapy positioning and Saluda Medical exemplifying closed-loop sensing convergence. Stimwave Technologies sits within the emerging wireless segment, pursuing lead-only implant architectures that eliminate generator pocket complications.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Nevro Corp |
| Saluda Medical |
| Stimwave Technologies |
| Nuvectra |
| Cirtec |
| Synapse Biomedical |
| Others |
Supply & Pricing Matrix
Biocompatible titanium alloy costs for implantable pulse generator housings flow through Swiss and German precision machining clusters before reaching three-tier pricing stratification across premium sensing-enabled systems, standard high-frequency platforms, and economy tonic stimulation devices.
Pricing Analysis
Margin tightening in economy-tier conventional stimulation traces to CMS reimbursement compression on older procedural codes and physician migration toward paresthesia-free alternatives. Premium-mid-economy pricing differentiation rests on firmware upgradeability, directional lead precision, and closed-loop sensing capability. Cost-down pressure on standard-tier hardware accelerates because ambulatory surgery centers negotiate volume contracts with GPOs. Academic medical centers show least price sensitivity; independent pain clinics in competitive US markets exhibit highest.
Supply Chain Analysis
EU MDR domestic-content evidence requirements are reshaping sourcing toward European contract manufacturers with established post-market surveillance infrastructure. Implantable pulse generator assembly concentrates in Switzerland, Germany, and Ireland; lead fabrication draws from Minnesota and Massachusetts medical device clusters. Critical dependencies include platinum-iridium electrode alloys, hermetic ceramic feedthroughs, and lithium-ion rechargeable cells. Single-source vulnerability sits with specialized neurostimulator battery suppliers. Distribution runs through hospital purchasing committees and ambulatory surgery center GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU MDR clinical evidence burdens and FDA breakthrough pathway advantages force capital-constrained neuromodulation pure-plays toward acquisition or exit.
For Market Incumbents: To counter closed-loop sensing convergence from Saluda Medical and emerging wireless architectures from Stimwave Technologies, Medtronic and Boston Scientific should deepen backward integration into electrode alloy supply and acquire predictive analytics platforms for trial-to-permanent conversion optimization. Channel control through exclusive ASC partnerships in Florida and Texas anchors volume defense. For New Entrants and Emerging Players: Direct-to-physician digital education platforms bypass incumbent field clinical specialist networks and open access to independent pain practices. Peripheral neuropathy indication expansion pending CMS national coverage determination offers the most penetrable white space. Reimbursement strategy consulting bundled with device trials accelerates hospital purchasing committee access. For Investors and Strategic Acquirers: FDA breakthrough device designation receipt is the leading indicator that a neuromodulation platform will achieve compressed market access timelines and premium reimbursement positioning. Five-to-ten year viability favors closed-loop sensing and wireless architectures over commodity tonic stimulation. Target acquisition profile: neuromodulation pure-plays with EU MDR technical files in progress and Medicare coverage determination strategy in place.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerates premarket review timelines for paresthesia-free stimulation platforms entering clinical use. |
| EU MDR Technical File Investment | Secures European market access against strengthened clinical evidence requirements for active implantables. |
| ASC Network Partnership Development | Captures outpatient procedural volume migration in Florida and Texas neuromodulation service lines. |
| Closed-Loop Sensing Platform Integration | Differentiates against open-loop competitors through automated evoked compound action potential response optimization. |
| Peripheral Neuropathy Reimbursement Strategy | Unlocks Medicare beneficiary access beyond failed back surgery syndrome for diabetic neuropathy indications. |
Research Methodology
Multi-period observation of implant volumes, replacement cycle timing, and CMS coverage determination status anchored the trend analysis, supplemented by interviews with pain management specialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, CMS national coverage determinations, ISO 14708-3 standards documentation, and EU MDR notified body certificates. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates.
Segment-weighting across product type, technology modality, application indication, and end-user channel shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves for high-frequency and burst stimulation adoption, overlaid with replacement cycle dynamics for implantable pulse generators. Forecast inputs incorporated ASC procedural volume migration rates and EU MDR transition timelines for technical file completion.
The model holds under stable CMS reimbursement levels and FDA review pathway consistency; deviation in national coverage determination scope or MDR implementation enforcement would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Silastic Implant Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Liposuction Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market