
 Respiratory Oxygen Delivery Devices Market | 2026-2036
Respiratory Oxygen Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Oxygen Delivery Devices Market Analytics
ISO 80601-2-69 certification for oxygen concentrator safety and performance is redrawing competitive boundaries in this sector. Koninklijke Philips N.V. leverages its integrated respiratory portfolio to sustain hospital contracting relationships across North America and Europe. Drägerwerk AG & Co. KGaA anchors its position through intensive R&D in anesthesia and ventilation adjacencies. Fisher & Paykel Healthcare Limited differentiates via humidification technology leadership that extends oxygen therapy comfort metrics.
Respiratory oxygen delivery devices comprise mechanical and electronic systems engineered to administer controlled oxygen concentrations, typically ranging from 21% to 100% FiO2, through nasal cannulas, masks, or endotracheal interfaces for therapeutic gas exchange support. Portable oxygen concentrators employing pressure swing adsorption with sieve bed molecular filtration dominate the product type landscape, while fixed bedside systems retain higher per-unit margins in institutional settings. The homecare patient end-user segment shows the steepest volume trajectory as reimbursement frameworks shift toward ambulatory chronic disease management. Electronic technology platforms are displacing pneumatic controls in premium device tiers, concentrating margin pools among manufacturers with proprietary valve and sensor architectures.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development cycles and market access timelines for manufacturers targeting dual-territory distribution. The EPA's energy efficiency standards for medical devices additionally influence concentrator power consumption specifications in the United States. Stakeholders must monitor evolving CMS national coverage determinations for home oxygen therapy, as reimbursement thresholds directly condition patient eligibility volumes and device procurement cadence across integrated delivery networks.
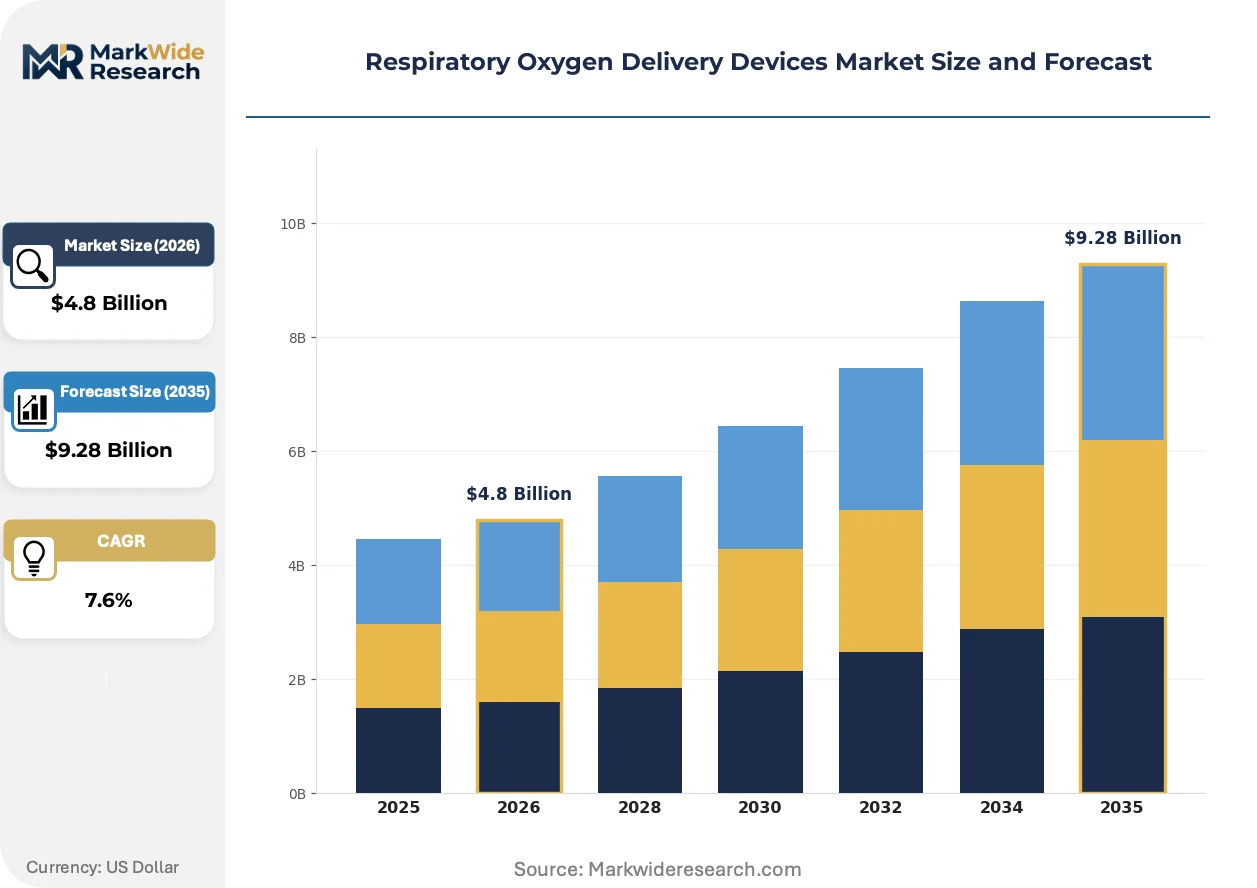
Market Dynamics
Portable oxygen concentrator technology is decomposing the traditional boundary between institutional and homecare oxygen delivery, forcing manufacturers to reengineer device architectures around ambulatory power efficiency and patient self-management capabilities rather than bedside reliability alone.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement eligibility for home oxygen therapy in the United States is pulling chronic obstructive pulmonary disease patients out of institutional settings and into ambulatory care models.
- Pressure Swing Adsorption Miniaturization:Advances in sieve bed molecular filtration are enabling concentrator weight reductions below five pounds without sacrificing oxygen purity thresholds.
- Germany's Hospital Consolidation:Integrated delivery networks across Bavaria and North Rhine-Westphalia are standardizing on single-vendor respiratory portfolios to reduce procurement complexity.
Market Restraints
- EU MDR Technical Documentation:Extended conformity assessment timelines for Class IIa medical devices are delaying market entry for oxygen concentrator manufacturers by twelve to eighteen months.
- Lithium-Ion Battery Supply Concentration:Portable device production depends on cell suppliers concentrated in East Asian manufacturing corridors, exposing assembly lines to raw material allocation volatility.
- Pneumatic System Obsolescence:Legacy oxygen delivery platforms face technical limitations in pulse-dose oxygen conservation, capping their competitiveness against electronic valve architectures.
Strategic Opportunities
- Japan's Super-Aged Society:METI incentives for home medical device deployment are creating white space for concentrator manufacturers targeting the seventy-five-plus demographic with simplified user interfaces.
- Wearable Oxygen Monitoring Convergence:Integration of pulse oximetry with concentrator feedback loops is enabling closed-loop oxygen titration for nocturnal hypoxemia patients.
- Direct-to-Patient Subscription Models:Equipment-as-a-service channels are bypassing durable medical equipment distributors in United States metropolitan markets.
Industry Challenges
- ISO 80601-2-69 Certification Bottlenecks:Testing laboratory capacity constraints are compressing product launch calendars for manufacturers seeking electrical safety and performance validation.
- Legacy EMR Integration Complexity:Homecare oxygen devices must interface with hospital information systems for remote patient monitoring, requiring FHIR standard compliance that strains firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Oxygen Delivery Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Concentrators, Nebulizers, Intubation Sets, BiPAP Devices End User: Homecare Patients, Hospitals, Emergency Medical Services, Rehabilitation Centers Technology: Portable Devices, Fixed Devices, Magnetic Technology, Electronic Technology Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Emergency Situations, Sleep Apnea Treatment |
| Companies Covered | Koninklijke Philips N.V., Becton, Dickinson and Company, Teleflex Incorporated, Drägerwerk AG & Co. KGaA, Fisher & Paykel Healthcare Limited, Smiths Group PLC, Invacare Corporation, Inogen, Inc., ResMed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Oxygen Delivery Devices Market Evolving Landscape
Electronic control architectures are supplanting pneumatic systems across oxygen delivery platforms, triggering parallel shifts in regulatory compliance frameworks and procurement evaluation criteria that favor integrated sensor and valve ecosystems.
Miniaturized pressure swing adsorption systems are decomposing the traditional trade-off between portability and therapeutic performance. Homecare patients with active lifestyles are adopting sub-five-pound concentrators at accelerating rates. This technology is decomposing the hospital-centric device market into discrete ambulatory and nocturnal use cases with divergent specification requirements.
The EU MDR's enhanced clinical evidence requirements for Class IIa devices are extending technical documentation preparation cycles for oxygen concentrator manufacturers. Notified body capacity constraints are compressing available certification slots. Portable system categories face the steepest compliance cost inflation as manufacturers commission post-market clinical follow-up studies.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing concentrator vendors to compete on discrete service level agreements. Integrated delivery networks in the United States are consolidating vendor panels to three preferred suppliers per region. This behavioral shift is most visible in Texas and Florida, where Medicare Advantage penetration is highest and payor cost-containment pressure is reshaping equipment acquisition patterns.
Respiratory Oxygen Delivery Devices Market Segmentation
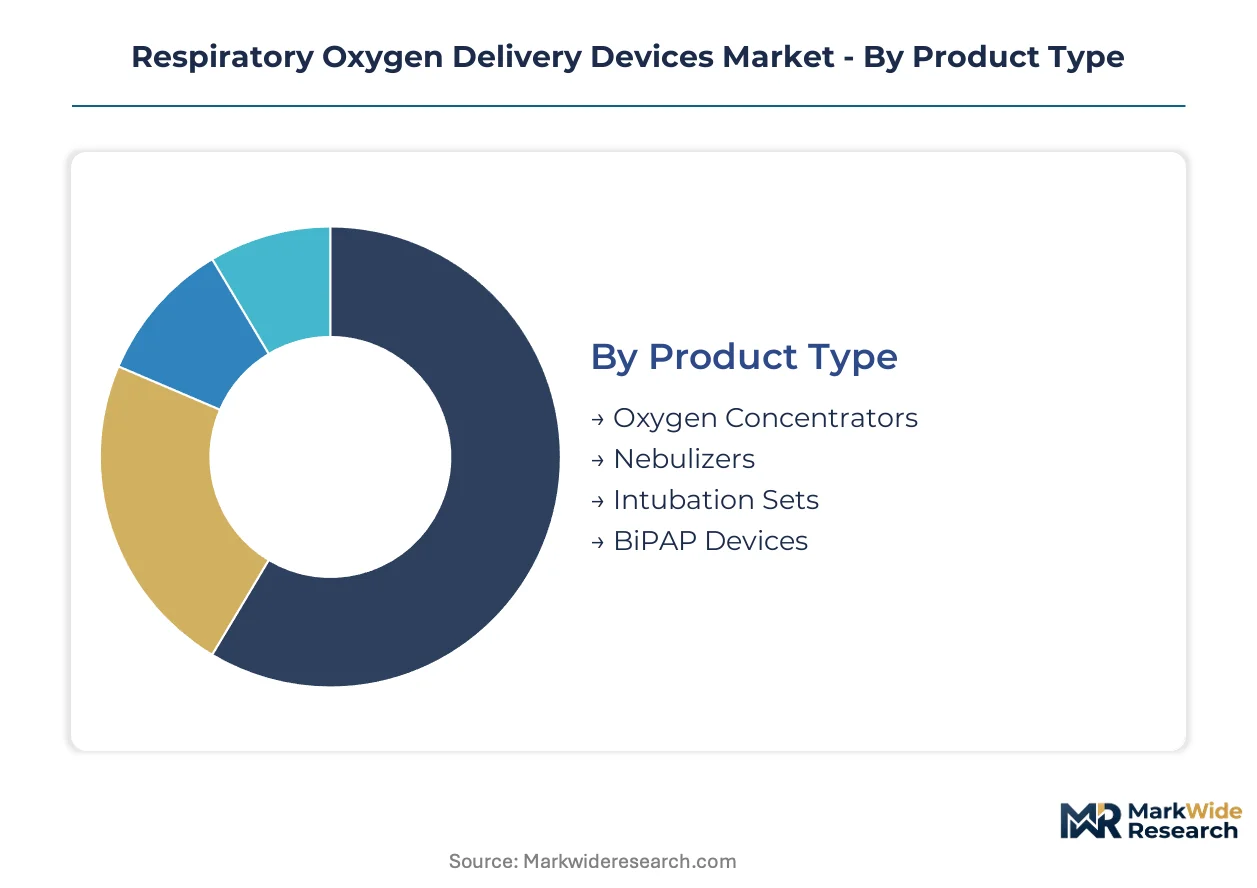
Oxygen delivery device manufacturers segment their portfolios to align reimbursement pathways with distinct clinical workflows. Each dimension—product type, end user, technology, and application—carries unique regulatory and procurement requirements that reshape competitive positioning.
Product Type:
Oxygen concentrators and nebulizers anchor domestic manufacturing footprints in the United States and Germany, while intubation sets and BiPAP devices flow through export-led supply chains concentrated in East Asian assembly corridors.
- Oxygen Concentrators:Pressure swing adsorption systems with molecular sieve beds generate 90-95% oxygen purity from ambient air. Demand concentrates among homecare patients in the United States where CMS reimbursement expansion pulls chronic obstructive pulmonary disease management into ambulatory settings. Portable sub-five-pound variants are displacing fixed bedside units in metropolitan markets.
- Nebulizers:Compressor-driven and mesh-based aerosol delivery platforms administer bronchodilators and corticosteroids to lower respiratory tracts. Hospital procurement committees in Germany's consolidated Bavarian networks favor single-vendor respiratory portfolios bundling nebulizers with oxygen concentrators. Mesh technology variants command premium positioning in pediatric applications.
- Intubation Sets:Endotracheal tubes with inflatable cuffs and stylet-guided insertion systems serve emergency airway management.
- BiPAP Devices:Bilevel positive airway pressure systems with spontaneous/timed modes support non-invasive ventilation for hypercapnic respiratory failure.
Oxygen concentrators command the established base. The steepest expansion runs through portable concentrator variants.
End User:
Cost tier stratification separates capital-intensive hospital installations from subscription-model homecare deployments, with emergency medical services and rehabilitation centers occupying intermediate procurement positions.
- Homecare Patients:Ambulatory oxygen users with active lifestyle requirements drive demand for FAA-cleared portable concentrators under five pounds. Direct-to-patient subscription models in United States metropolitan markets bypass traditional durable medical equipment distributors. Pulse-dose oxygen conservation technology extends battery duration for nocturnal and daytime mobility use cases.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate vendor panels to three preferred suppliers per region, unbundling after-sales service contracts from capital equipment purchases. Fixed bedside concentrators retain higher per-unit margins despite slower volume growth. Electronic control architectures with integrated sensor ecosystems win procurement evaluations over pneumatic legacy platforms.
- Emergency Medical Services:Pre-hospital oxygen delivery requires ruggedized portable systems with rapid deployment protocols.
- Rehabilitation Centers:Transitional care facilities bridge acute hospital discharge and permanent homecare placement.
Hospitals command the established base. The steepest expansion runs through homecare patient channels.
Technology:
Volume concentration favors electronic control platforms displacing pneumatic systems, while magnetic technology applications remain concentrated in premium device tiers with proprietary valve architectures.
- Portable Devices:Miniaturized pressure swing adsorption with lithium-ion power systems enables patient mobility without cylinder refills. FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape development cycles for dual-territory distribution. Weight reductions below five pounds are decomposing the traditional hospital-centric market into discrete ambulatory use cases.
- Fixed Devices:Stationary concentrators with continuous flow delivery serve nocturnal hypoxemia patients and institutional settings. Higher per-unit margins persist in hospital contracting despite slower replacement cycles. Energy efficiency specifications under EPA standards influence power consumption design targets in United States markets.
- Magnetic Technology:Proprietary valve control systems enable precise oxygen pulse dosing.
- Electronic Technology:Sensor-integrated feedback architectures support closed-loop oxygen titration.
Fixed devices command the established base. The steepest expansion runs through portable device platforms.
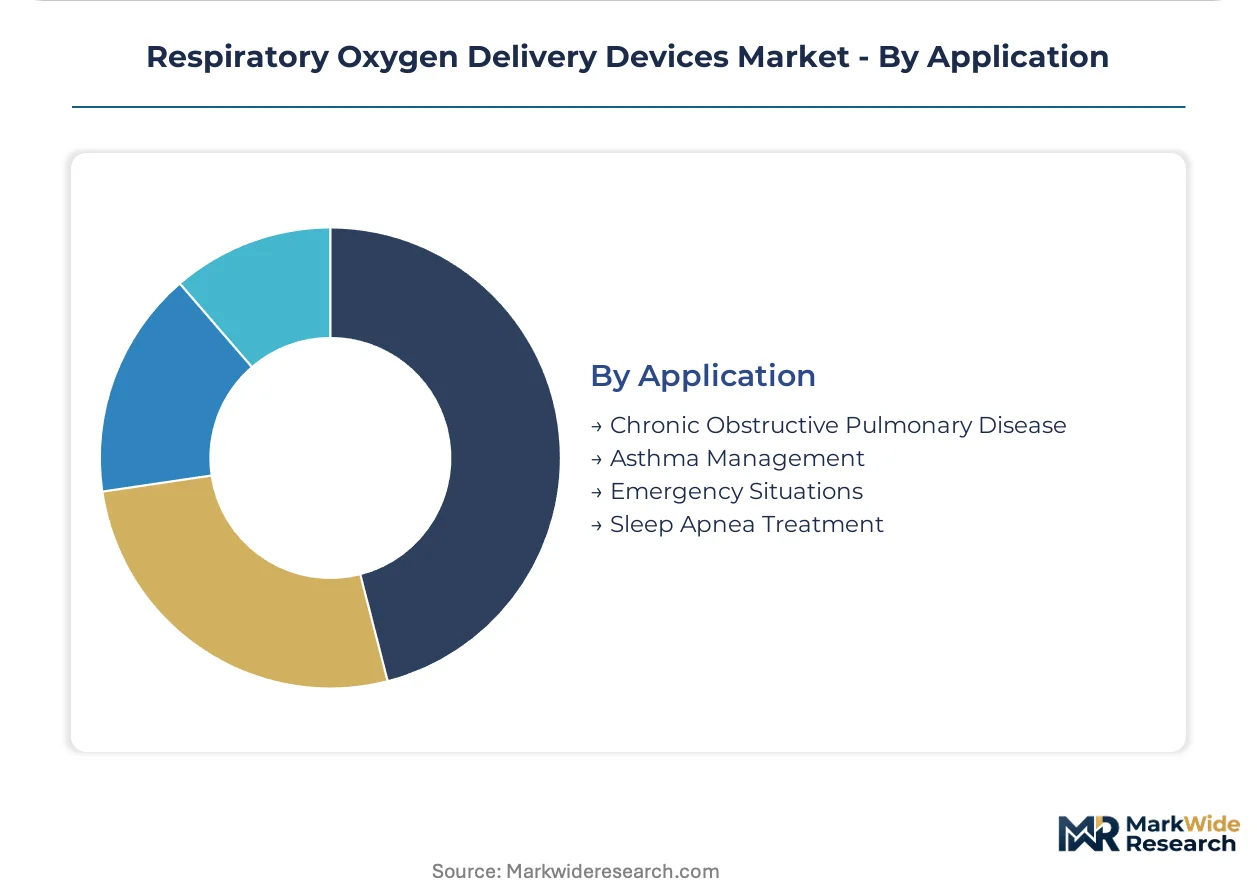
Application:
Customer type differentiation separates chronic disease management reimbursement pathways from acute emergency response procurement, with sleep apnea treatment occupying a distinct payor authorization channel.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy for hypoxemic patients with FEV1 below 50% predicted drives concentrator prescription volumes. Japan's super-aged society creates white space for simplified user interfaces targeting the seventy-five-plus demographic under METI home medical device incentives. Wearable oxygen monitoring convergence enables closed-loop titration for nocturnal hypoxemia.
- Asthma Management:Nebulized bronchodilator delivery for acute exacerbations and maintenance therapy concentrates demand in pediatric and geriatric populations. Germany's hospital consolidation standardizes respiratory device procurement across integrated networks in North Rhine-Westphalia.
- Emergency Situations:High-flow oxygen delivery for trauma, cardiac arrest, and anaphylaxis requires rapid-deployment portable systems.
- Sleep Apnea Treatment:Continuous and bilevel positive airway pressure systems address obstructive and central sleep-disordered breathing.
Chronic obstructive pulmonary disease command the established base. The steepest expansion runs through sleep apnea treatment applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution role for respiratory equipment, while the Los Angeles-Long Beach port complex anchors Pacific Rim supply chains for concentrator components.
United States
CMS reimbursement expansion for home oxygen therapy pulls chronic obstructive pulmonary disease patients into ambulatory care models. FDA 510(k) clearance pathways shape product development cycles for dual-territory distribution. Texas and Florida integrated delivery networks consolidate vendor panels to three preferred suppliers per region, unbundling after-sales service contracts from capital equipment purchases.
Germany
Hospital consolidation across Bavaria and North Rhine-Westphalia standardizes respiratory device procurement through single-vendor portfolio contracts. EU MDR technical documentation requirements extend conformity assessment timelines for Class IIa oxygen concentrators. The Eindhoven-Düsseldorf medical technology corridor concentrates manufacturing and R&D for pressure swing adsorption systems.
Japan
METI incentives for home medical device deployment target the seventy-five-plus demographic with simplified user interfaces. PMDA regulatory frameworks govern concentrator safety and performance validation. The Kansai region around Osaka anchors domestic manufacturing for portable oxygen systems serving the super-aged society.
China
NMPA medical device registration requirements condition market access for imported concentrator platforms. The Yangtze River Delta manufacturing belt concentrates lithium-ion battery cell production for portable device power systems. Shanghai's port infrastructure handles component imports for domestic assembly of electronic control architectures.
Respiratory Oxygen Delivery Devices Market Competitive Landscape
Listed leaders compete with private specialists across certification and reimbursement pathways, producing a tiered structure where scale-driven portfolios intersect with focused technology platforms. The vendor base clusters around three strategic archetypes: diversified healthcare conglomerates with integrated respiratory divisions, dedicated respiratory device specialists with concentrated R&D pipelines, and component-focused suppliers with proprietary valve or sensor architectures. Dominant competitive moves include geographic expansion through distributor acquisitions and technology licensing agreements for pulse-dose oxygen conservation systems.
Within the diversified healthcare tier, Koninklijke Philips N.V. and Drägerwerk AG & Co. KGaA exemplify portfolio breadth across anesthesia, ventilation, and oxygen delivery adjacencies. Fisher & Paykel Healthcare Limited occupies a position among specialists leveraging differentiated technology platforms. Inogen, Inc. represents the portable concentrator segment's focused player archetype. ResMed Inc. anchors the sleep-disordered breathing interface with respiratory care extensions.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| Drägerwerk AG & Co. KGaA |
| Fisher & Paykel Healthcare Limited |
| Smiths Group PLC |
| Invacare Corporation |
| Inogen, Inc. |
| ResMed Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for molecular sieve beds concentrate pricing power among concentrator manufacturers with captive supply agreements in East Asian manufacturing corridors. This lead-time structure rewards integrated players who internalize sieve bed production while forcing price concessions from assemblers dependent on spot-market procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales service bundling. FDA 510(k) cleared devices with ISO 80601-2-69 validation command substantial premiums over CE-marked equivalents, while homecare subscription models in United States metropolitan markets compress upfront hardware margins. Pricing pressure stems from Medicare Advantage cost-containment mandates in Texas and Florida, where integrated delivery networks unbundle service contracts. Hospital procurement committees demonstrate lowest price sensitivity due to capital budget insulation, whereas direct-to-patient channels face acute margin compression.
Supply Chain Analysis
Inventory concentration for lithium-ion battery cells centers on the Yangtze River Delta, South Korean cathode production corridors, and Japanese electrolyte specialists. Sieve bed molecular filtration media draws from specialized zeolite mining operations in the United States and China, while electronic control architectures source from Taiwanese semiconductor foundries. Single-source vulnerability runs through East Asian battery cell suppliers exposed to raw material allocation volatility. Distribution runs through durable medical equipment distributors in institutional channels and direct-to-patient logistics platforms in homecare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as closed-loop oxygen titration systems integrate pulse oximetry feedback with concentrator valve control, collapsing the boundary between device and digital therapeutic.
For Market Incumbents: Consolidate hospital contracting relationships through single-vendor respiratory portfolio bundling that spans oxygen concentrators, nebulizers, and humidification systems. Deepen backward integration into sieve bed manufacturing to secure supply continuity against East Asian raw material volatility. Prioritize firmware development resources for FHIR-compliant EMR integration that satisfies remote patient monitoring requirements from United States integrated delivery networks. For New Entrants and Emerging Players: Differentiate on simplified user interface design targeting Japan's seventy-five-plus demographic under METI home medical device deployment incentives. Penetrate the sleep apnea treatment application segment where reimbursement authorization channels remain less consolidated than chronic obstructive pulmonary disease pathways. Pursue direct-to-patient subscription models in United States metropolitan markets that bypass established durable medical equipment distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because ambulatory oxygen therapy is becoming embedded in payor cost-containment strategies for aging populations. Target acquisition profiles should emphasize portable concentrator specialists with proprietary pulse-dose valve architectures and FAA clearance for in-flight use. The signal to watch is CMS national coverage determination revisions that expand or contract home oxygen therapy eligibility thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market access for portable concentrator platforms against EU MDR delays. |
| Hospital System Partnership | Locks in preferred supplier status within Texas and Florida integrated delivery network consolidations. |
| Software Companion Development | Enables closed-loop oxygen titration through pulse oximetry integration for nocturnal hypoxemia patients. |
| Reimbursement Strategy | Aligns device specifications with CMS national coverage determination thresholds for home oxygen therapy. |
| CE Marking Pathway | Navigates EU MDR technical documentation requirements for Class IIa oxygen concentrator market entry. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, homecare durable medical equipment distributors, and concentrator manufacturing operations executives. Secondary validation drew from FDA 510(k) clearance databases, CMS national coverage determination records, EU MDR notified body documentation, and hospital procurement database aggregations. Bottom-up unit demand modeling triangulated against top-down reimbursement expenditure analysis across the analysis window.
Across the projection horizon, volume and value outputs reflect segmentation by product type, end user, technology platform, and application, with additional granularity for portable versus fixed device architectures. CAGRs were derived from fitted growth curves applied to patient eligibility volumes conditioned by reimbursement framework evolution. Industry-specific forecast inputs incorporated lithium-ion battery cost trajectories and pressure swing adsorption miniaturization learning curves.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or unanticipated EU MDR timeline compression would require recalibration. Forecasts reflect documented assumptions regarding patient adherence rates and payor authorization efficiency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Global Keratometers Market
Medical Devices
Venturi Mask Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
US Clear Aligners Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Europe Implantable Medical Devices Market