
 Enriched Flour Market | 2026-2036
Enriched Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Enriched Flour Market Analysis
Multi-source sourcing for micronutrient premixes is decoupling from traditional single-supplier dependencies among major millers. Cargill leverages its integrated grain handling and premix blending infrastructure to secure cost advantages across North American and Asian markets. Associated British Foods sustains competitive positioning through specialized bakery-sector formulations that command premium placement in European retail channels. General Mills anchors its enriched flour portfolio through direct relationships with quick-service restaurant chains requiring consistent protein-fortified specifications.
Enriched flour denotes cereal flour—predominantly wheat, corn, rice, or multigrain blends—to which iron, B vitamins, folic acid, and other micronutrients are restored or added post-milling to match or exceed natural whole-grain nutritional profiles, typically achieving 20-100% daily value claims per serving depending on regional fortification mandates. The primary commercial purpose centers on delivering standardized nutritional density for industrial baking, institutional foodservice, and retail consumer applications where dietary consistency and shelf stability are critical. Wheat flour occupies the dominant volume position given its entrenched role in bread and noodle manufacturing, while rice flour represents the fastest-expanding category as gluten-free and clean-label formulations displace conventional wheat alternatives in snack and specialty baking segments. Application-driven margin pools concentrate in food processing units, where bulk procurement contracts and custom micronutrient specifications generate higher per-ton value than commodity household channels.
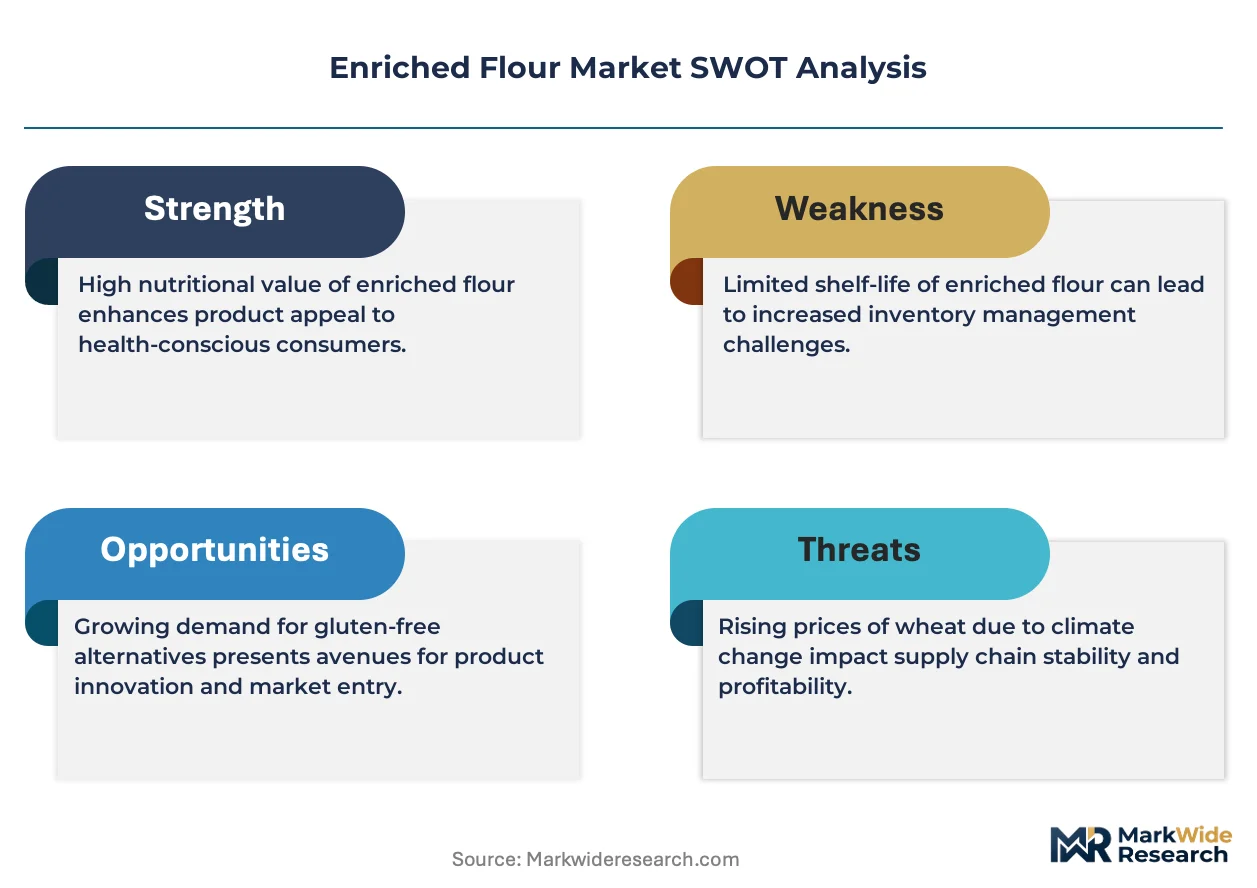
The FDA governs enriched flour labeling and fortification thresholds under standardized identity regulations, while the USDA administers school nutrition programs that create institutional demand for iron-fortified wheat products. India's FSSAI mandates wheat flour fortification in select states, compressing time-to-market for premix suppliers and domestic millers alike. Stakeholders must monitor evolving micronutrient specification shifts across multiple regulatory jurisdictions to align R&D pipelines with compliance-driven procurement criteria.
Market Dynamics
Government-mandated fortification programs are compressing time-to-market for premix suppliers while simultaneously fragmenting procurement patterns across industrial bakeries and institutional foodservice channels.
Growth Catalysts
- FSSAI wheat fortification mandates:India's phased state-level implementation creates guaranteed offtake volumes for domestic millers and premix blenders operating under compressed compliance timelines.
- Iron-deficiency reduction frameworks:WHO-backed micronutrient protocols are institutionalizing procurement specifications for iron-fortified wheat flour across school nutrition programs in multiple jurisdictions.
- Clean-label snack manufacturing:Rice flour formulations are displacing conventional wheat alternatives in gluten-free baking applications, expanding addressable premix categories beyond traditional cereal bases.
Market Restraints
- Micronutrient premix cost volatility:Synthetic folic acid and iron compound prices fluctuate with pharmaceutical-grade chemical feedstock markets, compressing margin predictability for mid-scale millers.
- Single-source supply concentration:Three premix suppliers control the majority of North American vitamin B complex formulations, creating vulnerability to force majeure disruptions in blending facilities.
- Whole-grain substitution preference:Consumer segments prioritizing minimally processed alternatives are redirecting bakery procurement toward stone-ground unenriched flour in premium retail channels.
Strategic Opportunities
- Sub-Saharan Africa institutional procurement:UN World Food Programme tender volumes for fortified wheat products are expanding procurement windows for premix suppliers with halal certification capabilities.
- Precision fermentation micronutrients:Bioengineered vitamin K2 and B12 strains are converging with traditional chemical synthesis, enabling clean-label fortification claims previously unattainable in mass-market flour.
- Direct-to-bakery premix distribution:E-procurement platforms are disintermediating traditional distributor relationships, allowing regional millers to access customized micronutrient specifications without volume minimums.
Industry Challenges
- Multijurisdictional compliance synchronization:Millers supplying cross-border industrial bakeries must reconcile divergent folic acid thresholds between FDA standardized identity regulations and EFSA maximum level determinations.
- Legacy mill equipment retrofit requirements:Continuous blending systems for homogeneous micronutrient distribution demand capital expenditure beyond depreciation cycles at family-owned milling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enriched Flour Market |
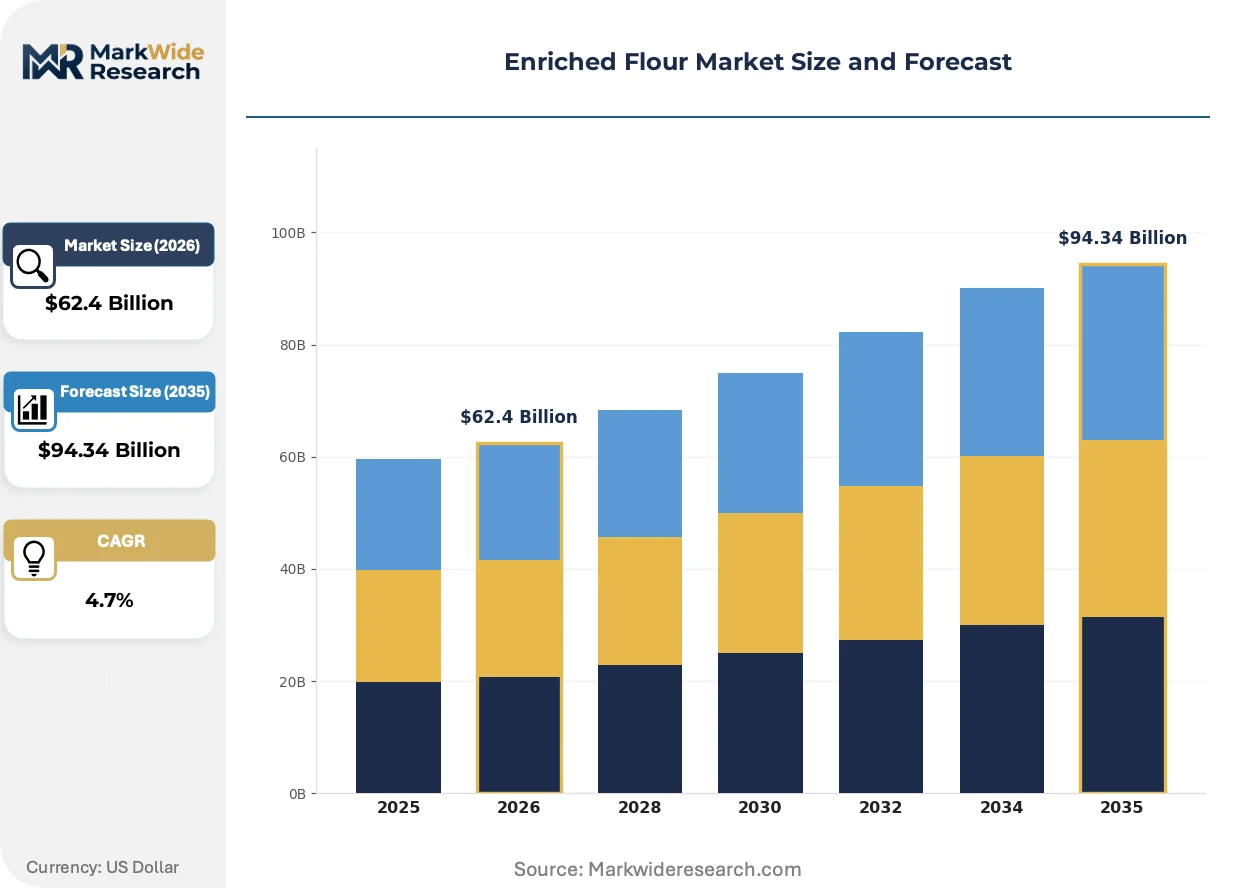
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $94.34 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Corn Flour, Rice Flour, Multigrain Flour Application: Baking, Cooking, Noodles, Snacks End User: Household, Food Processing Units, Restaurants, Bakeries Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores |
| Companies Covered | Bunge Limited, Ingredion Incorporated, Cargill, SunOpta, The Hain Celestial Group, Archer Daniels Midland, Associated British Foods, Limagrain, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enriched Flour Market Emerging Trajectories
Active restructuring of fortification technology stacks and procurement specifications is compressing product development cycles while elevating technical barriers to category participation.
Microencapsulation technology for heat-stable vitamin preservation is integrating into industrial-scale premix production lines. North American commercial bakeries are retrofitting continuous mixing systems to accommodate these advanced micronutrient delivery formats. This integration is enabling extended bake-temperature windows without nutrient degradation, compressing formulation constraints that previously limited protein-fortified bread applications.
REACH authorization requirements for novel food-contact substances are expanding toxicological documentation burdens for European premix suppliers introducing modified starch carriers. Industrial millers in Germany and France are consolidating supplier relationships to minimize regulatory exposure. Specialty bakery segments are responding by shifting procurement toward established vitamin forms with full safety dossiers rather than experimental encapsulation materials.
Consolidated procurement through quick-service restaurant chains is compressing supplier qualification timelines for enriched flour specifications. These centralized buying organizations are displacing fragmented distributor networks with direct miller relationships backed by third-party audit requirements. The operational strain is most visible in Southeast Asian markets where regional bakery conglomerates are vertically integrating into captive flour milling to secure specification control.
Enriched Flour Market Segmentation
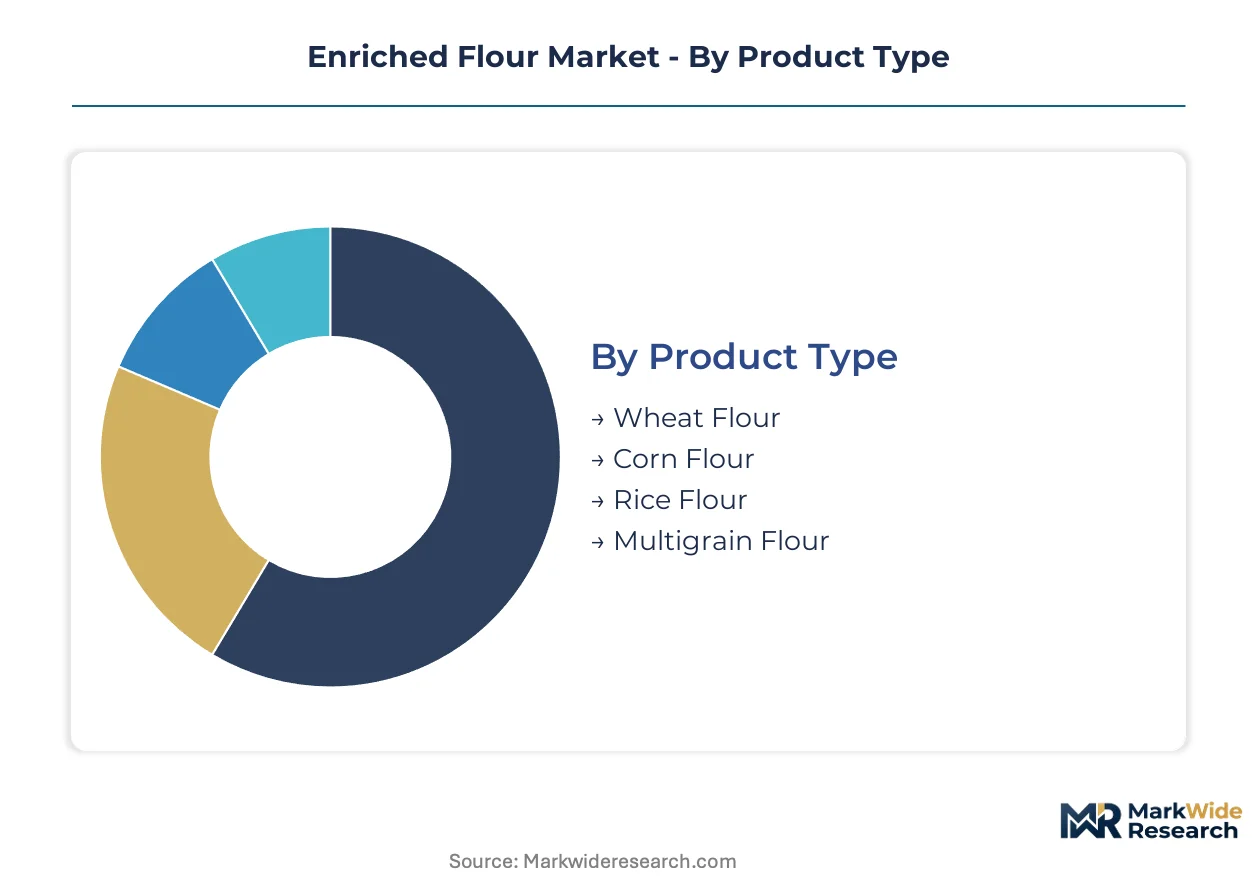
Segmentation in enriched flour markets exposes divergent compliance burdens across product categories. Certification requirements for micronutrient premixes and fortification standards fragment procurement specifications by end-use channel.
Product Type:
Wheat flour carries FDA standardized identity regulations and EFSA maximum level determinations for folic acid fortification. Rice flour faces divergent gluten-free certification protocols across importing jurisdictions.
- Wheat Flour:Dominant volume position derived from entrenched bread and noodle manufacturing specifications. Demand concentrates in Indian government-mandated fortification programs and North American quick-service restaurant chain procurement.
- Rice Flour:Fastest-expanding category displacing wheat alternatives in gluten-free snack formulations. Clean-label bakery applications in European retail channels are accelerating premix specification shifts toward this base.
- Corn Flour:Tortilla and masa production in US Southwest and Mexican industrial baking drives fortified procurement volumes.
- Multigrain Flour:Premium positioning requires composite micronutrient dossiers under REACH authorization for novel blend carriers.
Leading the category by volume: Wheat Flour. Growing fastest: Rice Flour.
Application:
Cost tiers separate commodity baking from precision snack manufacturing. Industrial scale determines premix blending infrastructure investment requirements.
- Baking:Commercial bakeries retrofit continuous mixing systems for heat-stable vitamin preservation. North American industrial facilities are integrating microencapsulation technology to extend bake-temperature windows.
- Snacks:Rice flour formulations in gluten-free extruded products command premium premix specifications. Southeast Asian bakery conglomerates are securing captive flour milling for specification control in this segment.
- Cooking:Institutional foodservice procurement for thickened sauces and coatings operates under compressed USDA school nutrition program compliance timelines.
- Noodles:Asian industrial manufacturers require iron-fortified wheat flour meeting WHO-backed micronutrient protocols for institutional offtake.
Highest margin pool: Snacks. Largest procurement volume: Baking.
End User:
Customer type dictates specification stringency and supplier qualification depth. Direct relationships displace distributor networks at scale thresholds.
- Food Processing Units:Bulk procurement contracts generate higher per-ton value than commodity channels. Custom micronutrient specifications and third-party audit requirements compress supplier qualification timelines.
- Bakeries:Quick-service restaurant chain consolidation demands consistent protein-fortified flour specifications. Direct miller relationships are displacing fragmented distributor networks.
- Household:Retail consumer applications prioritize shelf stability and standardized nutritional density claims.
- Restaurants:Foodservice operators procure through wholesalers with volume minimums limiting access to customized specifications.
Primary value concentration: Food Processing Units. Fastest procurement pattern shift: Bakeries.
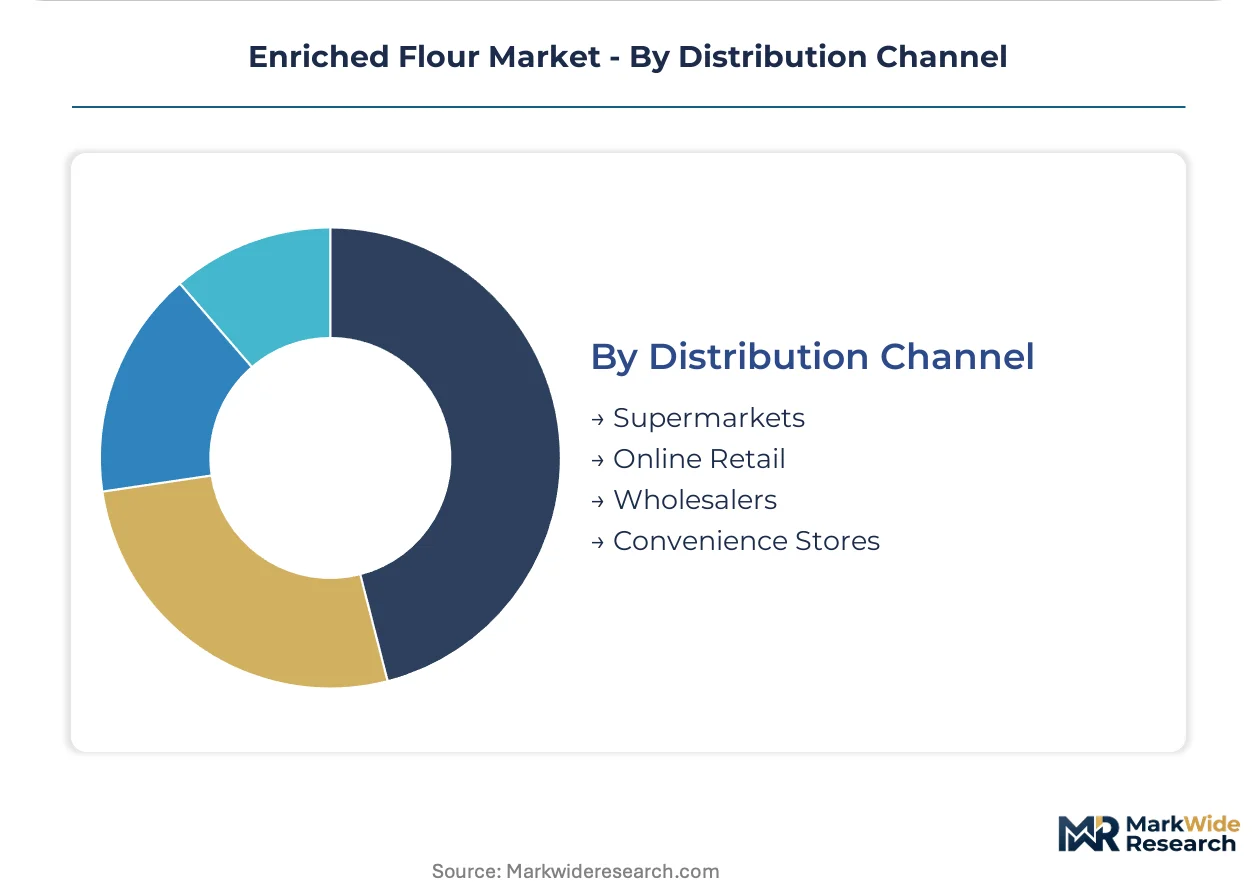
Distribution Channel:
Channel configuration determines geographic reach and compliance documentation accessibility. E-procurement platforms are restructuring traditional relationships.
- Supermarkets:Organized retail expansion in India accelerates category uptake through government-mandated wheat fortification program visibility. Premium placement commands specialized bakery-sector formulations.
- Online Retail:E-procurement platforms disintermediate traditional distributor relationships. Regional millers access customized micronutrient specifications without volume minimums.
- Wholesalers:Institutional foodservice and restaurant supply chains depend on consolidated procurement for iron-fortified product consistency.
- Convenience Stores:Limited SKU breadth restricts fortified flour offerings to standardized identity products with broad regulatory acceptance.
Deepest market penetration: Supermarkets. Steepest expansion trajectory: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat belt concentration across the North American Great Plains, the Indo-Gangetic plain, and the European breadbasket anchors enriched flour production capacity. Regulatory divergence between FDA standardized identity thresholds and EFSA maximum level determinations fragments formulation compliance across export destinations. Urban bakery cluster expansion in emerging economies is redirecting regional trade flows toward premix-intensive industrial channels.
United States
Commercial bakery procurement from quick-service restaurant chains compresses supplier qualification timelines for iron-fortified specifications. FDA standardized identity regulations govern folic acid fortification thresholds while USDA school nutrition programs institutionalize demand. Chicago and Minneapolis-St. Paul milling corridors concentrate continuous blending infrastructure for heat-stable vitamin preservation.
India
Government-mandated wheat fortification programs under FSSAI directives create guaranteed offtake volumes for domestic millers and premix blenders. Phased state-level implementation compresses compliance timelines across organized retail expansion zones. Mumbai and Delhi-NCR industrial bakery clusters accelerate category uptake through fortified flour procurement for institutional foodservice.
Germany
REACH authorization requirements for novel food-contact substances expand toxicological documentation burdens for premix suppliers introducing modified starch carriers. Industrial millers consolidate supplier relationships to minimize regulatory exposure. Bavaria and North Rhine-Westphalia baking conglomerates shift procurement toward established vitamin forms with full safety dossiers.
Brazil
Wheat import dependency concentrates milling capacity in coastal port zones with integrated premix blending infrastructure. ANVISA fortification standards align with WHO-backed micronutrient protocols for institutional procurement. São Paulo state industrial bakery networks drive demand for standardized nutritional density in bread and noodle manufacturing.
China
Dual carbon goals and GB standards for food fortification reshape micronutrient premix sourcing strategies among state-linked grain processors. NMPA oversight of novel food additives influences encapsulation technology adoption. Yangtze River Delta milling clusters retrofit equipment for homogeneous micronutrient distribution in bulk industrial contracts.
Enriched Flour Market Vendor Landscape
Capacity expansion dominates the current landscape as major millers retrofit continuous blending systems for microencapsulation technology integration. The vendor base separates into three tiers: integrated grain-handling conglomerates with captive premix infrastructure, specialized bakery-sector formulators commanding premium placement, and regional millers accessing customized specifications through e-procurement disintermediation. Strategic archetypes include backward integration into captive flour milling, upstream control over micronutrient premix supply, and in-house production of heat-stable vitamin delivery formats. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants reconcile multijurisdictional compliance requirements.
Within the integrated infrastructure tier, Cargill leverages its grain handling and premix blending footprint across North American and Asian markets. Associated British Foods occupies a position exemplifying specialized bakery-sector formulations that command premium placement in European retail channels. General Mills anchors the quick-service restaurant supply vector through direct relationships requiring consistent protein-fortified specifications. These three entities represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Bunge Limited |
| Ingredion Incorporated |
| Cargill |
| SunOpta |
| The Hain Celestial Group |
| Archer Daniels Midland |
| Associated British Foods |
| Limagrain |
| General Mills |
| Others |
Supply Flow & Price Mechanics
India's FSSAI wheat fortification mandates gate qualified supply and premium-tier pricing access for domestic millers and international premix suppliers seeking entry into government procurement channels. Compliance certification costs and continuous blending infrastructure investments stratify participants into price tiers that reflect technical capability rather than commodity grain sourcing alone.
Pricing Analysis
Warranty-backed micronutrient stability guarantees separate bundled service contracts from unbundled commodity transactions in industrial bakery procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FSSAI-mandated fortification commanding mid-tier positioning and REACH-authorized novel carriers extracting top-tier premiums. Cost compression in economy-grade unenriched flour intensifies because of whole-grain substitution trends in retail channels. Quick-service restaurant chains exhibit lowest price sensitivity due to specification rigidity, while regional bakeries operate at highest sensitivity given volume minimum constraints.
Supply Chain Analysis
Reverse-logistics flows for expired premix batches and recalled fortified products remain underdeveloped, creating working capital drag for distributors managing temperature-sensitive vitamin inventories. Supply concentrates in the United States, India, and Germany, with wheat belt proximity dictating milling infrastructure placement. Synthetic folic acid and iron compound feedstocks draw from pharmaceutical-grade chemical markets in China and India. Single-source vulnerability pervades North American vitamin B complex formulations. Distribution runs through consolidated quick-service restaurant procurement and e-procurement platforms disintermediating traditional wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from multijurisdictional compliance synchronization costs will force weaker regional millers toward acquisition or exit over the coming decade.
For Market Incumbents: Acquire continuous blending infrastructure and microencapsulation technology capabilities to defend against precision fermentation entrants disrupting traditional chemical synthesis premix supply. Backward integration into captive vitamin B complex formulation hedges single-source concentration risk. Investment in FSSAI and REACH parallel certification pipelines preserves cross-border industrial bakery contracts. For New Entrants and Emerging Players: Begin with direct-to-bakery e-procurement platforms targeting mid-scale regional millers excluded from volume-minimum distributor relationships. Sub-Saharan Africa institutional procurement through UN World Food Programme tenders offers most penetrable geographic white space. Halal certification capabilities unlock tender eligibility barriers incumbent suppliers have neglected. For Investors and Strategic Acquirers: FDA updated folic acid guidance publication is the leading indicator that regulatory divergence between jurisdictions will intensify acquisition premiums for multi-certified premix suppliers. Five-to-ten-year viability favors integrated grain-handling conglomerates with captive blending infrastructure over standalone millers. Monitor EFSA maximum level determination revisions for early signals of European formulation standard shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Blending | Cargill's integrated infrastructure secures cost advantages across North American and Asian procurement. |
| Microencapsulation Technology Adoption | Heat-stable vitamin preservation extends bake-temperature windows for protein-fortified bread applications. |
| Halal Certification Investment | UN World Food Programme tender eligibility expands addressable institutional procurement volumes. |
| E-Procurement Platform Development | Regional millers access customized specifications without volume minimums through disintermediated channels. |
| Parallel Regulatory Certification Pipeline | Simultaneous FDA and FSSAI compliance preserves cross-border quick-service restaurant chain contracts. |
Methodological Framework
Independent corroboration across primary interviews with mill operations directors, premix procurement managers, bakery R&D formulators, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from FDA standardized identity regulations, FSSAI fortification directives, EFSA maximum level determinations, WHO micronutrient protocols, and industrial bakery trade association technical standards. Bottom-up volume modeling from state-level fortification program implementation timelines triangulates against top-down market sizing from grain processing capacity data.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in enriched flour procurement. Segmentation dimensions modeled include product type, application channel, end-user category, and geographic regulatory cluster. CAGRs derive from regression analysis against fortification mandate implementation schedules and industrial bakery capacity expansion pipelines. Wheat import dependency ratios and premix blending infrastructure investment cycles inform forecast sensitivity bounds.
Underlying measurement precision varies by segment; government-mandated fortification program volumes carry tighter precision than discretionary premium bakery procurement. Forecasts reflect assumptions about FSSAI phased implementation adherence and REACH authorization timelines for novel encapsulation materials. Practitioners should monitor EFSA folic acid threshold revisions and precision fermentation vitamin K2 commercialization milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Global Vitamins Market