
 Fortified Food Market | 2026-2036
Fortified Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Food Market Analysis
Grain milling cooperatives in the North American Midwest is recalibrating output schedules to align with micronutrient premix demand from cereal manufacturers. Nestlé S.A. leverages its pediatric nutrition research infrastructure to sustain formulation leadership in iron-fortified dairy. Cargill, Incorporated anchors its position through backward integration into vitamin A and D premix production. DSM Nutritional Products differentiates via its Quali-Vitamin platform, which controls bioavailability testing across multiple climatic zones.
Fortified food denotes edible products with added vitamins, minerals, fiber, or probiotics beyond natural occurrence, typically achieved through spray-drying, extrusion coating, or microencapsulation to preserve nutrient stability through processing and shelf life. The primary commercial purpose centers on closing documented micronutrient gaps in populations where dietary diversity remains insufficient. The vitamins segment leads absolute revenue due to its integration into mandatory national fortification programs for wheat flour and edible oils. Probiotics occupies the fastest-expanding margin pool, as live culture stability improvements enable shelf-stable application in beverage supplements. Meal replacements concentrate value capture among athletes and seniors, where protein-plus-micronutrient density commands premium positioning.
The FDA governs nutrient content claims and fortification limits under 21 CFR 101, while the USDA administers school feeding specifications that mandate iron and vitamin A thresholds. The EU EFSA evaluates health claim substantiation under the Nutrition and Health Claims Regulation, directly shaping which fortification narratives reach European consumers. India's FSSAI enforces mandatory fortification standards for rice, wheat flour, salt, and edible oil under its Food Safety and Standards (Fortification of Foods) Regulations. Stakeholders must monitor evolving bioequivalence requirements for novel delivery formats, as regulatory divergence between jurisdictions threatens to fragment formulation strategies and complicate cross-border product registration.
Market Dynamics
Government-mandated staple fortification programs are compressing procurement timelines for micronutrient premix suppliers while simultaneously fragmenting formulation requirements across national regulatory boundaries.
Growth Catalysts
- FSSAI Mandatory Standards:India's Food Safety and Standards (Fortification of Foods) Regulations compel wheat flour, rice, salt, and edible oil processors to source certified premixes, creating guaranteed offtake volumes for vitamin A and iron suppliers.
- Pediatric Nutrition Infrastructure:Institutional feeding programs in schools and healthcare facilities are expanding shelf-stable fortified dairy procurement specifications.
- Microencapsulation Advances:Spray-drying and extrusion coating technologies now preserve probiotic viability through thermal processing, unlocking beverage applications previously restricted to refrigerated channels.
Market Restraints
- Vitamin Premix Concentration:Three chemical conglomerates control over 80% of global vitamin A and D3 feedstock production, exposing downstream formulators to input volatility and allocation rationing during supply shocks.
- EFSA Substantiation Requirements:The EU Nutrition and Health Claims Regulation demands clinical trial evidence for micronutrient content claims, extending product development timelines and raising compliance costs for European market entry.
- Bioavailability Variability:Iron compounds exhibit absorption rate differentials of 15-35% depending on dietary matrix, forcing costly reformulation when switching between wheat flour and rice carriers.
Strategic Opportunities
- Senior Nutrition White Space:Japan's aging demographic and METI-promoted functional food category create demand for protein-plus-micronutrient meal replacements with texture-modified formats for dysphagia patients.
- Dual-Fortification Convergence:Combining zinc with iron in salt fortification programs addresses co-deficiency patterns documented by WHO, opening multi-nutrient premix contracts in Indonesia and Bangladesh.
- Direct-to-Institution Channels:Hospital and long-term care procurement cooperatives are consolidating supplier relationships, bypassing traditional retail distribution markups for therapeutic nutrition products.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of food science, micronutrient chemistry, and regulatory compliance requires specialized expertise that outpaces university program output in India and Southeast Asia.
- Climate-Stability Validation:Premix suppliers must conduct bioavailability testing across tropical, temperate, and arid storage conditions to satisfy divergent national registration requirements, multiplying R&D expenditure.
- Legacy Equipment Retrofit Costs:Grain mills and oil refineries require pneumatic injection system upgrades to achieve homogeneous micronutrient dispersion, with payback periods exceeding five years for smaller cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Food Market |
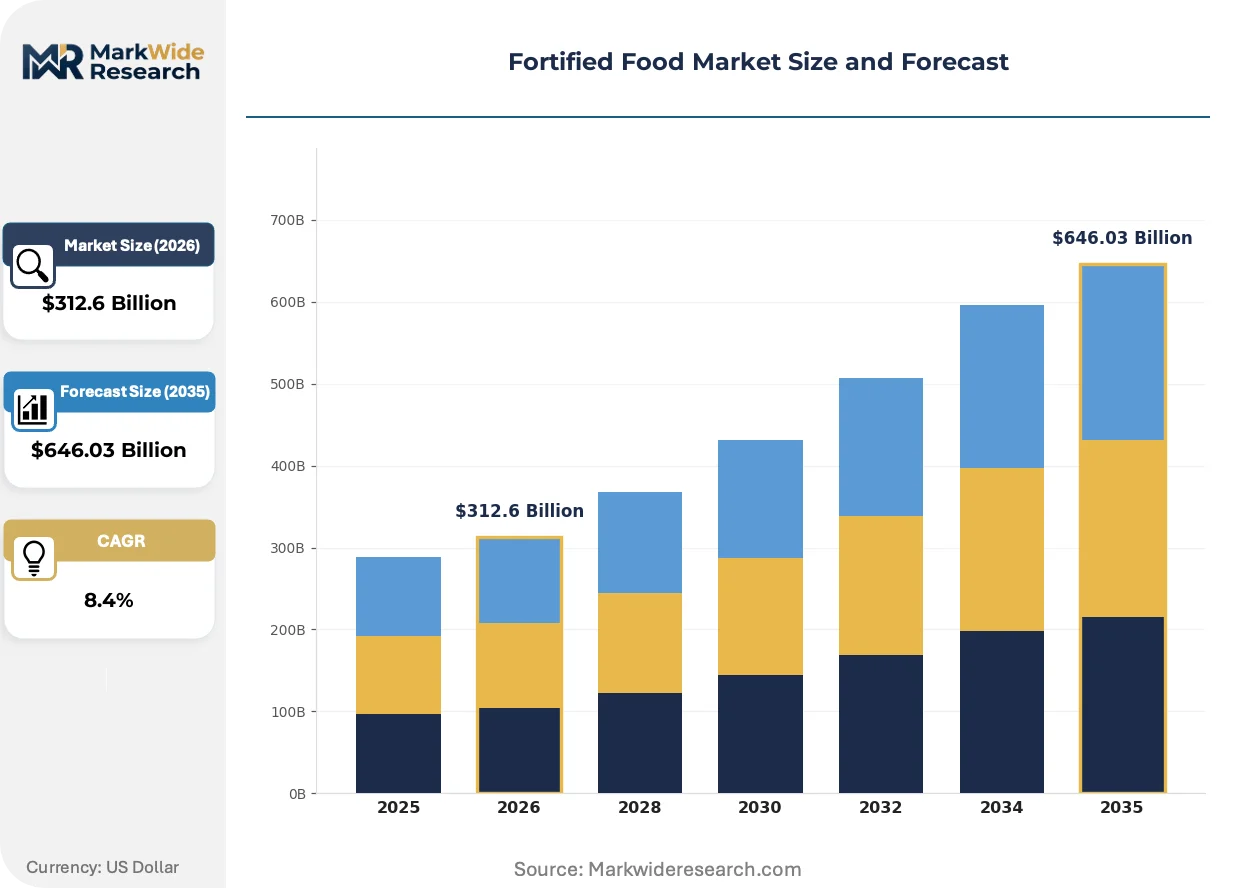
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Fiber, Probiotics End User: Children, Athletes, Seniors, Pregnant Women Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Application: Snack Foods, Dairy Products, Beverage Supplements, Meal Replacements |
| Companies Covered | Kellogg Company, Archer Daniels Midland, Nestlé S.A., DSM Nutritional Products, Cargill, Incorporated, Danone S.A., Unilever PLC, BASF SE, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Food Market Emerging Trajectories
Live culture stabilization technologies and precision fermentation are converging to redefine which nutrients can be delivered through shelf-stable formats, while regulatory divergence between major economies is fragmenting formulation strategies.
Microencapsulation via complex coacervation and lipid shell technologies is electrifying probiotic fortification by enabling 18-month ambient shelf stability previously unattainable with traditional freeze-dried cultures. Sports nutrition and senior meal replacement manufacturers are accelerating adoption of these heat-stable strains. This breakthrough is compressing the refrigerated cold chain infrastructure previously required for functional beverages, redirecting capital toward ambient distribution networks in tropical markets.
The EU EFSA's tightened evaluation of health claim substantiation under the Nutrition and Health Claims Regulation is forcing reformulation of European-positioned products toward clinically validated nutrient doses rather than marketing-driven sprinkle fortification. Manufacturers must now commission human intervention studies to support iron, folate, or vitamin D messaging. Dairy and cereal segments targeting health-conscious consumers are most affected, with several brands withdrawing marginal claims rather than absorbing trial costs.
Institutional procurement consolidation is reshaping supplier relationships as hospital group purchasing organizations and school feeding authorities centralize micronutrient premix sourcing under multi-year framework agreements. Direct contracting with premix manufacturers is displacing fragmented distributor networks in Brazil and Mexico. This pattern is most visible in pediatric nutrition programs, where state procurement agencies now mandate supplier qualification audits that exclude smaller regional blenders lacking ISO 22000 certification.
Fortified Food Market Segmentation
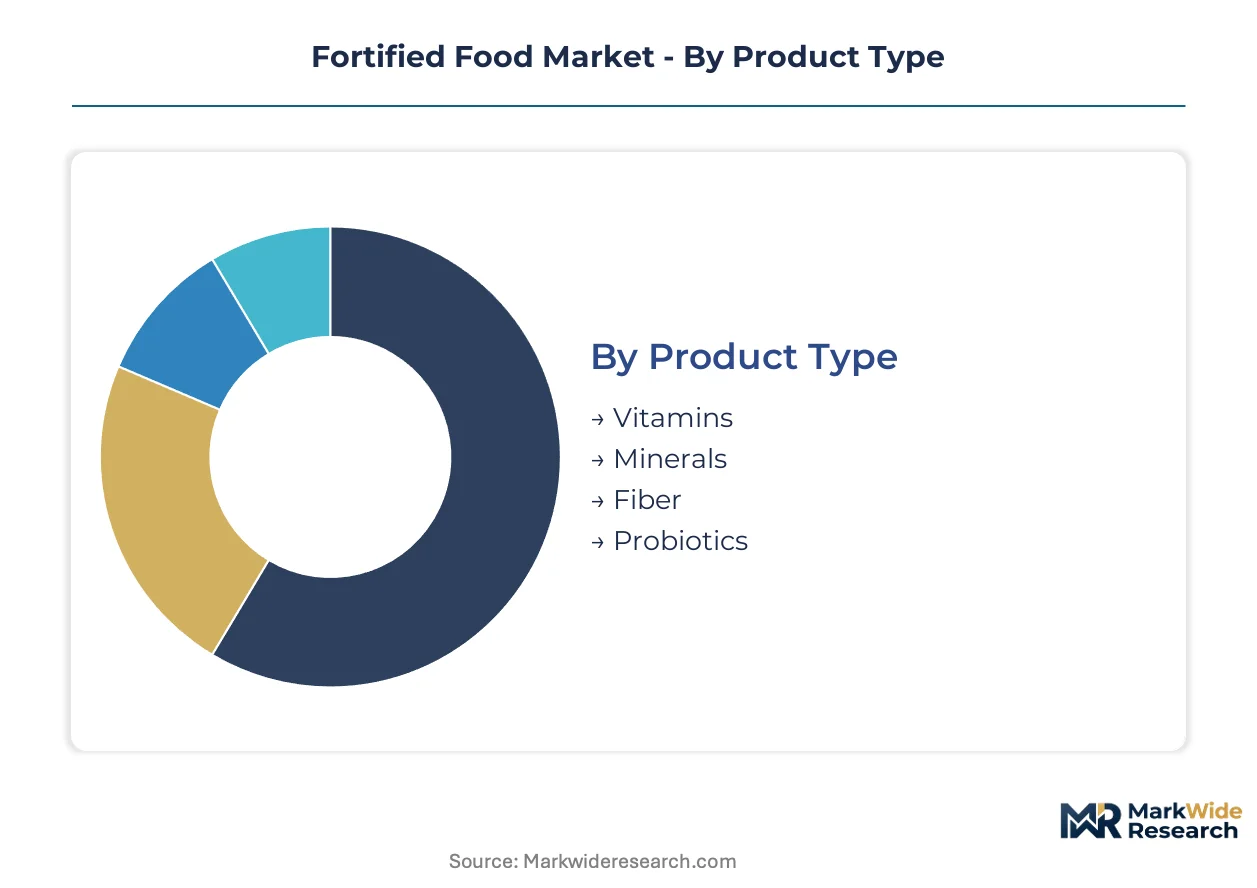
Fortified food segmentation reveals distinct nutrient delivery pathways, each governed by bioavailability requirements, regulatory thresholds, and end-user physiological needs. Understanding these divisions exposes where formulation complexity concentrates and where standardization enables scale.
Product Type:
Supply concentration for vitamin A and D3 feedstock shapes competitive dynamics across all nutrient categories, with three chemical conglomerates controlling upstream production.
- Vitamins:Water-soluble and fat-soluble compounds including A, D, E, K, B-complex, and C, typically stabilized through esterification or microencapsulation to withstand thermal processing. Mandatory national fortification programs for wheat flour and edible oils in India, Pakistan, and Nigeria generate guaranteed procurement volumes for premix suppliers.
- Probiotics:Live microbial cultures delivered through complex coacervation or lipid shell technologies that preserve viability through pasteurization and ambient storage. Sports nutrition and senior meal replacement manufacturers in Japan and Brazil are accelerating adoption of heat-stable strains for shelf-stable beverages.
- Minerals:Elemental compounds and chelated forms including iron, zinc, calcium, and iodine, with absorption rates varying 15-35% depending on dietary matrix and competing nutrient presence.
- Fiber:Soluble and insoluble fractions from cereal bran, resistant starch, or novel sources like chicory inulin, added for digestive health positioning in adult-targeted products.
Vitamins absorb the bulk of installed capacity; probiotics is expanding most quickly.
End User:
Physiological life-stage requirements drive divergent micronutrient dosing protocols, with institutional procurement consolidating around pediatric and geriatric specifications.
- Children:Iron, vitamin A, and zinc formulations addressing documented deficiency patterns in school-age populations. India's Mid-Day Meal Scheme and Brazil's National School Feeding Program mandate fortified dairy and grain procurement, creating dedicated supply channels.
- Seniors:Protein-plus-micronutrient density with texture-modified formats for dysphagia patients, responding to Japan's aging demographic and METI-promoted functional food category expansion.
- Pregnant Women:Folate, iron, and DHA combinations targeting neural tube defect prevention, with WHO guidelines influencing national supplementation policy in Bangladesh and Ethiopia.
- Athletes:Electrolyte, protein, and B-vitamin fortification in ready-to-drink formats, with demand concentrating in performance-oriented retail channels across Germany and Australia.
Children commands the largest institutional procurement volumes; seniors is climbing the fastest as aging demographics reshape foodservice specifications.
Distribution Channel:
Channel selection determines temperature control requirements, shelf-life specifications, and margin capture potential for fortified product portfolios.
- Supermarkets:Ambient and chilled fortified dairy, cereals, and oils in mass-market packaging, with shelf placement fees influencing visibility for emerging brands in Mexico and South Africa.
- Pharmacies:Clinical-grade formulations with substantiated health claims, requiring EFSA-compliant evidence dossiers for European positioning and FDA notification for US structure-function claims.
- Online Retail:Direct-to-consumer subscription models for personalized micronutrient stacks, bypassing traditional distributor markups but requiring cold-chain logistics for probiotic-containing products.
- Health Stores:Premium-positioned organic and non-GMO fortified options, with certification requirements from USDA Organic or EU Organic Regulation constraining formulation flexibility.
Supermarkets maintains the broadest geographic footprint; online retail is gaining share fastest through subscription retention models.
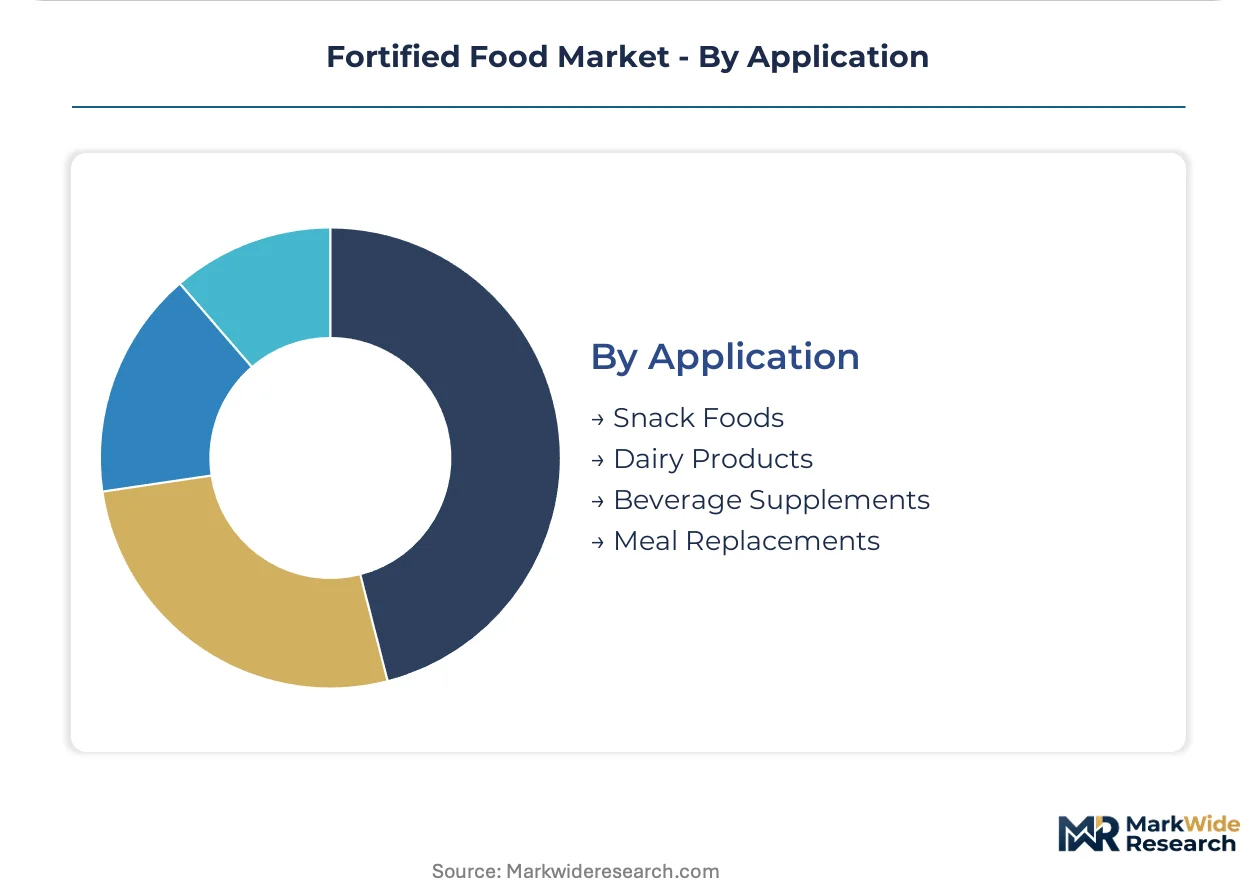
Application:
Processing technology compatibility dictates which nutrients survive manufacturing intact, with thermal stability thresholds segmenting formulation possibilities.
- Dairy Products:Fluid milk, yogurt, and cheese fortified with vitamins A and D through post-pasteurization injection or pre-mix homogenization. India's FSSAI mandates standardized fortification levels for edible oils and milk in targeted states.
- Meal Replacements:Complete nutrition powders and ready-to-drink formats combining protein, micronutrients, and fiber for medical nutrition and sports applications, with texture modification for dysphagia patients expanding clinical channel penetration.
- Beverage Supplements:Shelf-stable functional drinks leveraging microencapsulation advances for probiotic viability, displacing refrigerated distribution in tropical markets including Indonesia and Vietnam.
- Snack Foods:Extruded cereals, energy bars, and savory items with surface-applied or matrix-integrated nutrients, constrained by Maillard reaction interactions that degrade heat-sensitive vitamins during baking.
Dairy products retains the deepest regulatory integration; meal replacements is expanding most quickly through hospital and long-term care procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vitamin A and D3 feedstock production concentrates in China, Germany, and Switzerland, with downstream premix formulation dispersing to India, Brazil, and Indonesia where government fortification mandates drive procurement volumes.
India
FSSAI-mandated fortification of wheat flour, rice, salt, and edible oil generates guaranteed offtake for premix suppliers. The Mid-Day Meal Scheme and Integrated Child Development Services institutionalize pediatric nutrition procurement. Grain milling clusters in Punjab and Haryana retrofit pneumatic injection systems to achieve homogeneous micronutrient dispersion.
United States
USDA-administered school feeding specifications mandate iron and vitamin A thresholds in institutional dairy and grain procurement. FDA oversight of nutrient content claims under 21 CFR 101 constrains formulation flexibility for health-positioned products. Midwest grain cooperatives recalibrate output schedules to align with cereal manufacturer premix demand.
Brazil
The National School Feeding Program mandates fortified dairy and grain procurement for 40 million students, creating dedicated supply channels for pediatric nutrition formulators. ANVISA registration requirements for novel delivery formats extend product development timelines. São Paulo-based procurement cooperatives consolidate supplier relationships under multi-year framework agreements.
Germany
EFSA evaluation of health claim substantiation under the Nutrition and Health Claims Regulation forces reformulation toward clinically validated nutrient doses. Sports nutrition manufacturers in Bavaria accelerate adoption of heat-stable probiotic strains for ambient beverage applications. The country's chemical conglomerates control upstream vitamin A and D3 feedstock production.
Japan
METI-promoted functional food category expansion creates demand for protein-plus-micronutrient meal replacements with texture-modified formats for dysphagia patients. The aging demographic reshapes foodservice specifications toward senior nutrition products. Kanto region manufacturers lead microencapsulation technology deployment for live culture stabilization.
Fortified Food Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue probiotic stabilization and personalized micronutrient stacks. Three chemical conglomerates control over 80% of global vitamin A and D3 feedstock, exposing downstream formulators to input volatility. Strategic archetypes include backward-integrated premix manufacturers, research-driven pediatric nutrition specialists, and shelf-stable culture technology licensors. Competitive moves concentrate on multi-year institutional procurement contracts and climate-stability validation capabilities across tropical, temperate, and arid zones.
Within the research-driven tier, Nestlé S.A. and DSM Nutritional Products exemplify formulation leadership anchored by pediatric nutrition infrastructure and bioavailability testing platforms. Cargill, Incorporated occupies a position among backward-integrated suppliers controlling vitamin A and D premix production. These three entities represent distinct competitive vectors: proprietary research ecosystems, captive upstream supply, and multi-climatic validation protocols that shape procurement qualification standards for institutional feeding programs.
| Leading Market Players |
|---|
| Kellogg Company |
| Archer Daniels Midland |
| Nestlé S.A. |
| DSM Nutritional Products |
| Cargill, Incorporated |
| Danone S.A. |
| Unilever PLC |
| BASF SE |
| General Mills, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned premix specialists in India and Southeast Asia anchor regional supply networks while enforcing contract discipline through multi-year framework agreements with government procurement agencies. Their concentrated ownership structures enable rapid capital redeployment into pneumatic injection system upgrades, tightening price competition for smaller cooperatives lacking comparable balance sheet flexibility.
Pricing Analysis
Warranty-backed bioavailability certification now bundles with premium premix contracts, separating validated climate-stability documentation from unbundled commodity vitamin sourcing. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 certification status and geographic delivery radius. Pricing pressure stems from vitamin A and D3 feedstock allocation rationing during supply shocks, squeezing margin capture for non-backward-integrated formulators. Institutional procurement agencies exhibit lowest price sensitivity due to mandated compliance thresholds, while regional grain cooperatives face acute cost compression.
Supply Chain Analysis
Direct-to-institution channels handle consolidated hospital and school feeding procurement, displacing fragmented distributor networks in Brazil and Mexico. Upstream vitamin A and D3 synthesis concentrates in China, Germany, and Switzerland, while downstream premix formulation disperses to India, Indonesia, and Brazil where FSSAI and ANVISA mandates drive volume. Critical inputs include retinol acetate, cholecalciferol, and microencapsulation shell materials. Single-source vulnerability in vitamin feedstock exposes formulators to allocation rationing. Distribution runs through multi-year framework agreements with state procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin A and D3 feedstock concentration among three chemical conglomerates props pricing discipline, as downstream formulators lack alternative sourcing during allocation shocks.
For Market Incumbents: To counter emerging probiotic stabilization specialists, secure backward integration into vitamin premix production and expand climate-stability validation laboratories across tropical zones. Lock multi-year institutional procurement contracts before EFSA substantiation requirements harden qualification barriers. For New Entrants and Emerging Players: Heat-stable live culture technologies open white space in shelf-stable beverage applications for Indonesia and Vietnam, where refrigerated cold chain gaps constrain incumbent penetration. Target direct-to-institution channels in Brazil's National School Feeding Program, leveraging ANVISA registration timelines as competitive moat against established players. For Investors and Strategic Acquirers: Consolidation of hospital group purchasing organization contracts is the leading indicator that procurement leverage is shifting toward institutional buyers, compressing distributor margins. Position for 5-10 year horizon around microencapsulation technology licensors with validated tropical stability dossiers. Watch for FSSAI enforcement intensity in Indian states as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Premix Production | Cargill's captive supply of vitamins A and D insulates formulation margins from feedstock allocation shocks. |
| Climate-Stability Validation Laboratory Expansion | DSM's Quali-Vitamin platform controls bioavailability testing across tropical, temperate, and arid storage conditions. |
| Multi-Year Institutional Procurement Contracts | Brazil's ANVISA-registered suppliers secure dedicated offtake from the National School Feeding Program. |
| Heat-Stable Probiotic Strain Licensing | Japanese manufacturers deploy complex coacervation for 18-month ambient shelf stability in beverage applications. |
| Pneumatic Injection System Retrofit | Punjab grain milling clusters achieve homogeneous micronutrient dispersion for FSSAI-mandated wheat flour fortification. |
Methodological Framework
Multi-period observation of premix procurement volumes, EFSA health claim submission patterns, and FSSAI enforcement actions anchored the trend analysis, supplemented by interviews with premix formulation chemists, grain mill procurement managers, pediatric nutrition program directors, and ANVISA regulatory affairs specialists. Secondary validation drew from FSSAI fortification compliance reports, ANVISA novel food registration databases, EFSA health claim opinions, and WHO micronutrient deficiency surveillance data. Bottom-up premix volume estimates triangulated against top-down national fortification program budgets.
Input-output matrices modeled nutrient demand across vitamins, probiotics, minerals, and fiber segments, intersecting with dairy, meal replacement, beverage, and snack food applications over the projection horizon. Modeled dimensions included product type, end-user life stage, distribution channel temperature requirements, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and policy implementation timelines. Forecast inputs incorporated FSSAI mandate expansion schedules and EFSA substantiation cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under vitamin feedstock supply disruption or abrupt EFSA evidentiary requirement tightening. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Micronutrients Market