
 Global Central Nervous System (CNS) Stimulant Drugs Market | 2026-2036
Global Central Nervous System (CNS) Stimulant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Central Nervous System (CNS) Stimulant Drugs Market Foresight
Multi-source API procurement is consolidating across the CNS stimulant supply base as manufacturers seek to reduce dependency on single-region chemical synthesis. Novartis AG sustains one of the most vertically integrated production networks for methylphenidate derivatives, spanning active pharmaceutical ingredient synthesis through finished dose packaging. Jazz Pharmaceuticals Plc differentiates through its concentration on narcolepsy-focused formulations with specialized distribution to sleep disorder centers. Pfizer Inc. leverages its scale to control bulk amphetamine salt supplies for both branded and contract manufacturing channels.
Central nervous system stimulant drugs comprise a pharmacological class of psychoactive compounds that enhance dopaminergic and noradrenergic neurotransmission through reuptake inhibition or presynaptic release mechanisms, with potency measured by binding affinity at DAT and NET transporter sites and duration calibrated through esterification or osmotic-controlled release engineering. These agents serve primary commercial purposes in managing attention deficit hyperactivity disorder, narcolepsy, and refractory obesity where non-pharmacological interventions prove insufficient. Amphetamine-based therapies occupy the deepest margin pools due to manufacturing complexity and scheduling restrictions that limit generic substitution, while extended-release capsules represent the fastest-growing delivery mode as patient adherence programs and pediatric compliance protocols drive formulation preference. Modafinil for cognitive enhancement sits at the boundary of established therapy area expansion, with off-label prescribing patterns creating regulatory friction across multiple jurisdictions.
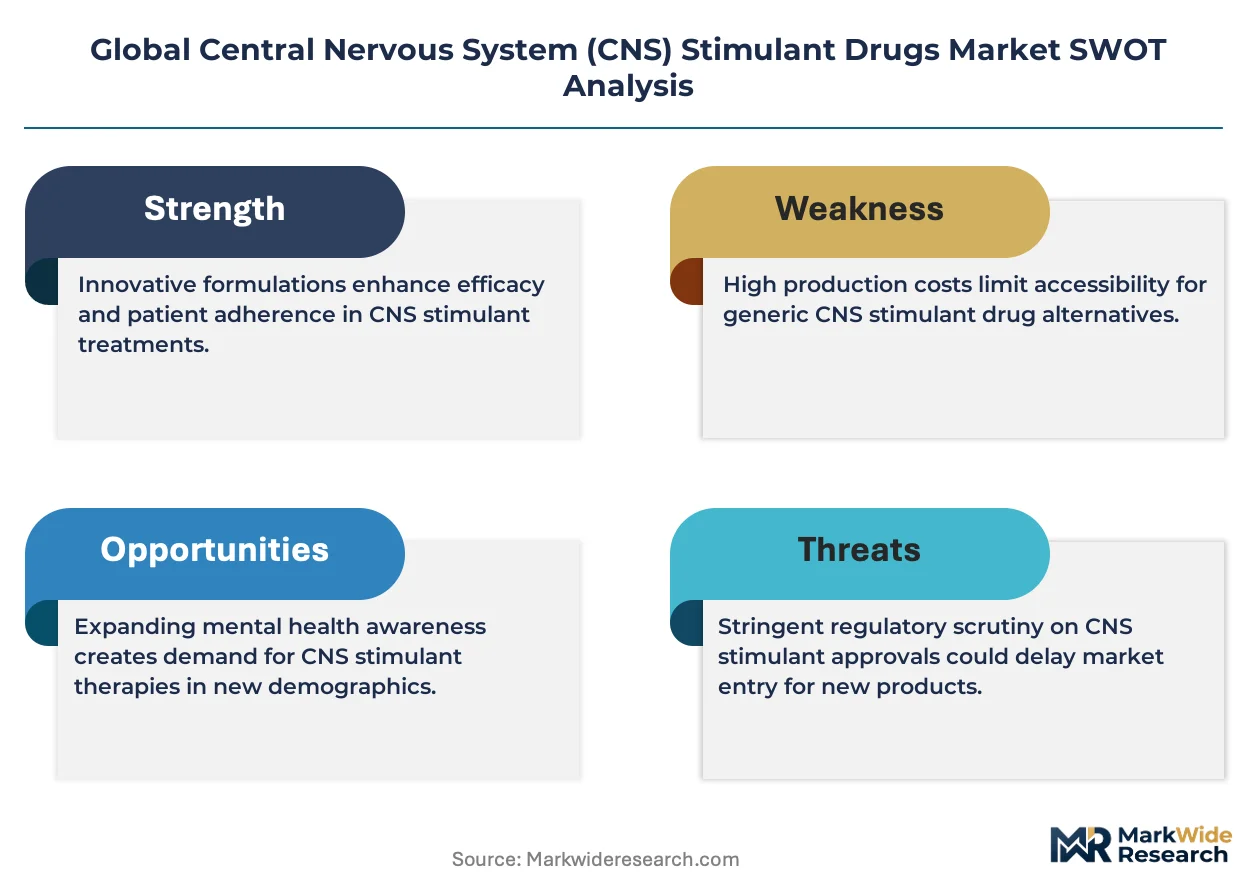
The FDA's Controlled Substances Act scheduling and DEA quota system for Schedule II stimulants directly constrains annual production volumes and creates allocation bottlenecks during demand surges. EMA's pharmacovigilance requirements under the EU Good Manufacturing Practice framework enforce batch-level traceability for psychostimulant APIs that raises compliance costs for European market access. Health Canada's PMRA applies comparable scheduling and import permit restrictions that align North American regulatory density. Stakeholders must monitor how tightening international precursor chemical controls and evolving digital therapeutics reimbursement policies will reshape the competitive boundary between pharmaceutical stimulants and device-based cognitive interventions.
Market Dynamics
The DEA quota system for Schedule II amphetamine salts creates annual production ceilings that force manufacturers into precise demand forecasting and inventory allocation protocols, compressing operational flexibility across the supply base.
Growth Catalysts
- Extended-release formulation engineering:Osmotic-controlled release technologies improve pediatric adherence rates and reduce caregiver burden in clinical settings.
- FDA Risk Evaluation and Mitigation Strategy:Mandatory prescriber certification programs expand the qualified physician pool for controlled substance prescribing.
- Sleep disorder center networks:Specialized narcolepsy clinics in the United States drive concentrated demand for wakefulness-promoting agents.
Market Restraints
- API synthesis concentration:Bulk methylphenidate intermediate production clusters in limited chemical manufacturing zones, creating single-source vulnerability.
- Schedule II storage and transport:DEA vault requirements and chain-of-custody protocols add fixed cost layers to distribution economics.
- Digital therapeutic substitution:FDA-cleared cognitive training devices compete for ADHD adjuvant therapy budgets.
Strategic Opportunities
- Brazilian narcolepsy diagnosis expansion:ANVISA streamlined approval pathways for orphan neurological indications accelerate market access.
- Refractory obesity protocols:Off-label prescribing for weight management in metabolic clinics creates new prescriber segments.
- Pharmacogenomic testing integration:CYP2D6 metabolizer status screening enables personalized stimulant selection and dosing optimization.
Industry Challenges
- DEA quota forecasting accuracy:Annual production allocation requests submitted 18 months ahead of demand cycles create inventory mismatch risk.
- Batch-level API traceability:EU Good Manufacturing Practice requirements for psychostimulant precursor tracking demand specialized serialization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Central Nervous System (CNS) Stimulant Drugs Market |
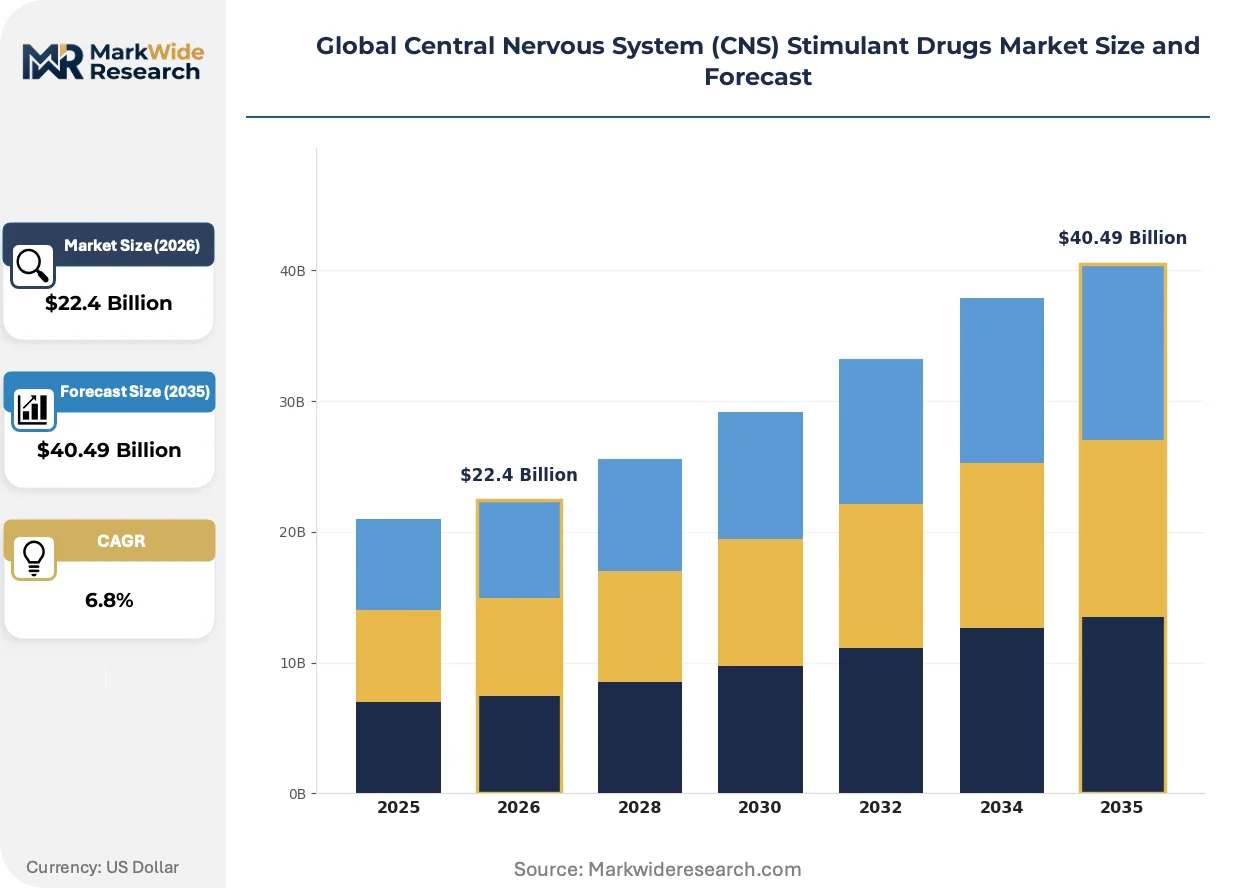
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylphenidate, Amphetamines, Modafinil, Dexmethylphenidate, Phentermine Therapy Area: Attention Deficit Disorder, Narcolepsy, Obesity Management, Cognitive Enhancement, Fatigue Reduction End User: Neurology Clinics, Psychiatric Centers, Research Laboratories, Specialty Pharmacies Delivery Mode: Oral Tablets, Extended-Release Capsules, Transdermal Patches, Injectable Solutions |
| Companies Covered | Pfizer Inc., Jazz Pharmaceuticals Plc, Novartis AG, Azurity Pharmaceuticals Inc., Eli Lilly and Company, Takeda Pharmaceutical Co. Ltd, Teva Pharmaceutical Industries Ltd., Ironshore Pharmaceuticals Inc., Johnson & Johnson Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Central Nervous System (CNS) Stimulant Drugs Market Shifts & Advancements
Formulation science and regulatory technology are converging to reshape how controlled substances move from synthesis to patient, with three distinct vectors altering competitive positioning.
Osmotic pump delivery systems with laser-drilled orifices enable zero-order drug release kinetics that flatten plasma concentration curves. Pediatric psychiatry clinics in the United States adopt these platforms as first-line therapy for treatment-naive patients. This technology is decentralizing prescribing authority from academic medical centers to community-based practices.
EMA's strengthened pharmacovigilance requirements under the EU Good Manufacturing Practice framework mandate real-time adverse event reporting for CNS stimulant batches. Manufacturers must maintain dedicated quality units for signal detection and risk management. European-market entrants face compliance cost barriers that favor established multi-national operators with existing pharmacovigilance infrastructure.
Specialty pharmacy distribution for controlled substances is consolidating around credentialled hubs with DEA-compliant vault networks and direct-to-patient cold chain capabilities. Independent retail pharmacies lose volume to centralized dispensers with automated adherence packaging and prescriber portal integration. This channel compression is most visible in United States metropolitan corridors with high ADHD diagnostic density.
Global Central Nervous System (CNS) Stimulant Drugs Market Segmentation
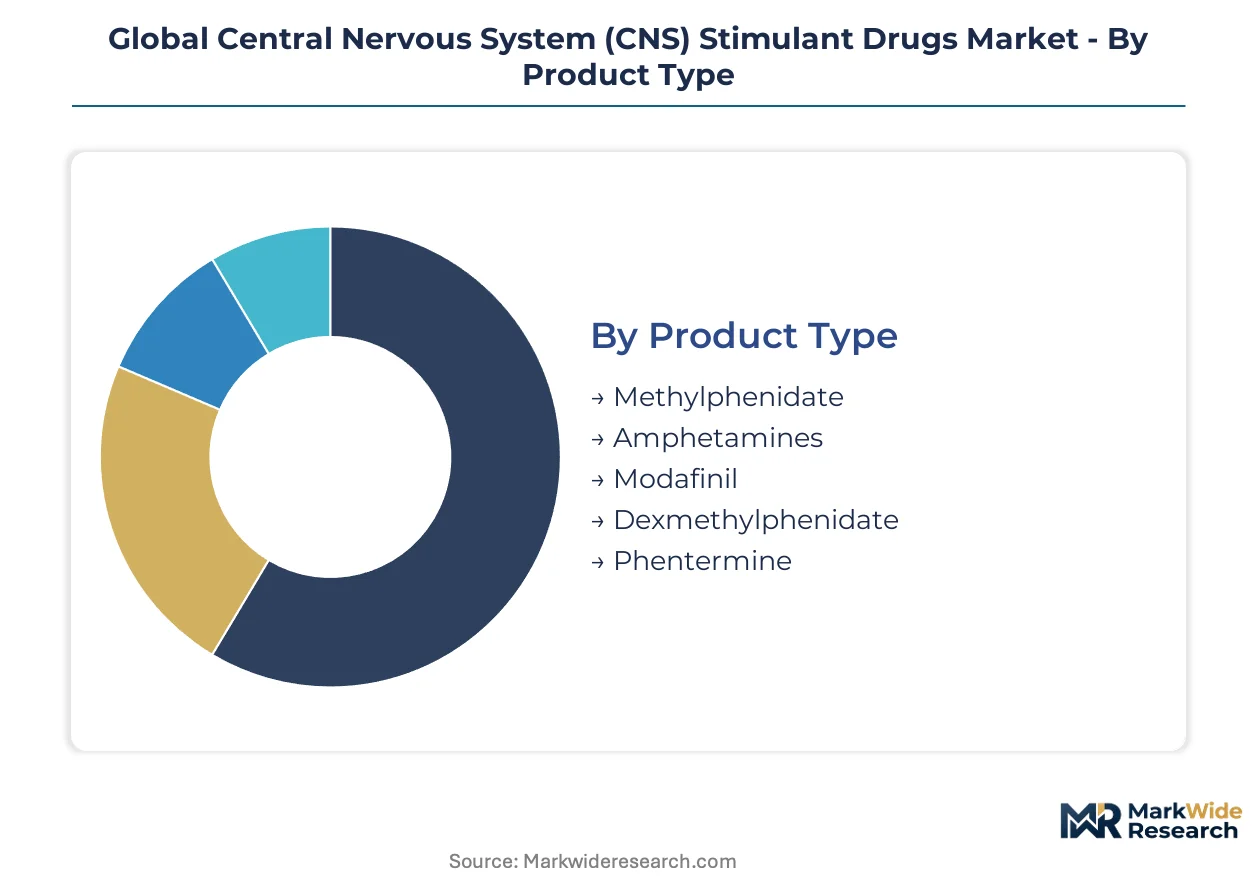
Regulatory scheduling tiers fragment the CNS stimulant landscape into distinct compliance burdens, with Schedule II classifications constraining manufacturing scale and distribution channels differently across molecular classes. Understanding how DEA quotas, FDA REMS requirements, and EMA pharmacovigilance obligations map onto each segment reveals where margin compression and competitive moats concentrate.
Product Type:
DEA Schedule II classification dominates this category, with API synthesis permits and annual production quotas determining which manufacturers can operate at scale; FDA REMS certification applies universally, while EMA batch-level traceability requirements create additional European market entry barriers.
- Amphetamines:DEA-mandated vault storage and dual-signature dispensing protocols apply throughout the supply chain. Demand concentrates in United States pediatric psychiatry practices where diagnostic protocols for attention deficit disorders drive volume. Manufacturing complexity and scheduling restrictions limit generic substitution, preserving margin pools for vertically integrated producers.
- Methylphenidate:Extended-release osmotic pump formulations require specialized laser-drilling equipment and dissolution testing infrastructure. United States specialty pharmacies with DEA-compliant distribution networks capture the majority of dispensed volume. Pediatric adherence programs favor these formulations as first-line therapy.
- Modafinil:Schedule IV classification reduces compliance overhead relative to amphetamine derivatives. Off-label cognitive enhancement prescribing creates regulatory friction across multiple jurisdictions.
- Dexmethylphenidate:Single-isomer manufacturing demands chiral separation capabilities that concentrate production among specialized API synthesis facilities.
- Phentermine:Short-term obesity indication limits prescribing duration under FDA labeling, constraining chronic therapy revenue models.
Amphetamines sit at the top of the volume ranking, with extended-release methylphenidate formulations climbing the fastest.
Therapy Area:
Reimbursement density varies sharply across indications, with attention deficit disorders commanding the broadest pharmacy benefit coverage and obesity management facing the most restrictive prior authorization requirements.
- Attention Deficit Disorder:FDA-approved indications span pediatric through adult populations, with diagnostic expansion in United States primary care settings driving prescription volume. Extended-release formulations capture preference in academic medical centers and community practices alike.
- Narcolepsy:Orphan disease status confers regulatory exclusivity benefits and accelerated review pathways. United States sleep disorder center networks concentrate prescriber expertise and patient volume.
- Obesity Management:Phentermine prescribing faces DEA-mandated duration limits and insurance exclusion from chronic disease formularies.
- Cognitive Enhancement:Off-label modafinil use sits outside established reimbursement codes, creating cash-pay market dynamics.
- Fatigue Reduction:Cancer-related and multiple sclerosis fatigue indications represent emerging prescriber segments with evolving clinical evidence requirements.
Attention deficit disorder claims the largest patient population, with narcolepsy expanding most quickly on orphan drug pricing power.
End User:
Channel consolidation favors credentialled dispensers with controlled substance infrastructure, squeezing independent retail pharmacies out of high-volume stimulant distribution.
- Specialty Pharmacies:Automated adherence packaging and prescriber portal integration differentiate centralized hubs from retail competitors. DEA vault networks and direct-to-patient cold chain capabilities are mandatory for Schedule II dispensing.
- Psychiatric Centers:Academic medical centers maintain REMS-certified prescriber pools and pediatric psychiatry expertise that community practices reference for complex cases.
- Neurology Clinics:Narcolepsy diagnosis and wakefulness-promoting agent prescribing concentrate in United States metropolitan corridors with specialized sleep medicine infrastructure.
- Research Laboratories:DEA research registration and protocol-specific quotas constrain non-clinical stimulant access for pharmacokinetic and mechanism-of-action studies.
Specialty pharmacies lead dispensed volume, with psychiatric centers gaining share fastest on prescriber certification expansion.
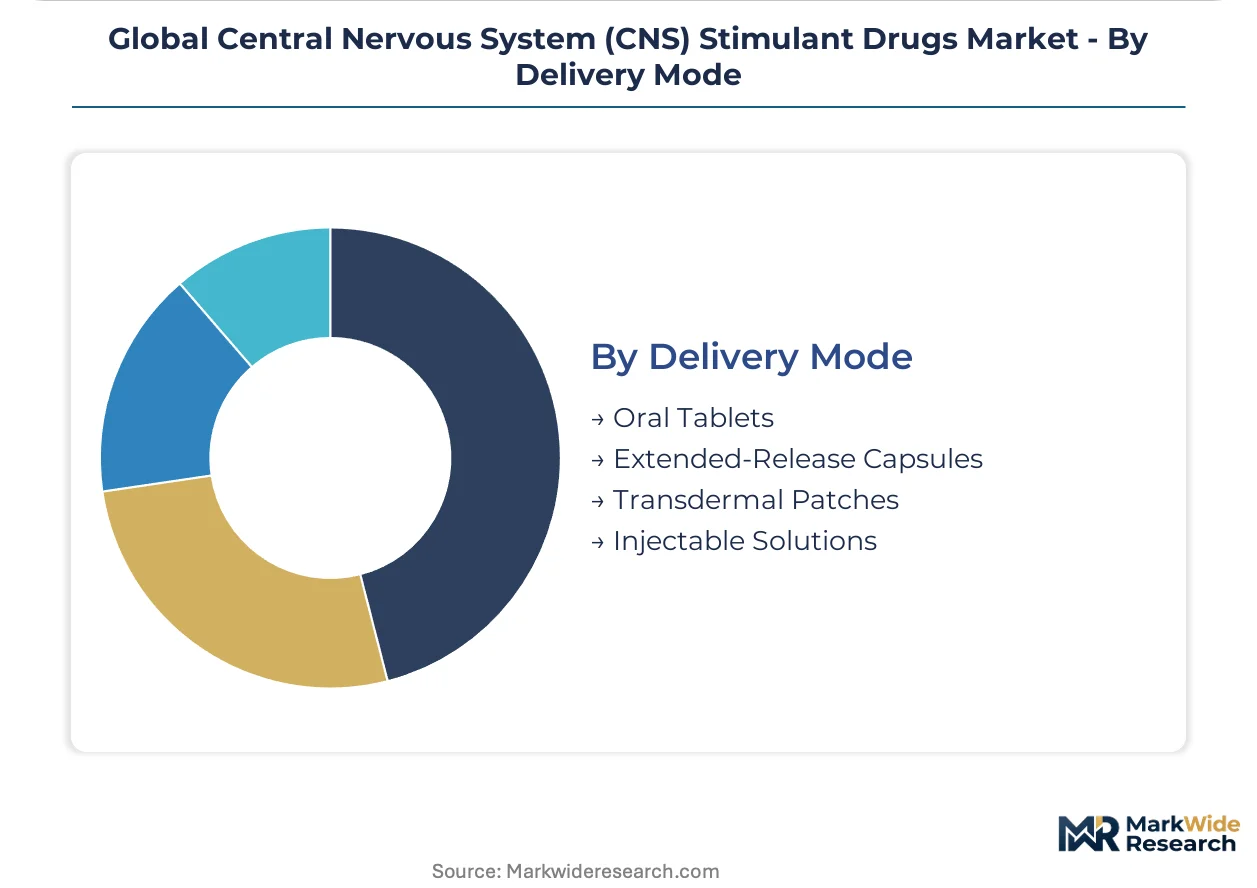
Delivery Mode:
Formulation technology investment requirements create tiered barriers to entry, with osmotic pump manufacturing demanding capital commitments that generic tablet producers cannot replicate.
- Extended-Release Capsules:Laser-drilled osmotic systems enable zero-order release kinetics that flatten plasma concentration curves. Pediatric psychiatry clinics in United States community settings adopt these as first-line therapy for treatment-naive patients.
- Oral Tablets:Immediate-release formulations face the deepest generic penetration and price compression, with DEA quota allocation favoring extended-release production for quota efficiency.
- Transdermal Patches:Methylphenidate patch technology requires adhesive formulation expertise and skin permeation testing that limits manufacturer participation.
- Injectable Solutions:Parenteral stimulant manufacturing demands sterile fill-finish capabilities and cold chain distribution infrastructure rarely applied in this therapeutic class.
Extended-release capsules command the highest volume trajectory, with transdermal patches posting the steepest expansion curve on pediatric compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pharmaceutical corridor stretching from Boston to Research Triangle Park dominates CNS stimulant development, with specialized psychiatry clinics and DEA-registered manufacturing facilities clustering in this corridor. Regulatory density and reimbursement infrastructure here exceed all other markets. Diagnostic expansion in pediatric and adult populations drives volume concentration.
United States
Pediatric psychiatry practices and sleep disorder centers in metropolitan corridors drive prescription volume for extended-release formulations. The FDA's Risk Evaluation and Mitigation Strategy mandates prescriber certification that shapes physician pool expansion. New Jersey and North Carolina host DEA-registered API synthesis and finished-dose manufacturing facilities serving domestic distribution networks.
Germany
Specialized narcolepsy treatment centers in Munich and Berlin concentrate demand for wakefulness-promoting agents. EMA pharmacovigilance requirements under EU Good Manufacturing Practice enforce batch-level traceability that raises compliance barriers. The Rhine-Main industrial zone houses pharmaceutical manufacturing with dedicated controlled substance handling capabilities.
Switzerland
Swissmedic's regulatory framework attracts headquarters operations for companies managing global stimulant portfolios. Basel and Zurich host pharmacovigilance infrastructure serving EMA-aligned reporting requirements. The country's precision chemical synthesis heritage supports specialized API production for niche stimulant derivatives.
Japan
PMDA scheduling restrictions and metropolitan sleep medicine clinics in Tokyo and Osaka shape market access for narcolepsy therapies. The country's aging population creates emerging demand for fatigue-reduction indications in cancer and multiple sclerosis. Kansai region pharmaceutical manufacturing maintains specialized controlled substance production lines.
Brazil
ANVISA streamlined approval pathways for orphan neurological indications accelerate narcolepsy diagnosis expansion in São Paulo and Rio de Janeiro. Private sleep medicine clinics proliferate in southeastern metropolitan corridors. Local regulatory convergence with FDA protocols simplifies import licensing for finished stimulant formulations.
Global Central Nervous System (CNS) Stimulant Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized distribution partnerships with sleep disorder networks and pediatric psychiatry chains. The market structures around three tiers: vertically integrated pharmaceutical conglomerates with captive API synthesis, specialty pharmaceutical companies focused on orphan neurological indications, and generic manufacturers competing on immediate-release tablet formulations. Consolidation pressures intensify as DEA quota allocation favors scale-efficient producers. Strategic moves concentrate on backward integration into precursor chemical supply and geographic expansion into Latin American narcolepsy markets.
Within the integrated pharmaceutical tier, Novartis AG and Pfizer Inc. exemplify scale-driven operators with established controlled substance manufacturing infrastructure. Jazz Pharmaceuticals Plc occupies a specialized position focused on sleep medicine distribution networks. These three entities anchor the competitive structure, with their geographic and regulatory positioning reflecting broader industry patterns of concentration in high-compliance jurisdictions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Jazz Pharmaceuticals Plc |
| Novartis AG |
| Azurity Pharmaceuticals Inc. |
| Eli Lilly and Company |
| Takeda Pharmaceutical Co. Ltd |
| Teva Pharmaceutical Industries Ltd. |
| Ironshore Pharmaceuticals Inc. |
| Johnson & Johnson Services |
| Others |
Supply & Pricing Matrix
Pediatric psychiatry clinic procurement consolidation in the United States favors extended-release formulations, forcing manufacturers to prioritize osmotic pump capacity over immediate-release tablet lines and compressing margins on legacy products. This demand-side specification shift rewards producers with captive API synthesis and DEA quota allocation efficiency.
Pricing Analysis
Input-cost pass-through from methylphenidate intermediate concentration in limited chemical manufacturing zones sustains elevated API pricing for non-integrated producers. Three-tier pricing structure across branded extended-release, authorized generic, and commodity immediate-release tablets separates patient adherence premiums from basic therapy costs. Pricing pressure stems from DEA quota efficiency mandates favoring extended-release production volumes. Cash-pay cognitive enhancement segments exhibit highest price sensitivity; orphan narcolepsy indications show lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
DEA vault certification and dual-signature dispensing protocols gate entry to Schedule II distribution, concentrating qualified handlers in New Jersey and North Carolina manufacturing corridors. API synthesis draws from Switzerland and Germany for chiral separation capabilities, with bulk intermediate production anchored in India and China. Single-source vulnerability in methylphenidate laser-drilling equipment creates procurement risk. Distribution runs through credentialled specialty pharmacy hubs with automated adherence packaging rather than independent retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA REMS certification requirements and ANVISA streamlined orphan pathways creates cost-differential opportunities for manufacturers willing to parallel-track development across jurisdictions.
For Market Incumbents: To counter digital therapeutic substitution in ADHD adjuvant therapy, Novartis AG and Pfizer Inc. should deepen backward integration into precursor chemical supply and expand DEA-registered manufacturing footprint in Research Triangle Park. Captive methylphenidate derivative synthesis preserves margin pools against generic tablet erosion. For New Entrants and Emerging Players: Launch via specialty pharmacy distribution partnerships targeting Brazilian narcolepsy diagnosis expansion in São Paulo metropolitan corridors. White-space concentration in pharmacogenomic testing integration for CYP2D6 metabolizer screening offers prescriber differentiation with lower regulatory burden than novel molecule development. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty pharmaceutical companies holding orphan neurological exclusivity and sleep disorder center relationships. Long-term viability hinges on REMS infrastructure scalability rather than molecule patent duration. Watch DEA quota allocation methodology revisions as inflection signal for scale-efficient producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive methylphenidate intermediate production reduces single-source vulnerability and quota allocation risk. |
| Specialty Pharmacy Distribution Partnership | DEA-compliant vault networks with prescriber portal integration capture high-volume ADHD dispensing volume. |
| Pharmacogenomic Testing Integration | CYP2D6 metabolizer screening enables personalized stimulant selection and dosing optimization protocols. |
| ANVISA Regulatory Pathway Navigation | Streamlined orphan neurological approval accelerates Brazilian narcolepsy market access versus FDA timelines. |
| Extended-Release Formulation Scale-Up | Osmotic pump manufacturing capacity expansion aligns with pediatric psychiatry first-line therapy preferences. |
Research Methodology
Bottom-up patient population modeling reconciled against top-down DEA quota allocation tracking forms the analytical core of this study. Primary interviews with pediatric psychiatry clinic directors, specialty pharmacy procurement managers, regulatory affairs leads at controlled substance manufacturers, and sleep disorder center prescribers combined with secondary validation from FDA REMS enrollment data, DEA production quota publications, EMA pharmacovigilance databases, and ANVISA approval registries. Triangulation across supply-side capacity constraints and demand-side diagnostic expansion patterns ensures consistency.
Input-output matrix framing connects API synthesis capacity, DEA quota ceilings, and formulation technology investment to patient volume projections across the analysis window. Segmentation dimensions include molecular class, therapy area, delivery mode, and regional regulatory cluster. CAGRs derive from reconciling bottom-up prescription volume build-ups with top-down manufacturer revenue disclosures. Forecast inputs incorporate DEA quota request timing lags and EMA batch-level traceability compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DEA quota methodology revisions or international precursor chemical control tightening. Projections reflect assumptions regarding REMS prescriber certification expansion rates and specialty pharmacy channel consolidation velocity. Deviation in FDA digital therapeutic reimbursement policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Europe Adenomyosis Drugs Market