
 Global Cancer Vaccines Drug Pipeline Market | 2026-2036
Global Cancer Vaccines Drug Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Vaccines Drug Pipeline Market Foresight
ISO 14155 clinical investigation standards is reorganizing which sponsors can run multinational cancer vaccine trials, raising compliance costs for smaller developers. Merck & Co., Inc. leverages its established Keytruda combination protocols to anchor immuno-oncology vaccine development across North America and Europe. BioNTech sustains mRNA manufacturing scale that differentiates its supply security from preclinical-stage competitors. Bristol-Myers Squibb competes through checkpoint inhibitor pairing expertise, occupying a dominant position in combination therapy design.
Cancer vaccines drug pipeline refers to therapeutic biologics engineered to stimulate antigen-specific T-cell responses against tumor-associated antigens, typically manufactured through recombinant DNA technology, mRNA synthesis, or ex vivo dendritic cell loading, with purity specifications often requiring endotoxin levels below 0.5 EU/mL and peptide epitope validation via mass spectrometry. RNA-Based platforms command the fastest expansion in early-phase trials due to rapid manufacturing turnaround and flexible neoantigen encoding. Dendritic Cell vaccines retain concentrated margin pools in autologous therapy segments despite higher production complexity. Melanoma leads therapy area allocation, while Lung Carcinoma trials accelerate on the strength of shared neoantigen discovery.
FDA breakthrough therapy designations, EMA PRIME eligibility, and WHO prequalification frameworks collectively determine which pipeline assets secure accelerated review and reimbursed market access across their respective jurisdictions. These regulatory gates filter candidate pools before Phase III commitment, shaping R&D budget allocation toward platforms with designated status. Stakeholders must monitor which development-stage assets achieve regulatory qualification milestones, as these designations signal where manufacturing partnerships and clinical infrastructure investments will concentrate.
Market Dynamics
RNA-based manufacturing platforms are compressing development timelines from years to weeks, forcing legacy recombinant protein producers to retool facilities or exit oncology vaccine contracting entirely.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated review pathway slashes Phase II-to-III transition delays for novel platforms, concentrating capital flows among designated assets.
- Neoantigen sequencing advances:Tumor-specific epitope identification via next-generation sequencing enables truly individualized vaccine design for melanoma and lung carcinoma patients.
- Germany:The country's specialized CDMO cluster in Heidelberg-Mannheim supplies GMP mRNA manufacturing capacity that anchors European trial infrastructure.
Market Restraints
- Lipid nanoparticle input concentration:Four suppliers control ionizable lipid production, exposing developers to raw material allocation risk during scale-up.
- ISO 14155 compliance burden:Restructured multinational trial standards impose documentation requirements that consume 15-20% of smaller sponsor budgets.
- Autologous dendritic cell processing:Patient-specific manufacturing requires cleanroom capacity per dose, capping batch economics regardless of demand.
Strategic Opportunities
- China's biologics corridor:Shanghai and Suzhou zones offer expedited IND pathways for imported mRNA assets, creating first-mover access to the world's second-largest patient pool.
- Tumor-infiltrating lymphocyte pairing:Convergence of cancer vaccines with adoptive cell therapy protocols opens combination trial designs in solid tumors.
- WHO prequalification framework:Emerging market access programs create reimbursed volume channels outside traditional FDA/EMA jurisdictions.
Industry Challenges
- Peptide synthesis scale-up:GMP-grade neoantigen manufacturing requires mass spectrometry validation protocols that few contract manufacturers have operationalized.
- Cold chain integrity:mRNA stability demands ultralow-temperature logistics that strain distribution networks in secondary and tertiary hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Vaccines Drug Pipeline Market |
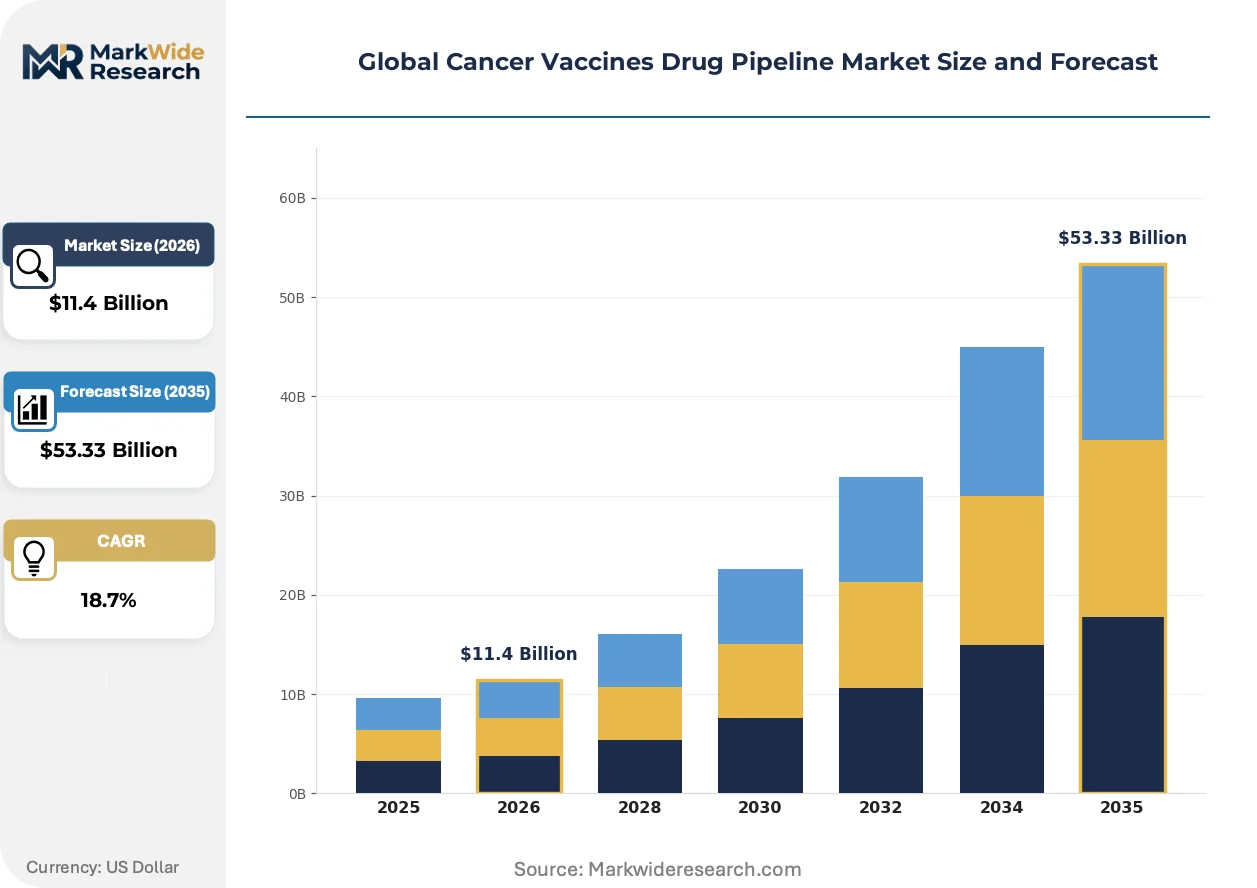
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $53.33 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Peptide-Based, Dendritic Cell, DNA-Based, RNA-Based, Recombinant Protein, Whole-Cell Therapy Area: Melanoma, Lung Carcinoma, Breast Tumors, Colorectal Malignancies, Prostate Neoplasms, Ovarian Cancers Development Stage: Preclinical, Phase I, Phase II, Phase III, Regulatory Review End User: Research Institutions, Biotechnology Firms, Oncology Clinics, Contract Research Organizations, Pharmaceutical Companies |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Moderna, Inc., BioNTech, F. Hoffmann-La Roche Ltd, AstraZeneca plc, Bristol-Myers Squibb, Dendreon Pharmaceuticals LLC, OSE Immunotherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Vaccines Drug Pipeline Market Shifts & Advancements
Manufacturing modality selection now precedes target selection in pipeline design, with platform economics overriding traditional target-centric R&D prioritization.
mRNA synthesis technology is bifurcating clinical trial pipelines into rapid-turnaround personalized neoantigen programs and slower, shared-antigen approaches. Oncology clinics in the United States and Germany are adopting the faster modality for melanoma and non-small cell lung carcinoma indications. This split is compressing investment into preclinical-stage recombinant protein platforms that cannot match mRNA's six-week manufacturing window.
EMA's PRIME eligibility scheme now mandates accelerated assessment timelines for advanced therapy medicinal products, including cancer vaccines. The industrial consequence is a concentration of European trial site investment in Belgium, Netherlands, and Germany where centralized ethics review infrastructure supports parallel national submissions. RNA-based developers are responding by pre-positioning manufacturing partnerships in Leuven and Frankfurt before Phase II initiation.
Hospital procurement departments are unbundling cancer vaccine sourcing from bundled oncology service contracts, creating direct manufacturer-accountable relationships for autologous therapies. Academic medical centers in the United States are leading this disintermediation, establishing dedicated cell therapy procurement offices that negotiate dose-level pricing and manufacturing slot guarantees. The shift is most visible in melanoma treatment networks where patient-specific production timelines require guaranteed manufacturing capacity rather than traditional pharmaceutical inventory models.
Global Cancer Vaccines Drug Pipeline Market Segmentation
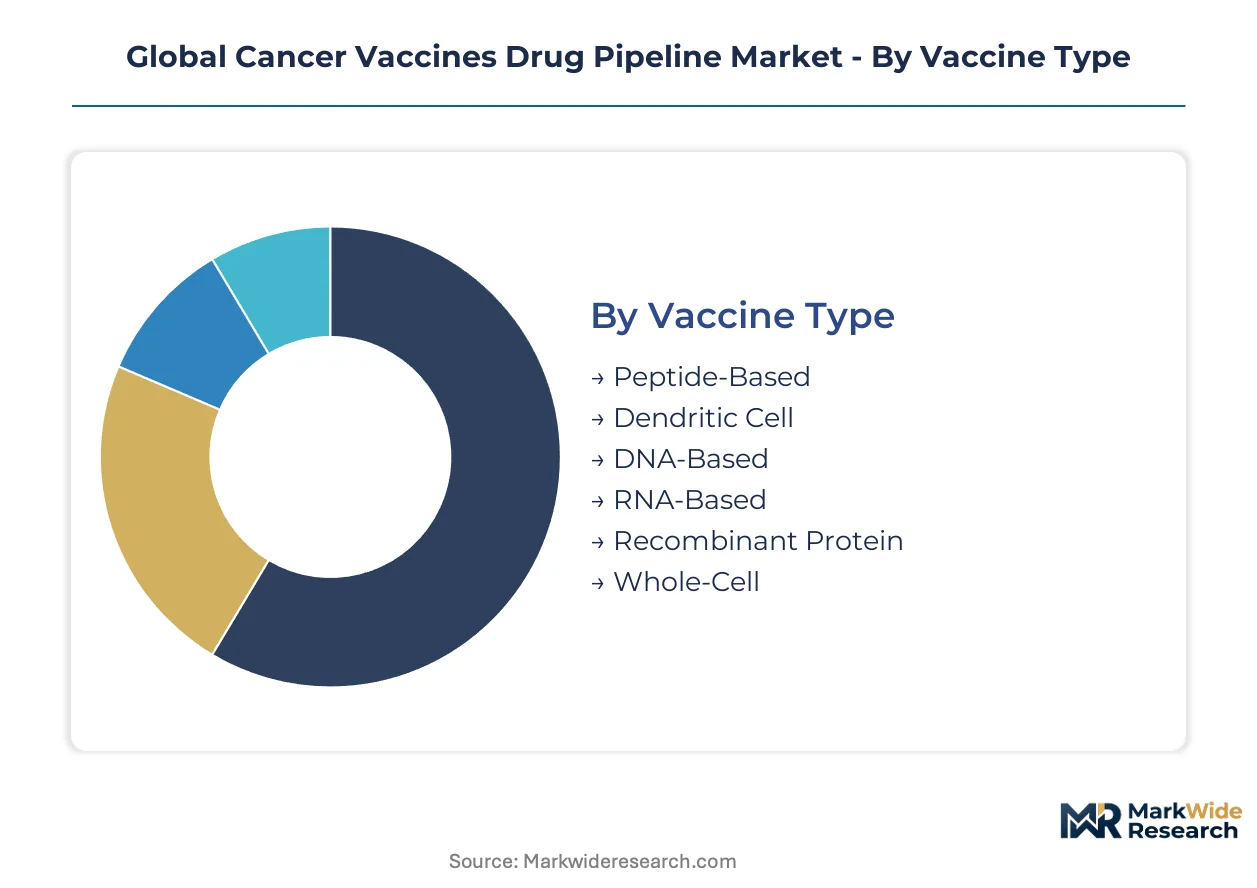
Platform economics now override target-centric R&D prioritization in cancer vaccine development. Manufacturing modality selection precedes therapeutic indication decisions, reshaping how sponsors allocate capital across pipeline assets.
Vaccine Type:
RNA-Based platforms exert the strongest substitution pressure on legacy recombinant protein manufacturing, compressing development timelines from years to weeks and forcing facility retooling decisions.
- RNA-Based:Synthetic mRNA manufactured through in vitro transcription enables rapid neoantigen encoding with six-week turnaround. Demand concentrates in United States and Germany melanoma networks where personalized protocols require flexible, patient-specific production.
- Dendritic Cell:Autologous ex vivo loading of patient-derived antigen-presenting cells demands cleanroom capacity per dose. United States academic medical centers anchor demand despite batch economics that resist scale regardless of volume.
- Peptide-Based:Synthetic epitope cocktails validated via mass spectrometry, constrained by GMP-grade synthesis bottlenecks at contract manufacturers.
- DNA-Based:Plasmid vectors encoding tumor antigens, facing competitive displacement where RNA platforms demonstrate superior immunogenicity.
- Recombinant Protein:Yeast or mammalian cell culture production of purified antigens, losing trial investment share to faster manufacturing alternatives.
- Whole-Cell:Irradiated tumor cell preparations, retaining niche applications in shared-antigen protocols with established clinical datasets.
RNA-Based anchors the volume base while Dendritic Cell gains share at the steepest rate in autologous therapy segments.
Therapy Area:
Cost tier stratification separates high-complexity personalized protocols from standardized shared-antigen approaches across oncology indications.
- Melanoma:Highest density of neoantigen load per tumor enables robust personalized vaccine responses. United States and Germany treatment networks concentrate Phase II investment where sequencing infrastructure supports rapid epitope identification.
- Lung Carcinoma:Shared neoantigen discovery in non-small cell subtypes accelerates trial enrollment. China biologics corridors attract IND filings for imported mRNA assets targeting this indication.
- Breast Tumors:HER2-directed and triple-negative subtypes drive distinct vaccine platform selection based on antigen heterogeneity.
- Colorectal Malignancies:Microsatellite instability-high subset shows enhanced immunogenicity, directing trial design toward checkpoint inhibitor pairings.
- Prostate Neoplasms:Prostatic acid phosphatase and PSA-targeting vaccines occupy a mature clinical space with established regulatory pathways.
- Ovarian Cancers:Intraperitoneal delivery challenges and immunosuppressive microenvironment constrain platform selection to potent cellular therapies.
Melanoma dominates current trial allocation while Lung Carcinoma expands most quickly on shared neoantigen platform adoption.
Development Stage:
Customer type concentration shapes resource allocation, with pharmaceutical sponsors commanding Phase III infrastructure while biotechnology firms populate earlier phases.
- Phase II:Critical value-inflection point where FDA breakthrough therapy designation concentrates capital flows. RNA-Based platforms achieve this status most frequently, triggering manufacturing partnership commitments.
- Phase III:Registration-enabling trials requiring transnational site networks and commercial-scale GMP supply. Merck and Bristol-Myers Squibb anchor investment through checkpoint inhibitor combination protocols.
- Preclinical:Target validation and immunogenicity assessment in murine models, populated by academic and venture-backed developers.
- Phase I:Safety and dose-escalation studies in small patient cohorts, with RNA platforms compressing traditional timelines.
- Regulatory Review:EMA PRIME and FDA priority review pathways determine market access sequencing across jurisdictions.
Phase II commands the steepest investment trajectory while Phase III anchors committed capital deployment.
End User:
Supply concentration among CDMO clusters in Heidelberg-Mannheim and Shanghai-Suzhou dictates which end users secure manufacturing slots for clinical supply.
- Oncology Clinics:Academic medical centers in United States and Germany lead procurement disintermediation, establishing dedicated cell therapy offices for autologous dose negotiation.
- Biotechnology Firms:Venture-backed developers lacking captive manufacturing depend on mRNA CDMO partnerships in Leuven and Frankfurt for European trial supply.
- Pharmaceutical Companies:Integrated sponsors leverage established Keytruda and Opdivo combination infrastructure to anchor vaccine development.
- Contract Research Organizations:IQVIA and Parexel compete for site management contracts in Belgium-Netherlands-Germany corridor where centralized ethics review accelerates enrollment.
- Research Institutions:NIH and German Cancer Research Center generate preclinical datasets that license to commercial developers.
Oncology Clinics anchor patient access volume while Biotechnology Firms drive platform innovation at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations, EMA PRIME eligibility, and China's expedited IND pathways for imported mRNA assets collectively concentrate clinical trial investment and manufacturing partnerships across four dominant geographies. Germany's specialized CDMO cluster supplies European GMP capacity, while United States academic medical centers anchor procurement disintermediation for autologous therapies.
United States
Oncology clinics in academic medical centers drive demand for personalized neoantigen vaccines with rapid manufacturing turnaround. FDA breakthrough therapy designation accelerates Phase II-to-III transitions for RNA-based platforms, slashing regulatory delays for designated assets. Greater Boston and San Diego biotech corridors host concentrated venture-backed developers lacking captive manufacturing who depend on CDMO partnerships.
Germany
The Heidelberg-Mannheim specialized CDMO cluster anchors European mRNA manufacturing capacity for clinical trial supply. EMA PRIME eligibility mandates accelerated assessment timelines for advanced therapy medicinal products, including cancer vaccines. Leuven and Frankfurt manufacturing partnerships pre-position RNA-based developers before Phase II initiation across the Belgium-Netherlands-Germany corridor.
China
Shanghai and Suzhou biologics zones offer expedited IND pathways for imported mRNA assets targeting lung carcinoma indications. The national pharmaceutical regulator prioritizes innovative biologics through streamlined review mechanisms. Yangtze River Delta manufacturing infrastructure attracts first-mover developers seeking access to the world's second-largest patient pool for oncology trials.
United Kingdom
London and Southeast England research institutions generate preclinical datasets that license to commercial developers for pipeline expansion. MHRA operates under retained EU regulatory alignment for advanced therapy medicinal products while developing independent accelerated pathways. Oxford-Cambridge-London golden triangle concentrates early-stage biotechnology firms specializing in peptide-based vaccine platforms.
Switzerland
Swissmedic maintains rigorous but predictable review timelines that attract multinational sponsors seeking regulatory certainty for combination therapy protocols. Basel and Zurich pharmaceutical clusters host integrated sponsors leveraging established checkpoint inhibitor infrastructure. The country's neutrality in regulatory harmonization discussions positions it as a preferred site for multinational Phase III registration trials.
Global Cancer Vaccines Drug Pipeline Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with immuno-oncology infrastructure and venture-backed biotechnology firms dependent on CDMO manufacturing partnerships. The competitive structure concentrates around checkpoint inhibitor pairing expertise and mRNA platform scale. Three archetypes dominate: large-cap pharmaceutical sponsors with established combination protocols, mid-cap RNA platform specialists with captive manufacturing, and preclinical-stage developers licensing institutional datasets. Competitive moves center on manufacturing partnership pre-positioning and regulatory designation capture.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Bristol-Myers Squibb occupy anchor positions through their established Keytruda and Opdivo combination infrastructure. BioNTech exemplifies the RNA platform specialist archetype with differentiated manufacturing scale. Among European biotechnology firms, OSE Immunotherapeutics represents the preclinical-to-clinical transition model dependent on regulatory milestone achievement.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Moderna, Inc. |
| BioNTech |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| Bristol-Myers Squibb |
| Dendreon Pharmaceuticals LLC |
| OSE Immunotherapeutics |
| Others |
Supply & Pricing Matrix
Six-week manufacturing turnaround for personalized mRNA vaccines concentrates pricing power with CDMOs possessing GMP ionizable lipid stocks, while autologous dendritic cell therapies face cost floors from cleanroom capacity constraints per patient dose. This lead-time compression favors sponsors with pre-negotiated manufacturing slots over developers competing for spot capacity.
Pricing Analysis
Certification level (FDA breakthrough therapy designation versus standard IND pathway) creates the primary spread between premium and standard development tiers. Contract-based long-term offtake agreements dominate, with designated assets commanding manufacturing slot guarantees and priority raw material allocation. Price differentiation stems from GMP-grade peptide synthesis validation costs and cold chain logistics complexity. Pricing pressure intensifies in autologous segments as hospital procurement offices negotiate dose-level accountability. Biotechnology firms lacking captive manufacturing exhibit highest price sensitivity; integrated pharmaceutical sponsors with checkpoint inhibitor infrastructure demonstrate lowest.
Supply Chain Analysis
Inventory concentration for ionizable lipids runs through four specialized suppliers in the United States and Germany, exposing developers to allocation risk during Phase III scale-up. Raw material dependencies center on N1-methylpseudouridine modified nucleotides, cholesterol derivatives, and synthetic peptide precursors. Single-source vulnerability in lipid nanoparticle formulation creates supply chain fragility. Distribution runs through ultralow-temperature logistics networks anchored by oncology clinic hubs in Boston, San Diego, Heidelberg, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform modality fragmentation across RNA, dendritic cell, and peptide manufacturing creates specialized service niches as sponsors prioritize speed-to-clinic over vertical integration. Personalized neoantigen protocols demand distinct procurement and logistics capabilities from shared-antigen approaches.
For Market Incumbents: Shield manufacturing partnerships from emerging mRNA platform specialists by locking multi-year GMP capacity agreements in Heidelberg-Mannheim and Leuven clusters. Anchor combination protocol dominance through exclusive checkpoint inhibitor pairing arrangements with academic medical centers.
For New Entrants and Emerging Players: Cold chain logistics coordination for ultralow-temperature mRNA distribution represents an under-served service layer where incumbents rely on fragmented third-party networks. Target China's Yangtze River Delta biologics corridor for expedited IND filings in lung carcinoma indications. Position through CDMO partnerships offering guaranteed manufacturing slots rather than spot contracting.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting preclinical-stage recombinant protein vaccine assets displaced by RNA platform substitution. Long-term viability favors sponsors with regulatory designation momentum and captive lipid nanoparticle formulation capabilities. Watch FDA breakthrough therapy designation velocity as the inflection signal for manufacturing partnership concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Designation Capture | FDA breakthrough therapy status accelerates Phase II-to-III capital commitment timelines. |
| Manufacturing Scale-Up | GMP mRNA capacity expansion in Heidelberg-Mannheim anchors European trial infrastructure. |
| Checkpoint Inhibitor Pairing | Keytruda and Opdivo combination protocols concentrate investment among designated sponsors. |
| Geographic IND Expansion | Shanghai-Suzhou expedited pathways unlock access to China's second-largest patient pool. |
| Pipeline Diversification | Tumor-infiltrating lymphocyte convergence opens solid tumor combination trial designs. |
Research Methodology
Desk research of FDA breakthrough therapy designation databases, EMA PRIME eligibility records, and ClinicalTrials.gov protocol filings preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and CDMO operations directors. Secondary validation drew from formulary databases, GMP inspection records, and customs trade data for lipid nanoparticle precursor imports. Bottom-up patient-flow modeling and top-down pharmaceutical R&D budget allocation analysis were triangulated.
Variance decomposition across vaccine type, therapy area, development stage, and regional regulatory cluster shaped analytical framework construction throughout the projection horizon. CAGRs were derived from sponsor-reported enrollment timelines and manufacturing capacity expansion announcements. Forecast inputs incorporated ISO 14155 compliance cost absorption rates and ionizable lipid supplier concentration indices.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA PRIME eligibility schemes; material policy shifts would require re-modeling designation-driven capital flows. Emerging market reimbursement framework evolution and raw material export restrictions represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market