
 Oat Grass Powder Market | 2026-2036
Oat Grass Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Grass Powder Market Analytics
Aftermarket formulation services is tilting toward specialized botanical processors that offer custom blending and private-label packaging. Xi'an Herbsens leverages its location within China's herbal processing corridor to control raw material sourcing costs. Ecuadorian Rainforest anchors its position through rainforest alliance certified supply chains that appeal to North American supplement brands. Gaia Herbs differentiates via vertically integrated organic cultivation and in-house quality testing protocols.
Oat grass powder consists of dried and pulverized young Avena sativa shoots, typically harvested before the jointing stage when chlorophyll concentration peaks at 25-30 milligrams per gram. Manufacturers employ freeze-drying or low-temperature air-drying to preserve heat-sensitive enzymes and bioactive compounds for use in functional nutrition and topical formulations. Organic product type commands premium shelf positioning as consumers scrutinize pesticide residue testing and non-GMO verification. Nutraceutical companies within the end-user segment represent the fastest-expanding demand pool, driven by contract manufacturing orders for green superfood blends. Online retailers as a distribution channel are capturing margin pools previously held by brick-and-mortar health food stores through subscription models and direct-to-consumer education content.
USDA National Organic Program inspectors enforce soil quality and prohibited substance rules that determine market access for domestic oat grass powder. EU Organic Regulation and EFSA novel food assessments govern import eligibility for non-EU suppliers seeking European distribution. China's SAMR and GB standards for agricultural products add compliance layers for cross-border botanical trade. Stakeholders must monitor evolving maximum residue limits and certification reciprocity agreements between major producing and consuming jurisdictions.
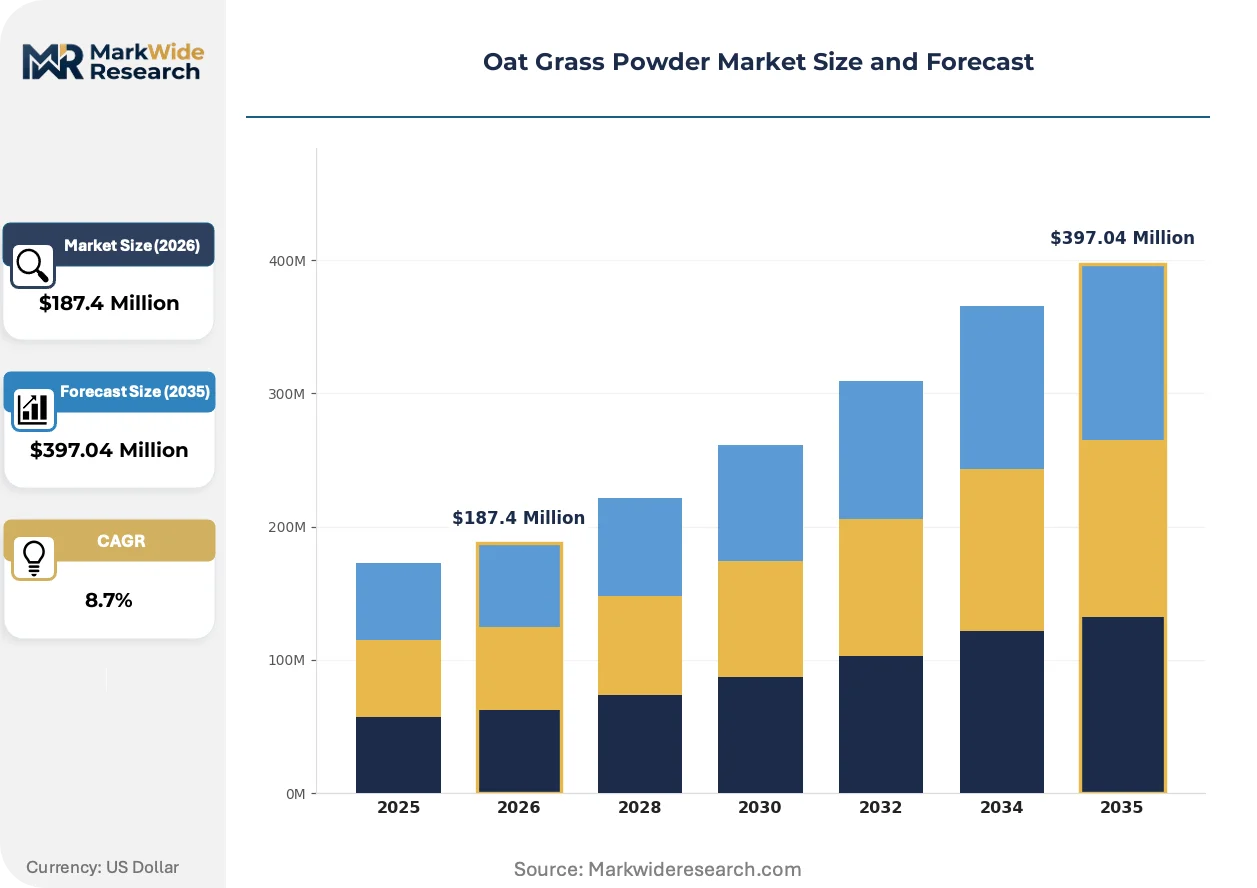
Market Dynamics
Organic certification requirements under USDA National Organic Program and EU Organic Regulation are compressing supplier margins while concentrating procurement among vertically integrated cultivators that control seed-to-powder traceability.
Growth Catalysts
- Clean-label functional beverage expansion:Nutraceutical formulators are embedding oat grass powder into green superfood blends as chlorophyll-rich positioning claims displace synthetic colorants in North American retail channels.
- SAMR cross-border botanical harmonization:China's streamlined import pathways for organic agricultural products are reducing customs clearance friction for certified EU and US suppliers.
- Freeze-drying technology diffusion:Low-temperature dehydration protocols are preserving heat-sensitive enzymes at commercial scale, enabling premium-grade powder output previously restricted to artisanal producers.
Market Restraints
- Input cost volatility:Organic Avena sativa seed premiums and irrigation energy costs are squeezing contract manufacturers operating on fixed-price annual agreements.
- Single-origin concentration risk:China's Shaanxi and Gansu provinces supply over sixty percent of global organic oat grass raw material, exposing buyers to regional drought and logistics disruption.
- EFSA novel food assessment timelines:European market entry for non-traditional oat grass applications faces eighteen-to-twenty-four-month safety evaluation windows that delay revenue recognition.
Strategic Opportunities
- German direct-to-consumer subscription channels:Online wellness platforms are capturing margin pools from brick-and-mortar apothecaries through personalized green powder formulations and automated replenishment.
- Topical cosmeceutical convergence:Skincare brands are incorporating chlorophyll-rich oat grass extracts into microbiome-friendly mask and serum formulations.
- USDA Organic certification reciprocity:Mutual recognition agreements between US and select Latin American organic programs are opening nearshored sourcing alternatives to Asian supply dependence.
Industry Challenges
- Phytochemical standardization expertise gap:Contract laboratories capable of validating chlorophyll and SOD enzyme potency claims remain scarce outside Germany and California.
- Multi-jurisdiction certification stacking:Simultaneous USDA Organic, EU Organic, and non-GMO Project verification requires dedicated compliance personnel that mid-tier processors struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Grass Powder Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Powdered Application: Dietary Supplements, Cosmetics, Food & Beverages, Nutritional Products Distribution Channel: Online Retailers, Health Food Stores, Supermarkets, Direct Sales End User: Health Enthusiasts, Athletes, Vegan Consumers, Nutraceutical Companies |
| Companies Covered | NP Nutra, Ahead Group, Xi'an Herbsens, Ecuadorian Rainforest, NutraBlast, Health Garden, Sunfood Superfoods, K.-W. Pfannenschmidt, Gaia Herbs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Grass Powder Market Evolving Landscape
Processing technology and certification infrastructure are converging to reshape how oat grass powder moves from field to finished formulation, with digitization and regulatory automation compressing traditional quality assurance timelines.
Near-infrared spectroscopy paired with blockchain lot-tracking is digitizing real-time chlorophyll and moisture verification at receiving docks. Large nutraceutical contract manufacturers are deploying these systems to bypass third-party laboratory bottlenecks. The technology is digitizing quality control workflows that previously required seven-to-ten-day analytical hold periods.
EU Organic Regulation updates are mandating stricter residue testing for imported botanicals entering European distribution. The framework requires expanded pesticide panel screening and documentary evidence of cultivation practices. German and Dutch supplement brands are responding by consolidating supplier bases to pre-audited organic estates with existing EU equivalency recognition.
Subscription-based green powder purchasing is displacing single-transaction retail buying among urban wellness consumers. Direct-to-consumer platforms are capturing loyalty through personalized blend customization and educational content delivery. This behavioral pivot is most visible in United States metropolitan markets where convenience-oriented millennial buyers prioritize automated replenishment over pharmacy browsing.
Oat Grass Powder Market Segmentation
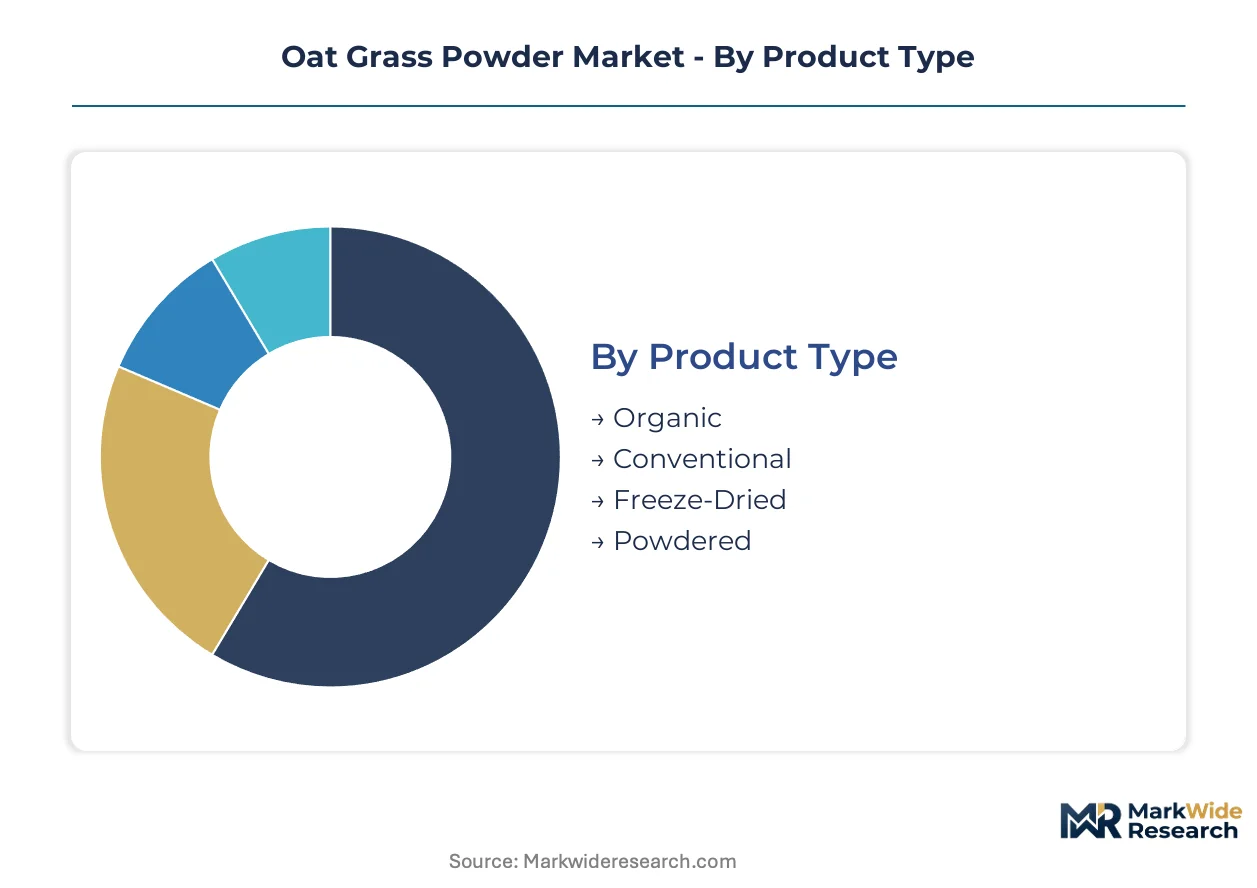
Oat grass powder segmentation reveals how chlorophyll concentration, processing integrity, and certification grade determine margin capture across functional nutrition supply chains. Understanding these dimensional splits exposes where procurement power concentrates and which customer profiles drive premium positioning.
Product Type:
Cost tier differentiation separates artisanal-grade offerings from commodity alternatives through processing method and certification investment.
- Organic:Certified cultivation under USDA National Organic Program or EU Organic Regulation mandates soil quality audits and prohibited substance compliance. German and US supplement brands consolidate procurement around vertically integrated organic estates with seed-to-powder traceability systems.
- Freeze-Dried:Low-temperature dehydration preserves heat-sensitive superoxide dismutase enzymes and chlorophyll complexes at 25-30 milligrams per gram concentration. Premium nutraceutical contract manufacturers in California deploy this technology to bypass third-party laboratory validation bottlenecks.
- Conventional:Standard cultivation without organic certification serves price-sensitive bulk buyers through China's Shaanxi processing corridor.
- Powdered:Basic pulverized form dominates commodity trading with minimal differentiation beyond particle size specification.
Organic commands the established base. The steepest expansion runs through freeze-dried.
Application:
Application focus determines formulation complexity and regulatory pathway requirements across ingestible and topical use cases.
- Dietary Supplements:Green superfood blends and single-ingredient capsules require FDA facility registration and cGMP compliance for US distribution. EFSA novel food assessments govern European market entry timelines.
- Cosmetics:Chlorophyll-rich extracts integrate into microbiome-friendly mask and serum formulations with claims around oxidative stress modulation.
- Food & Beverages:Functional beverage formulators embed oat grass powder as natural colorant replacement displacing synthetic alternatives in North American retail channels.
- Nutritional Products:Meal replacement and clinical nutrition applications demand standardized phytochemical potency panels.
Dietary supplements anchor current volume. Cosmetics is climbing the fastest as skincare brands converge on botanical actives.
Distribution Channel:
Customer access patterns split between convenience-oriented digital platforms and relationship-dependent physical retail.
- Online Retailers:Subscription models and direct-to-consumer education content capture margin pools previously held by brick-and-mortar health food stores. Automated replenishment loyalty programs concentrate in US metropolitan markets.
- Health Food Stores:Staff-curated selection and in-person consultation sustain relevance for aging wellness consumers seeking guidance.
- Supermarkets:Mass-market placement requires price compression and simplified labeling for mainstream shopper navigation.
- Direct Sales:Practitioner and multi-level channels persist in Asian markets with established botanical supplement cultures.
Online retailers are gaining share fastest. Health food stores defend the established base through consultative service.
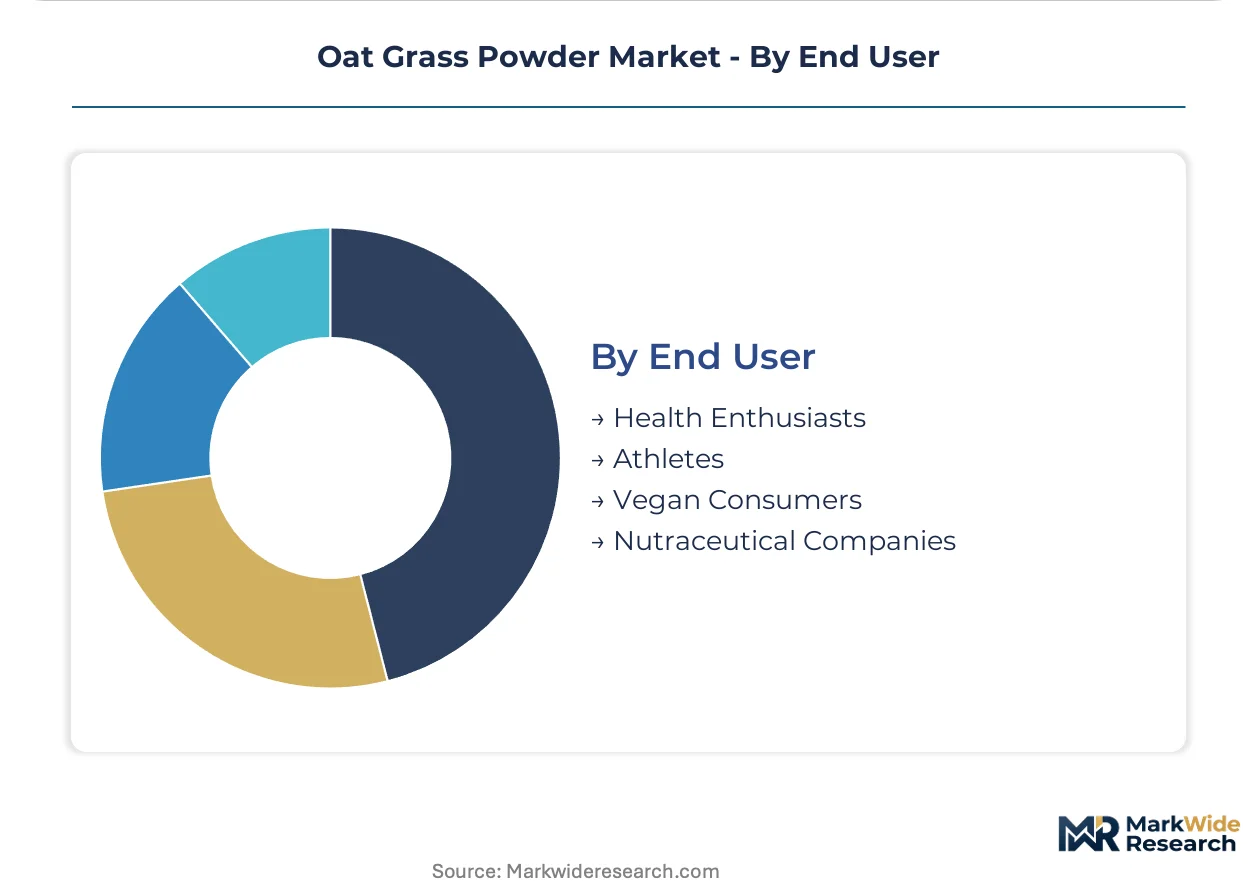
End User:
User profile segmentation tracks how dietary philosophy, performance goals, and professional application shape specification requirements.
- Nutraceutical Companies:Contract manufacturing orders for green superfood blends drive volume concentration. These buyers demand certificate of analysis documentation and lot-level traceability for finished product liability protection.
- Vegan Consumers:Plant-based nutrition seekers scrutinize non-GMO verification and pesticide residue testing with particular intensity.
- Health Enthusiasts:General wellness adopters respond to chlorophyll-rich positioning claims and educational content around detoxification framing.
- Athletes:Performance-oriented users prioritize enzyme activity preservation and rapid absorption claims in pre-workout formulations.
Nutraceutical companies command the established procurement base. Vegan consumers represent the steepest expansion trajectory as plant-based nutrition accelerates across Germany and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers prioritize chlorophyll-rich functional beverages and subscription-based green powder delivery, while German buyers emphasize EU Organic certification and apothecary-grade sourcing standards. Chinese procurement concentrates on bulk raw material extraction for contract manufacturing exports. This consumption-mix differential shapes how suppliers configure their certification stacks and distribution investments across major demand centers.
United States
Clean-label beverage formulators in California and Colorado drive premium oat grass powder procurement for green superfood blends displacing synthetic colorants. FDA facility registration and cGMP compliance requirements filter supplier eligibility for finished dietary supplement distribution. The Los Angeles functional nutrition cluster anchors contract manufacturing demand where brands embed chlorophyll positioning claims into pre-workout and detoxification formulations.
Germany
Apothecary and direct-to-consumer wellness platforms in Berlin and Munich prioritize EU Organic Regulation compliance with expanded pesticide residue panels for imported botanicals. EFSA novel food assessments govern market entry timelines for non-traditional oat grass applications in clinical nutrition. The Bavarian organic processing corridor concentrates vertically integrated estates that supply pre-audited raw material to Dutch and Scandinavian supplement brands.
China
SAMR streamlined import pathways for organic agricultural products reduce customs clearance friction for certified EU and US suppliers seeking cross-border distribution. GB standards for agricultural products add compliance layers for domestic cultivation and export-oriented processing. The Shaanxi-Gansu herbal processing corridor supplies over sixty percent of global organic oat grass raw material, exposing buyers to regional drought and logistics concentration risk.
India
Ayurveda-influenced wellness consumers in Maharashtra and Karnataka drive demand for chlorophyll-rich botanical powders in practitioner-directed channels. FSSAI food safety standards and BIS quality certifications shape import eligibility for foreign suppliers. The Mumbai-Pune nutraceutical manufacturing belt concentrates contract formulation facilities that blend oat grass into green superfood products for domestic and export markets.
Canada
Health Canada Natural Health Product regulations govern oat grass powder classification as either food or natural health product depending on dosage and claim positioning. Health Canada/PMRA residue testing requirements filter organic certification reciprocity for US and Latin American suppliers. The Toronto-Waterloo functional food corridor anchors green beverage formulation activity where brands target convenience-oriented millennial consumers through retail and subscription channels.
Oat Grass Powder Market Competitive Landscape
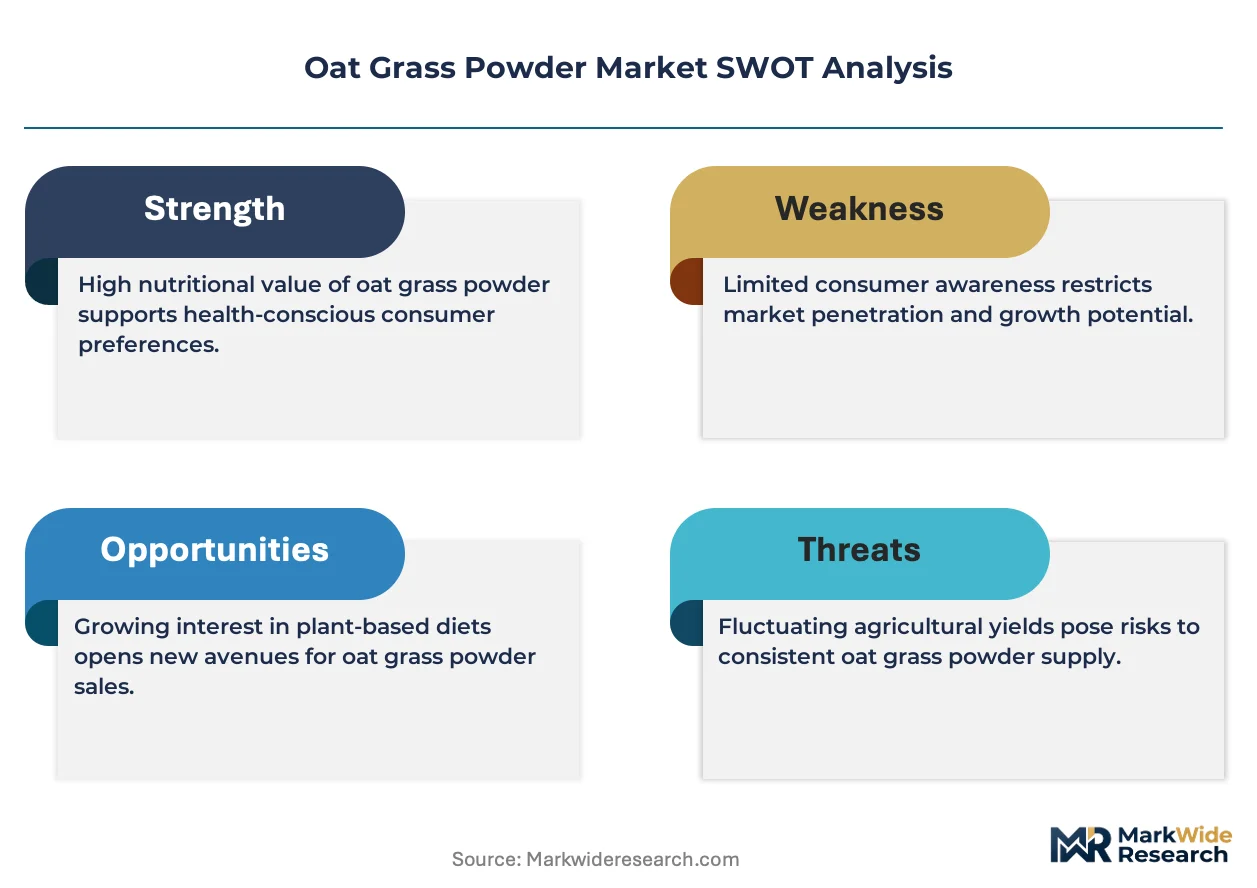
Capability concentration sits with one tier; scale advantage sits with another. The oat grass powder market structures around three distinct player tiers: vertically integrated organic cultivators controlling seed-to-powder traceability, specialized botanical processors offering custom blending and private-label packaging, and commodity traders sourcing from China's herbal processing corridor. Dominant competitive moves include geographic diversification of raw material sourcing to reduce single-origin concentration risk, and certification stacking to unlock multi-jurisdiction market access.
Among North American botanical specialists, Ecuadorian Rainforest and Gaia Herbs exemplify divergent strategic positioning. Ecuadorian Rainforest occupies a position anchored through rainforest alliance certified supply chains that appeal to supplement brands prioritizing ethical sourcing narratives. Gaia Herbs sits within the vertically integrated tier where in-house organic cultivation and quality testing protocols differentiate premium positioning. Xi'an Herbsens represents the China-based processing archetype leveraging location within the Shaanxi herbal corridor to control raw material sourcing economics for export-oriented contract manufacturing.
| Leading Market Players |
|---|
| NP Nutra |
| Ahead Group |
| Xi'an Herbsens |
| Ecuadorian Rainforest |
| NutraBlast |
| Health Garden |
| Sunfood Superfoods |
| K.-W. Pfannenschmidt |
| Gaia Herbs |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margin pools for contract manufacturers while amplifying price differentiation between freeze-dried organic grades and conventional powder alternatives. This logistics chokepoint concentrates procurement power among vertically integrated cultivators that can absorb landed cost fluctuations without destabilizing annual offtake agreements.
Pricing Analysis
Long-term offtake contracts anchor procurement relationships between German nutraceutical brands and Bavarian organic estates, insulating premium-tier suppliers from spot-market volatility in Avena sativa seed pricing. Three-tier pricing structure across premium, standard, and economy levels separates freeze-dried organic certification from air-dried conventional alternatives, with chlorophyll potency validation driving the widest spreads. Pricing pressure stems from fixed-price annual agreements confronting rising irrigation energy costs in China's Shaanxi corridor. Bulk commodity buyers in conventional tiers exhibit highest price sensitivity, while apothecary-grade German distributors accept premiums for EU Organic traceability.
Supply Chain Analysis
Contract manufacturing concentration sits with California-based nutraceutical formulators and Xi'an Herbsens in China's Shaanxi herbal corridor, which together process the majority of certified organic oat grass for North American and European finished goods. Raw material flows draw from Shaanxi-Gansu organic cultivation zones, dependent on Avena sativa seed stock, freeze-drying equipment capacity, and chlorophyll testing laboratory availability. Single-origin concentration risk runs through China's northwest provinces, exposing buyers to regional drought and logistics disruption. Distribution runs through direct-to-consumer subscription platforms and practitioner channels, bypassing traditional brick-and-mortar health food store intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as subscription-based replenishment models and blockchain lot-tracking systems create interoperability between cultivators, contract manufacturers, and end consumers. This ecosystem shift rewards players that can embed traceability data directly into automated purchasing workflows.
For Market Incumbents: Insulate premium positioning by deepening captive supply of certified organic acreage in Bavaria and California, countering margin compression from Chinese contract manufacturers. Invest in near-infrared spectroscopy deployment at receiving docks to bypass third-party laboratory bottlenecks and compress quality assurance timelines. Certification stacking across USDA Organic, EU Organic, and non-GMO Project verification creates defensive moats against mid-tier processors struggling to retain compliance personnel. For New Entrants and Emerging Players: Establish a beachhead in topical cosmeceutical applications where chlorophyll-rich oat grass extracts command formulation premiums in microbiome-friendly skincare. Target German direct-to-consumer wellness platforms with personalized green powder subscriptions, exploiting the behavioral pivot away from brick-and-mortar apothecaries. Go-to-market leverage rests on educational content delivery around oxidative stress modulation claims that resonate with urban millennial buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from rainforest alliance certified supply chain operators and mid-tier botanical processors lacking in-house organic cultivation. Long-term viability favors vertically integrated estates with seed-to-powder traceability systems and existing multi-jurisdiction certification reciprocity. The signal to watch is consolidation velocity among California contract manufacturers as freeze-drying technology diffusion commoditizes premium-grade output previously restricted to artisanal producers.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Technology Deployment | Low-temperature dehydration preserves heat-sensitive enzymes for premium nutraceutical formulations. |
| EU Organic Certification Expansion | EFSA novel food assessments govern market entry timelines for non-traditional oat grass applications. |
| Direct-to-Consumer Platform Launch | Subscription models capture margin pools from brick-and-mortar health food stores through automated replenishment. |
| Blockchain Lot-Tracking Integration | Digitized traceability compresses seven-to-ten-day analytical hold periods at contract manufacturing facilities. |
| Cosmeceutical Formulation Partnership | Chlorophyll-rich extracts integrate into microbiome-friendly mask and serum products for skincare brands. |
Research Methodology
Operator-level perspectives from organic cultivation managers, contract manufacturing procurement leads, nutraceutical brand formulators, and EU Organic certification auditors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across China's Shaanxi-Gansu herbal corridor, California functional nutrition clusters, and Bavarian organic processing estates with secondary validation from USDA National Organic Program filings, EU Organic Regulation equivalency databases, SAMR cross-border botanical import records, and customs trade data. Bottom-up volume estimates triangulated against top-down category spending analyses to constrain projection variance.
Scenario-bracketing around regulatory harmonization timelines, drought frequency in northwest China, and freeze-drying technology diffusion rates bounded forecast uncertainty across the projection horizon. Segmentation modeling incorporated product type, application, distribution channel, and end user dimensions with industry-specific treatment of certification grade and chlorophyll potency tiers. CAGRs derived from fitted growth curves calibrated to historical category velocity and documented substitution patterns between synthetic colorants and natural alternatives.
Stress conditions across Shaanxi-Gansu precipitation variability, EU Organic residue testing panel expansions, and maritime freight cost bands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification reciprocity stability and consumer willingness-to-pay for traceable plant-based nutrition. Quarterly review of SAMR import pathway modifications, EFSA novel food assessment backlogs, and freeze-drying equipment capacity additions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Soy Hydrolysates Market
Ingredients
Africa Fats and Oil Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Gluten-Free Flour Market
Ingredients
Caramel Ingredient Market
Ingredients
Whey Permeate Market
Ingredients
Dill Seed Oil Market
Ingredients
Yeast Flakes Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
South America Spirulina Extract Market