
 Fermented Ingredients Market | 2026-2036
Fermented Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Ingredients Market Analysis
The fermented ingredients sector is pivoting on a widening split between precision-fermented premium inputs and commodity-grade bulk extracts. BASF leverages its industrial biotechnology base to dominate high-purity enzyme supply for pharmaceutical applications. Kerry Group anchors its position through deep backward integration into yeast and probiotic strain libraries. Chr. Hansen specializes in live culture collections that differentiate its dairy and nutritional supplement offerings.
Fermented ingredients comprise metabolically active or inactivated biomass, organic acids, enzymes, and flavor compounds produced through controlled microbial cultivation on carbohydrate or protein substrates, typically operating at temperatures between 25°C and 45°C with pH monitoring across batch or fed-batch bioreactor systems. These inputs serve primarily to enhance shelf stability, bioavailability, sensory profiles, and functional nutrition in downstream formulations. Probiotics and yeast extracts lead product type revenue pools due to entrenched demand in digestive health and umami flavor replacement, while fermented beverages within the same category show faster growth trajectories tied to kombucha and functional soda expansion. Powder forms capture the largest share of the form segmentation through superior logistics economics and extended stability, though liquid concentrates gain traction in beverage and cosmetics applications where solubility and sensory integration matter.
EFSA novel food regulations and FDA GRAS notification requirements impose substantial toxicological documentation burdens that filter out smaller entrants and favor established players with dedicated regulatory affairs capacity. REACH compliance for fermentation-derived chemicals and EU Green Deal bioeconomy targets further redirect capital toward carbon-efficient production platforms and renewable feedstock sourcing. Stakeholders must monitor evolving strain classification protocols and emerging genome-editing guidance from multiple jurisdictions to anticipate which innovation pipelines secure market access fastest.
Market Dynamics
Precision fermentation scale-up is compressing production timelines for high-purity enzymes and bioactive compounds, forcing incumbent suppliers to reconfigure capital deployment toward continuous bioprocessing systems or cede margin to biotech-native competitors.
Growth Catalysts
- EFSA novel food pathways:Streamlined safety assessments for fermentation-derived proteins accelerate commercialization timelines for dairy alternatives and functional ingredients across European formulations.
- Clean-label bakery demand:Manufacturers replace chemical preservatives with fermented antimicrobial metabolites to meet retailer ingredient blacklists and consumer transparency expectations.
- Biotech clusters in Hamburg and Munich:Concentrated strain engineering expertise and shared pilot facilities reduce R&D fixed costs for precision fermentation startups targeting industrial enzyme markets.
Market Restraints
- Feedstock cost volatility:Corn and sugar cane price swings directly compress margins for bulk organic acid and yeast extract producers operating on thin conversion economics.
- Strain IP concentration:Proprietary probiotic and enzyme-producing organisms remain locked behind exclusive licensing agreements held by a narrow set of culture collection custodians.
- Dual-use biosecurity screening:Export control classifications for engineered microbial strains create customs delays and documentation burdens that disrupt just-in-time supply to Asian manufacturing partners.
Strategic Opportunities
- Personalized nutrition pipelines:Gut microbiome testing integration enables bespoke probiotic formulations targeting individual metabolic profiles, opening direct-to-consumer channels beyond mass-market retail.
- EU Green Deal bioeconomy procurement:Public sector catering and institutional foodservice mandates for sustainably sourced ingredients create guaranteed offtake volumes for carbon-efficient fermentation platforms.
- Cosmeceutical fermentation:Postbiotic lysates and fermented botanical extracts penetrate premium skincare lines seeking microbiome-friendly positioning distinct from traditional preservative systems.
Industry Challenges
- Continuous bioprocessing talent scarcity:Operators capable of managing perfusion fermentation and real-time metabolite monitoring command premium compensation that strains mid-scale facility economics.
- Multi-jurisdictional strain registration:Divergent genome-edited organism classifications between FDA, EFSA, and China's SAMR force parallel safety dossier preparation for identical production strains.
- Legacy batch infrastructure retrofitting:Converting stainless steel tank farms to single-use or hybrid continuous systems demands extended validation timelines that delay capacity expansion by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Ingredients Market |
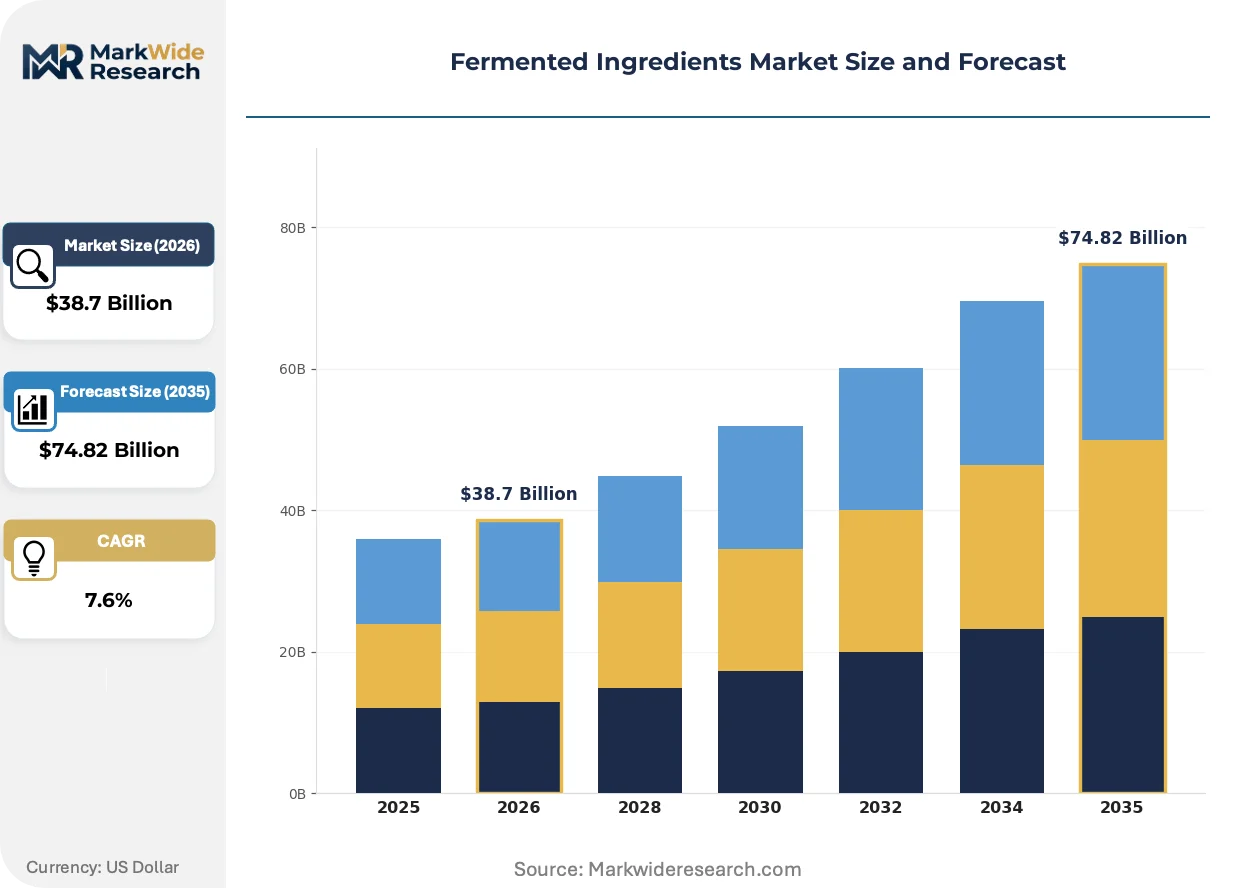
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $74.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Yeast Extracts, Fermented Grains, Fermented Beverages End Use: Dairy Products, Bakery Items, Sauces, Nutritional Supplements Form: Liquid, Powder, Granular, Paste Application: Food & Beverages, Animal Feed, Pharmaceuticals, Cosmetics |
| Companies Covered | BASF, Angel Yeast, DuPont, Corbion, Lesaffre, Kerry Group, Chr. Hansen, Novozymes, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Ingredients Market Emerging Trajectories
Bioprocess intensification and modular manufacturing architectures are redrawing competitive boundaries between centralized commodity producers and distributed specialty fermentation operations serving regional formulation hubs.
Continuous perfusion fermentation is converging with inline Raman spectroscopy for real-time metabolite monitoring, enabling pharmaceutical-grade enzyme manufacturers to tighten batch-to-batch consistency specifications. Biologics contract manufacturers adopt these integrated platforms fastest, compressing quality assurance cycles from weeks to days. The technology is converging with automated feedback control systems that adjust feed rates and harvest timing without operator intervention, reducing labor intensity in high-wage European production environments.
REACH registration requirements for fermentation-derived chemicals above one-tonne annual volume impose toxicological data generation costs that filter out smaller specialty producers. ECHA's evolving guidance on substance identity for complex microbial fermentation mixtures creates classification uncertainty that delays dossier approvals. Dairy enzyme suppliers face the steepest compliance burdens, as lipase and protease formulations frequently trigger multi-constituent substance debates requiring extensive analytical characterization.
Formulation houses now specify certified carbon footprint metrics alongside purity and activity specifications in probiotic procurement tenders. Third-party verified lifecycle assessments displace generic sustainability claims, with Scandinavian and German buyers demanding scope-three emissions documentation through tier-two suppliers. This behavioral shift concentrates contract awards on fermentation operators with captive renewable energy and agricultural residue feedstock sourcing, penalizing conventional glucose-based production in carbon-intensive electricity grids.
Fermented Ingredients Market Segmentation
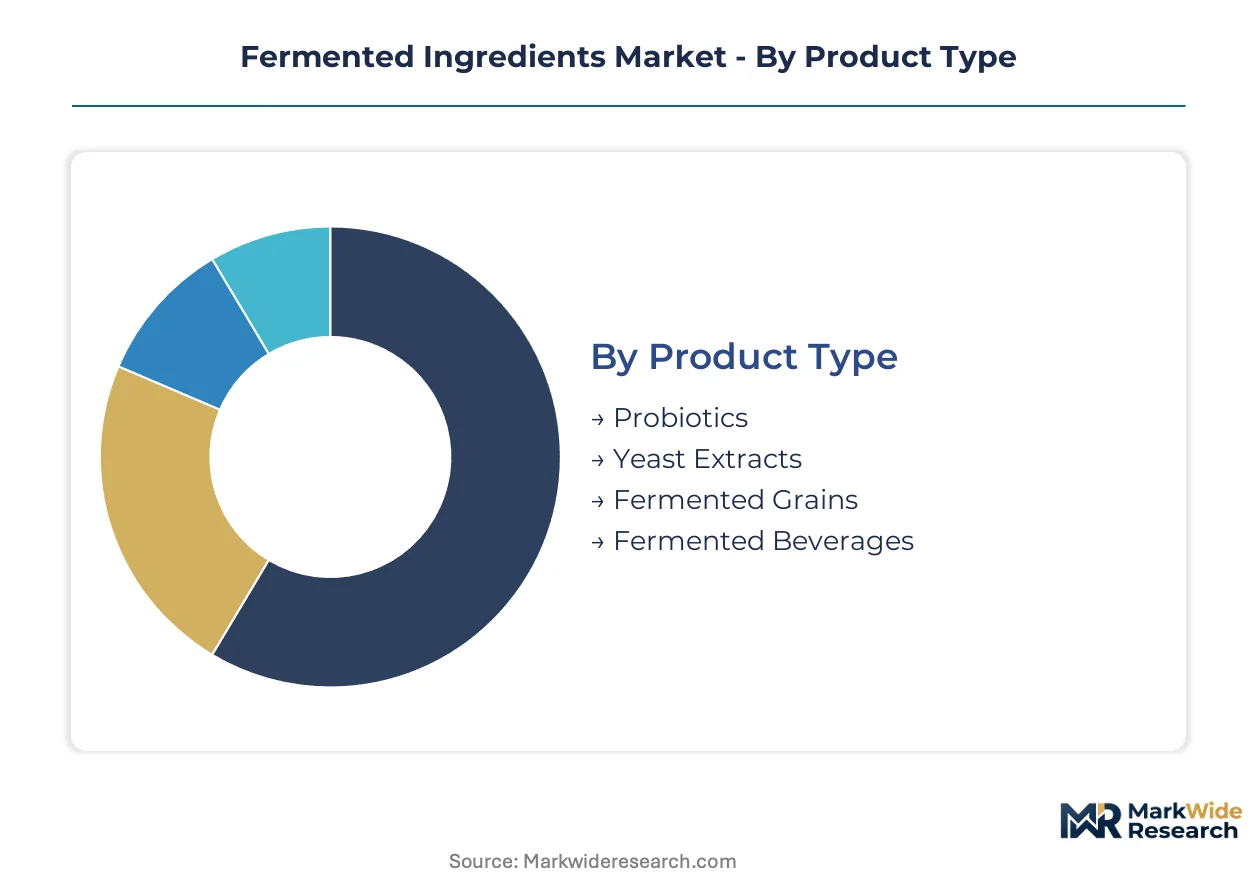
Fermented ingredients exhibit distinct performance profiles across product categories, end-use applications, and physical forms that determine procurement specifications and margin structures. Manufacturers align strain selection and processing intensity with downstream requirements ranging from live culture viability to shelf-stable extract concentration.
Product Type:
Strain engineering sophistication and metabolic pathway control differentiate product tiers, with live cultures demanding cold-chain integrity against thermally processed extracts.
- Probiotics:Live microbial cultures requiring CFU potency guarantees and refrigerated logistics dominate digestive health formulations. Dairy and supplement manufacturers in Germany and the Netherlands specify strain-level identity for label claims compliance with EFSA health assessment protocols.
- Yeast Extracts:Autolyzed biomass rich in nucleotides and glutamic acid serves as clean-label umami enhancers replacing synthetic flavor enhancers. Clean-label bakery and sauce applications in France and Italy drive specification tightening around sodium reduction and allergen-free certification.
- Fermented Grains:Bioprocessed cereal substrates yield prebiotic fiber and modified starch functionalities for texture modification.
- Fermented Beverages:Kombucha and functional soda bases with active cultures or pasteurized metabolites target convenience retail channels.
Mature deployment sits with Yeast Extracts. Newer deployment is concentrated in Fermented Beverages.
End Use:
Formulation tolerance for microbial load, pH interaction, and thermal stress varies sharply across food matrices and nutritional delivery systems.
- Dairy Products:Yogurt, kefir, and fermented milk applications integrate live cultures as primary functional ingredients. German and French processors specify Chr. Hansen and DuPont strain libraries for documented survival rates through gastric transit.
- Bakery Items:Sourdough starters and enzyme-active ferments replace chemical dough conditioners in artisan and industrial bread lines. Italian and Spanish bakers source region-specific lactobacilli consortia for protected designation of origin compliance.
- Sauces:Fermented soy and grain bases deliver depth and stability in condiment formulations.
- Nutritional Supplements:Capsule and sachet formats prioritize high-CFU probiotics with enteric coating compatibility.
Volume concentration rests with Dairy Products. Steepest expansion trajectory appears in Nutritional Supplements.
Form:
Moisture content and particle engineering dictate dissolution kinetics, packaging requirements, and transport economics across supply chain configurations.
- Powder:Spray-dried or freeze-dried matrices with glass transition stabilization enable ambient distribution and extended shelf life. Bulk ingredient procurement by pharmaceutical and animal feed compounders in the US and Brazil prioritizes flowability and reconstitution speed.
- Liquid:Concentrates and suspensions with preserved metabolic activity suit beverage blending and cosmetics fermentation. German and Swiss cosmetics formulators specify postbiotic lysates in aqueous bases for microbiome-friendly skincare positioning.
- Granular:Agglomerated particles balance dispersibility with reduced dusting for industrial scale-up.
- Paste:High-solids preparations serve artisan foodservice and ethnic cuisine authenticity requirements.
Supply chain scale favors Powder. Application innovation clusters in Liquid.
Application:
Regulatory classification and quality system requirements fragment demand across food-grade, feed-grade, pharmaceutical-grade, and cosmetic-grade specifications.
- Food & Beverages:Clean-label reformulation drives replacement of synthetic preservatives and flavor enhancers with fermentation-derived alternatives. US and European manufacturers face retailer ingredient blacklists that mandate natural antimicrobial metabolites in prepared foods.
- Animal Feed:Probiotic and enzyme supplements for gut health and feed conversion efficiency target poultry and swine operations. Brazilian and Thai integrators specify Bacillus-based spore formulations for tropical climate stability.
- Pharmaceuticals:High-purity enzymes and active pharmaceutical ingredients require GMP compliance and documented strain lineage.
- Cosmetics:Fermented botanical extracts and postbiotic lysates penetrate premium skincare with microbiome-friendly positioning.
Established volume resides in Food & Beverages. Gaining share fastest in Cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg and Munich anchor European precision fermentation capacity, while biotech clusters in the United States and Asia-Pacific accelerate strain engineering scale-up for industrial enzyme and probiotic output.
Germany
Clean-label bakery reformulation and dairy alternative development drive demand for fermented antimicrobial metabolites and precision-fermented proteins. EFSA novel food assessments streamline safety documentation for fermentation-derived ingredients entering European formulations. The Hamburg-Munich corridor concentrates shared pilot facilities and strain engineering expertise that reduce R&D fixed costs for industrial biotechnology startups.
United States
FDA GRAS notification pathways and retailer ingredient blacklists push food and beverage manufacturers toward natural preservative systems and umami flavor replacements. EPA biofuel mandates and USDA bioeconomy programs redirect agricultural residue streams toward renewable fermentation feedstocks. The Greater Boston and San Francisco Bay Area clusters host venture-backed precision fermentation ventures targeting pharmaceutical-grade enzyme markets.
China
Domestic probiotic demand in nutritional supplements and functional beverages expands manufacturing capacity for high-CFU culture production. SAMR strain registration requirements and evolving genome-edited organism classifications impose parallel safety dossier burdens for multi-jurisdictional market access. The Yangtze River Delta concentration around Shanghai integrates contract fermentation services with downstream formulation capabilities for cosmetics and animal feed applications.
India
FSSAI functional food regulations and PLI scheme incentives for biotechnology manufacturing attract capital toward probiotic and enzyme production infrastructure. Traditional fermented dairy and beverage consumption patterns create established distribution channels for live culture products. The Maharashtra-Gujarat industrial corridor develops bulk organic acid and yeast extract capacity serving domestic processed food manufacturers and export markets.
Brazil
Poultry and swine integrators specify Bacillus-based spore formulations for tropical climate stability in animal feed probiotic applications. ANVISA regulatory harmonization efforts with FDA and EFSA frameworks reduce documentation duplication for imported strain libraries. The São Paulo-Minas Gerais axis concentrates fermentation-derived feed additive production aligned with integrated protein supply chains.
Fermented Ingredients Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fermented ingredients sector, with integrated biotechnology conglomerates maintaining captive strain libraries and fermentation infrastructure against specialized culture collection custodians and contract manufacturing organizations. The market structure concentrates around three archetypes: diversified chemical and nutrition conglomerates with backward integration into industrial biotechnology, dedicated yeast and bacteria culture suppliers with proprietary strain collections, and emerging precision fermentation ventures with asset-light platform technologies. M&A activity targets strain IP portfolios and regulatory dossier libraries, while capacity expansion focuses on continuous bioprocessing retrofits and single-use system deployments.
Among European-based biotechnology conglomerates, BASF and Kerry Group occupy positions spanning industrial enzyme supply and integrated fermentation-derived ingredient portfolios. Chr. Hansen anchors the specialized culture collection tier with live microbial strain libraries serving dairy and nutritional applications. These three entities exemplify divergent strategic postures: chemical conglomerate diversification, nutrition ingredient backward integration, and focused microbial expertise concentration.
| Leading Market Players |
|---|
| BASF |
| Angel Yeast |
| DuPont |
| Corbion |
| Lesaffre |
| Kerry Group |
| Chr. Hansen |
| Novozymes |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade enzyme procurement teams at European and North American biologics manufacturers anchor pricing power through value-based contracts tied to batch consistency specifications and documented strain lineage. This buyer concentration forces fermentation operators to absorb feedstock volatility rather than pass through cost swings, compressing margins on commodity-grade yeast extracts while preserving premium capture for precision-fermented bioactives.
Pricing Analysis
Yield-guaranteed pricing tied to enzymatic activity and purity certification anchors contract structures for pharmaceutical and nutritional applications. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated strains from food-grade bulk extracts and feed-grade commodities. Pricing pressure stems from corn and sugar cane cost volatility that strains thin-conversion economics for organic acid producers. Animal feed compounders in Brazil and Thailand exhibit highest price sensitivity, while cosmetics formulators in Germany accept premium positioning for carbon-verified postbiotic lysates.
Supply Chain Analysis
Glucose feedstock supply rests on Brazilian sugar cane and US corn belt production cycles, with agricultural residue streams emerging as alternative carbohydrate sources under EU Green Deal procurement mandates. Specialty enzyme production draws from German and Danish strain engineering clusters, while bulk yeast extract capacity concentrates in China and India. Single-source vulnerability around proprietary probiotic strain libraries held by Chr. Hansen and DuPont creates supply concentration risk for dairy manufacturers. Distribution runs through regional formulation hubs serving bakery, dairy, and cosmetics manufacturers with just-in-time cold-chain logistics for live cultures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing talent scarcity and extended validation timelines for legacy batch infrastructure retrofits constrain effective capacity expansion, propping pricing for pharmaceutical-grade fermentation outputs.
For Market Incumbents: Deepen backward integration into renewable feedstock sourcing to insulate margin structures from agricultural commodity volatility. Lock in exclusive licensing agreements with academic strain engineering programs before precision fermentation ventures commercialize competing platforms. Prioritize continuous bioprocessing retrofits in Hamburg and Munich facilities to defend throughput advantages against biotech-native entrants. For New Entrants and Emerging Players: Precision fermentation scale-up platforms offer the most penetrable wedge for specialized bioactive compounds serving cosmetics and personalized nutrition pipelines. Target direct-to-consumer probiotic formulations integrating gut microbiome testing, where regulatory burdens filter out established pharmaceutical players. Pursue EU Green Deal bioeconomy procurement mandates as guaranteed offtake channels bypassing retail concentration. For Investors and Strategic Acquirers: The window for entry favors asset-light strain engineering ventures with regulatory dossier libraries already submitted to EFSA or FDA. Long-term viability hinges on multi-jurisdictional strain registration capabilities spanning European, North American, and Asian approval pathways. Watch for SAMR genome-edited organism classification clarity as the signal triggering consolidation of Chinese precision fermentation assets.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Retrofit | Reduces labor intensity in high-wage European production environments while tightening batch consistency. |
| Renewable Feedstock Sourcing | Aligns with EU Green Deal procurement mandates and Scope 3 emissions documentation requirements. |
| Strain IP Portfolio Acquisition | Captures proprietary probiotic and enzyme-producing organisms locked behind exclusive licensing agreements. |
| Regulatory Dossier Expansion | Accelerates multi-jurisdictional market access across EFSA, FDA, and SAMR approval pathways. |
| Direct-to-Consumer Channel Launch | Bypasses mass-market retail concentration for personalized nutrition and microbiome-targeted formulations. |
Methodological Framework
Independent corroboration across fermentation plant managers, procurement leads at dairy and bakery manufacturers, regulatory affairs directors, and cosmetics formulators underwrites the qualitative findings. Secondary validation draws from EFSA novel food submission databases, FDA GRAS notification filings, REACH registration dossiers at ECHA, and EU customs trade data for fermentation-derived chemicals. Bottom-up strain-level production estimates triangulate against top-down category spending patterns reported by food and beverage manufacturers.
Rate-of-change decomposition across the analysis window isolates volume drivers from price mix effects, with segmentation modeling spanning product type, end-use application, physical form, and geographic production hub. CAGRs derive from fitted growth curves calibrated to historical capacity expansion timelines and regulatory approval velocity. Forecast inputs incorporate EFSA assessment pipeline backlogs, precision fermentation venture funding trajectories, and EU bioeconomy procurement mandate rollout schedules.
Several conditions sit outside the modeled scope, including unforeseen genome-edited organism classification reversals, biosecurity export control escalations, and feedstock crop failure events. Forecasts assume stable regulatory interpretation of fermentation-derived substances under REACH and ongoing strain engineering productivity gains. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Barley Malt Extract Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Textured Soy Flour Market
Ingredients
Specialty Flours Market
Ingredients
North America Vegetable Oils Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Rendered Products Market
Ingredients
Barley Flake Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Lentils Flour Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
North America Phytosterols Market
Ingredients
North America Potato Protein Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Europe Malt Ingredient Market