
 Hemophilia B Market | 2026-2036
Hemophilia B Market Size, Share, and Industry Trends Forecast 2026-2036
Hemophilia B Market Outlook
The EU Green Deal is broadening sustainability mandates across European pharmaceutical supply chains, pressuring manufacturers to reduce cold-chain carbon intensity in plasma-derived and recombinant biologics distribution. CSL Behring leverages vertically integrated plasma collection networks to sustain cost advantages in Factor IX concentrates. Novo Nordisk anchors its position through recombinant technology leadership, while uniQure competes with differentiated gene therapy platforms designed for single-administration hemophilia B correction.
Hemophilia B denotes an X-linked recessive bleeding disorder caused by deficient or defective clotting Factor IX, requiring either lifelong exogenous replacement or curative genetic intervention via adeno-associated viral vector delivery of functional F9 genes. Factor IX concentrates retain the largest revenue share due to established reimbursement and decades of clinical safety data, though gene therapy represents the fastest-growing segment as one-time administration promises elimination of prophylactic burden. Specialty pharmacies capture disproportionate margin pools by managing prior authorization, patient assistance programs, and cold-chain logistics for high-value biologics.
The FDA maintains stringent lot-release requirements for plasma-derived products under 21 CFR 640, while the EMA's MDR framework intensifies post-market surveillance obligations for gene therapy developers seeking CE marking. The EU F-Gas Regulation further constrains refrigeration choices in cross-border distribution, elevating compliance costs for temperature-sensitive biologics. Stakeholders must monitor evolving payer willingness to cover gene therapy premiums against background recombinant pricing benchmarks.
Market Dynamics
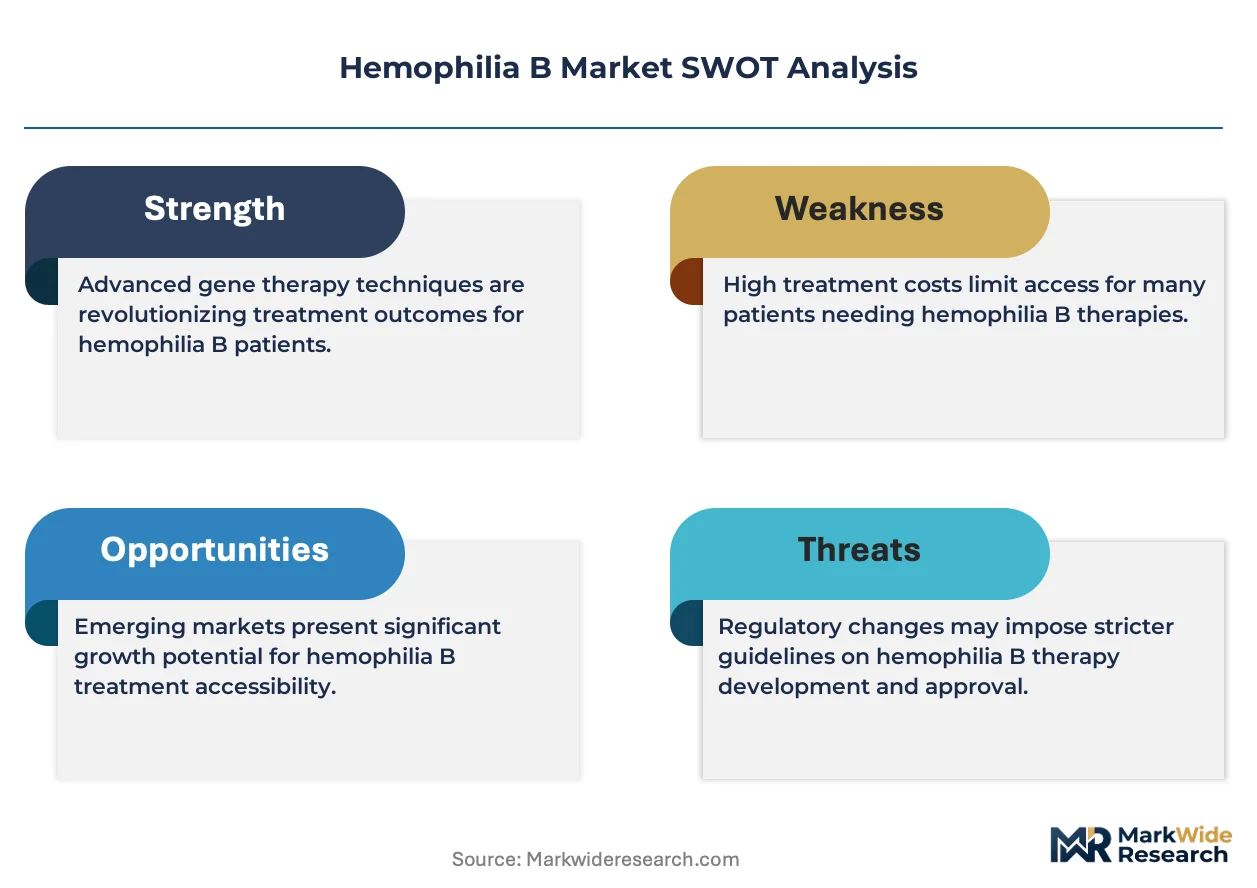
Gene therapy's emergence as a one-time curative intervention is compressing the traditional lifetime value model built on recurring Factor IX replacement, forcing manufacturers to defend recombinant franchises while building viral vector manufacturing capacity.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation and EMA's PRIME scheme compress development timelines for rare disease biologics, shortening patient access gaps.
- Specialty Pharmacy Networks:Hemophilia treatment centers coordinate integrated care models that streamline prior authorization and cold-chain delivery for high-value therapeutics.
- AAV Vector Manufacturing Scale-Up:Suspension-based bioreactor technology is displacing adherent cell culture, expanding viral yield per batch and reducing gene therapy cost of goods.
Market Restraints
- Plasma Supply Concentration:North American and European plasma collection networks dominate raw material supply for derived concentrates, exposing manufacturers to donor availability volatility.
- Gene Therapy Reimbursement Friction:Payer actuarial models struggle to amortize one-time curative premiums against lifetime prophylaxis benchmarks, creating access delays.
- F-Gas Refrigeration Constraints:The EU F-Gas Regulation limits hydrofluorocarbon use in cold-chain distribution, elevating compliance costs for temperature-sensitive biologics.
Strategic Opportunities
- Pediatric Gene Therapy Expansion:Regulatory frameworks for early-intervention AAV dosing in pre-liver-cirrhosis patients could extend addressable populations beyond adult cohorts.
- Outcome-Based Contracts:Payers and manufacturers are piloting annuity-style payment structures that distribute gene therapy costs across years contingent on sustained Factor IX expression.
- Biosimilar Factor IX Entry:Patent expirations on legacy recombinant products create white space for follow-on biologics to capture price-sensitive segments in emerging markets.
Industry Challenges
- Viral Vector Manufacturing Talent Scarcity:AAV upstream and downstream process development expertise concentrates in a limited pool of specialists, constraining capacity expansion timelines.
- Immunogenicity Management Complexity:Pre-existing neutralizing antibodies and T-cell responses to AAV capsids require patient stratification protocols that complicate clinical trial enrollment and commercial screening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemophilia B Market |
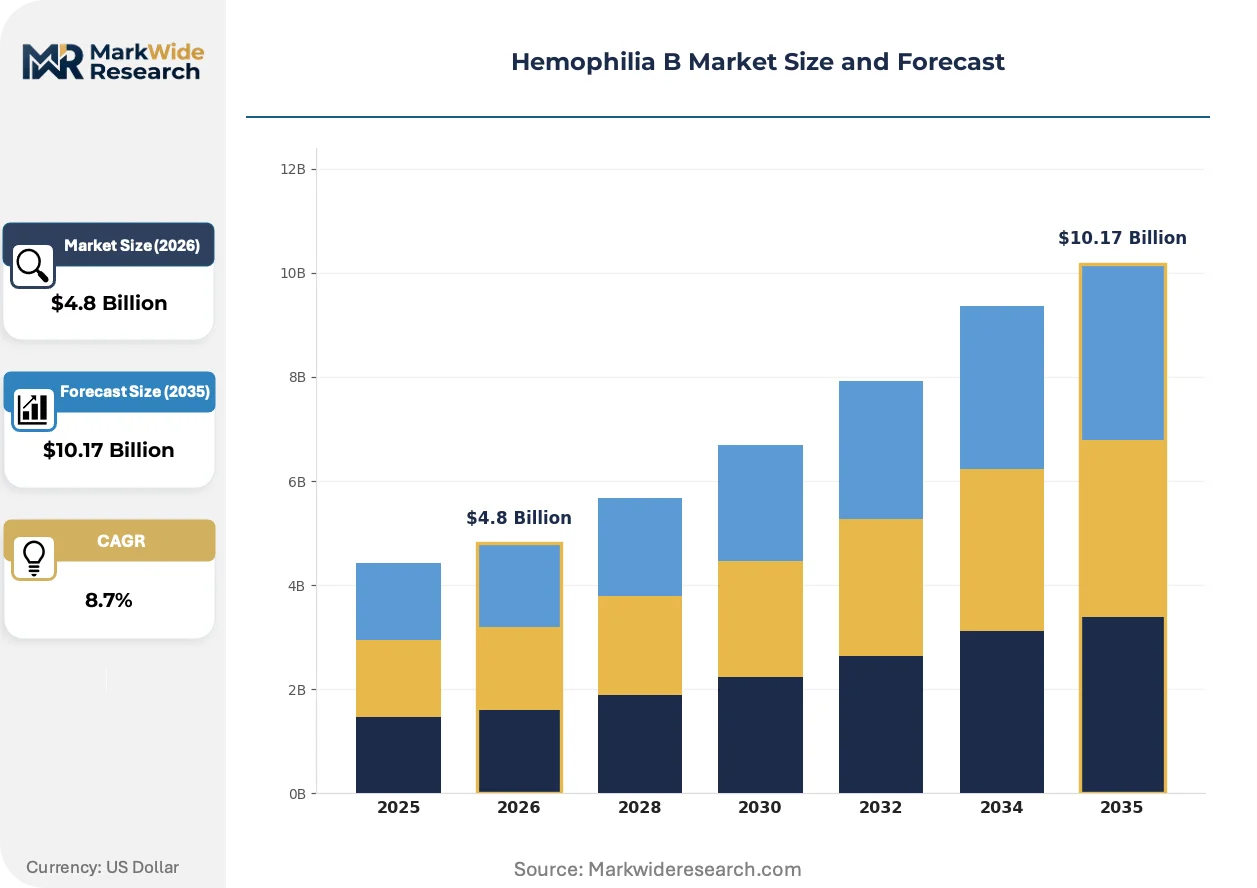
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Factor IX Concentrates, Gene Therapy, Monoclonal Antibodies, Prophylactic Treatment Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Pharmacies End User: Pediatric Patients, Adult Patients, Healthcare Professionals, Caregivers Therapeutic Area: Bleeding Disorders, Rare Diseases, Chronic Conditions, Genetic Disorders |
| Companies Covered | CSL Behring, Pfizer, Novo Nordisk, Bayer AG, F. Hoffmann-La Roche Ltd, Takeda Pharmaceutical Company, Sanofi, Spark Therapeutics, uniQure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemophilia B Market Strategic Shifts
Biologics distribution and patient management models are undergoing structural transformation as curative modalities displace chronic therapy paradigms, reshaping everything from manufacturing scale to reimbursement mechanics.
Extended half-life recombinant Factor IX fusion proteins are decentralizing prophylactic treatment from clinic-based infusions toward home administration protocols. Adult patients and caregivers are adopting subcutaneous and less frequent dosing regimens that reduce treatment center dependency. This shift is compressing site-of-care revenue pools while expanding pharmacy benefit management influence over therapy selection and adherence monitoring.
The EMA's Medical Device Regulation framework intensifies post-market surveillance obligations for combination products involving drug-device delivery systems. Manufacturers must maintain vigilance databases and periodic safety update reports that extend beyond traditional pharmaceutical obligations. Gene therapy developers seeking CE marking face expanded clinical follow-up requirements that prolong regulatory investment horizons.
Patient advocacy organizations are consolidating purchasing influence through specialized pharmacy benefit contracts that negotiate rebates and patient assistance programs directly with manufacturers. Hemophilia treatment centers in the United States are ceding formulary control to integrated delivery networks that centralize biologics procurement across multi-state systems. This concentration is visible most acutely in states with dominant academic medical center networks that aggregate rare disease patient volumes.
Hemophilia B Market Segmentation
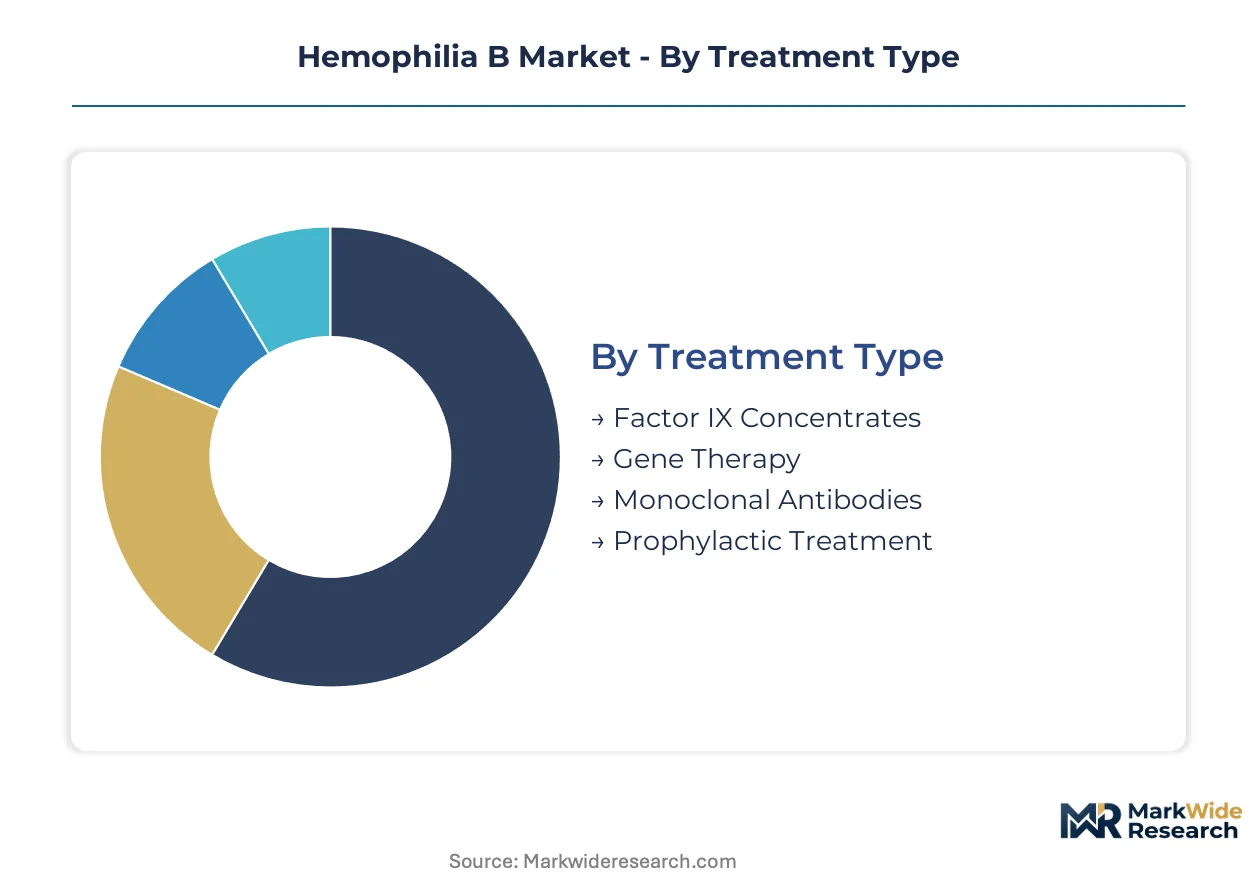
Segmentation in the Hemophilia B Market reflects divergent clinical pathways: lifelong prophylaxis versus one-time curative intervention. Each category captures distinct reimbursement mechanics, distribution infrastructure requirements, and patient stratification protocols that determine commercial viability.
Treatment Type:
Replacement-cycle dynamics dominate this dimension, with patients cycling between chronic Factor IX administration and irreversible gene therapy conversion.
- Factor IX Concentrates:Plasma-derived and recombinant formulations deliver exogenous clotting factor through intravenous infusion. Demand concentrates in the United States, where hemophilia treatment centers coordinate prophylactic regimens and FDA lot-release requirements under 21 CFR 640 ensure supply security.
- Gene Therapy:AAV5 and AAV8 vector platforms deliver functional F9 genes for sustained endogenous Factor IX expression. Adult patients in Germany and the United Kingdom are driving early adoption as EMA PRIME-designated products secure conditional marketing authorization.
- Monoclonal Antibodies:Bispecific constructs mimicking Factor VIIIa cofactor activity offer non-replacement hemostasis for inhibitor patients.
- Prophylactic Treatment:Scheduled infusion protocols prevent spontaneous bleeding episodes in severe hemophilia B phenotypes.
Factor IX Concentrates sits at the top of the volume ranking, with Gene Therapy climbing the fastest.
Distribution Channel:
Channel selection tracks therapy value density and cold-chain complexity, with high-cost biologics favoring controlled distribution networks.
- Specialty Pharmacies:Integrated models manage prior authorization, patient assistance programs, and temperature-controlled logistics for recombinant and gene therapy products. Margin pools concentrate in United States networks serving hemophilia treatment center referral systems.
- Hospital Pharmacies:Acute bleed management and surgical prophylaxis drive inpatient Factor IX dispensing.
- Retail Pharmacies:Extended half-life products enabling home administration expand community pharmacy participation.
- Online Pharmacies:Digital platforms facilitate refill coordination for stable prophylactic patients with established regimens.
Specialty Pharmacies commands the highest value throughput, with Hospital Pharmacies maintaining the deepest penetration in acute care settings.
End User:
Patient life-stage determines treatment modality eligibility, with gene therapy trials historically excluding pediatric cohorts due to liver immaturity considerations.
- Adult Patients:Established liver architecture and informed consent capacity position this cohort for AAV-mediated gene transfer. Clinical trial enrollment concentrates in academic medical centers across France, Italy, and Spain.
- Pediatric Patients:Early prophylaxis initiation prevents joint arthropathy, with recombinant extended half-life products enabling less frequent dosing.
- Healthcare Professionals:Hematologists, nurse coordinators, and infusion specialists guide therapy selection and adherence monitoring.
- Caregivers:Family members administer home-based prophylaxis for pediatric and adult dependent patients.
Adult Patients represents the primary addressable population for emerging curative modalities, with Pediatric Patients expanding most quickly as regulatory frameworks evolve for early intervention.
Therapeutic Area:
Classification systems determine orphan drug designation eligibility, accelerated approval pathways, and payer categorization for budget impact assessments.
- Rare Diseases:Hemophilia B's X-linked recessive inheritance and low prevalence trigger EMA orphan designation and FDA breakthrough therapy protocols. Reimbursement negotiations in the Netherlands and Belgium apply rare disease budget caps and outcome-based payment structures.
- Genetic Disorders:Monogenic etiology enables precise gene therapy targeting of the F9 locus.
- Bleeding Disorders:Coagulation cascade deficiency classification groups hemophilia B with hemophilia A and von Willebrand disease for treatment center specialization.
- Chronic Conditions:Lifelong management requirements distinguish hemophilia B from acute coagulopathies in healthcare resource planning.
Rare Diseases anchors regulatory and commercial strategy, with Genetic Disorders gaining classification prominence as gene therapy platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hematology nurses and gene therapy process engineers concentrate in Germany, the United States, and the United Kingdom, anchoring clinical trial execution and viral vector manufacturing capacity for hemophilia B interventions.
United States
Hemophilia treatment centers in Boston, Philadelphia, and Los Angeles coordinate the largest adult gene therapy enrollment cohorts worldwide. The FDA's breakthrough therapy designation compresses review timelines for AAV-based F9 gene delivery candidates. Manufacturing scale-up concentrates in Research Triangle Park, North Carolina, where suspension bioreactor facilities expand viral yield capacity.
Germany
Academic medical centers in Munich and Hamburg drive EMA PRIME-designated product adoption for severe hemophilia B phenotypes. The country's national pharmaceutical regulator, BfArM, coordinates with the EMA on conditional marketing authorizations for one-time curative therapies. Plasma collection networks in Bavaria sustain raw material supply for CSL Behring's recombinant Factor IX production.
United Kingdom
NHS England's specialized commissioning framework negotiates outcome-based contracts for gene therapy access, with treatment centers in London and Manchester piloting annuity-style payment structures. The MHRA's post-Brexit recognition pathway accelerates EMA-approved product availability. Cell and gene therapy manufacturing clusters in Stevenage and Oxfordshire expand AAV production infrastructure.
France
Reference centers in Paris and Lyon maintain Europe's highest per-capita hemophilia B patient registries, enabling long-term gene therapy follow-up protocols. ANSM intensifies pharmacovigilance requirements for viral vector products under the EU MDR framework. The Île-de-France region hosts contract development and manufacturing organizations supporting viral vector process development.
Japan
PMDA's sakigake designation system prioritizes review of gene therapies for rare bleeding disorders, with university hospitals in Tokyo and Osaka enrolling adult patients in sponsor-initiated trials. The Ministry of Health, Labour and Welfare's premium pricing scheme for innovative medicines accommodates one-time curative premiums. Yokohama's biotech corridor attracts AAV manufacturing investment from multinational sponsors.
Hemophilia B Market Competitive Environment
Capital-heavy plasma fractionators compete with asset-light gene therapy developers for hemophilia B revenue pools, creating a bifurcated competitive structure. The market consolidates around three strategic archetypes: vertically integrated plasma collectors with recombinant manufacturing capabilities, viral vector specialists pursuing one-time curative platforms, and diversified biopharmaceutical conglomerates with hybrid portfolios. Dominant competitive moves include backward integration into captive plasma supply and strategic partnerships bridging recombinant legacy franchises with gene therapy pipelines.
Within the plasma-derived and recombinant concentrate tier, CSL Behring and Takeda Pharmaceutical Company exemplify vertically integrated archetypes with controlled raw material sourcing. Among gene therapy specialists, uniQure and Spark Therapeutics occupy positions as viral vector platform developers targeting single-administration correction. Novo Nordisk sits between these categories, leveraging recombinant protein engineering leadership while building AAV manufacturing capabilities.
| Leading Market Players |
|---|
| CSL Behring |
| Pfizer |
| Novo Nordisk |
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Takeda Pharmaceutical Company |
| Sanofi |
| Spark Therapeutics |
| uniQure |
| Others |
Value Chain & Pricing Dynamics
Hemophilia treatment centers and integrated delivery networks in the United States concentrate purchasing power for high-value biologics, anchoring a value-based pricing model where one-time gene therapy premiums compete against amortized lifetime prophylaxis costs. This buyer concentration shapes manufacturer negotiation leverage and reimbursement contracting structures across North American and European markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates one-time AAV gene therapies from extended half-life recombinant products and legacy plasma-derived concentrates. Price differentiation hinges on clinical outcome durability and FDA breakthrough therapy designation status. Cost compression in the standard recombinant tier is intensifying because biosimilar entry and payer benchmarking against prophylactic lifetime costs. Pediatric patients and emerging market purchasers exhibit the highest price sensitivity, while adult severe phenotype patients in Germany and the United Kingdom demonstrate the lowest.
Supply Chain Analysis
EMA MDR certification and FDA 21 CFR 640 lot-release requirements gate entry for plasma-derived and recombinant biologics, constraining supplier bases to qualified facilities. Manufacturing concentrates in the United States, Germany, and Japan, with viral vector production anchored in North Carolina, Bavaria, and Yokohama biotech corridors. Raw material dependencies span human plasma collections, AAV5/AAV8 packaging cell lines, and suspension bioreactor media. Single-source vulnerability characterizes AAV upstream process development expertise. Distribution runs through specialty pharmacy networks coordinating cold-chain logistics to hemophilia treatment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hemophilia B represents a late-cycle quality story where gene therapy durability and recombinant half-life extension are reshaping procurement toward premium specifications with demonstrable outcome metrics. Payer willingness to absorb curative premiums depends on sustained Factor IX expression data.
For Market Incumbents: Hedge recombinant franchise erosion by building captive AAV manufacturing capacity in Research Triangle Park and Oxfordshire clusters while securing outcome-based contracts with NHS England and German sickness funds. Gene therapy reimbursement friction and viral vector talent scarcity threaten legacy revenue streams; backward integration into plasma collection sustains cost advantages in concentrates. For New Entrants and Emerging Players: The pricing gap between premium gene therapies and economy plasma-derived concentrates creates white-space opportunity in biosimilar recombinant Factor IX and pediatric AAV dosing protocols. Emerging markets in Spain and Italy offer the most penetrable geography given EMA centralized approval pathways. A go-to-market angle anchored in specialty pharmacy partnership bypasses hemophilia treatment center formulary gatekeeping. For Investors and Strategic Acquirers: Large-cap biopharmaceutical conglomerates with rare disease franchises are the most active acquirers in this space, targeting viral vector platform developers and extended half-life protein engineering capabilities. Long-term viability favors hybrid portfolios spanning recombinant legacy cash flows and gene therapy optionality. The signal to watch is EMA conditional marketing authorization conversion rates to full approval.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Manufacturing Scale-Up | Suspension bioreactor deployment in North Carolina expands viral yield capacity for uniQure and Spark Therapeutics pipeline candidates. |
| Outcome-Based Contracting | Annuity-style payment structures with NHS England distribute gene therapy costs contingent on sustained Factor IX expression thresholds. |
| Regulatory Approval Pathway | EMA PRIME designation accelerates conditional marketing authorization for severe hemophilia B phenotypes in Germany and France. |
| Backward Integration | CSL Behring's captive plasma collection networks in Bavaria and North America insulate raw material supply from donor availability volatility. |
| Pipeline Diversification | Novo Nordisk extends recombinant protein engineering leadership into AAV5 vector platforms for single-administration correction. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with regulatory affairs leads, formulary directors at integrated delivery networks, hemophilia treatment center coordinators, and viral vector manufacturing heads. Secondary validation draws from FDA filings, EMA assessment reports, ClinicalTrials.gov enrollment data, and NHS England specialized commissioning frameworks. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchor market size estimation.
Granularity-level modeling disaggregates revenue across treatment type, distribution channel, patient life-stage, and regional regulatory cluster throughout the forecast period. CAGRs derive from segment-level growth rate blending anchored to gene therapy adoption curves and recombinant biosimilar penetration assumptions. Forecast inputs incorporate AAV manufacturing capacity expansion timelines, payer budget impact assessment methodologies, and plasma collection network growth projections.
The model assumes a particular technology adoption path where AAV-mediated gene transfer achieves mainstream reimbursement; alternative pathways for non-viral gene editing or mRNA-based Factor IX expression would alter the outlook substantially. Forecasts reflect assumptions about EMA MDR compliance timelines and FDA breakthrough therapy conversion rates. Gene therapy immunogenicity rates and sustained expression durability present specific risk factors warranting sensitivity analysis. A model refresh is warranted upon material change in payer outcome-based contracting adoption or viral vector manufacturing cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market