
 Europe Aircraft Engines Market | 2026-2036
Europe Aircraft Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Engines Market Foresight
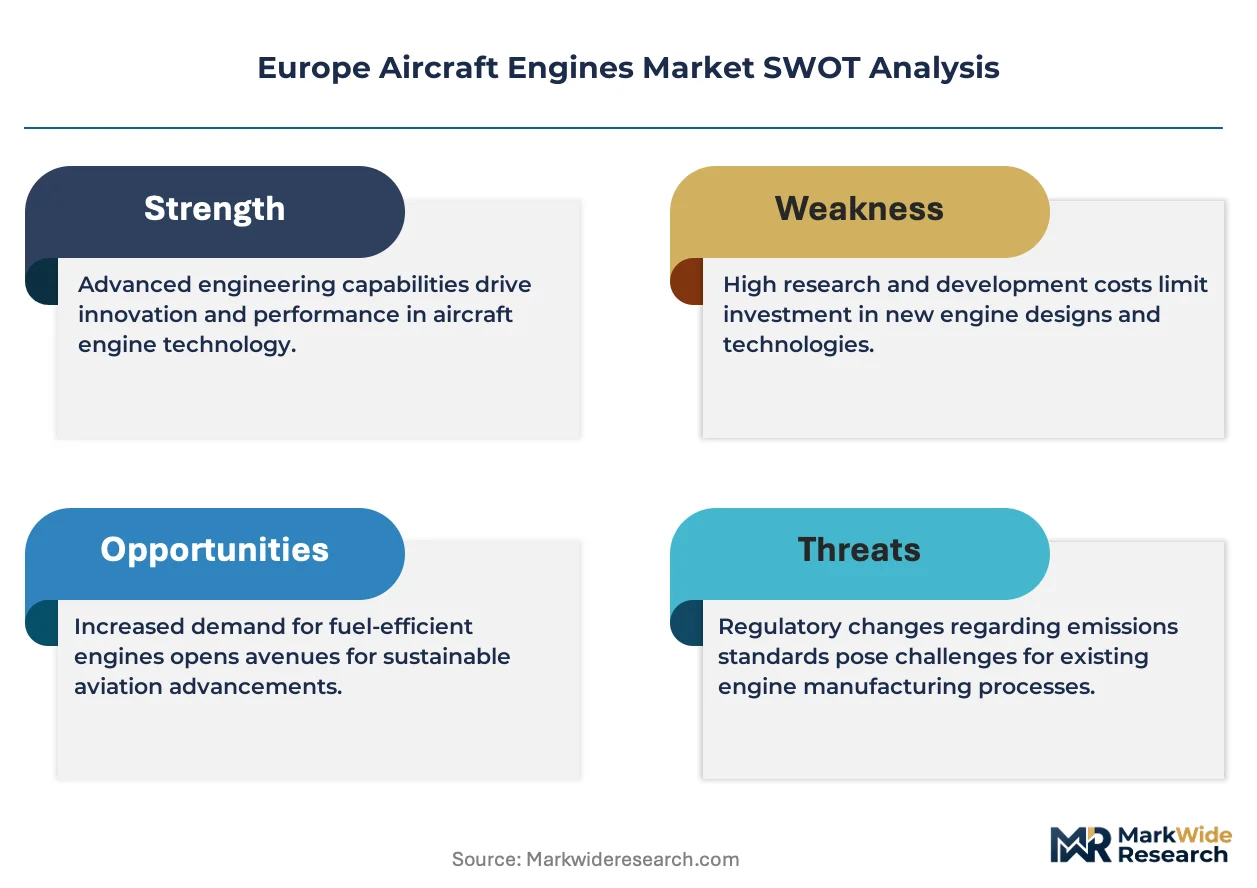
France is reshaping competitive dynamics in European aero-engine manufacturing through Safran SA's industrial expansion around Toulouse and Bordeaux. Rolls-Royce plc dominates wide-body propulsion through its Trent family, leveraging Derby-based test facilities and Derby assembly lines for aftermarket capture. MTU Aero Engines AG sustains its position via specialized high-pressure compressor modules, anchoring Munich as a precision manufacturing hub for geared turbofan architectures.
Aircraft engines are gas turbine powerplants that convert thermal energy into mechanical thrust through multi-stage compressors, combustors, and turbines operating at core temperatures exceeding 1,400°C. These systems propel fixed-wing aircraft across commercial, military, and general aviation missions where power-to-weight ratios and specific fuel consumption determine operational economics. Turbofan configurations lead European order books due to their bypass ratio advantages on medium-haul routes, while electric and hybrid technology segments attract venture funding for sub-regional aircraft below fifty seats. Conventional architectures still occupy the bulk of installed base hours, though margin pools are migrating toward advanced turbofan overhaul contracts.
EASA certification requirements and EU Green Deal aviation protocols are tightening NOx and CO2 thresholds, forcing OEMs to redesign combustor liners and introduce sustainable aviation fuel compatibility kits. REACH chemical regulations constrain coating materials and heat-resistant alloys, reshaping supplier qualification processes across the continent. Stakeholders must monitor how ETS carbon pricing for intra-European flights alters airline fleet renewal timelines and engine selection criteria.
Market Dynamics
EASA's tightened NOx and CO2 thresholds are forcing OEMs to redesign combustor architectures and accelerate sustainable aviation fuel compatibility programs across European production lines.
Growth Catalysts
- EU Green Deal aviation protocols:Mandates for carbon-neutral flight paths are pulling forward fleet renewal cycles among European network carriers. Airlines now prioritize next-generation turbofan acquisitions to meet binding emissions reduction timelines.
- France:Safran SA's industrial expansion around Toulouse and Bordeaux is anchoring continental production capacity and attracting precision manufacturing suppliers to southwestern France.
- Geared turbofan architectures:These powerplants deliver 15-20% fuel efficiency gains over conventional high-bypass designs, making them the default selection for narrow-body replacements on intra-European routes.
Market Restraints
- REACH chemical regulations:Constraints on coating materials and heat-resistant alloys are reshaping supplier qualification processes, extending development timelines for new engine programs by 18-24 months.
- Superalloy supply concentration:Critical nickel and titanium inputs depend on a concentrated supplier base, exposing OEMs to price volatility and geopolitical disruption risks in raw material sourcing.
- Technical limitation:Current battery energy density caps electric propulsion to sub-regional aircraft below fifty seats, blocking electrification from addressing medium-haul demand.
Strategic Opportunities
- Germany:Munich's precision manufacturing ecosystem around MTU Aero Engines AG offers entry points for specialized high-pressure compressor module production serving geared turbofan programs.
- Hybrid-electric architectures:Convergence of gas turbine cores with distributed electric propulsion is hybridizing sub-regional aircraft designs, creating white space for powerplant integrators.
- ETS carbon pricing:The EU Emissions Trading System's coverage of intra-European flights is accelerating airline fleet renewal timelines, expanding the addressable market for fuel-efficient engine retrofits.
Industry Challenges
- Turbine blade coating specialists:Scarce expertise in thermal barrier application and ceramic matrix composite processing is constraining production ramp rates for next-generation hot section components.
- EASA certification timelines:Extended validation periods for new combustor designs and emissions testing protocols are compressing program launch windows and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Engines Market |
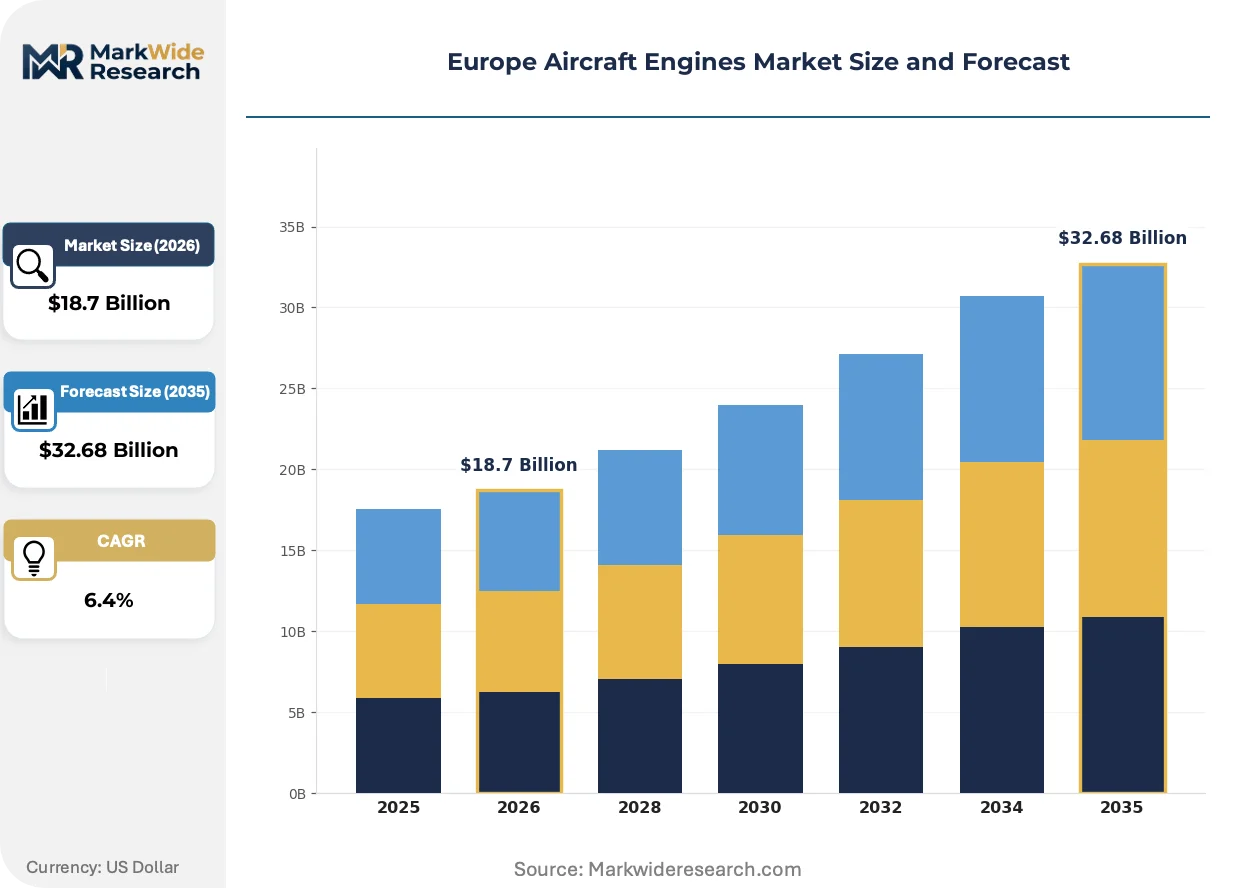
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbofan, Turboprop, Turbojet, Piston Technology: Hybrid, Electric, Advanced Turbofan, Conventional End User: Commercial Aviation, Military Aviation, Cargo Carriers, Business Aviation Application: Short Haul, Long Haul, Regional Transport, General Aviation |
| Companies Covered | Safran SA, Rolls-Royce plc, Pratt & Whitney, General Electric Company, MTU Aero Engines AG, CFM International, Rostec, Honeywell International Inc., United Engine Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Engines Market Shifts & Advancements
Propulsion technology is converging with digital monitoring systems and alternative fuel architectures, reshaping how European OEMs design, manufacture, and service powerplants across the product lifecycle.
Hybrid-electric propulsion systems are hybridizing sub-regional aircraft platforms by combining gas turbine generators with distributed electric fans. Regional carriers operating routes under 500 nautical miles are piloting these configurations to reduce fuel burn and noise footprints. This architecture is compressing the traditional turboprop market while opening new segments for power electronics and thermal management suppliers.
REACH regulations are constraining coating chemistries and heat-resistant alloy formulations used in turbine hot sections. OEMs must reformulate thermal barrier systems and requalify suppliers under ECHA substance restrictions, adding development cost and timeline risk. High-pressure compressor module production in Germany and France faces the most acute material substitution pressures.
Airlines are unbundling engine maintenance from airframe leases and pursuing power-by-the-hour contracts directly with OEM service arms. Lessor and operator procurement teams now negotiate availability guarantees separate from aircraft financing, shifting margin pools toward aftermarket service networks. This pattern concentrates in France and the United Kingdom where Rolls-Royce and Safran have built captive MRO infrastructure.
Europe Aircraft Engines Market Segmentation
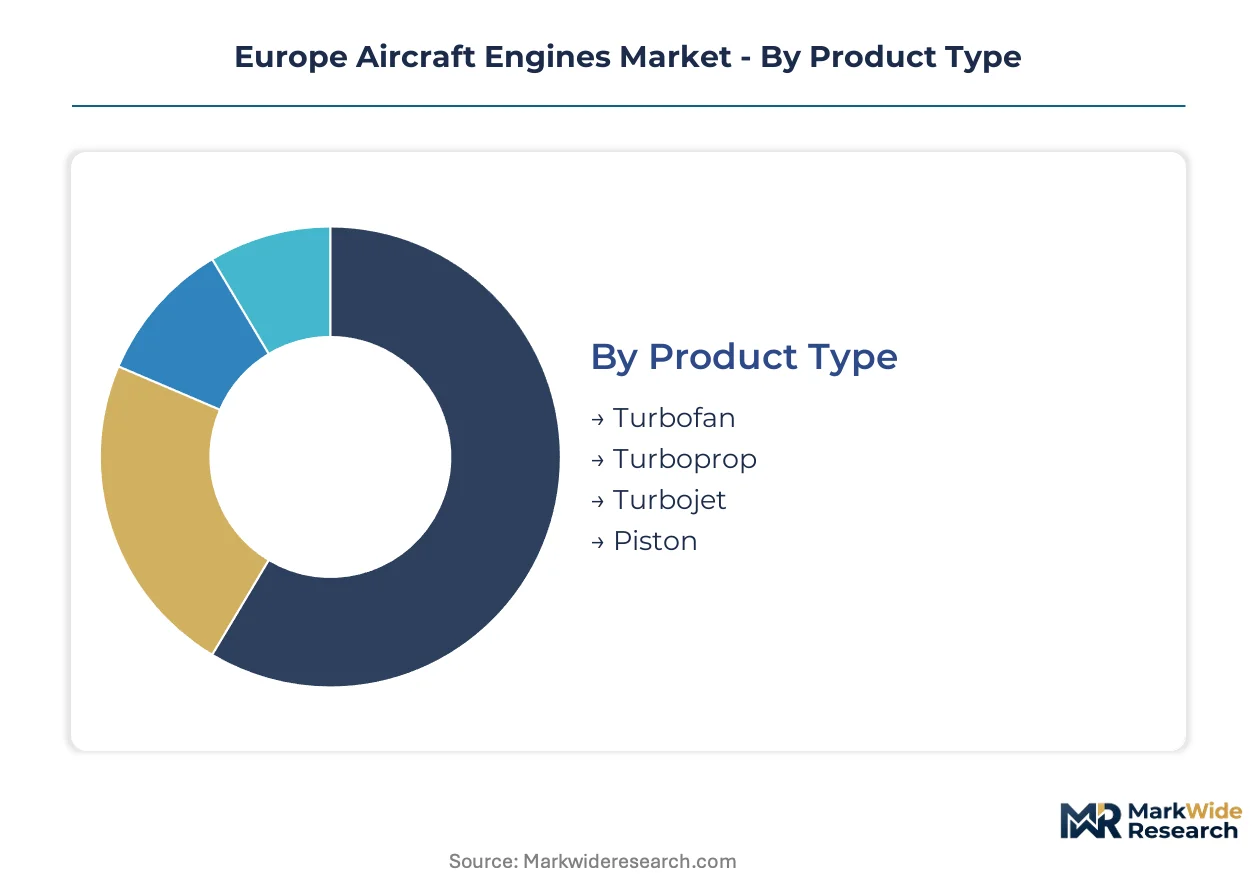
Engine architecture choices determine fuel efficiency, maintenance economics, and regulatory compliance across European fleet renewal cycles. Segmentation reveals how technology maturity, mission profiles, and operator business models concentrate procurement decisions and aftermarket revenue pools.
Product Type:
Cost tier differentiation separates high-thrust wide-body powerplants from regional and general aviation alternatives with distinct manufacturing scales and margin structures.
- Turbofan:High-bypass architectures dominate European narrow-body and wide-body fleets with core temperatures exceeding 1,400°C. Demand concentrates among French and UK network carriers refreshing A320neo and A350 fleets under EU Green Deal timelines. EASA emissions certification for next-generation combustor designs extends development cycles.
- Turboprop:Geared powerplants serve regional routes under 500 nautical miles with superior short-field performance. Operators in Germany and Scandinavia favor these configurations for thin point-to-point markets where jet economics fail. Cold-climate operational reliability anchors procurement decisions.
- Turbojet:Pure jet configurations persist in military trainer and light combat aircraft with simplified maintenance footprints. Select NATO air forces retain these platforms for pilot transition programs.
- Piston:Reciprocating engines power European general aviation and flight training infrastructure with certified avgas and emerging unleaded alternatives. French and German flying clubs sustain installed base hours.
Turbofan commands the established base. The steepest expansion runs through turboprop architectures serving regional connectivity mandates.
Technology:
Maturity gradients separate field-proven architectures from developmental platforms attracting venture capital and government clean-aviation funding.
- Hybrid:Gas turbine generators paired with distributed electric fans are hybridizing sub-regional designs below fifty seats. Munich and Toulouse engineering clusters host power electronics integration programs. Battery energy density constraints limit range to under 500 nautical miles.
- Electric:Battery-electric propulsion serves urban air mobility and training aircraft with zero direct emissions. French and German regulators are developing certification frameworks for commercial operations. Energy storage weight penalties restrict payload-range economics.
- Advanced Turbofan:Geared architectures with ultra-high bypass ratios deliver 15-20% fuel efficiency gains over previous generation designs. Rolls-Royce and Safran production lines in Derby and Toulouse prioritize these powerplants for A320neo and A330neo backlogs.
- Conventional:Legacy high-bypass turbofans sustain installed base operations through overhaul and retrofit programs. Aftermarket service networks in the United Kingdom and France capture residual margin from mature fleet segments.
Conventional technology commands the established base. The steepest expansion runs through advanced turbofan architectures.
End User:
Customer type determines procurement volume, financing structure, and aftermarket contract terms across European aviation.
- Commercial Aviation:Network carriers in France, Germany, and the United Kingdom drive narrow-body and wide-body engine demand with power-by-the-hour service agreements. EU ETS carbon pricing accelerates fleet renewal timelines for intra-European operations.
- Military Aviation:NATO allies are accelerating engine refresh programs for fighter and transport fleets with sovereign maintenance requirements. UK and French defense procurement channels favor domestic supply chains.
- Cargo Carriers:Express freight operators prioritize engine durability and time-on-wing metrics over passenger comfort specifications. Leipzig and Cologne cargo hubs influence regional engine selection.
- Business Aviation:Corporate operators and charter fleets demand dispatch reliability and residual value preservation. Swiss and Austrian business aviation clusters sustain premium engine service demand.
Commercial aviation commands the established base. The steepest expansion runs through military aviation refresh programs.
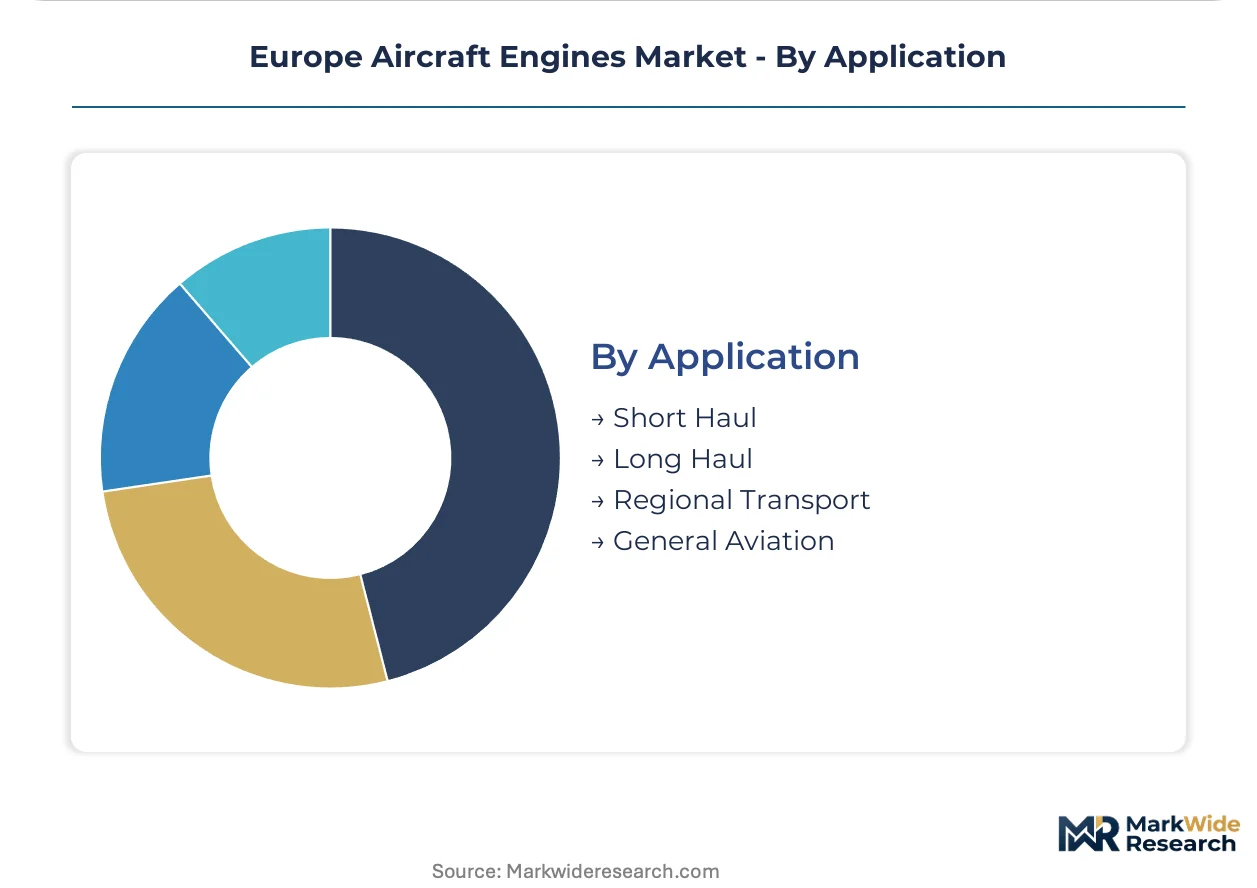
Application:
Mission range and frequency profiles segment engine duty cycles, overhaul intervals, and technology requirements.
- Short Haul:High-cycle operations on routes under 1,000 nautical miles demand rapid climb performance and quick-turn reliability. European low-cost carriers dominate this segment with narrow-body turbofan fleets.
- Long Haul:Extended-range twin-engine operations require ETOPS-certified powerplants with thermal management for 12+ hour missions. Rolls-Royce Trent installations on A350 and 787 fleets anchor this category.
- Regional Transport:Thin-route economics favor turboprop and small turbofan configurations with lower trip costs. French and Italian island connectivity routes sustain demand.
- General Aviation:Private and training operations utilize piston and small turboprop engines with simplified maintenance protocols. German and UK flight schools sustain installed base activity.
Short haul commands the established base. The steepest expansion runs through regional transport applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA certification requirements anchor France as the dominant geography, with Toulouse and Bordeaux clusters driving continental production capacity for next-generation turbofan architectures.
France
Safran SA's industrial expansion around Toulouse and Bordeaux anchors continental production capacity for geared turbofan architectures. EU Green Deal aviation protocols mandate carbon-neutral flight paths, pulling forward fleet renewal cycles among Air France-KLM and regional carriers. The Toulouse aerospace cluster attracts precision manufacturing suppliers for high-pressure compressor module production.
United Kingdom
Rolls-Royce plc dominates wide-body propulsion through Derby-based test facilities and assembly lines capturing aftermarket service contracts. UK defense procurement channels favor domestic supply chains for NATO fighter engine refresh programs. The Derby engineering cluster sustains captive MRO infrastructure for Trent family powerplants.
Germany
MTU Aero Engines AG sustains its position via specialized high-pressure compressor modules, anchoring Munich as a precision manufacturing hub. REACH chemical regulations constrain coating materials and heat-resistant alloys, reshaping supplier qualification processes. The Munich engineering ecosystem hosts power electronics integration programs for hybrid-electric architectures.
Italy
Leonardo's supply chain relationships sustain regional turboprop demand for island connectivity routes under 500 nautical miles. EASA's tightened NOx thresholds force combustor redesigns affecting Italian MRO providers serving Mediterranean operators. The Pomigliano d'Arco cluster specializes in small turbofan maintenance for thin-route economics.
Spain
Iberia's fleet renewal timelines accelerate demand for fuel-efficient narrow-body powerplants on intra-European routes. ETS carbon pricing for intra-European flights alters engine selection criteria for Madrid-based network carriers. The Madrid-Barajas maintenance hub captures aftermarket volume from Latin American connecting traffic.
Europe Aircraft Engines Market Competitive Landscape
Full-service OEMs and specialized module suppliers split the market between integrated propulsion system providers and component-focused precision manufacturers. The vendor base concentrates around three strategic archetypes: vertically integrated engine developers, risk-sharing module specialists, and aftermarket service capturers. Consolidation pressures favor M&A activity among tier-two suppliers, while capacity expansion concentrates in southwestern France and the English Midlands.
Within the integrated OEM tier, Safran SA and Rolls-Royce plc exemplify full-system developers with captive manufacturing and service networks spanning continental Europe. MTU Aero Engines AG occupies a specialized position as a risk-sharing partner for high-pressure compressor modules in geared turbofan programs. These three anchors represent distinct competitive vectors: French industrial expansion, UK aftermarket capture, and German precision manufacturing specialization.
| Leading Market Players |
|---|
| Safran SA |
| Rolls-Royce plc |
| Pratt & Whitney |
| General Electric Company |
| MTU Aero Engines AG |
| CFM International |
| Rostec |
| Honeywell International Inc. |
| United Engine Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in French high-pressure compressor module production is compressing supplier margins while concentrating pricing power among Rolls-Royce and Safran captive service networks. EASA certification delays extend program timelines, forcing tier-two suppliers to absorb financing costs that OEMs pass through as availability guarantees in power-by-the-hour contracts.
Pricing Analysis
Geographic price spreads between Derby-based Trent overhaul facilities and Toulouse geared turbofan service centers reflect divergent labor cost structures and captive parts availability. Three-tier pricing structure across premium OEM-direct, standard authorized service, and economy third-party MRO levels segments airline procurement teams by fleet age and residual value sensitivity. Price differentiation hinges on EASA certification tier and bundled thermal management system warranties. Cost compression in standard-tier compressor blade recoating is intensifying because REACH-compliant material substitutions extend turnaround times. Low-cost carriers with narrow-body fleets exhibit highest price sensitivity; business aviation operators with residual value concerns show lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days among French and German OEMs are squeezing working capital for ceramic matrix composite suppliers and thermal barrier coating applicators. Superalloy supply concentrates in France, the United Kingdom, and Germany, with nickel and titanium feedstock drawing from concentrated mining jurisdictions. Critical inputs include single-crystal turbine blades, high-pressure compressor forgings, and ceramic matrix composite preforms. Single-source vulnerability in Russian-origin titanium sponge exposes OEMs to forced material substitution under REACH substance restrictions. Distribution runs through captive OEM logistics networks and authorized distributor channels serving MRO facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in thermal barrier coating application expertise and ceramic matrix composite processing capability is constraining production ramp rates for next-generation hot section components. OEMs and suppliers must prioritize skill development and equipment investment to capture margin pools migrating toward advanced turbofan overhaul contracts.
For Market Incumbents: Insulate core aftermarket revenue by deepening backward integration into thermal barrier coating application and ceramic matrix composite processing in Derby and Toulouse facilities. Accelerate certification investment for sustainable aviation fuel compatibility kits to preempt regulatory displacement of legacy combustor architectures. Vertical integration into high-pressure compressor module production anchors margin capture as tier-two suppliers face REACH-driven qualification delays. For New Entrants and Emerging Players: Establish a beachhead in hybrid-electric power electronics integration serving sub-regional aircraft below fifty seats, where battery energy density constraints block incumbent turbofan dominance. Target Munich and Toulouse engineering clusters for power module assembly partnerships with MTU and Safran technology licensing programs. White space exists in thermal management system supply for distributed electric propulsion architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across geared turbofan high-pressure compressor module production as REACH compliance extends development timelines. Long-term viability favors suppliers with demonstrated EASA certification track records and captive relationships with Rolls-Royce or Safran production lines. Acquisition target archetype: tier-two thermal barrier coating specialists with ceramic matrix composite processing capability and established aerospace customer relationships. Monitor ETS carbon price levels as inflection signal for airline fleet renewal acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | Captures margin migrating from tier-two suppliers facing REACH material substitution pressures. |
| Sustainable Aviation Fuel Compatibility Certification | Secures EASA approval for next-generation combustor designs ahead of EU Green Deal enforcement timelines. |
| Hybrid-Electric Power Electronics Partnership | Positions suppliers for distributed propulsion architectures serving sub-regional routes under 500 nautical miles. |
| Captive MRO Infrastructure Expansion | Concentrates aftermarket revenue as airlines unbundle engine maintenance from airframe leases. |
| Ceramic Matrix Composite Processing Scale-Up | Addresses production bottlenecks in next-generation turbine blade manufacturing for geared turbofan programs. |
Research Methodology
A spread of perspectives from engine program directors, EASA certification leads, airline procurement managers, MRO operations heads, and thermal systems engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EASA type certificate databases, EU emissions trading registry filings, OEM annual disclosures, and aerospace supplier customs records. Bottom-up segment sizing triangulated against top-down fleet projection models derived from airline order backlogs and retirement schedules.
Demand-supply balance dynamics across the projection horizon anchored analytical framework development, with segmentation modeling across engine architecture, technology maturity tier, end-user procurement structure, and application duty cycle. CAGRs emerged from installed base hour projections, fleet renewal timelines, and aftermarket contract value migration patterns. Forecast inputs incorporated REACH substance restriction implementation schedules and ETS carbon price trajectory assumptions.
Sensitivities concentrate around EASA certification timeline extensions, superalloy supply disruption events, and airline fleet renewal acceleration or deferral decisions. Forecasts reflect documented assumptions regarding EU Green Deal enforcement pacing and sustainable aviation fuel blending mandate adoption. Macroeconomic contraction, regulatory timeline compression, or breakthrough battery energy density improvement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Fighter Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Latin America General Aviation Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Helicopter Lighting Market
Aircraft
Evtol Aircraft Market
Aircraft
Aircraft Door Market