
 Asia-Pacific Helicopters Market | 2026-2036
Asia-Pacific Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Helicopters Market Outlook
Buyer concentration among Asia-Pacific defense ministries is repositioning procurement toward multi-role platforms with dual civilian-military utility. Airbus Helicopters leverages its H225M supply chain across Southeast Asian air forces to sustain long-term service contracts. Hindustan Aeronautics Limited anchors India's rotorcraft indigenization through the Light Utility Helicopter program. Korea Aerospace Industries competes in the Surion family segment with manufacturing scale focused on domestic military requirements and export variants.
Helicopters are rotary-wing aircraft generating lift through powered rotors, with turbine engines typically delivering 500 to 3,000 shaft horsepower and main rotor diameters spanning 8 to 18 meters depending on payload class; they serve critical functions where fixed-wing runway access proves unavailable or impractical. Light Helicopters occupy the dominant volume position across Asia-Pacific due to cost accessibility for civilian operators in tourism and training roles, while Heavy Helicopters capture concentrated margin pools in offshore energy logistics where payload-range requirements exclude smaller alternatives. Attack Helicopters represent a structurally constrained but strategically defended segment, with national security protocols limiting foreign supplier access in several regional markets.
Japan's METI enforces airworthiness certification standards that shape product entry timelines for imported rotorcraft, while India's DGFT export-import controls and Defence Acquisition Procedure localization thresholds directly determine market access for foreign OEMs. Australia's Civil Aviation Safety Authority mandates stringent maintenance intervals for emergency services fleets, elevating aftermarket service revenue intensity for incumbent suppliers. Stakeholders must monitor how evolving military-civil dual-use classification protocols across regional regulators alter competitive positioning for multi-mission platform sales.
Market Dynamics
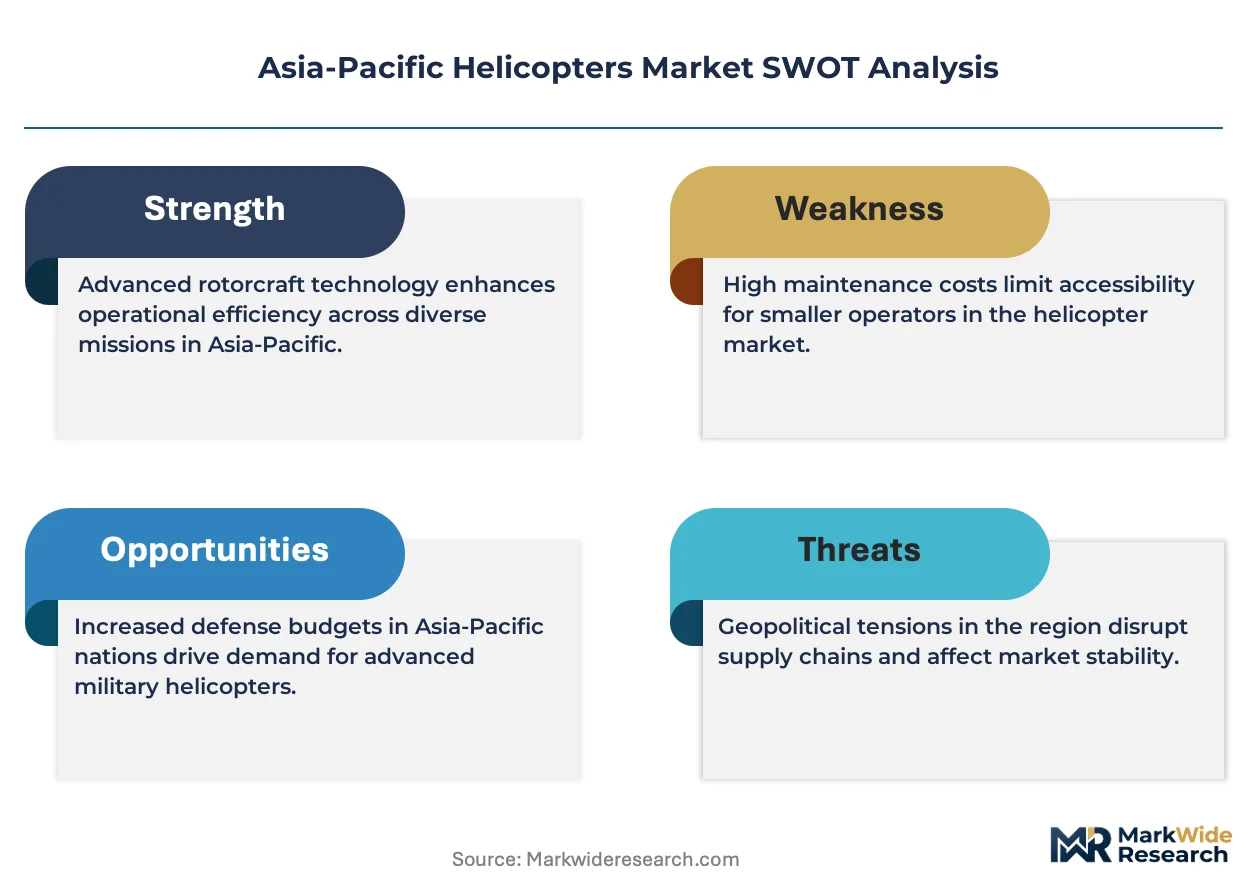
Deepwater offshore energy expansion across Southeast Asian basins is concentrating demand for heavy-lift rotorcraft with extended range capabilities, while India's Defence Acquisition Procedure localization mandates are restructuring supplier access for military platforms.
Growth Catalysts
- Offshore Crew Transfer Mandates:Australia's offshore safety regulator now requires twin-engine redundancy for personnel transport to installations beyond 50 nautical miles from shore.
- India's Indigenization Push:The Defence Acquisition Procedure 2020 mandates minimum 50 percent domestic content for rotorcraft procurement, redirecting foreign OEM partnerships toward licensed production.
- Aerial Firefighting Contracts:State governments in Victoria and New South Wales are consolidating aerial suppression fleets under multi-year service agreements.
Market Restraints
- Turbine Engine Supply Concentration:Safran and Pratt & Whitney Canada control 80 percent of turboshaft supply for light and medium helicopters, creating input bottlenecks.
- Airworthiness Certification Timelines:Japan's METI type certification process extends 18-24 months for new rotorcraft variants, delaying product entry.
- Fixed-Wing Drone Substitution:Long-endurance unmanned aerial systems are displacing light helicopters in pipeline surveillance and agricultural spraying missions.
Strategic Opportunities
- Vietnam's Offshore Licensing Round:Block awards in the Nam Con Son basin will require new crew transfer capacity for deepwater drilling campaigns.
- Urban Air Mobility Convergence:Electric vertical take-off and landing platforms are creating certification pathways that helicopter operators can leverage for infrastructure access.
- Emergency Medical Service Expansion:Indonesia's healthcare decentralization program is funding helicopter-based patient transfer networks across the archipelago.
Industry Challenges
- Airframe Maintenance Technician Shortage:Australia's Civil Aviation Safety Authority reports 30 percent vacancy rates in rotary-wing maintenance organizations.
- Military-Civil Dual-Use Classification Complexity:India's DGFT export-import controls create compliance friction for platforms with configurable mission systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Helicopters Market |
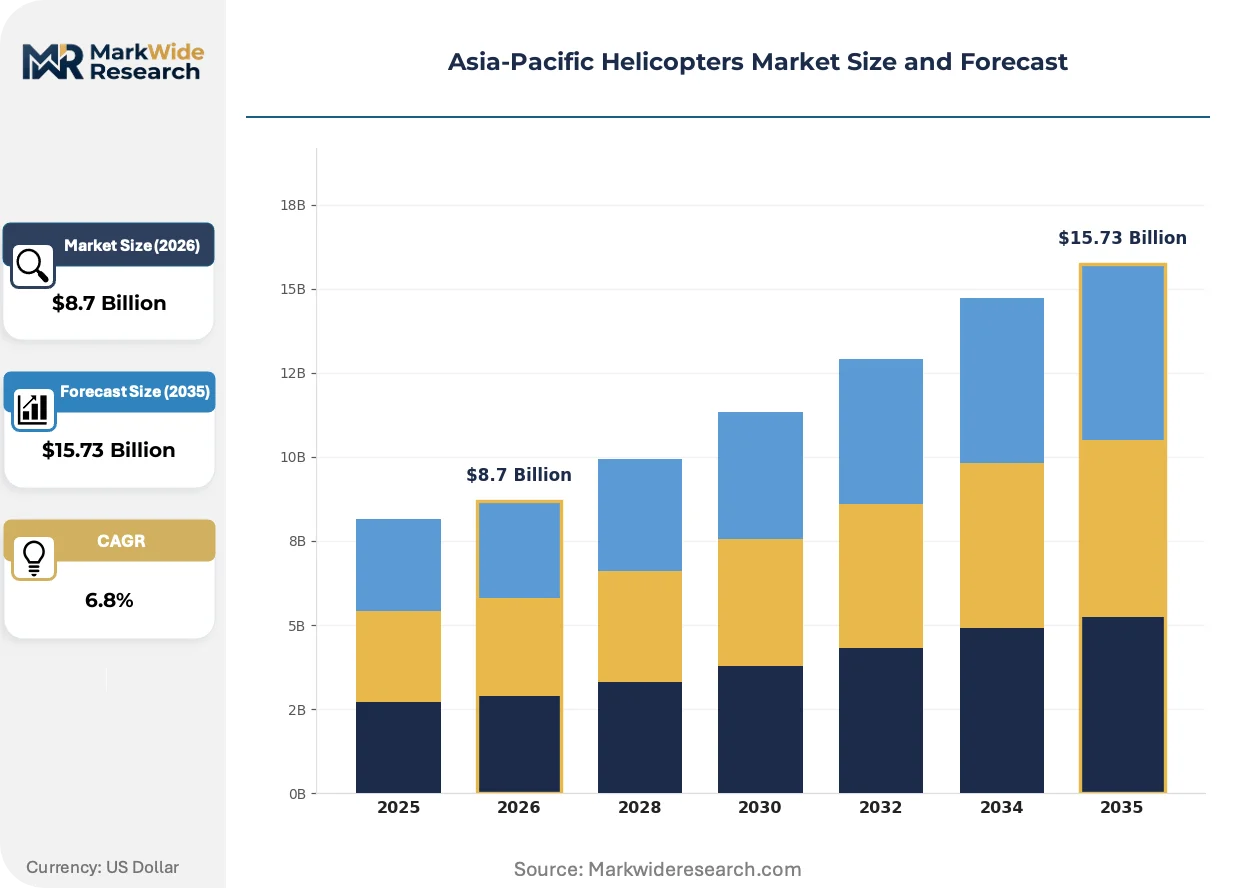
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Attack Helicopters End User: Military, Civilian, Emergency Services, Transport Operators Technology: Traditional Rotor, Fly-by-Wire, Autonomous Systems, Hybrid Technology Application: Search & Rescue, Law Enforcement, Medical Evacuation, Tourism |
| Companies Covered | Airbus Helicopters, Leonardo S.p.A., Textron Inc., Lockheed Martin Corporation, The Boeing Company, Hindustan Aeronautics Limited, Aviation Industry Corporation of China, Kawasaki Heavy Industries, Korea Aerospace Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Helicopters Market Strategic Shifts
Helicopter technology trajectories in Asia-Pacific are bifurcating between incremental efficiency gains in conventional turboshaft platforms and disruptive propulsion architectures that threaten to resegment the market by mission radius.
Hybrid-electric propulsion is converging with advanced rotorcraft design to extend mission endurance without sacrificing payload capacity. Offshore operators in Australia's Bass Strait are piloting systems that reduce fuel burn by 15 percent on crew transfer routes. This convergence is compressing the operational cost gap between light twins and single-engine turbines for medium-range missions.
India's DGFT localization thresholds under the Defence Acquisition Procedure are forcing foreign OEMs to restructure supply chains around domestic component sourcing. The policy requires indigenization audits at prototype and production stages. Military rotorcraft procurement is responding through joint ventures with Hindustan Aeronautics Limited for final assembly and subsystem integration.
Service contracting is displacing asset ownership across Australia's emergency services sector. State fire agencies now procure firefighting hours rather than leasing or owning helicopter fleets. Queensland and Western Australia have adopted this model, transferring maintenance liability and utilization risk to specialist operators while retaining mission control.
Asia-Pacific Helicopters Market Segmentation
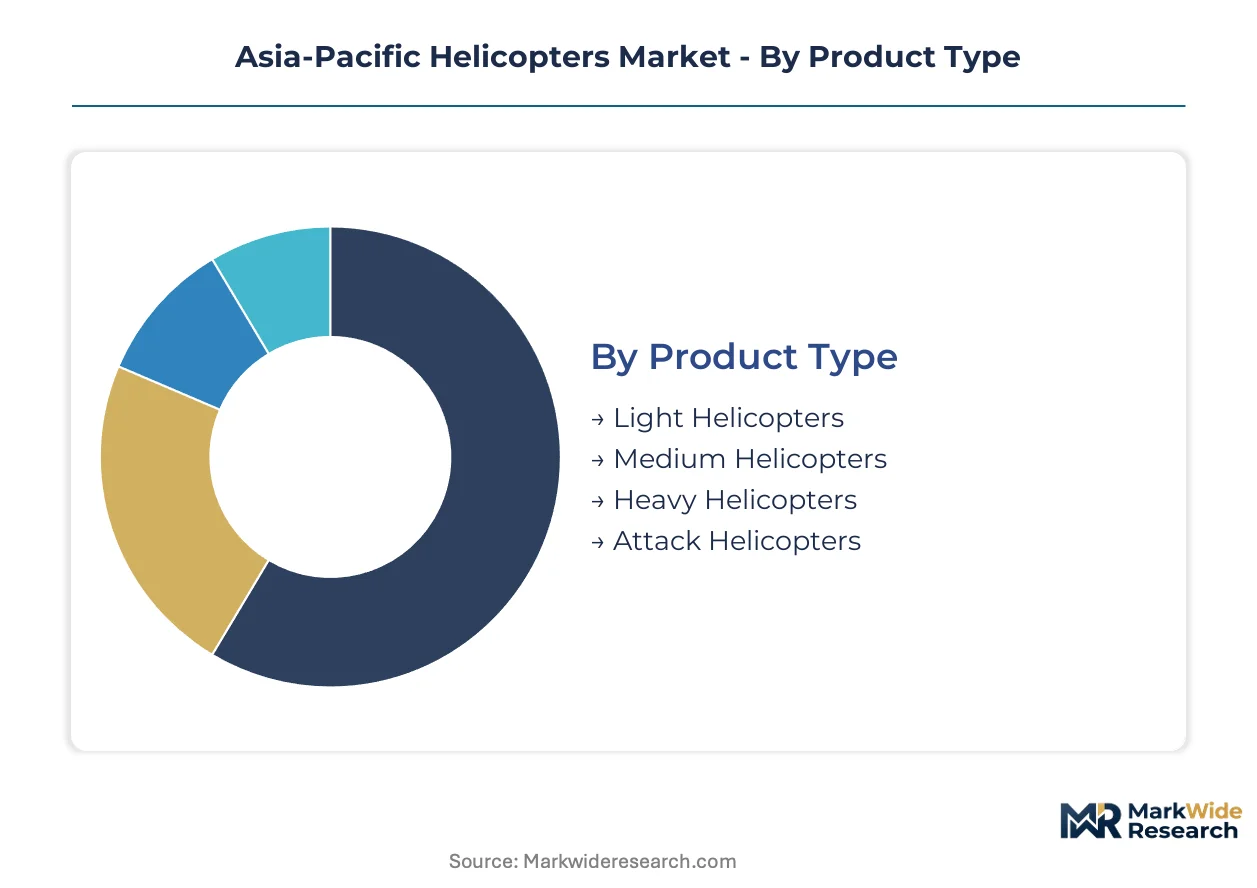
Segmentation in the Asia-Pacific helicopters market reveals how payload class, mission profile, and technology maturity create distinct competitive arenas. Procurement patterns diverge sharply between civilian operators prioritizing operating economics and defense ministries demanding multi-role configurability.
Product Type:
Standalone platforms dominate fleet counts, while embedded mission systems within heavier airframes command premium pricing through integrated avionics suites.
- Light Helicopters:Single and twin-turbine configurations under 3,175 kilograms maximum takeoff weight serve flight training schools and private charter operators. Australia's tourism corridors around the Great Barrier Reef and New Zealand's alpine regions concentrate civilian demand for sightseeing configurations.
- Heavy Helicopters:Rotorcraft exceeding 9,000 kilograms MTOW with twin-engine redundancy carry 19+ passengers or external sling loads exceeding 4,500 kilograms. India's offshore oil fields in the Mumbai High basin and Vietnam's Nam Con Son developments drive fleet expansion for crew transfer to deepwater platforms beyond 50 nautical miles from shore.
- Medium Helicopters:Intermediate payload platforms bridge utility and transport roles with 5,000-9,000 kilograms MTOW.
- Attack Helicopters:Armored gunship configurations with integrated weapons management systems serve national defense requirements.
Volume placements concentrate in Light Helicopters; the faster expansion belongs to Heavy Helicopters.
End User:
Cost tier stratification separates military procurement with indigenization mandates from civilian operators focused on hourly operating economics.
- Military:Defense ministries procure multi-role platforms under strict localization thresholds. India's Defence Acquisition Procedure mandates 50 percent domestic content, redirecting foreign OEM partnerships toward licensed production with Hindustan Aeronautics Limited.
- Emergency Services:State-funded aerial firefighting and medical evacuation fleets operate under performance-based contracts. Victoria and New South Wales governments in Australia now procure firefighting hours rather than owning assets, transferring maintenance liability to specialist operators.
- Civilian:Private operators in tourism, corporate transport, and agricultural spraying segments prioritize acquisition cost and fuel efficiency.
- Transport Operators:Commercial charter and scheduled helicopter services connect remote communities and resource extraction sites.
Contract value aggregates in Military; Emergency Services are climbing the fastest as Australian state agencies consolidate fleets under multi-year agreements.
Technology:
Application maturity separates field-proven mechanical systems from developmental architectures still navigating certification pathways.
- Traditional Rotor:Mechanical flight control linkages with hydraulically boosted manual inputs dominate installed fleet hours. Southeast Asian militaries and Australian civil operators rely on these systems for maintainability in austere environments.
- Hybrid Technology:Combined turboshaft and electric propulsion architectures reduce fuel burn on medium-range missions. Offshore operators in Australia's Bass Strait pilot systems achieving 15 percent consumption reduction on crew transfer routes.
- Fly-by-Wire:Digital flight control systems with envelope protection improve handling in degraded visual environments.
- Autonomous Systems:Reduced-crew and optionally-piloted configurations remain in experimental deployment for cargo resupply.
Installed base concentrates in Traditional Rotor; Hybrid Technology is gaining share fastest through offshore energy sustainability mandates.
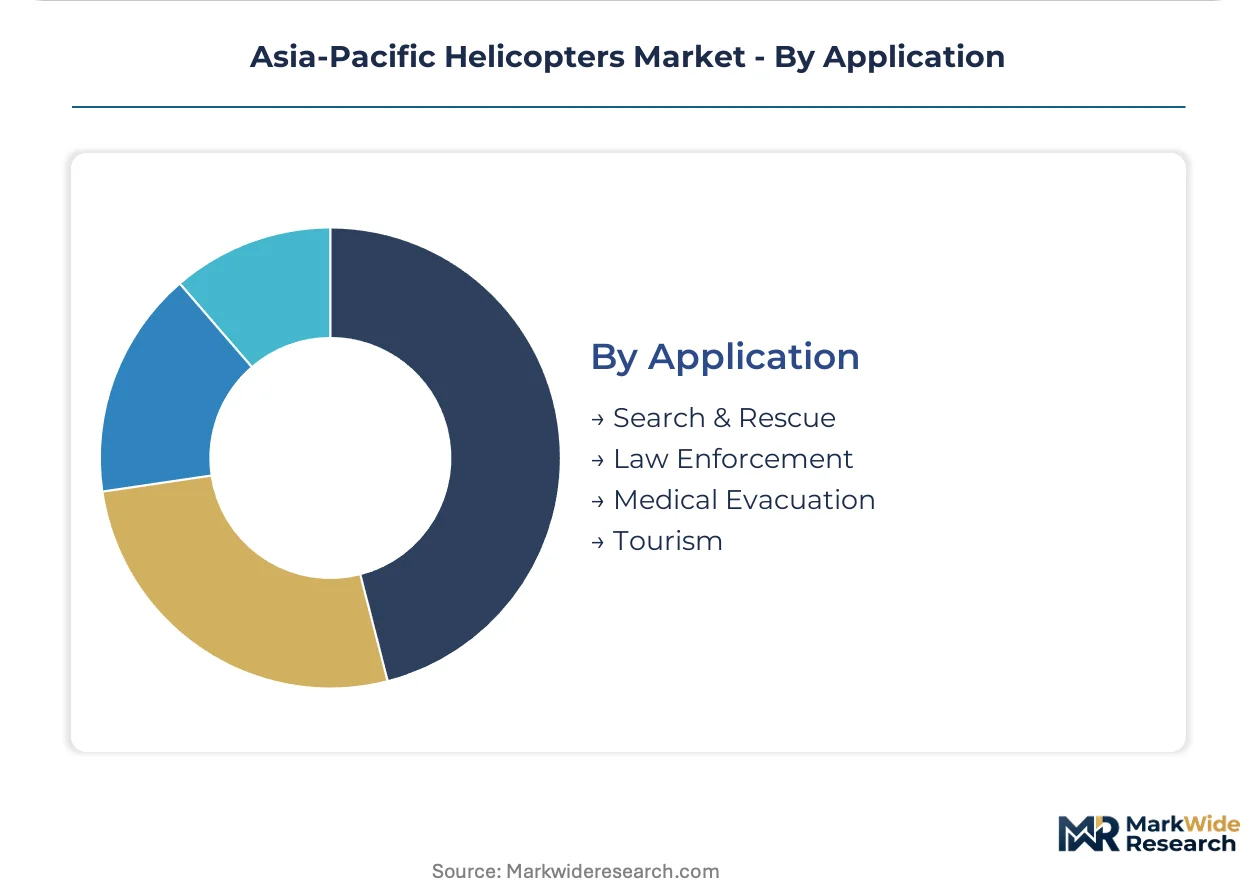
Application:
Geography shapes mission requirements, with archipelagic nations prioritizing range and continental markets emphasizing payload flexibility.
- Medical Evacuation:Helicopter emergency medical services require rapid launch capability and cabin configurations for intensive care transport. Indonesia's healthcare decentralization program funds patient transfer networks across the archipelago, connecting provincial hospitals.
- Search & Rescue:All-weather capability with winch-equipped cabins serves maritime and alpine environments. Japan's island territories and Australia's extensive coastline drive specialized fleet requirements.
- Law Enforcement:Surveillance and tactical transport configurations support border patrol and counter-narcotics operations.
- Tourism:Scenic flights and heli-skiing operations demand panoramic cabin visibility and noise certification for sensitive environments.
Flight hours concentrate in Medical Evacuation; Search & Rescue shows the steepest expansion trajectory as Pacific nations extend territorial coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement and offshore energy logistics concentrate demand across the Asia-Pacific, with national indigenization mandates and crew transfer safety regulations reshaping supplier access and fleet composition.
India
The Defence Acquisition Procedure 2020 mandates 50 percent domestic content for military rotorcraft, redirecting foreign OEM partnerships toward licensed production with Hindustan Aeronautics Limited. DGFT export-import controls create compliance friction for platforms with configurable mission systems. Bengaluru anchors India's rotorcraft indigenization through the Light Utility Helicopter program.
Australia
State governments in Victoria and New South Wales are consolidating aerial suppression fleets under multi-year service agreements, procuring firefighting hours rather than owning assets. The Civil Aviation Safety Authority mandates stringent maintenance intervals for emergency services fleets. Offshore safety regulators now require twin-engine redundancy for personnel transport beyond 50 nautical miles from shore.
Japan
METI enforces airworthiness certification standards that extend 18-24 months for new rotorcraft variants, delaying product entry timelines. Island territories drive specialized search and rescue fleet requirements with all-weather winch-equipped cabins. Tokyo's regulatory framework shapes competitive positioning for multi-mission platform sales.
South Korea
Korea Aerospace Industries competes in the Surion family segment with manufacturing scale focused on domestic military requirements and export variants. National security protocols limit foreign supplier access for attack helicopter procurement. Seoul's defense industrial base supports rotorcraft final assembly and subsystem integration capabilities.
Vietnam
Block awards in the Nam Con Son basin will require new crew transfer capacity for deepwater drilling campaigns beyond 50 nautical miles from shore. Offshore licensing rounds are concentrating demand for heavy-lift rotorcraft with extended range capabilities. Ho Chi Minh City serves as the logistics hub for energy sector fleet expansion.
Asia-Pacific Helicopters Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electric propulsion and autonomous flight architectures. The vendor base spans consolidated European-American OEMs with integrated global supply chains alongside state-backed Asian fabricators serving domestic military requirements. Three archetypes dominate: legacy full-line manufacturers with certified product families, national champions operating under indigenization mandates, and technology ventures advancing hybrid-electric configurations. Competitive moves concentrate on strategic partnerships for localized assembly and technology licensing to satisfy domestic content thresholds.
Within the legacy full-line tier, Airbus Helicopters and Leonardo S.p.A. exemplify established positioning through extensive certified product portfolios and long-term service contract penetration across Southeast Asian air forces. Hindustan Aeronautics Limited occupies the national champion archetype, anchoring India's rotorcraft indigenization through licensed production partnerships and domestic final assembly capabilities.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Leonardo S.p.A. |
| Textron Inc. |
| Lockheed Martin Corporation |
| The Boeing Company |
| Hindustan Aeronautics Limited |
| Aviation Industry Corporation of China |
| Kawasaki Heavy Industries |
| Korea Aerospace Industries |
| Others |
Value Chain & Pricing Dynamics
Turboshaft engine procurement costs cascade through three distinct pricing tiers, with Safran and Pratt & Whitney Canada supplying powerplants that anchor premium positioning for heavy-lift platforms while light-turbine alternatives compete on hourly operating economics. India's DGFT localization mandates under the Defence Acquisition Procedure force foreign OEMs to absorb domestic sourcing premiums, compressing margins on military contracts even as they secure long-term fleet positions.
Pricing Analysis
Volume placements concentrate in Light Helicopters where acquisition costs dominate buyer decisions; Heavy Helicopters capture concentrated margin pools through payload-range performance that excludes smaller alternatives. Price differentiation separates platforms by certification grade and after-sales service bundling, with Australia's Civil Aviation Safety Authority maintenance mandates elevating lifecycle cost premiums for emergency services fleets. Cost compression in the light-turbine segment is intensifying because fixed-wing drone substitution is eroding agricultural spraying and pipeline surveillance missions. Civilian tourism operators exhibit highest price sensitivity, while defense ministries prioritize multi-role configurability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with French and Canadian turboshaft suppliers controlling critical propulsion inputs for the majority of regional fleet capacity. Airframe assembly draws from Japan's precision manufacturing cluster, South Korea's aerospace industrial base, and India's licensed production facilities under HAL partnerships. Supply chain risk centers on regulatory restriction, with Japan's METI certification timelines extending 18-24 months for new rotorcraft variants and India's DGFT export-import controls creating compliance friction for configurable mission systems. Distribution runs through OEM-direct military procurement channels, specialist leasing operators in Australian emergency services, and tourism fleet aggregators across Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific helicopters market functions as a cost-of-compliance arena where India's Defence Acquisition Procedure 50 percent domestic content threshold constructs a barrier-to-entry moat for foreign OEMs willing to absorb localization investment. Compliant players secure multi-decade fleet positions; non-compliant suppliers face systematic exclusion from defense procurement pipelines.
For Market Incumbents: Anticipate electric vertical take-off and landing platform certification pathways compressing the operational cost gap for medium-range missions, eroding the light-twin helicopter advantage in crew transfer routes. Backward integration into avionics and mission system supply chains reduces exposure to India's DGFT import control friction, while expanding service contract penetration across Southeast Asian air forces locks in aftermarket revenue streams against emerging technology substitution.
For New Entrants and Emerging Players: Enter via Indonesia's healthcare decentralization program funding helicopter-based patient transfer networks across the archipelago, where state-funded procurement prioritizes service reliability over brand heritage. Australia's consolidated aerial firefighting contracts present the most penetrable segment for specialist operators willing to assume maintenance liability under performance-based hour-procurement models. A go-to-market angle centered on hybrid-electric fuel burn reduction aligns with offshore energy sustainability mandates in the Bass Strait.
For Investors and Strategic Acquirers: Vietnam's Nam Con Son basin block awards triggering deepwater drilling campaigns is the leading indicator that heavy-lift crew transfer capacity will face structural shortage. Long-term viability favors platform-agnostic service operators with contracted revenue visibility over airframe manufacturers exposed to procurement cycle volatility. Acquisition targets should display established maintenance organization credentials under Australia's Civil Aviation Safety Authority jurisdiction, with contracted hour-procurement relationships replacing asset-heavy fleet ownership models.
| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Production Partnership | India's HAL joint ventures satisfy Defence Acquisition Procedure localization thresholds for military rotorcraft procurement. |
| Hybrid-Electric Technology Pilot | Australia's Bass Strait operators validate 15 percent fuel burn reduction on offshore crew transfer routes. |
| Performance-Based Service Contract | Victoria and New South Wales state agencies transfer maintenance liability to specialist operators under multi-year agreements. |
| Avionics Backward Integration | OEM control over mission systems reduces compliance friction from India's DGFT export-import classification protocols. |
| Emergency Medical Network Expansion | Indonesia's healthcare decentralization funds patient transfer infrastructure across provincial hospital networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving fleet operations directors at offshore energy contractors, rotary-wing maintenance organization leads under Australia's Civil Aviation Safety Authority jurisdiction, defense procurement officers at India's Ministry of Defence, and tourism fleet managers across Southeast Asian markets. Secondary sources included DGFT export-import control notifications, METI airworthiness certification databases, Defence Acquisition Procedure amendment circulars, and customs records of turboshaft engine imports. Bottom-up fleet enumeration by operator and airframe combined with top-down market sizing through OEM delivery disclosures.
Segment-level modeling tracked payload class, mission profile, end-user category, and technology maturity across the projection horizon. Light, medium, and heavy helicopter categories were modeled separately with divergent replacement cycle assumptions. Military procurement flows incorporated indigenization threshold compliance timelines, while civilian segments reflected hour-procurement contract conversion rates in Australian emergency services. CAGRs were derived from fleet expansion requirements tied to offshore licensing rounds, healthcare infrastructure programs, and defense modernization budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory reclassification of military-civil dual-use platforms or accelerated electric vertical take-off and landing certification disrupting medium-range helicopter economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aeronautic Propeller Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Light Electric Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Evtol Aircraft Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Firefighting Aircraft Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Air Speed Indicator Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Helicopter Flight Control Systems Market