
 Digital Height Gauges Market | 2026-2036
Digital Height Gauges Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Height Gauges Market Insights
The capital-intensity divergence between integrated sensor manufacturers and assembly-focused distributors is reorganizing competitive tiers in digital height gauges. Mitutoyo leverages captive semiconductor fabrication for encoder chips to sustain margin control across its electronic gauge lines. Hexagon anchors its position through software-integrated metrology platforms that extend hardware functionality into quality-management systems. Mahr competes by specializing in sub-micron resolution units for medical device manufacturers in Southern Germany.
A digital height gauge is a precision vertical measuring instrument incorporating a linear encoder or capacitive sensor to capture dimensional deviations, typically resolving to 0.01 mm or finer. These devices serve primarily as shop-floor verification tools in machined-part acceptance, tool presetting, and geometric tolerance inspection within manufacturing quality systems. Electronic technology variants command the dominant share of current revenue due to proven reliability in coolant-heavy environments, while laser-based configurations represent the fastest-expanding segment as optical displacement sensors displace contact probes in non-destructive turbine-blade measurement. The calibration application category carries concentrated margin pools because accredited service contracts generate recurring revenue streams that offset cyclical equipment purchases.
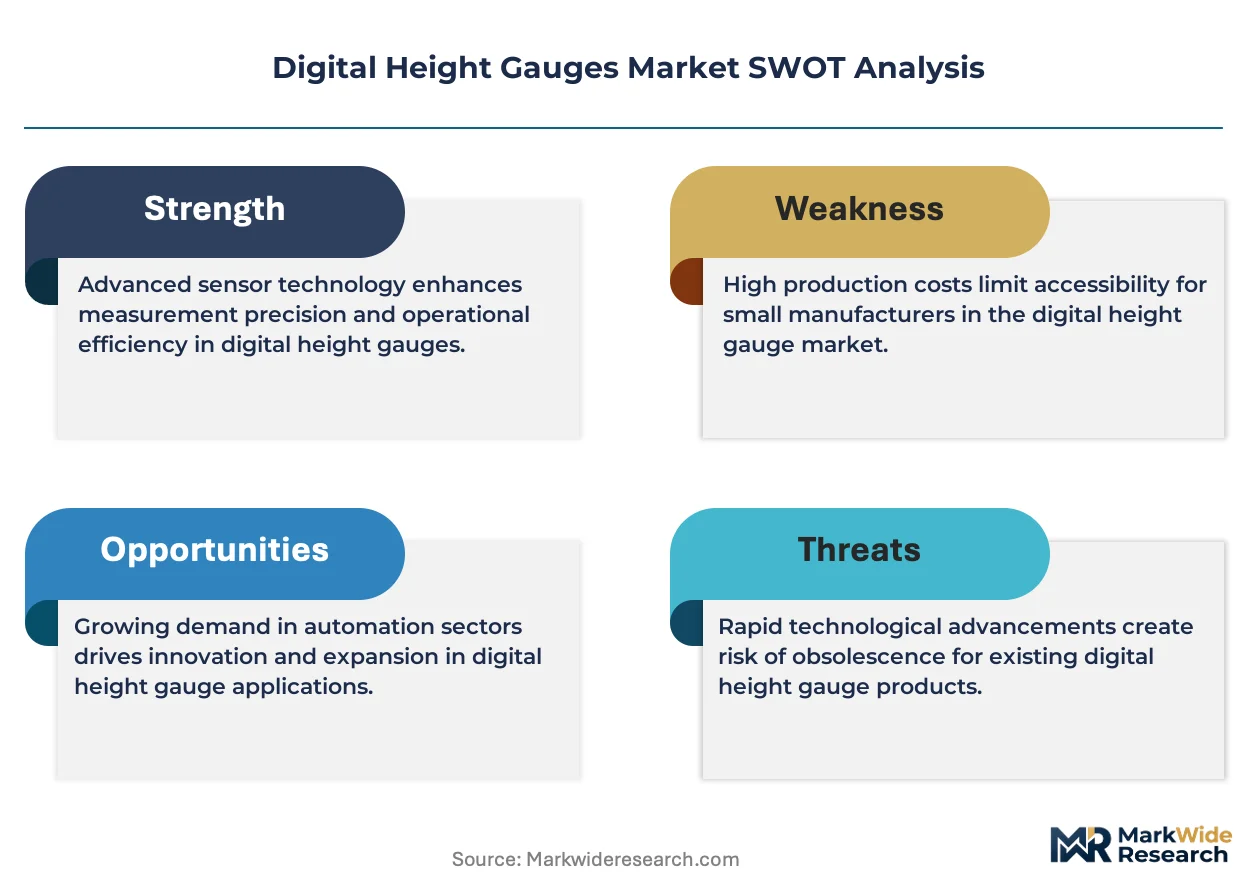
ISO 17025 accreditation requirements from national standards bodies in Germany, Japan, and the United States compel manufacturers to maintain traceable calibration chains that elevate replacement demand for certified digital height gauges. The EU Machinery Directive and CE marking obligations further shape product design by mandating electromagnetic compatibility and operator safety interlocks on electromechanical variants. Stakeholders must monitor how NIST and PTB evolve their documentary standards for digital dimensional measurement, as revised uncertainty budgets could render existing gauge architectures non-compliant before typical replacement cycles conclude.
Market Dynamics
Encoder chip supply concentration among Japanese semiconductor foundries is compressing lead times for mid-tier gauge manufacturers while ISO 17025 recalibration mandates in Germany and Japan force replacement cycles faster than typical equipment depreciation schedules.
Growth Catalysts
- ISO 17025 mandates:Accreditation requirements from Germany's PTB and Japan's JIS compel aerospace and medical device manufacturers to maintain traceable calibration chains, elevating replacement demand for certified units.
- Medical device precision requirements:Sub-micron resolution specifications for orthopedic implant machining in Southern Germany drive specification upgrades among contract manufacturers.
- Optical displacement sensors:Laser-based configurations are penetrating non-destructive turbine-blade measurement applications previously served by contact probes.
Market Restraints
- Encoder chip supply concentration:Captive semiconductor fabrication capacity at integrated sensor manufacturers limits component availability for assembly-focused distributors.
- Calibration infrastructure costs:Accredited laboratory investment requirements create fixed-cost barriers for service providers seeking ISO 17025 certification.
- Electromagnetic compatibility compliance:EU Machinery Directive testing protocols extend product development timelines for electromechanical variants.
Strategic Opportunities
- South Korean precision machining corridors:Shipbuilding and semiconductor equipment manufacturers in Gyeonggi Province demonstrate unmet demand for software-integrated metrology platforms.
- Additive manufacturing quality verification:Post-process inspection requirements for metal 3D-printed aerospace components create application expansion potential.
- Cloud-connected calibration tracking:Remote monitoring capabilities align with NIST's evolving documentary standards for digital dimensional measurement traceability.
Industry Challenges
- Dimensional metrology technician scarcity:Specialized calibration expertise shortages constrain service capacity expansion among independent laboratories.
- Legacy quality management system integration:Hardware-software interoperability gaps complicate deployment of connected gauge architectures in established machining facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Height Gauges Market |
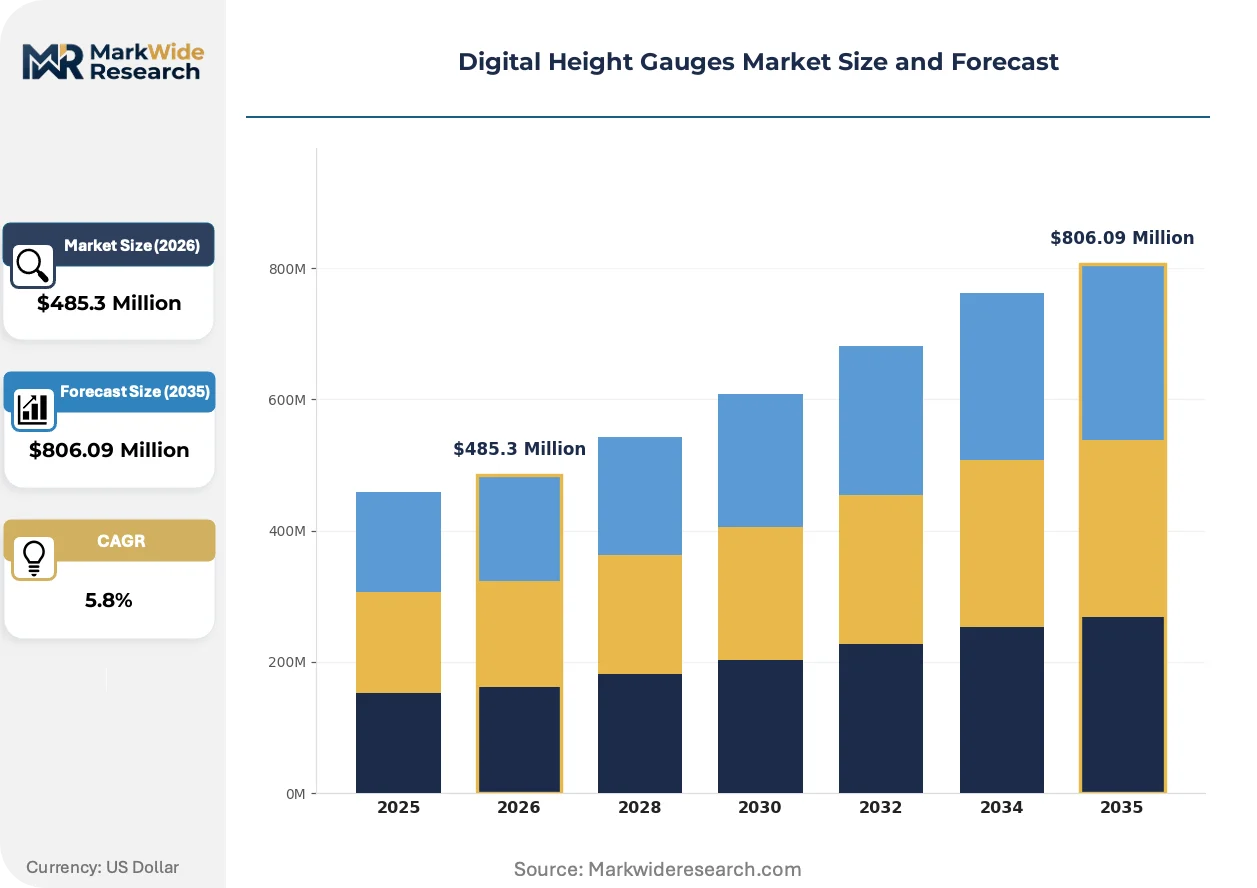
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Height Gauges, Digital Height Gauges, Electromechanical Height Gauges, Optical Height Gauges Technology: Mechanical, Electronic, Laser, Hybrid End User: Manufacturing, Automotive, Aerospace, Education Application: Quality Control, Research & Development, Production, Calibration |
| Companies Covered | Mitutoyo, Hexagon, Mahr, Starrett, TRIMOS, TESA, Sylvac, Bowers Group, HEL IOS-PREISSER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Height Gauges Market Trends and Innovations
Optical measurement architectures are penetrating coolant-heavy environments previously dominated by electronic encoders, while regulatory documentation requirements accelerate cloud-based calibration record adoption across aerospace supply chains.
Capacitive linear encoders with sealed optical read heads are supplanting traditional glass-scale encoders in Swiss precision machining corridors. Medical device manufacturers in Tuttlingen and Solothurn are specifying these units for orthopedic implant verification. The technology is supplanting contact-based measurement in environments where coolant contamination previously mandated frequent recalibration cycles.
Germany's PTB and the United States NIST are revising uncertainty budgets for digital dimensional measurement documentation. Revised calibration interval specifications compress replacement timelines for gauges approaching architectural limits. Aerospace suppliers in Hamburg and Wichita are pre-emptively upgrading encoder resolutions to maintain compliance headroom.
After-sales service unbundling is fragmenting procurement relationships between gauge manufacturers and independent calibration laboratories. Swiss and German machining clusters now separate hardware acquisition from accredited service contracts. This pattern is most visible among Tier-2 aerospace suppliers seeking to optimize capital deployment across cyclical order books.
Digital Height Gauges Market Segmentation
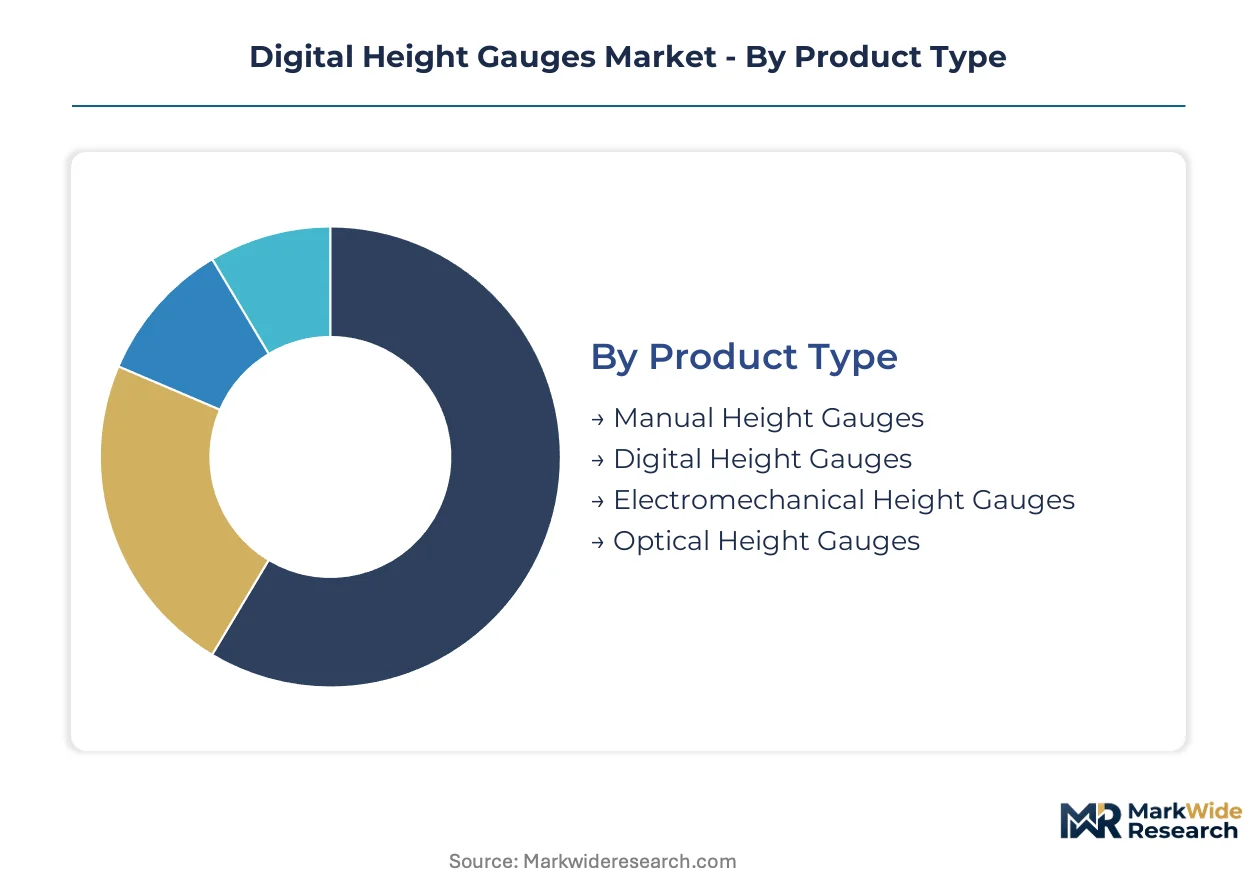
Digital height gauge procurement splits sharply between established electronic architectures and emerging optical platforms, with regulatory calibration mandates reshaping replacement patterns across every category. ISO 17025 compliance requirements in Germany and Japan concentrate specification upgrades in segments serving aerospace and medical device supply chains.
Product Type:
German PTB and Japanese JIS calibration standards impose distinct hardware requirements that segment replacement cycles and margin structures across product architectures.
- Digital Height Gauges:Linear encoder or capacitive sensor architectures resolve to 0.01 mm or finer, serving as shop-floor verification tools in machined-part acceptance. Aerospace manufacturers in Hamburg and Wichita concentrate procurement here to satisfy ISO 17025 traceability mandates for turbine blade inspection.
- Optical Height Gauges:Laser-based configurations employ optical displacement sensors for non-destructive measurement of complex geometries. Medical device manufacturers in Southern Germany and Swiss orthopedic machining clusters in Tuttlingen are expanding adoption for coolant-contaminated environments where contact probes degrade.
- Manual Height Gauges:Traditional vernier or dial-based mechanical systems persist in educational institutions and small-scale maintenance operations.
- Electromechanical Height Gauges:Hybrid architectures combining mechanical frames with electronic readouts serve price-sensitive precision machining corridors in South Korea.
Established volume favors Digital Height Gauges; emerging adoption favors Optical Height Gauges.
Technology:
Cost tier differentiation separates captive semiconductor fabrication from assembly-focused distribution models, with encoder chip supply concentration compressing availability for mid-tier manufacturers.
- Electronic:Proven reliability in coolant-heavy manufacturing environments sustains dominant revenue share, with sealed optical read heads supplanting glass-scale encoders in Swiss precision corridors.
- Laser:Expanding most quickly as optical displacement sensors displace contact probes in non-destructive turbine-blade measurement applications across aerospace supply chains in Wichita and Hamburg.
- Mechanical:Legacy architectures persist where electromagnetic compatibility compliance costs prohibit electromechanical upgrades.
- Hybrid:Combined sensor approaches address additive manufacturing quality verification for metal 3D-printed aerospace components.
Electronic technology commands current procurement volume; Laser configurations gain share fastest.
End User:
Application-specific precision requirements drive specification divergence, with sub-micron resolution mandates concentrating demand in medical device and aerospace verticals.
- Aerospace:Turbine blade geometric tolerance inspection and tool presetting operations in Germany and the United States demand certified calibration chains with documented uncertainty budgets.
- Manufacturing:General precision machining corridors across Switzerland, the United States, and South Korea generate baseline volume for shop-floor verification tools.
- Automotive:Powertrain component acceptance and quality system integration requirements shape procurement toward software-connected platforms.
- Education:Technical training institutions maintain demand for entry-level manual and basic digital configurations.
Manufacturing provides foundational volume; Aerospace concentrates premium specification upgrades.
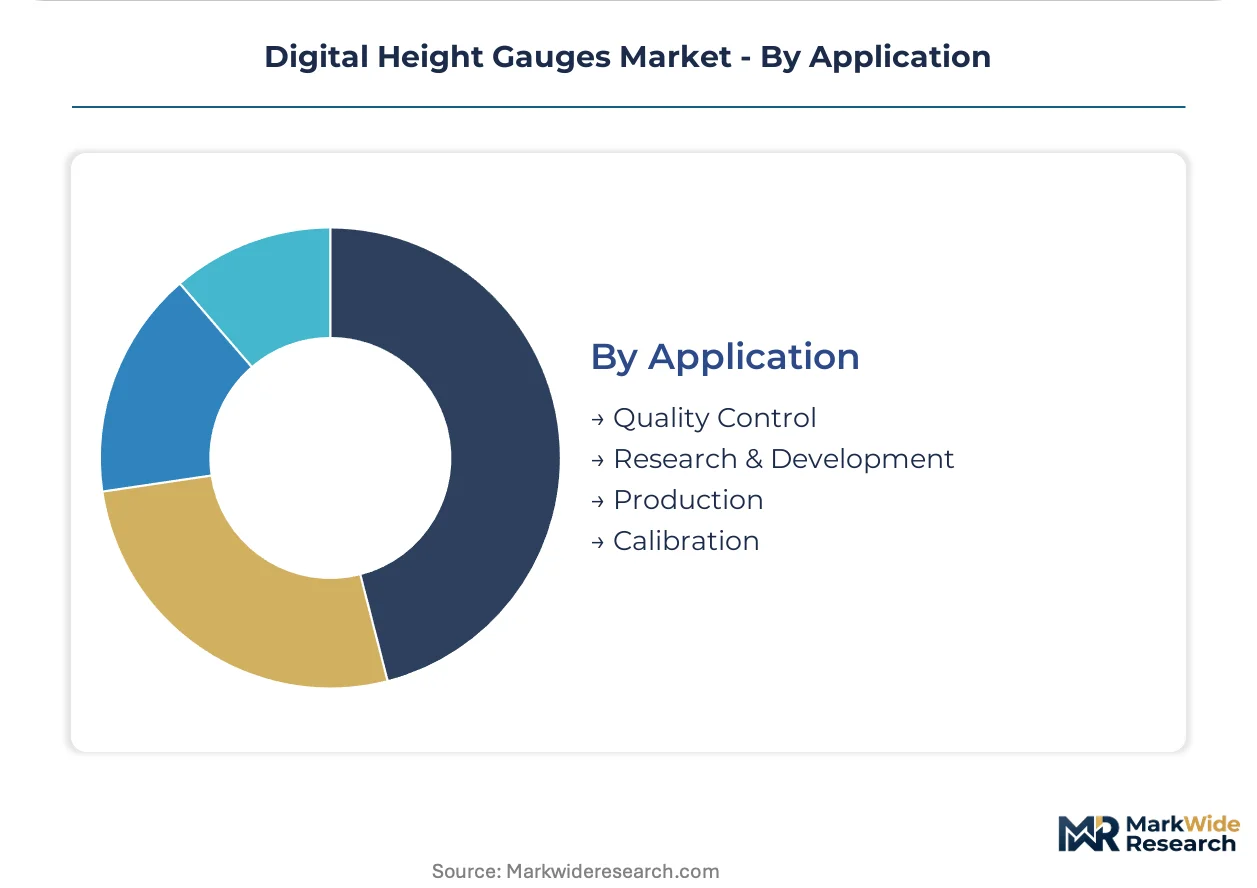
Application:
Margin pool concentration follows recurring revenue potential, with accredited service contracts offsetting cyclical equipment purchases in calibration-focused procurement.
- Calibration:Accredited laboratory services generate recurring revenue streams through ISO 17025 traceability requirements, with German and Japanese aerospace manufacturers expanding metrology budgets to comply with tighter mandates.
- Quality Control:Shop-floor machined-part acceptance drives replacement demand as uncertainty budget revisions compress gauge architectural lifecycles.
- Production:In-process measurement integration with quality management systems shapes demand toward software-integrated metrology platforms.
- Research & Development:Experimental measurement protocols and prototype verification sustain demand for flexible, high-resolution configurations.
Quality Control anchors equipment volume; Calibration captures concentrated service margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across precision manufacturing corridors. Buyers in South Korea and Swiss machining clusters accept premium specifications, while maintenance-focused operations in Mexico prioritize acquisition cost over calibration infrastructure.
United States
Aerospace manufacturers in Wichita and defense contractors across the Midwest drive specification upgrades for turbine blade inspection. NIST uncertainty budget revisions compress replacement timelines for gauges approaching architectural limits. Tool presetting operations in Connecticut and Ohio concentrate procurement for ISO 17025-compliant verification chains.
Germany
Medical device manufacturers in Tuttlingen and orthopedic machining clusters demand sub-micron resolution for implant verification. PTB calibration mandates force faster replacement cycles than typical depreciation schedules. Hamburg aerospace suppliers pre-emptively upgrade encoder resolutions to maintain compliance headroom against evolving documentary standards.
Switzerland
Precision machining corridors in Solothurn and Geneva specify sealed optical read heads for coolant-contaminated environments. Swissmedic device quality requirements elevate metrology budgets among contract manufacturers. Watchmaking and medical component clusters in the Jura Arc demonstrate concentrated demand for software-integrated platforms.
Japan
Semiconductor equipment manufacturers and aerospace subcontractors in Nagoya and Osaka expand encoder chip procurement from captive foundries. JIS calibration standards compel traceable measurement chains for export-qualified production. Automotive suppliers in Toyota City integrate height gauges with quality management systems for powertrain acceptance.
South Korea
Shipbuilding yards in Busan-Ulsan and semiconductor equipment fabricators in Gyeonggi Province demonstrate unmet demand for software-integrated metrology. MFDS medical device regulations drive specification upgrades among orthopedic implant contract manufacturers. Daegu-Gyeongbuk machining clusters favor hybrid electromechanical architectures for price-sensitive verification.
Digital Height Gauges Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated sensor manufacturers with captive semiconductor fabrication control premium electronic encoder supply, while assembly-focused distributors compete on price in mid-tier mechanical configurations. Two strategic archetypes dominate: vertically integrated precision specialists and software-platform integrators. Competitive moves concentrate on backward integration into encoder chip supply and cloud-connected calibration service unbundling.
Among Japanese precision instrument specialists, Mitutoyo exemplifies the vertically integrated archetype through captive encoder fabrication. Hexagon occupies a position representing software-integrated metrology platforms that extend hardware functionality into quality-management systems. Mahr anchors the sub-micron resolution specialist tier serving medical device manufacturers with accredited calibration infrastructure.
| Leading Market Players |
|---|
| Mitutoyo |
| Hexagon |
| Mahr |
| Starrett |
| TRIMOS |
| TESA |
| Sylvac |
| Bowers Group |
| HEL IOS-PREISSER |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor fabrication capacity at integrated sensor manufacturers concentrates cost advantages among vertically integrated precision specialists, compressing margin headroom for assembly-focused distributors while elevating price floors for ISO 17025-certified configurations. Scale economies in encoder chip production tether pricing power to foundry access, fragmenting competitive tiers between premium electronic architectures and price-sensitive electromechanical alternatives.
Pricing Analysis
Accredited calibration service contracts generate lifetime value exceeding hardware acquisition costs, with recurring revenue streams from ISO 17025 traceability mandates offsetting cyclical equipment purchases. Three-tier pricing structure across premium, standard, and economy levels separates Mitutoyo's captive-fabrication electronic lines from Hexagon's software-integrated platforms and Mahr's sub-micron medical specializations. Price differentiation hinges on certification grade and after-sales bundling, with unbundled procurement patterns in Swiss machining clusters intensifying pressure on standalone hardware margins. Aerospace manufacturers in Hamburg and Wichita demonstrate lowest price sensitivity, while maintenance-focused operations in Mexican border maquiladoras prioritize acquisition cost over calibration infrastructure investment.
Supply Chain Analysis
Tsugaru Strait shipping lanes and Pacific container routes channel encoder chip deliveries from Japanese semiconductor foundries to assembly facilities across Germany, Switzerland, and the United States. Component sourcing draws from Japanese encoder fabrication, Swiss precision machining for optical read heads, and German sensor calibration equipment. Single-source vulnerability concentrates in linear encoder supply, where Mitutoyo's captive foundry capacity limits component availability for mid-tier gauge manufacturers. Distribution runs through authorized metrology distributors serving aerospace and medical device clusters, with independent calibration laboratories unbundling service relationships from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 accredited service contracts expand faster than hardware unit shipments, transforming procurement economics toward recurring-revenue models that reward calibration infrastructure investment over manufacturing scale.
For Market Incumbents: Shield premium positioning by deepening backward integration into encoder chip supply and accelerating cloud-connected calibration platform deployment. Optical displacement sensor substitution threatens electronic encoder dominance in turbine-blade applications; counter through software-integrated metrology platforms that extend hardware functionality into quality-management systems. Certification investment in PTB and NIST uncertainty budget compliance preserves replacement cycle capture as documentary standards evolve.
For New Entrants and Emerging Players: ISO 17025 fast-track accreditation for independent laboratories creates service-attach entry points without captive fabrication requirements. South Korean precision machining corridors in Gyeonggi Province present underpenetrated demand for software-integrated platforms, while additive manufacturing quality verification for metal 3D-printed aerospace components offers application white space. Go-to-market through unbundled calibration contracts with Tier-2 aerospace suppliers seeking capital deployment optimization across cyclical order books.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated precision specialists with captive semiconductor fabrication and accredited calibration infrastructure over assembly-focused distributors. Long-term viability across the five-to-ten year window rests on recurring revenue attachment rates and regulatory compliance headroom. Acquisition target archetype: sub-micron resolution specialists serving medical device manufacturers with established PTB or NIST laboratory relationships. Watch NIST and PTB uncertainty budget revision timelines as inflection indicators for replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encoder Fabrication | Captive semiconductor capacity insulates Mitutoyo against component shortages affecting mid-tier competitors. |
| Cloud-Connected Calibration Platform Launch | Remote monitoring capabilities align with NIST evolving documentary standards for digital traceability. |
| ISO 17025 Laboratory Accreditation Expansion | Accredited service contracts generate recurring revenue offsetting cyclical equipment purchase volatility. |
| Optical Displacement Sensor Product Line Extension | Laser-based configurations penetrate non-destructive turbine-blade measurement in Hamburg and Wichita. |
| South Korean Distribution Partnership | Gyeonggi Province semiconductor equipment fabricators demonstrate unmet demand for software-integrated metrology. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with metrology equipment procurement managers, quality system directors at aerospace manufacturers, biomedical engineers at orthopedic implant firms, and aftermarket service heads at precision machining clusters; and secondary validation through customs/trade data, SEC 10-K filings of listed precision instrument manufacturers, NIST and PTB documentary standard publications, and ISO 17025 accreditation registries. Bottom-up equipment shipment estimates triangulated against top-down metrology budget allocations across German, Japanese, and United States manufacturing corridors.
Across the projection horizon, the analytical framework modeled demand across product architecture, technology type, end-use vertical, and application category, with geographic segmentation reflecting precision machining corridor concentration. CAGRs derived from replacement cycle analysis against ISO 17025 mandate compliance timelines, with encoder resolution upgrade patterns and software-integrated platform adoption curves informing trajectory assumptions.
Decision-makers should treat outputs as directional under base assumptions of stable ISO 17025 accreditation requirements and continued encoder chip supply concentration; material deviation in regulatory documentary standards or semiconductor fabrication capacity expansion would warrant model refresh. Practitioners should keep alternative scenarios live as NIST uncertainty budget revisions and JIS calibration interval specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hour Meter Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Digital Inspection Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Sound Meter Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Laser Interferometer Market