
 Plasma Arc Cutting Market | 2026-2036
Plasma Arc Cutting Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Arc Cutting Market Insights
Multi-source procurement among metal fabricators is consolidating as tier-one suppliers rationalize vendor lists for consumables and spare parts. Hypertherm sustains technology leadership through proprietary torch and plasma source integration. ESAB competes on geographic coverage with localized service networks across industrial corridors. Lincoln Electric anchors its position through backward integration into power supply electronics and welding adjacencies.
Plasma arc cutting employs electrically ionized gas jets reaching temperatures exceeding 20,000°C to melt and expel conductive metals, serving primarily for precision severing of thick steel, aluminum, and copper alloys in heavy fabrication environments. CNC plasma systems now dominate capital equipment sales as shipyards and automotive stamping operations automate bevel cutting and multi-axis contouring workflows. Consumables generate recurring revenue streams with higher margin stability than machine hardware, while software segments for nesting optimization and cut-path programming represent the fastest-growing attach category as fabricators pursue yield improvement.
OSHA ventilation standards and EPA air quality rules in the United States compel fabricators to specify fume extraction packages and water table configurations with new plasma installations. China's MEE enforces emission limits on particulate matter from thermal cutting operations, pushing domestic manufacturers toward submerged plasma and high-definition torch technologies. Stakeholders must weigh capex trade-offs between conventional plasma reliability and hybrid plasma versatility as end-user specifications diverge across heavy industries versus precision metal fabrication.
Market Dynamics
Shipbuilders in South Korea and Japan are consolidating automated plasma cutting procurement around fewer, larger system integrators capable of delivering full-stack hull fabrication cells, compressing vendor diversity and elevating technical certification barriers for new entrants.
Growth Catalysts
- Submerged plasma torch adoption:China's MEE emission limits on thermal cutting particulate matter are compelling domestic fabricators to retrofit water table configurations, expanding the addressable base for high-definition consumables.
- Thick-plate hull automation:Korean shipbuilders at Ulsan are mandating CNC plasma systems with multi-axis bevel cutting for naval and commercial vessel construction, locking in replacement cycles.
- REACH substance restrictions:EU regulatory pressure on hexavalent chromium in welding fume is diverting metal fabrication capex toward plasma alternatives with integrated extraction packages.
Market Restraints
- Copper electrode cost volatility:Hafnium-tipped cathodes and silver-bearing nozzles face raw material price swings that erode consumables margin predictability for distributors.
- Hypertherm torch ecosystem lock-in:Proprietary consumables architecture concentrates supply risk with a single dominant technology licensor, limiting second-source options for high-definition systems.
- Laser cutting substitution:Fiber laser technology below 25mm mild steel thickness is capturing precision fabrication volume previously served by plasma, compressing addressable market scope in light-gauge applications.
Strategic Opportunities
- Vietnamese shipyard greenfield expansion:Emerging hull construction clusters around Haiphong lack established plasma service infrastructure, creating first-mover advantage for localized spare parts logistics networks.
- EU Green Deal industrial retrofit incentives:Member state recovery funds for manufacturing decarbonization are subsidizing fume extraction and energy-efficient plasma source upgrades in Italian and German metalworking corridors.
- Nesting software attach expansion:Cloud-based cut-path optimization converging with ERP systems is opening recurring SaaS revenue streams independent of hardware replacement cycles.
Industry Challenges
- CNC programming skill scarcity:Shipyards and job shops face persistent shortages of operators capable of calibrating kerf compensation and torch height control for bevel applications on multi-axis gantries.
- GB standard certification timelines:China's tightening equipment safety and electromagnetic compatibility testing protocols are extending type-approval lead times for imported plasma power supplies, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Arc Cutting Market |
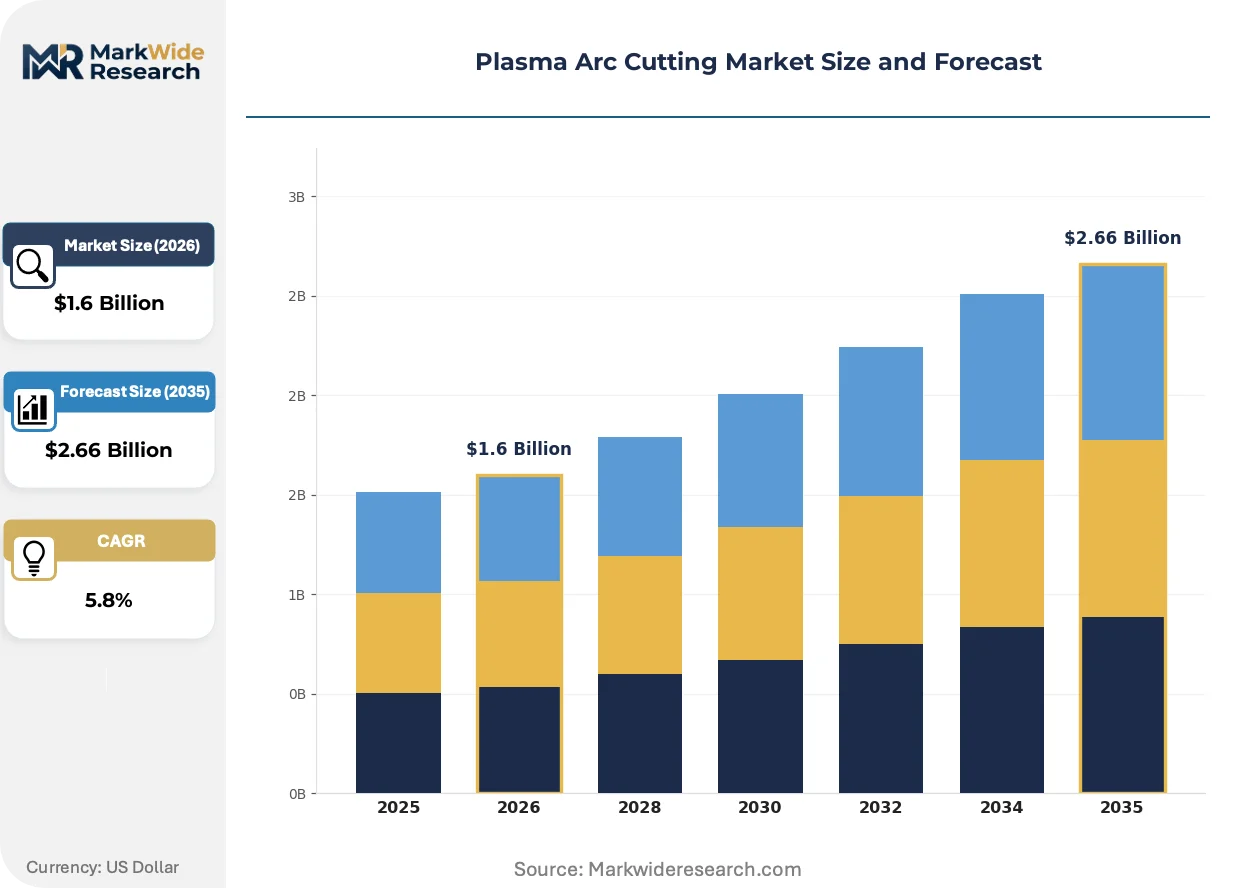
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional Plasma, CNC Plasma, Hybrid Plasma, Submerged Plasma Application: Manufacturing, Aerospace, Automotive, Shipbuilding End User: Heavy Industries, Metal Fabrication, Construction, Energy Product Type: Plasma Cutting Machines, Consumables, Software, Accessories |
| Companies Covered | Hypertherm, ESAB, Lincoln Electric, Miller Electric Mfg., DAIHEN Corporation, Komatsu NTC, Messer Cutting Systems, Stürmer maschinen GmbH, Kjellberg Finsterwalde Plasma und Maschinen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Arc Cutting Market Trends and Innovations
Plasma arc cutting technology is fragmenting into distinct performance tiers as end-users diverge between heavy fabrication reliability and precision metalworking flexibility, with software and consumables increasingly determining competitive differentiation.
High-definition plasma torch technology is decentralizing precision cutting capability from centralized OEM service centers to mid-sized job shops. Japanese automotive stamping suppliers are adopting compact 130-amp systems for prototype and short-run production. This capability diffusion is compressing the historical volume threshold at which laser investment became economically justified, reshaping competitive dynamics in the 6-25mm thickness band.
EPA air quality enforcement under the Clean Air Act is tightening fume capture specifications for thermal cutting operations in US metal fabrication facilities. Fabricators in Ohio and Pennsylvania industrial corridors are specifying integrated downdraft tables and high-efficiency cartridge filtration as mandatory package components. Equipment vendors are responding by pre-engineering extraction systems into standard machine configurations rather than treating them as aftermarket add-ons.
After-sales service unbundling is accelerating as fleet operators separate consumables procurement from maintenance contracts. Large German automotive suppliers are negotiating direct electrode and nozzle supply agreements with specialized distributors, bypassing traditional OEM captive parts programs. This disintermediation is most pronounced in the Ruhr industrial region, where multi-site fabricators are consolidating spare parts inventory management under centralized procurement functions.
Plasma Arc Cutting Market Segmentation
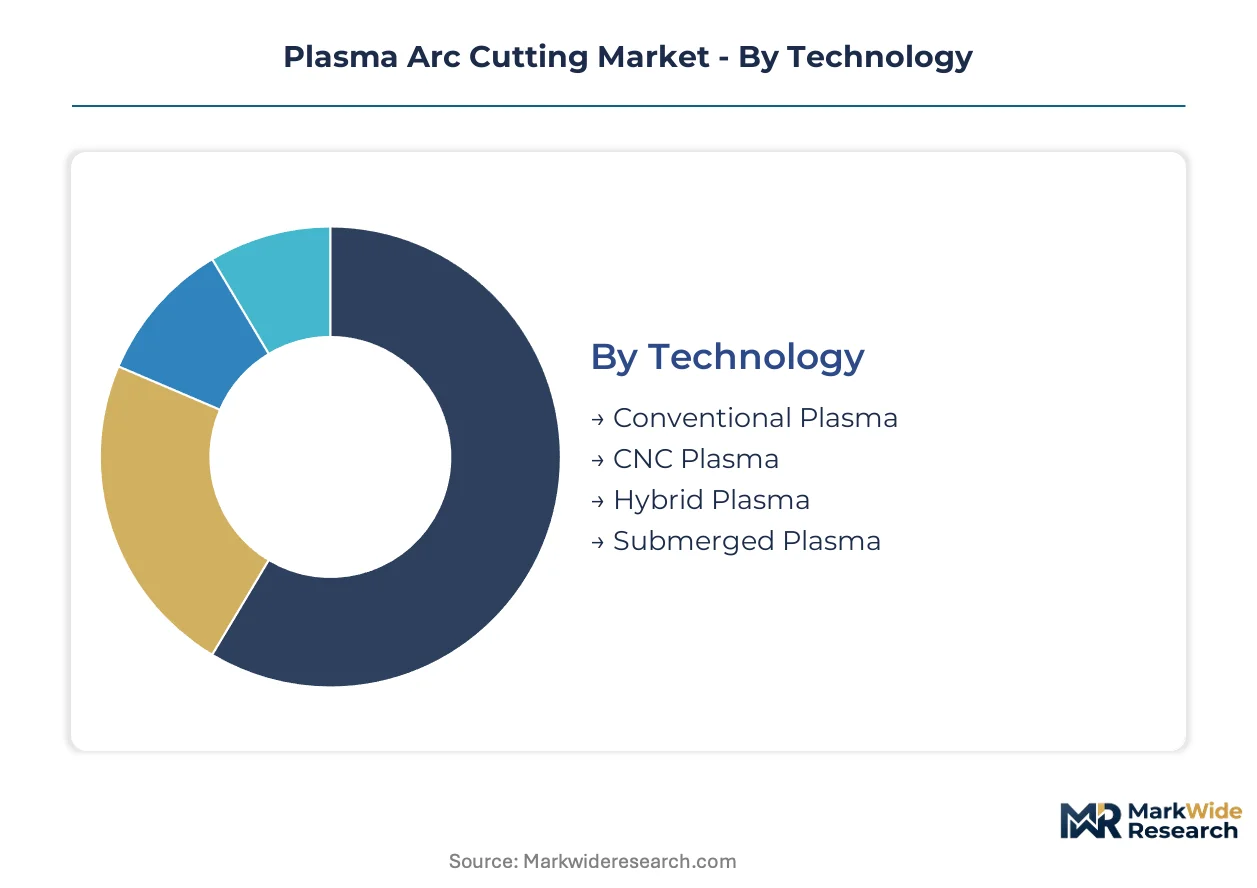
Technology tiers determine certification intensity and margin structure across plasma arc cutting procurement. Application and end-user splits reveal where automation premiums command pricing power versus commodity replacement cycles.
Technology:
GB standard electromagnetic compatibility testing and MEE emission compliance create divergent approval timelines across plasma source architectures.
- CNC Plasma:Computer numerical control systems integrate multi-axis torch positioning with automated bevel cutting for thick-plate hull sections. Korean shipbuilders at Ulsan mandate these configurations for naval and commercial vessel construction, locking in replacement cycles and elevating technical certification barriers.
- Submerged Plasma:Water table configurations suppress particulate emissions by cutting beneath the waterline, meeting China's MEE thermal cutting limits. Domestic fabricators retrofit existing gantries with submerged torch packages, expanding the addressable base for high-definition consumables and integrated extraction.
- Conventional Plasma:Basic arc systems without CNC integration serve job shops and maintenance operations where capital constraints limit automation investment.
- Hybrid Plasma:Dual-process systems combine plasma severing with oxy-fuel or waterjet capability, serving metal fabricators seeking equipment versatility across thickness ranges.
CNC Plasma sits at the top of the volume ranking, with Submerged Plasma climbing the fastest.
Application:
End-use concentration shapes service infrastructure requirements and spare parts logistics density.
- Shipbuilding:Automated hull fabrication cells demand full-stack system integration from fewer, larger vendors. Japanese and Korean yards consolidate procurement around certified integrators capable of delivering multi-axis gantry installations with embedded fume extraction.
- Automotive:Stamping suppliers adopt compact 130-amp systems for prototype and short-run production, compressing the volume threshold where laser investment becomes economically justified.
- Manufacturing:General metal fabrication spans job shops and OEM component suppliers with heterogeneous thickness and precision requirements.
- Aerospace:Precision contouring of aluminum and titanium alloys demands high-definition torch technology with tight kerf control and minimal heat-affected zones.
Shipbuilding commands the highest absolute equipment value per installation, while Automotive gains share fastest through capability diffusion to mid-tier suppliers.
End User:
Procurement sophistication separates centralized fleet operators from distributed job shop purchasing patterns.
- Heavy Industries:Steel mills, mining equipment manufacturers, and infrastructure fabricators operate large installed bases with captive maintenance teams and direct consumables sourcing agreements.
- Metal Fabrication:Independent job shops and contract manufacturers prioritize equipment flexibility and localized service response over single-source technology lock-in.
- Construction:Field-based cutting for structural steel erection and repair favors portable manual plasma systems with minimal setup complexity.
- Energy:Oil, gas, and power generation maintenance operations require explosion-rated equipment and specialized torch configurations for pipeline and vessel repair.
Heavy Industries dominates replacement consumables volume, with Metal Fabrication expanding most quickly through software attach and nesting optimization adoption.
Product Type:
Margin stability varies sharply between capital equipment cycles and recurring revenue streams.
- Consumables:Electrodes, nozzles, and shields generate recurring revenue with higher margin predictability than machine hardware. Hafnium-tipped cathodes and silver-bearing nozzles face raw material price volatility that erodes distributor margins.
- Software:Cloud-based nesting optimization and cut-path programming attach to ERP systems, opening recurring SaaS revenue independent of hardware replacement cycles.
- Plasma Cutting Machines:Power supplies, torch assemblies, and gantry systems constitute capital equipment sales with cyclical demand tied to shipyard and automotive capex cycles.
- Accessories:Fume extraction packages, downdraft tables, and filtration cartridges increasingly ship as mandatory pre-engineered configurations rather than aftermarket add-ons.
Consumables anchors revenue stability across the product mix, with Software showing the steepest expansion trajectory as fabricators pursue yield improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan anchors plasma arc cutting procurement intensity through Korean shipyard automation mandates, while regulatory divergence across major fabrication economies reshapes equipment certification timelines and vendor selection criteria.
United States
Automotive stamping suppliers in Michigan and Ohio drive compact system adoption for prototype production. OSHA ventilation standards compel integrated fume extraction specifications on new installations. Pittsburgh and Cleveland industrial corridors specify downdraft table configurations as mandatory package components.
Germany
Ruhr region multi-site fabricators consolidate spare parts inventory under centralized procurement functions. EU Green Deal recovery funds subsidize energy-efficient plasma source upgrades. Stuttgart and Munich automotive suppliers negotiate direct consumables agreements bypassing OEM captive programs.
China
Domestic fabricators retrofit water table configurations to meet MEE thermal cutting emission limits. GB standard electromagnetic compatibility testing extends type-approval lead times for imported power supplies. Yangtze River Delta shipbuilding clusters absorb high-definition consumables expansion.
Japan
Nagasaki and Kure shipyards consolidate procurement around certified system integrators delivering full-stack hull fabrication cells. METI industrial efficiency guidelines accelerate CNC gantry replacement cycles. Osaka-based automotive stamping suppliers adopt 130-amp systems for short-run production.
South Korea
Ulsan shipbuilders mandate multi-axis bevel cutting systems for naval and commercial vessel construction. MFDS equipment safety protocols elevate technical certification barriers for new market entrants. Busan fabrication clusters lock in replacement cycles through automated hull section workflows.
Plasma Arc Cutting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software attach and consumables specialization. The vendor base stratifies across three tiers: integrated power supply OEMs with captive consumables programs, specialized torch technology licensors, and regional system integrators with localized service density. Dominant competitive moves include backward integration into power supply electronics and geographic expansion through distributor network consolidation.
Among German precision engineering specialists, Kjellberg Finsterwalde Plasma und Maschinen GmbH and Stürmer maschinen GmbH exemplify the torch technology archetype, while DAIHEN Corporation represents integrated industrial equipment conglomerates with captive fabrication technology portfolios. These three entities anchor distinct competitive positioning vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Hypertherm |
| ESAB |
| Lincoln Electric |
| Miller Electric Mfg. |
| DAIHEN Corporation |
| Komatsu NTC |
| Messer Cutting Systems |
| Stürmer maschinen GmbH |
| Kjellberg Finsterwalde Plasma und Maschinen GmbH |
| Others |
Pricing and Supply Chain Analysis
China's MEE thermal cutting emission limits gate qualified supply for high-definition plasma systems, restricting premium-tier pricing access to vendors with certified submerged torch configurations and electromagnetic compatibility testing under GB standards. Domestic fabricators seeking water table retrofits face extended procurement timelines, compressing margin flexibility for distributors caught between raw material volatility and fixed-price service contracts.
Pricing Analysis
Input-cost pass-through from hafnium-tipped cathodes and silver-bearing nozzles shapes margin predictability across consumables tiers. Three-tier pricing structure across premium, standard, and economy levels separates high-definition OEM captive programs from second-source distributors and generic electrode suppliers. Cost compression in standard plasma consumables is intensifying because Korean shipbuilders consolidate procurement around fewer integrators with volume-scale leverage. Heavy industries with captive maintenance teams show least price sensitivity, while independent job shops in fragmented metal fabrication corridors exhibit highest elasticity.
Supply Chain Analysis
Certification gating under China's GB electromagnetic compatibility protocols and South Korea's MFDS equipment safety standards restricts qualified power supply sourcing to Germany, Japan, and the United States. Raw material dependencies center on hafnium for cathode tips, silver alloys for precision nozzles, and high-purity copper for electrode bodies. Single-source vulnerability concentrates in Hypertherm's proprietary torch ecosystem, limiting second-source options for high-definition consumables. Distribution runs through regional system integrators with localized service density, anchored by captive parts programs and direct agreements with large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's extended GB certification timelines and Vietnam's greenfield shipyard expansion lacking established service infrastructure, with regulatory compliance costs in the former creating first-mover margin capture opportunities in the latter.
For Market Incumbents: Anchor technology leadership through backward integration into power supply electronics and proprietary torch-consumables bundling. Fiber laser substitution below 25mm mild steel thickness threatens plasma's precision fabrication volume, demanding defensive investment in hybrid plasma-oxy-fuel systems. Certification investment under tightening MEE and GB standards elevates barriers against emerging entrants lacking testing infrastructure. For New Entrants and Emerging Players: Capture Vietnamese shipyard clusters around Haiphong through localized spare parts logistics networks ahead of incumbent service footprint expansion. Cloud-based nesting software attach represents the most penetrable segment, with SaaS revenue models decoupled from hardware replacement cycles and lower capital intensity than machine manufacturing. Go-to-market execution should prioritize direct consumables agreements with multi-site fabricators consolidating procurement under centralized functions. For Investors and Strategic Acquirers: Roll-up economics work for specialized torch technology licensors because fragmented regional system integrators lack scale to independently fund R&D for high-definition consumables. The 5-10 year viability window favors platform consolidation around software-enabled service models with recurring revenue streams. Watch for inflection when China's GB type-approval lead times compress, signaling domestic supply maturation and import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Lincoln Electric's captive supply of inverter components reduces dependency on semiconductor foundry allocation. |
| Submerged Plasma Retrofit Programs | Water table configurations satisfy China's MEE particulate limits while expanding high-definition consumables attach. |
| Cloud-Based Nesting Software Launch | ERP-integrated cut-path optimization opens SaaS revenue independent of shipyard capex cycles. |
| Regional Service Network Expansion | ESAB's localized density across industrial corridors compresses response time for Korean shipbuilder maintenance. |
| Hybrid Plasma-Oxy-Fuel System Development | Dual-process capability defends against fiber laser displacement in 6-25mm thickness applications. |
Research Methodology
Multiple input streams — technical interviews with shipyard maintenance directors and automotive stamping engineers, regulatory filings with China's MEE and South Korea's MFDS, and trade data from Korean and Japanese industrial equipment customs records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of listed welding equipment manufacturers, GB standard electromagnetic compatibility testing protocols, and EU Green Deal manufacturing decarbonization fund disbursements. Primary fieldwork encompassed plant engineers at Ulsan shipbuilders, procurement leads at Ruhr region multi-site fabricators, and aftermarket service heads at German automotive suppliers.
Data-stream reconciliation across the projection horizon applied analytical frameworks modeling technology tier, application end-use, and regional regulatory cluster segmentation. CAGRs were derived through installed base replacement cycle analysis, shipbuilding orderbook trajectories, and automotive stamping capacity expansion patterns. Forecast inputs incorporated CNC gantry automation mandates, REACH substance restriction compliance costs, and nesting software attach rates.
Underlying measurement precision varies by segment; shipbuilding and automotive applications carry tighter precision than dispersed job shop metal fabrication. Forecasts reflect assumptions about GB certification timeline stability, hafnium supply continuity, and laser substitution elasticity. A model refresh is warranted upon material change in China's MEE enforcement intensity or Korean shipbuilder consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Height Gauge Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
India Power Tool Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Holder Market
Industrial Tools
Electric Tools Market
Industrial Tools
Die Grinders Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Micro Welders Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Handheld DC Torque Tools Market