
 Battery Materials Market | 2026-2036
Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Materials Market Intelligence
Solid-state electrolyte development is reconfiguring how cell architectures eliminate thermal runaway risks and enable lithium-metal anodes. Albemarle Corporation leverages its Chilean and Australian brine assets to sustain upstream lithium carbonate supply. POSCO Future M anchors cathode precursor output through integrated nickel refining in South Korea. Umicore differentiates via closed-loop battery recycling technology that recovers cobalt and nickel at industrial scale.
Battery materials encompass the active and passive substances—cathode powders, anode graphite or silicon composites, electrolyte salts, and polyolefin separators—that store and transfer electrochemical energy within cells, with energy density typically measured in watt-hours per kilogram and cycle life spanning 1,000 to 3,000 charge events depending on chemistry. The primary commercial purpose is enabling rechargeable energy storage for mobility and grid applications. Lithium-ion chemistries dominate installed capacity, though solid-state configurations represent the fastest-growing product category as manufacturers resolve ceramic-electrolyte manufacturing yields. Cathode materials command the largest margin pool due to nickel and cobalt value concentration, while separator production remains the most consolidated component segment.
The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations for cells sold in Europe, compelling producers to restructure supply chains. China's MIIT enforces GB standards for cell safety and material purity that gate market access for imported components. The EPA and OSHA in the United States impose hazardous material handling rules on cathode powder facilities. Stakeholders must monitor how regulatory divergence between these jurisdictions reshapes qualification costs and localization requirements.
Market Dynamics
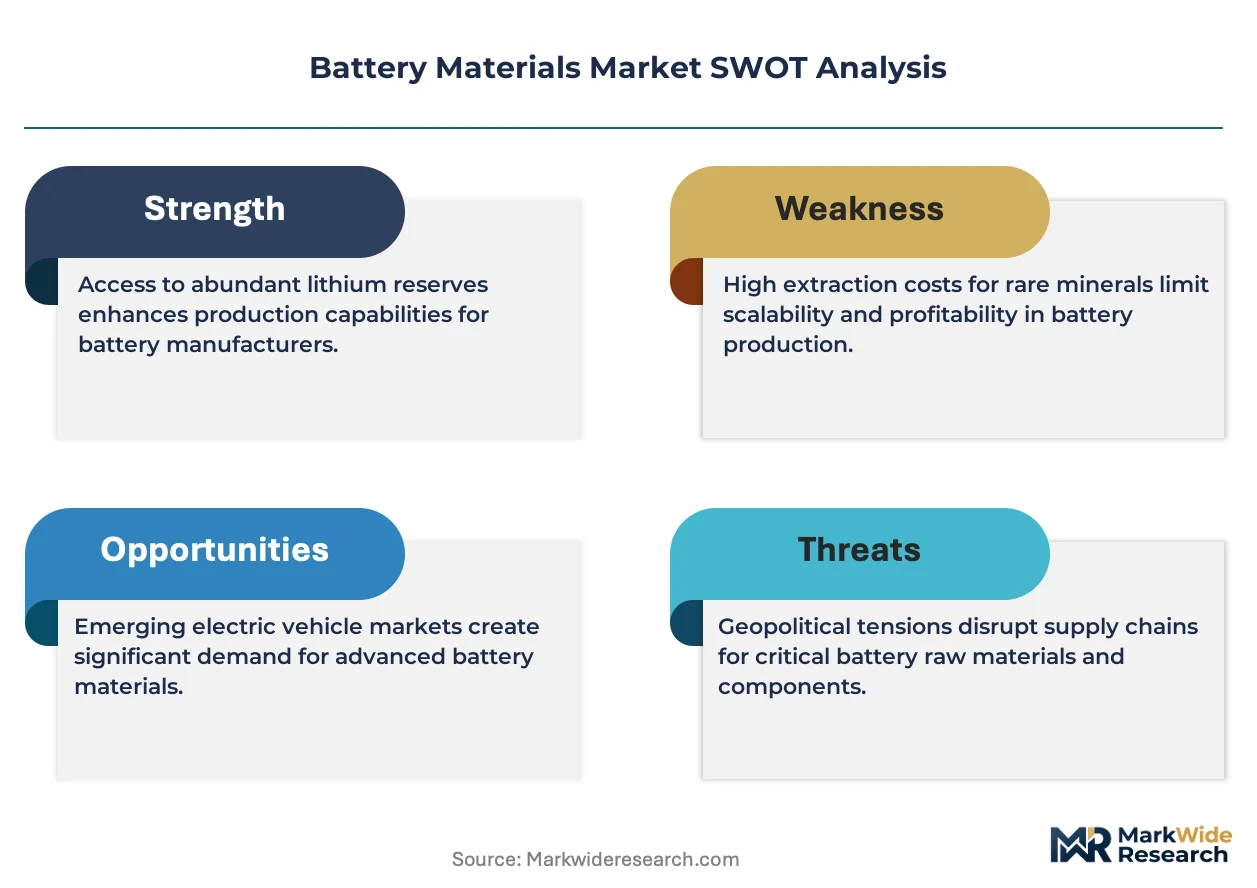
High-nickel cathode chemistry migration is compressing cobalt demand while concentrating procurement leverage among integrated precursor manufacturers with captive nickel refining positions.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Cells sold in Europe must meet escalating recycled lithium and cobalt thresholds, forcing producers to invest in closed-loop recovery infrastructure.
- China's dual carbon policy framework:MIIT enforcement of carbon intensity caps on cathode production is accelerating facility relocation to provinces with renewable-heavy grids.
- Solid-state electrolyte maturation:Ceramic and sulfide electrolyte manufacturing yields are improving sufficiently to enable pilot-scale lithium-metal anode cell production.
Market Restraints
- Brine-to-hydroxide conversion bottlenecks:South American lithium carbonate output faces limited conversion capacity to battery-grade hydroxide required by high-nickel cathodes.
- Graphite anode supply concentration:Spherical graphite processing and coating capacity clusters in China's Shandong and Heilongjiang provinces, creating single-country dependency risks.
- Polyolefin separator technical ceiling:Conventional wet-process polyethylene separators face thermal stability limits above 150°C that constrain fast-charging cell architectures.
Strategic Opportunities
- Indonesia nickel matte integration:High-pressure acid leach projects in Sulawesi and Halmahera offer integrated routes from laterite ore to battery-grade nickel sulfate.
- Second-life battery material recovery:Decommissioned EV packs in Europe and China are emerging as feedstock streams for direct recycling of cathode active materials.
- Sodium-ion chemistry industrialization:Hard carbon anode and layered oxide cathode supply chains are scaling for stationary storage applications with reduced lithium dependency.
Industry Challenges
- Dry electrode coating process engineering:Eliminating solvent-based cathode slurry coating requires requalification of entire electrode production lines and binder material sets.
- Cell formation protocol standardization:Divergent cycling protocols between automotive OEMs and cell manufacturers extend qualification timelines and inflate R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Materials Market |
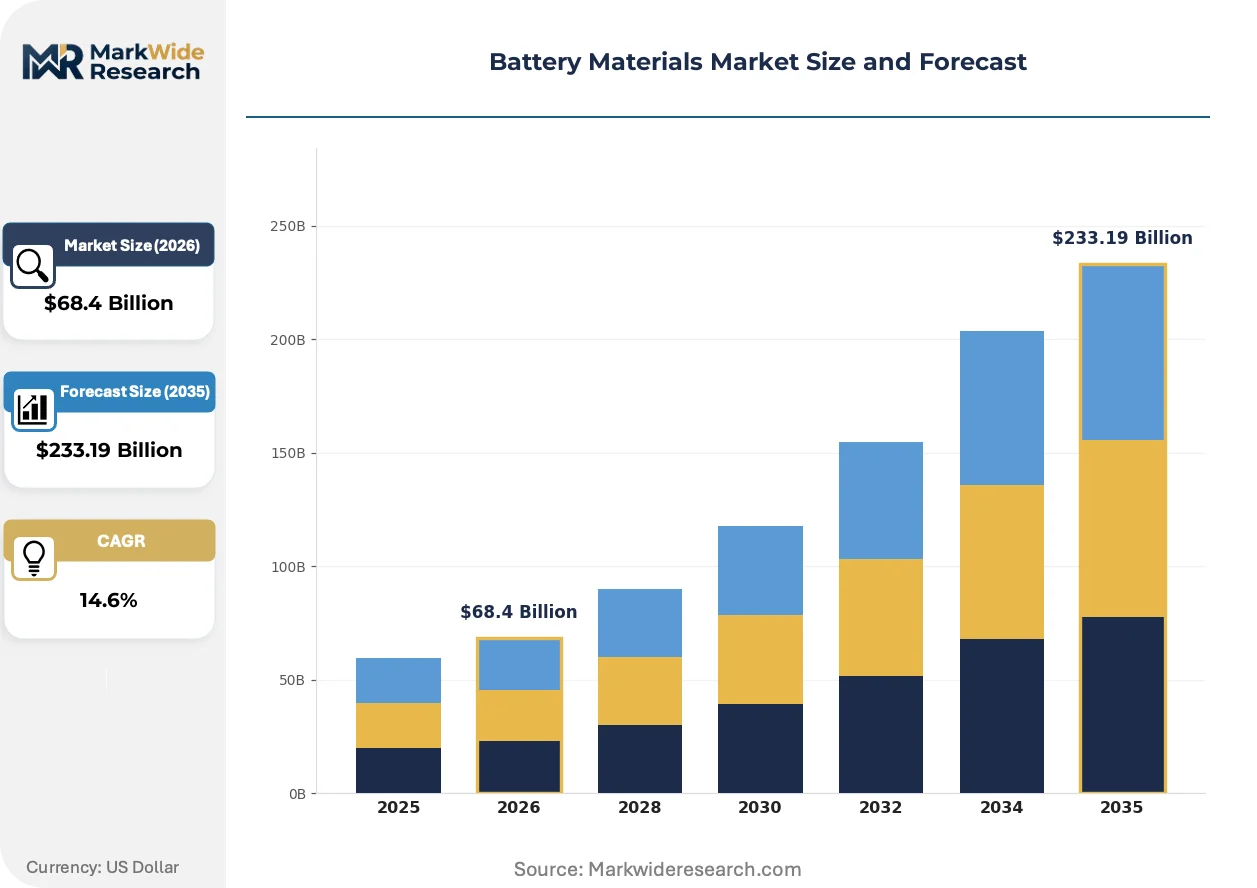
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $233.19 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Cobalt, Lead-Acid, Solid-State Component: Electrolyte, Anode, Cathode, Separator Application: Electric Vehicles, Energy Storage, Consumer Electronics, Industrial Use Manufacturing Stage: Raw Material Processing, Component Assembly, Full Cell Production, Quality Testing |
| Companies Covered | BASF, POSCO Future M, Asahi Kasei Corporation, Umicore, Sumitomo Metal Mining Co., Ltd., Albemarle Corporation, LG Chem Ltd., Samsung SDI Co., Ltd., Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Materials Market Strategic Shifts & Innovations
Cathode precursor synthesis routes are bifurcating between high-pressure hydroxide co-precipitation for nickel-rich formulations and novel low-temperature molten salt processes that promise reduced energy intensity.
Silicon composite anodes are migrating from graphite blending ratios below 5% toward 20-30% silicon oxide loadings in automotive cells. Korean and Chinese cell manufacturers are qualifying silicon-carbon architectures for 2025 model-year EV platforms. This migration from incremental to substantial silicon content is compressing the energy density gap against theoretical lithium-metal limits while demanding novel binder chemistries and electrolyte additive packages to manage volumetric expansion.
REACH authorization requirements for nickel compounds are tightening occupational exposure thresholds at European cathode powder facilities. ECHA's 2023-2024 substance evaluation wave is forcing producers to submit extended safety dossiers for nickel sulfate and nickel hydroxide intermediates. German and Polish precursor plants are responding by sealing powder handling lines and installing real-time aerosol monitoring systems to maintain operating licenses.
Fleet operators and energy storage developers are consolidating cell procurement through multi-year offtake agreements with tier-one manufacturers, bypassing traditional trading house intermediaries. This direct contracting pattern is compressing spot market liquidity for cathode materials and shifting price discovery toward bilateral negotiation frameworks. The trend is most visible in North American utility-scale storage deployments and European commercial EV fleet electrification programs.
Battery Materials Market Segmentation
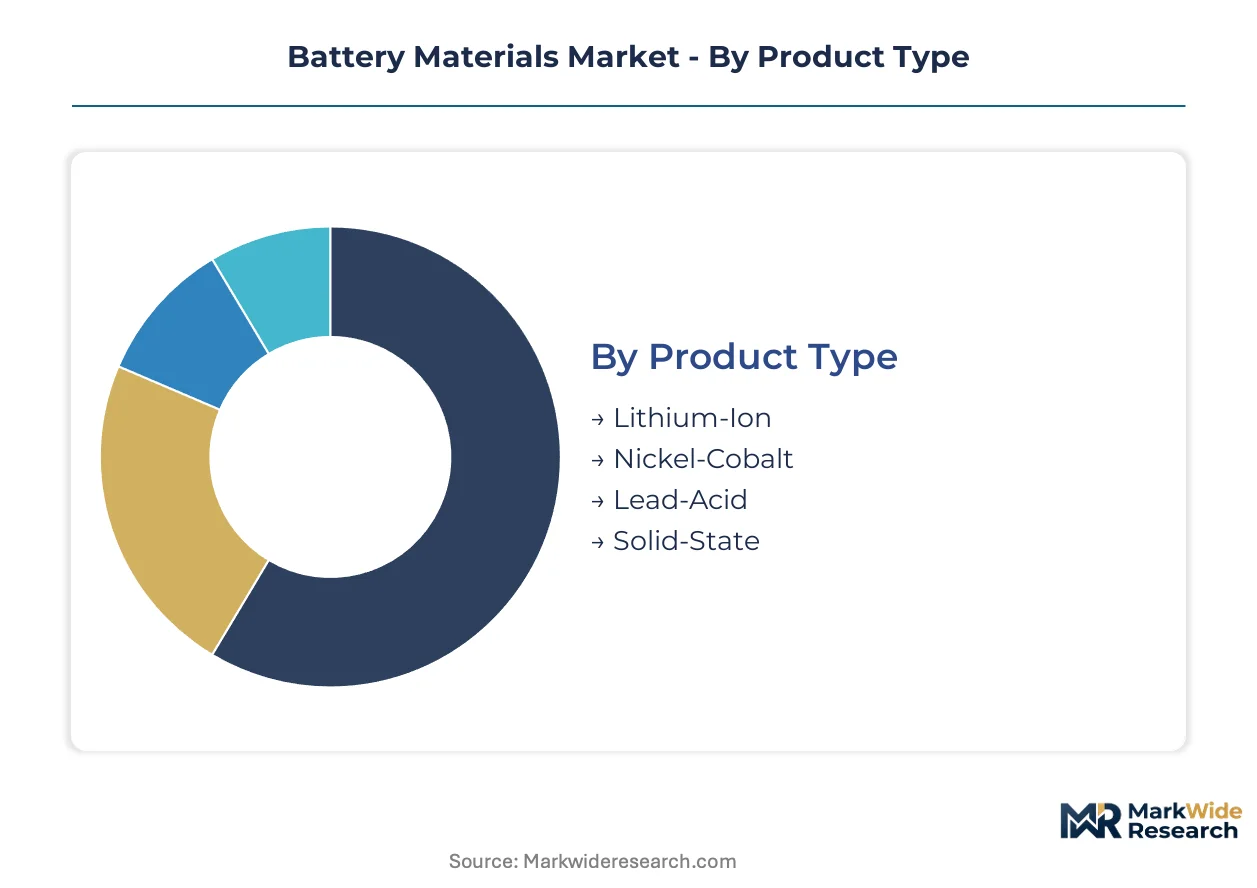
Battery materials segmentation reveals how chemistry choices cascade through component specifications, application requirements, and manufacturing complexity. Each dimension governs procurement patterns, qualification timelines, and margin structures differently.
Product Type:
Mature lithium-ion chemistries coexist with emerging solid-state architectures, creating a bifurcated maturity landscape across electrochemical systems.
- Lithium-Ion:Layered oxide cathodes paired with graphite anodes dominate installed capacity. Automotive OEMs in Germany, South Korea, and the United States scale procurement of nickel-manganese-cobalt variants for 800-volt platforms.
- Solid-State:Ceramic and sulfide electrolyte cells eliminate flammable liquid components while enabling lithium-metal anodes. Japanese manufacturers and Chinese startups pilot production lines for premium EV applications.
- Nickel-Cobalt:High-voltage spinel and layered structures persist in consumer electronics and aviation batteries where energy density premiums justify cobalt exposure.
- Lead-Acid:Mature flooded and absorbed glass mat designs retain cost advantages for stationary backup power and ICE vehicle starting applications.
Lithium-Ion handles the majority of throughput; Solid-State is the fastest mover on share.
Component:
Cost tier stratification separates commodity anodes from precision-manufactured separators with steep qualification barriers.
- Cathode:Precursor powders command the largest material cost share in cell bills of materials. Nickel sulfate and cobalt hydroxide feedstock sourcing determines competitiveness for producers in Finland, Canada, and Australia.
- Anode:Synthetic and natural graphite grades, plus emerging silicon-carbon composites, store lithium ions during charge cycles. Chinese spherical graphite processing clusters in Shandong province supply Korean and Japanese cell makers.
- Electrolyte:Lithium hexafluorophosphate salts dissolved in carbonate solvents facilitate ion transport between electrodes. Additive packages determine high-voltage stability and fast-charging tolerance.
- Separator:Wet-process polyethylene and polypropylene membranes prevent internal short circuits while permitting ion permeability. Ceramic coating layers extend thermal shutdown thresholds for automotive safety requirements.
Cathode absorbs the dominant share of material expenditure; Separator commands the steepest margin premiums.
Application:
Volume concentration varies sharply across mobility, grid, and consumer segments with divergent performance specifications.
- Electric Vehicles:Cylindrical, prismatic, and pouch cells for passenger cars and commercial trucks drive nickel-rich cathode demand. European and North American OEMs enforce cell-level carbon footprint declarations through supply contracts.
- Energy Storage:Lithium iron phosphate and sodium-ion chemistries prioritize cycle life over energy density for grid-scale installations. Utility developers in Texas, California, and the United Kingdom sign multi-year offtake agreements directly with tier-one manufacturers.
- Consumer Electronics:Cobalt-containing cathodes maintain presence in smartphones and laptops where volumetric energy density limits device form factors.
- Industrial Use:Forklifts, mining equipment, and marine vessels adopt battery systems for indoor air quality and torque response advantages.
Electric Vehicles generates the dominant procurement volume; Energy Storage is climbing the fastest on capacity additions.
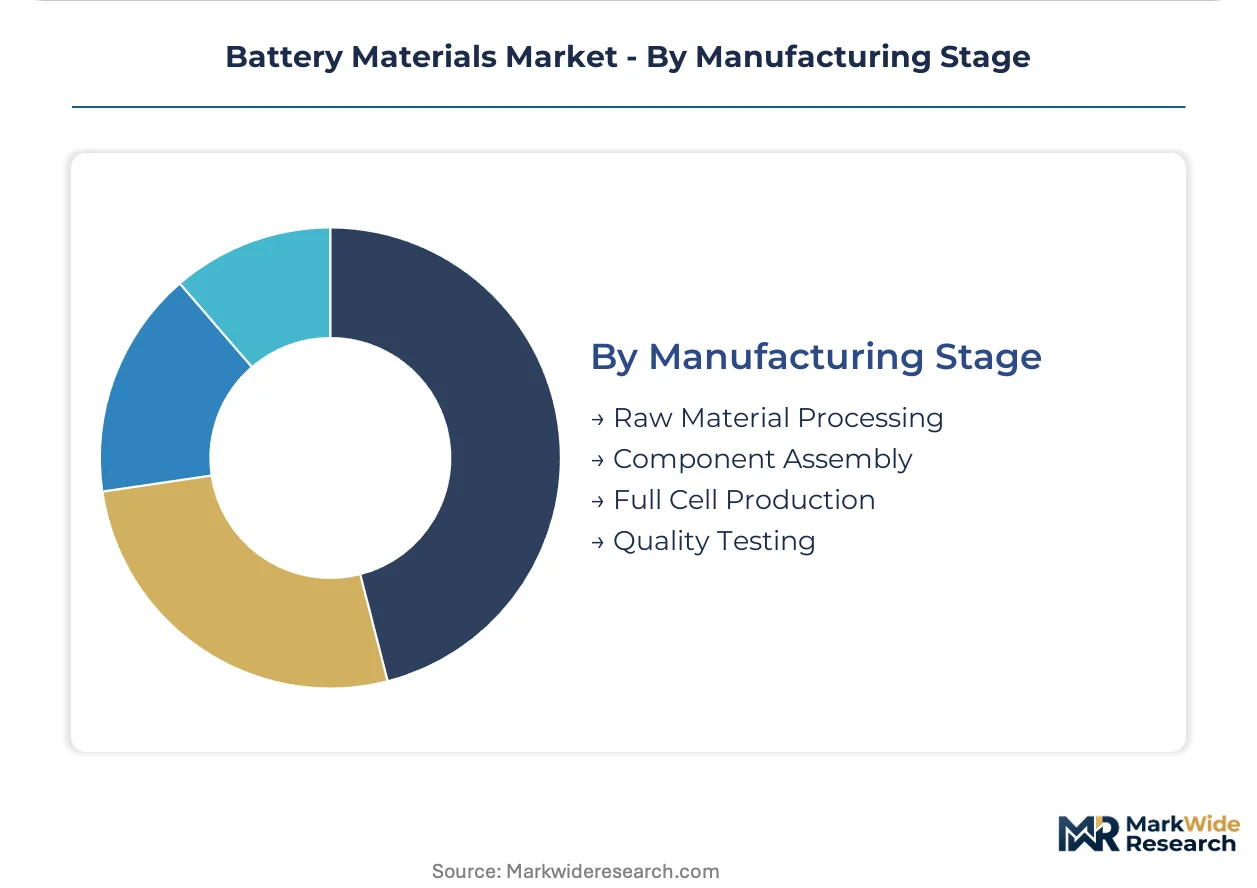
Manufacturing Stage:
Supply concentration intensifies downstream, with raw material processing fragmented across mining jurisdictions and cell production consolidating among integrated manufacturers.
- Raw Material Processing:Brine evaporation in Chile and Argentina, spodumene crushing in Australia, and laterite smelting in Indonesia supply battery-grade lithium, nickel, and cobalt intermediates.
- Component Assembly:Cathode precursor co-precipitation, anode coating and calendering, electrolyte blending, and separator fabrication occur in specialized facilities with chemistry-specific equipment.
- Full Cell Production:Electrode stacking or winding, electrolyte filling, and formation cycling integrate components into finished cells. Korean and Chinese producers operate the largest electrode coating capacities.
- Quality Testing:Aging protocols, electrochemical impedance spectroscopy, and safety abuse testing verify cell performance before shipment to pack assemblers.
Component Assembly concentrates value-added margin; Full Cell Production is expanding most quickly on capacity investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The battery materials trade balance tilts heavily toward net-importing cell manufacturing economies, with raw material exporters in South America and Australasia feeding integrated precursor hubs in East Asia. This geographic specialization creates concentrated supply vulnerabilities that regional industrial policies are actively redrawing.
China
Jiangsu and Hunan provinces host the world's densest cathode precursor manufacturing clusters, supplying Korean and European cell makers with nickel-cobalt-manganese hydroxides. MIIT enforcement of GB standards for material purity and carbon intensity is forcing facility relocations toward western provinces with renewable-heavy grids. Qinghai and Sichuan lithium carbonate from brine operations feeds domestic hydroxide conversion plants.
South Korea
POSCO Future M anchors integrated nickel refining-to-precursor output in Pohang and Gwangyang, leveraging captive sulfate supply from Indonesian HPAL partnerships. The country's national industrial regulator enforces strict cell safety certifications that gate market access for imported cathode materials. Seoul-based cell manufacturers are expanding electrode coating capacity to supply North American EV assembly plants.
United States
The Inflation Reduction Act's domestic content bonuses are reshoring cathode active material production to Kentucky and Nevada, though lithium hydroxide supply remains import-dependent from Chilean brine operations. EPA hazardous material handling rules and OSHA occupational exposure limits apply to cathode powder facilities in the Midwest. Texas and California utility-scale storage developers sign direct offtake agreements with tier-one cell manufacturers, bypassing traditional trading intermediaries.
Germany
REACH authorization requirements for nickel compounds are tightening occupational exposure thresholds at precursor plants in Saxony and North Rhine-Westphalia. ECHA's substance evaluation wave demands extended safety dossiers for nickel sulfate intermediates. BASF's Schwarzheide facility exemplifies the EU Battery Regulation's recycled content mandates, integrating closed-loop cobalt recovery from decommissioned industrial batteries.
Indonesia
High-pressure acid leach projects in Sulawesi and Halmahera are scaling integrated routes from laterite ore to battery-grade nickel sulfate, displacing traditional matte exports to China. The country's mineral export ban policies are forcing downstream investment commitments from foreign mining concessionaires. Morowali Industrial Park concentrates HPAL capacity with direct pipeline connections to precursor plants under construction.
Battery Materials Market Key Industry Players
On the supply side, the industry is consolidating around integrated miners with captive refining positions and diversified chemical conglomerates with precursor synthesis expertise. Tier-one cathode material producers maintain steep qualification barriers through automotive OEM validation programs. Two strategic archetypes dominate: upstream-integrated miners controlling lithium brine or nickel laterite assets, and downstream-integrated specialists commanding closed-loop recycling capabilities. Competitive intensity centers on backward integration into mineral feedstocks and geographic diversification of precursor manufacturing to satisfy regional content rules.
Within the diversified chemical conglomerate tier, BASF and Umicore exemplify archetypes built on petrochemical process expertise and circular materials technology respectively. Albemarle Corporation anchors the upstream-integrated miner category through its Chilean and Australian brine asset positions. POSCO Future M occupies a distinctive position as a steel-industry descendant leveraging metallurgical process knowledge for nickel sulfate refining and precursor co-precipitation.
| Leading Market Players |
|---|
| BASF |
| POSCO Future M |
| Asahi Kasei Corporation |
| Umicore |
| Sumitomo Metal Mining Co., Ltd. |
| Albemarle Corporation |
| LG Chem Ltd. |
| Samsung SDI Co., Ltd. |
| Johnson Matthey |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from concentrated cathode precursor production in Jiangsu province to European cell manufacturers, amplifying price spreads between contract offtake and spot market procurement while compressing margins for non-integrated buyers lacking captive nickel refining positions.
Pricing Analysis
Current-generation NMC811 cathode powders command substantial premiums over prior-generation NCM523 formulations, while next-generation solid-state electrolyte materials remain pre-commercial with pilot-scale pricing. Three-tier pricing structure across automotive-grade certified, industrial-grade standard, and emerging-economy economy levels separates qualified suppliers from unqualified competitors. Pricing pressure stems from Indonesian HPAL nickel sulfate flooding Asian precursor markets, eroding conversion margins. Energy storage developers exhibit highest price sensitivity due to lithium iron phosphate commoditization, whereas aviation battery buyers accept substantial premiums for cobalt-containing high-voltage spinels.
Supply Chain Analysis
Upstream brine evaporation in Chile's Atacama and spodumene hard-rock mining in Western Australia feed lithium carbonate and hydroxide conversion plants. Chinese spherical graphite processing in Shandong province and Korean polyolefin separator manufacturing in Gyeonggi-do anchor component supply. Single-source vulnerability concentrates in Indonesian nickel laterite processing, where export ban enforcement forces downstream investment commitments. Distribution runs through multi-year offtake agreements between tier-one cell manufacturers and automotive OEMs, displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cathode chemistry generations creates specialist niches as solid-state electrolyte development diverges procurement requirements from incumbent lithium-ion supply chains.
For Market Incumbents: Harden qualification barriers by deepening backward integration into Indonesian nickel sulfate production and accelerating closed-loop recycling certification under EU Battery Regulation thresholds. Sodium-ion chemistry industrialization threatens lithium-dependent incumbents with substitution risk in stationary storage segments. Captive precursor synthesis in Morowali Industrial Park offers defensive margin protection against Chinese cost competition. For New Entrants and Emerging Players: Establish a beachhead in hard carbon anode supply for sodium-ion stationary storage applications, where incumbent graphite suppliers lack positioning. European second-life battery direct recycling presents underdeveloped white-space with qualified feedstock scarcity. Partner with utility-scale storage developers in Texas and California through toll-processing arrangements to bypass capital-intensive electrode coating infrastructure. For Investors and Strategic Acquirers: Specialist ceramic electrolyte manufacturers with automotive OEM validation partnerships represent priority acquisition archetypes as solid-state commercialization accelerates. Long-term viability centers on chemistry-agnostic material recovery capabilities spanning lithium-ion and emerging sodium-ion architectures. Monitor ECHA substance evaluation waves for nickel compound authorization restrictions as inflection indicators for European precursor plant restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Nickel Integration | Indonesian laterite-to-sulfate projects in Sulawesi displace traditional matte export routes to China. |
| Solid-State Electrolyte Scale-Up | Japanese manufacturers pilot ceramic and sulfide production lines for premium EV platforms. |
| Closed-Loop Recycling Certification | Umicore and BASF facilities integrate EU Battery Regulation recycled content mandates into precursor output. |
| Sodium-Ion Chemistry Industrialization | Hard carbon anode and layered oxide cathode supply chains reduce lithium dependency for grid storage. |
| Direct Cell Procurement Contracts | North American utility developers bypass trading intermediaries through bilateral tier-one manufacturer agreements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed chemical conglomerates, and IEA critical mineral supply reports. Interviews with cathode precursor plant managers, automotive OEM battery procurement leads, and utility-scale storage developers informed demand-side assumptions. Technical validation drew from MIIT GB standard documentation and ECHA substance evaluation dossiers. Bottom-up cell production capacity modeling triangulated against top-down electric vehicle sales projections.
Forecast inputs span cathode chemistry generation, component manufacturing stage, and regional production cluster across the analysis window. Segmentation dimensions include product type, application end-use, and manufacturing stage complexity. CAGRs derive from installed capacity buildout trajectories and chemistry migration curves. Lithium carbonate-to-hydroxide conversion bottlenecks and solid-state electrolyte yield improvements constitute industry-specific forecast sensitivities.
Sensitivities concentrate around Indonesian export policy enforcement, EU Battery Regulation recycled content threshold acceleration, and solid-state manufacturing yield breakthroughs. Cross-checking against IEA critical mineral supply security benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
AAA Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Portable Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Iron Salt Battery Market
Batteries
Battery Separators Market
Batteries
Cobalt-Free Battery Market
Batteries
US Solar Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
High Voltage Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Zinc Ion Batteries Market
Batteries
Taiwan Battery Market