
 Axial Piston Pumps Market | 2026-2036
Axial Piston Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Axial Piston Pumps Market Outlook
Mobile equipment fleets is collapsing as the dominant buyer archetype as stationary industrial installations gain procurement share amid reshoring of manufacturing capacity. Bosch Rexroth AG leverages its captive drive technology portfolio to anchor European supply relationships for high-pressure applications. Parker Hannifin Corporation sustains North American channel control through integrated motion and control distribution. Kawasaki Heavy Industries dominates Asian mobile hydraulics through backward integration into precision casting and machining operations.
An axial piston pump converts rotational mechanical energy into hydraulic fluid pressure through a cylindrical block containing pistons arranged parallel to the drive shaft axis, typically achieving operating pressures exceeding 400 bar and displacement ranges from 10 to 1000 cc per revolution. These pumps serve as primary power units in closed-loop hydrostatic transmissions and open-circuit load-sensing systems across construction, agriculture, and industrial machinery. Variable displacement configurations command premium positioning due to their demand-responsive flow control and energy recovery capabilities, while fixed displacement variants occupy mature, price-sensitive segments in auxiliary circuits. Closed circuit installations concentrate margin pools in mining and heavy earthmoving where system integration complexity creates vendor stickiness.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing OEMs to specify higher-efficiency hydraulic architectures, directly elevating pump performance thresholds and certification burdens for component suppliers. ISO 4406 cleanliness standards and EU Machinery Directive safety requirements shape product design validation cycles and aftermarket filter replacement demand. Stakeholders must monitor how electrification of auxiliary functions in mobile equipment redistributes hydraulic power requirements across pump duty cycles.
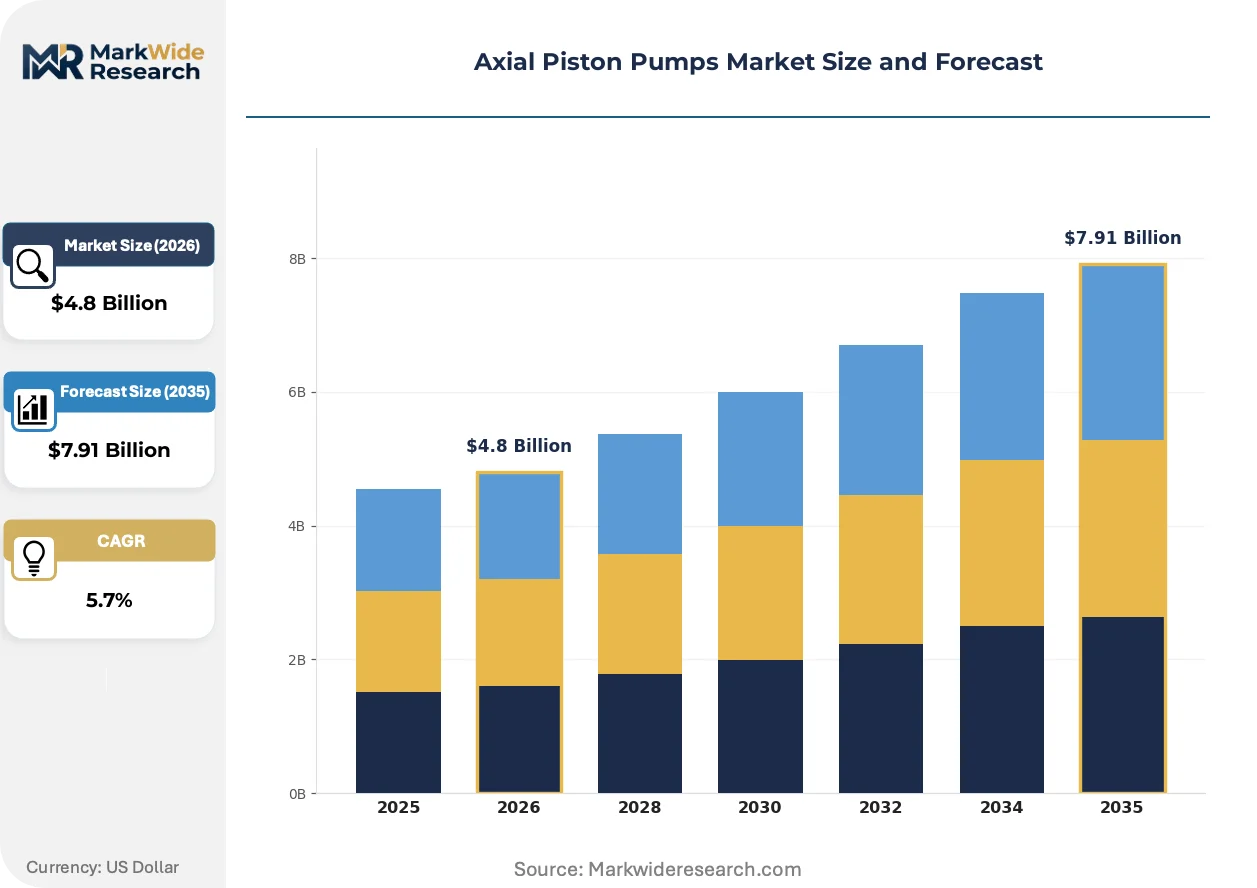
Market Dynamics
Emissions compliance deadlines are compressing hydraulic system procurement cycles as OEMs redesign powertrains around higher-efficiency architectures, forcing pump suppliers to recertify products under accelerated timelines while absorbing elevated R&D costs.
Growth Catalysts
- EPA Tier 4 Final mandates:US mobile equipment manufacturers are specifying variable displacement pumps to meet particulate and NOx thresholds, creating specification pull-through across construction and agriculture machinery.
- EU Stage V framework:European OEMs are eliminating lower-efficiency fixed displacement units from primary power circuits, redirecting procurement toward closed-loop hydrostatic systems with energy recovery.
- Precision casting clusters:Backward integration into high-pressure component manufacturing in Germany and Japan is compressing lead times for critical rotating groups and valve plates.
Market Restraints
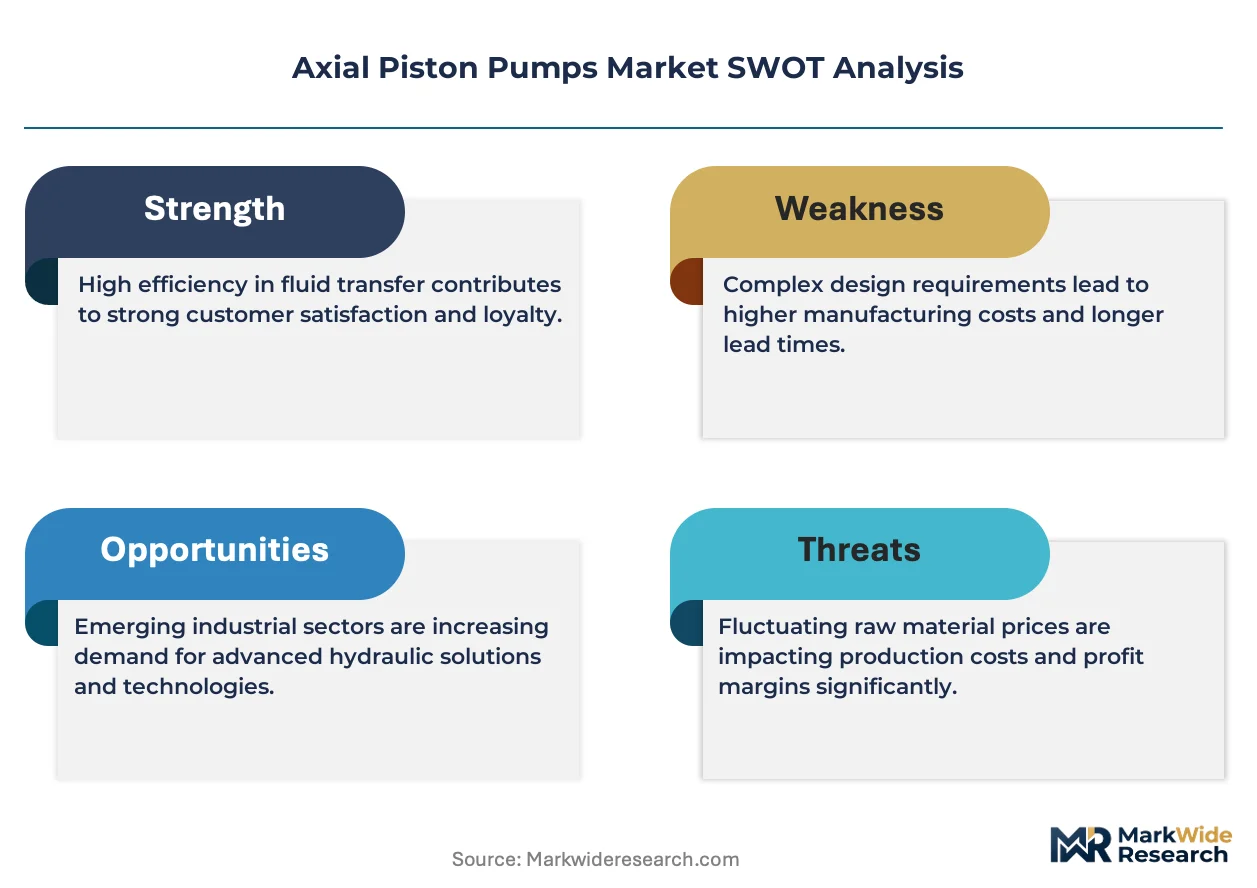
- Specialized alloy input costs:Nickel and chromium price volatility is squeezing margin structures for high-pressure cylinder block and piston manufacturing, particularly affecting mid-tier suppliers without long-term material hedging.
- Foundry concentration in East Asia:Overreliance on Taiwanese and South Korean precision machining capacity creates vulnerability to geopolitical disruption and shipping lane congestion.
- Electrification substitution:Battery-electric auxiliary systems in municipal and light-duty mobile equipment are displacing hydraulic power take-off requirements in sub-50kW applications.
Strategic Opportunities
- Reshoring manufacturing installations:New automotive and industrial plant construction in the US Southeast and Midwest is generating demand for stationary hydraulic power units in stamping and assembly lines.
- Digital pump monitoring:Integration of pressure sensors and edge computing into pump housings enables predictive maintenance contracts, opening recurring revenue streams for component suppliers.
- India PLI scheme:Production-linked incentives for construction equipment manufacturing in Tamil Nadu and Maharashtra are attracting pump suppliers to establish local assembly operations.
Industry Challenges
- ISO 4406 cleanliness validation:Extended certification timelines for high-pressure pumps under revised contamination standards are delaying new product introductions by 8-14 months.
- Legacy system integration:Retrofitting variable displacement units into existing open-circuit architectures requires custom manifold design, stretching application engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial Piston Pumps Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Displacement, Variable Displacement, Open Circuit, Closed Circuit Industry Vertical: Agriculture, Construction, Manufacturing, Automotive Installation Type: Mobile, Stationary, Integrated, Retrofit End User: OEMs, Tier-1 Suppliers, Maintenance Providers, System Integrators |
| Companies Covered | Bosch Rexroth AG, Danfoss, Parker Hannifin Corporation, Eaton Corporation, Kawasaki Heavy Industries, HAWE Hydraulik SE, Moog Inc., Daikin Industries, Liebherr-International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial Piston Pumps Market Strategic Shifts
Additive manufacturing of hydraulic manifolds is compressing prototyping cycles and enabling topology-optimized flow paths that were previously unmachinable, though production-scale adoption remains constrained by powder bed fusion throughput limitations.
Electro-hydraulic pump control is fragmenting the traditional mechanical-hydraulic interface as construction OEMs adopt CAN-bus integrated displacement actuators for real-time load matching. Caterpillar and Komatsu are phasing in electronically governed pumps across excavator lines above 20 tons. This convergence is compressing the addressable market for purely mechanical control systems and elevating software competency requirements among traditional pump suppliers.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing refrigerant-driven cooling system redesigns in mobile hydraulics, indirectly elevating pump thermal management specifications. OEMs are specifying wider operating temperature ranges and integrated oil cooling circuits to compensate for reduced auxiliary cooling capacity. German and Italian construction equipment manufacturers are most exposed, with compliance deadlines accelerating through 2027.
Fleet operators are consolidating supplier relationships around integrated motion control vendors rather than standalone pump procurement, compressing the viable channel structure for pure-play hydraulic component manufacturers. Large rental companies in the US and Western Europe are demanding single-source accountability for complete drive systems. This concentration is visible most acutely in the North American aerial work platform segment, where JLG and Genie parent companies have reduced qualified pump suppliers by 40% since 2022.
Axial Piston Pumps Market Segmentation
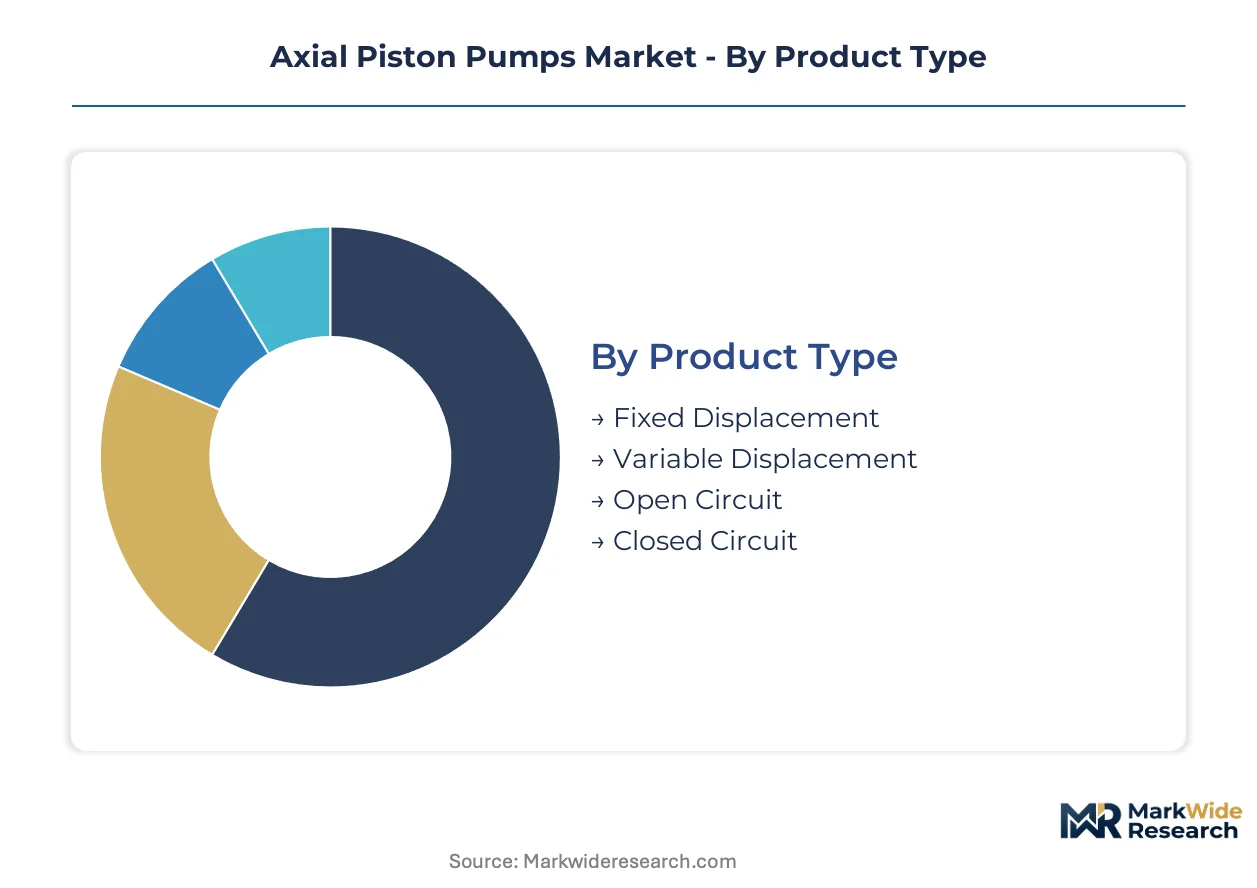
Axial piston pump procurement patterns diverge sharply across technical configurations and customer archetypes, with displacement architecture and circuit topology determining margin structures. Segmentation clarity enables suppliers to align R&D investment with the highest-value installation types.
Product Type:
Variable displacement configurations face the most acute electrification substitution pressure as battery-electric auxiliary systems displace hydraulic power in sub-50kW municipal equipment.
- Fixed Displacement:These pumps deliver constant flow per revolution regardless of system demand, employing simpler swashplate geometry at lower manufacturing cost. Demand concentrates in agricultural auxiliary circuits across the US Midwest and Brazilian soy belt, where price sensitivity dominates specification decisions and EPA Tier 4 compliance pressures remain lighter on secondary hydraulic systems.
- Variable Displacement:Swashplate angle modulation enables demand-responsive flow control with energy recovery capabilities in closed-loop architectures. Construction OEMs in Germany and Japan specify these units for excavators above 20 tons, where EU Stage V emissions frameworks mandate hydraulic efficiency gains to offset engine after-treatment power draws.
- Open Circuit:Return-line configurations suit load-sensing systems with multiple actuator branches, prevalent in manufacturing press lines.
- Closed Circuit:Hydrostatic transmission loops with charge pump circuits dominate mining haul trucks and heavy earthmoving where system integration complexity creates vendor stickiness.
Fixed displacement anchors the volume base while variable displacement gains share at the steepest rate.
Industry Vertical:
Cost tier segmentation reveals construction commanding premium positioning through specification complexity, while automotive faces the steepest margin compression from electrification substitution.
- Agriculture:Tractor hydraulic systems and combine harvester drives require pumps with wide temperature tolerance and contamination resistance. Demand clusters in Iowa, Illinois, and Mato Grosso where fleet replacement cycles accelerate amid commodity price volatility.
- Construction:Excavator, loader, and crane primary power circuits specify pressures exceeding 400 bar with integrated electronic displacement control. Japanese and German OEMs dominate specification authority, backward-integrating into precision casting for rotating groups.
- Manufacturing:Stamping press and injection molding power units favor stationary installations with predictive maintenance integration.
- Automotive:Transmission test stands and assembly line power packs represent a contracting segment as electric vehicle production reduces hydraulic fixture demand.
Construction commands the highest specification premiums while manufacturing expands most quickly through reshoring-related plant construction.
Installation Type:
Customer type segmentation shows OEMs consolidating procurement around integrated motion control vendors, compressing standalone pump channels.
- Mobile:On-machine installations in construction and agriculture equipment require compact packaging with integrated oil cooling circuits. US Southeast assembly plants and Tamil Nadu manufacturing clusters under India's PLI scheme drive specification volume.
- Stationary:Factory-floor power units for metal forming and plastics processing emphasize service accessibility and noise attenuation. Midwest US automotive transplants and Mexican maquiladora expansions anchor demand.
- Integrated:Pump-motor-reservoir assemblies supplied as complete drive systems to rental fleet operators.
- Retrofit:Replacement installations in legacy open-circuit architectures require custom manifold engineering, stretching application support capacity.
Mobile installations dominate unit volume while integrated systems climb the fastest through fleet operator consolidation.
End User:
Supply concentration segmentation reveals OEMs and Tier-1 suppliers co-locating manufacturing in Germany, China, and the United States, while maintenance providers fragment geographically.
- OEMs:Original equipment manufacturers specify pumps at the powertrain design stage, locking in displacement architecture and control interfaces for production runs exceeding 10,000 units. Caterpillar and Komatsu exercise particular influence through electronically governed pump adoption across excavator lines.
- Tier-1 Suppliers:Drive system integrators like Bosch Rexroth and Parker Hannifin bundle pumps with motors and controls, capturing specification authority through single-source accountability contracts.
- Maintenance Providers:Aftermarket replacement demand concentrates in filter and seal consumables, with ISO 4406 cleanliness validation driving recurring revenue.
- System Integrators:Custom hydraulic designers serve specialized industrial applications with low volume but high margin potential.
OEMs anchor the volume base while Tier-1 suppliers gain share at the steepest rate through integrated motion control bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision casting clusters and Japanese machining operations anchor high-pressure component supply chains, while US Southeast assembly plants and Chinese construction equipment manufacturing concentrate procurement volume.
United States
Mobile construction equipment OEMs in the US Southeast are expanding variable displacement pump procurement to meet EPA Tier 4 Final emissions thresholds. The Department of Energy efficiency mandates are accelerating hydraulic system redesigns in municipal fleets. Caterpillar's Illinois and Texas assembly plants are specifying electronically governed pumps across excavator lines above 20 tons.
Germany
EU Stage V compliance deadlines are eliminating fixed displacement units from primary power circuits in German construction machinery. The country's national automotive regulator KBA is enforcing stricter hydraulic efficiency certifications for mobile equipment type approval. Stuttgart and Munich industrial corridors host backward-integrated suppliers controlling precision casting for rotating groups and valve plates.
China
Domestic construction equipment manufacturers are localizing variable displacement pump production to reduce import dependency in high-pressure applications. MIIT industrial efficiency standards are mandating energy recovery capabilities in new hydraulic architectures. Xuzhou and Changzhou manufacturing clusters are attracting foreign joint ventures for closed-loop hydrostatic transmission assembly.
Japan
Komatsu's adoption of CAN-bus integrated displacement actuators is compressing the addressable market for purely mechanical control systems. METI carbon neutrality roadmaps are elevating pump thermal management specifications in mobile hydraulics. Osaka and Nagoya precision machining centers maintain captive supply of high-pressure cylinder blocks through in-house casting operations.
India
Production-linked incentives for construction equipment manufacturing in Tamil Nadu and Maharashtra are attracting pump suppliers to establish local assembly operations. The central electricity authority CEA is drafting efficiency standards for industrial hydraulic power units. Chennai and Pune automotive transplants are generating demand for stationary installations in stamping and assembly lines.
Axial Piston Pumps Market Competitive Environment
Concentration sits with diversified motion control conglomerates that bundle pumps with motors and electronic controls, while pure-play hydraulic component manufacturers face channel compression from fleet operator consolidation. Japanese and German industrial groups anchor high-pressure technology tiers through captive precision manufacturing. Two dominant competitive moves are reshaping positioning: integrated motion control bundling that captures specification authority through single-source accountability contracts, and backward integration into precision casting clusters that compress lead times for critical rotating components.
Among Germany-based diversified industrial groups, Bosch Rexroth AG and HAWE Hydraulik SE represent the integrated motion control archetype, occupying positions where hydraulic component expertise converges with electronic control system development. Parker Hannifin Corporation exemplifies the North American channel control model, anchoring specification authority through distribution networks spanning integrated motion and control systems. Kawasaki Heavy Industries sits within the Asian mobile hydraulics specialization, representing backward integration into precision casting and machining operations that supply construction equipment OEMs.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Danfoss |
| Parker Hannifin Corporation |
| Eaton Corporation |
| Kawasaki Heavy Industries |
| HAWE Hydraulik SE |
| Moog Inc. |
| Daikin Industries |
| Liebherr-International AG |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final certification gates both supplier qualification and price differentiation simultaneously, as OEMs demand ISO 4406-validated cleanliness tiers that stratify component vendors by compliance investment and technical capability. Variable displacement units command substantial premiums over fixed displacement alternatives where emissions mandates apply, while mid-tier suppliers without captive precision casting face margin compression from alloy input volatility.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across construction and agriculture equipment procurement, with three-tier pricing separating certified closed-loop systems from standard open-circuit units and economy-grade auxiliary pumps. Price differentiation rests on ISO 4406 cleanliness grade and electronic displacement control integration, with German and Japanese OEMs paying substantial premiums for CAN-bus compatible architectures. Cost compression in fixed displacement tiers is intensifying because agricultural buyers in the US Midwest and Brazilian soy belt prioritize first-cost over lifecycle efficiency. Fleet operators consolidating around integrated motion control vendors exhibit the lowest price sensitivity, while independent maintenance providers remain highly cost-conscious.
Supply Chain Analysis
Inventory cycles for high-pressure cylinder blocks and valve plates stretch 16-24 weeks, compressing OEM procurement flexibility during emissions compliance deadlines. Precision casting capacity concentrates in Germany, Japan, and Taiwan, with nickel and chromium alloy supply drawing from South African and Indonesian mining operations. Single-source vulnerability sits with Taiwanese precision machining clusters, where geopolitical disruption risks cascade through rotating group availability. Distribution runs through integrated motion control vendors bundling pumps with motors and electronic controls, displacing standalone component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as electrification of sub-50kW auxiliary systems splinters demand, opening niches for specialized suppliers in high-pressure mining applications and predictive maintenance-enabled units. Reshoring of manufacturing capacity generates new stationary installation demand outside traditional mobile equipment channels.
For Market Incumbents: Consolidate specification authority through backward integration into precision casting clusters in Germany and Japan, compressing lead times for critical rotating groups while absorbing alloy cost volatility through captive supply. Defend against electrification substitution by embedding pressure sensors and edge computing into pump housings, opening recurring predictive maintenance revenue streams that bind fleet operators through service contracts rather than component transactions. For New Entrants and Emerging Players: ISO 4406 certification fast-tracks market entry for suppliers targeting the retrofit segment, where legacy open-circuit architectures require custom manifold engineering that stretches incumbent application engineering capacity. Target India's Tamil Nadu and Maharashtra construction equipment clusters under the PLI scheme, where local assembly operations qualify for production-linked incentives while serving underpenetrated aftermarket demand. Lead with digital pump monitoring capabilities as the primary go-to-market angle, differentiating against mechanical-control legacy suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates pruning non-core hydraulic divisions amid portfolio streamlining pressures. Five-to-ten year viability hinges on positioning within closed-loop hydrostatic transmission architectures where system integration complexity creates vendor stickiness. Monitor electrification penetration rates in municipal equipment as the critical inflection signal, with battery-electric auxiliary adoption above 35% in sub-50kW applications indicating structural demand contraction for traditional pump suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of high-pressure rotating groups compresses lead times and insulates margin structures from nickel and chromium volatility. |
| Digital Pump Monitoring Integration | Pressure sensors and edge computing enable predictive maintenance contracts, shifting revenue from transactional component sales to recurring service streams. |
| Local Assembly Operations in India | Tamil Nadu and Maharashtra facilities under PLI scheme access production-linked incentives while serving reshoring-driven manufacturing demand. |
| CAN-Bus Control Interface Development | Electronic displacement actuators align with Caterpillar and Komatsu excavator specifications above 20 tons, capturing specification authority. |
| ISO 4406 Certification Investment | Cleanliness validation tiers qualify suppliers for EU Stage V and EPA Tier 4 Final OEM procurement, gating access to premium pricing pools. |
Study Parameters
A spread of perspectives from OEM procurement teams, Tier-1 drive system integrators, aftermarket maintenance providers, and precision casting facility managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with hydraulic system engineers and plant-level sourcing directors, validated against customs records for high-pressure component trade flows, SEC filings from diversified motion control conglomerates, and emissions certification databases from EPA and EU type-approval registries. Bottom-up unit demand estimates triangulated against top-down equipment production forecasts.
Segmentation dimensions modeled include displacement architecture, circuit topology, industry vertical, and installation type, with additional granularity on electronic control integration levels across the projection horizon. CAGRs derived from equipment fleet replacement cycles, emissions compliance deadline clustering, and reshoring-related manufacturing construction permits. Forecast inputs incorporated alloy price futures for nickel and chromium, precision casting capacity utilization rates, and electrification penetration assumptions for municipal equipment segments.
Decision-makers should treat outputs as directional under base assumptions of sustained emissions regulatory stringency and moderate electrification substitution; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Industrial Pumps Market