
 Double Diaphragm Pump Market | 2026-2036
Double Diaphragm Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Double Diaphragm Pump Market Intelligence
Divergence in material science and control automation is recalibrating the competitive landscape between high-performance, specialized pumps and lower-cost, general-purpose units. Ingersoll Rand Inc. leverages its extensive distribution network to serve both premium and standard segments. Graco Inc. differentiates through its focus on fluid handling systems for specific, high-viscosity applications in manufacturing. Meanwhile, Yamada Corporation sustains a strong position in the Asia-Pacific region with its durable and reliable air-operated models.
A double diaphragm pump is a type of positive displacement pump that utilizes two reciprocating flexible diaphragms to move fluid. Its sealless, leak-free design makes it ideal for transferring abrasive, viscous, or hazardous liquids without contamination. Within applications, the chemical processing and water treatment sectors command significant volume due to stringent safety requirements. Material selection is critical, with polypropylene and stainless steel models dominating based on chemical compatibility and sanitation needs.
Regulatory frameworks like the EU's ATEX directives for explosive environments and US EPA regulations on industrial fluid handling directly influence pump design and material certification. Compliance with international standards, including various ISO certifications for manufacturing quality, is a prerequisite for market access in critical industries. Vendor selection will increasingly hinge on the ability to provide certified, energy-efficient solutions that minimize operational downtime and environmental risk.
Market Dynamics
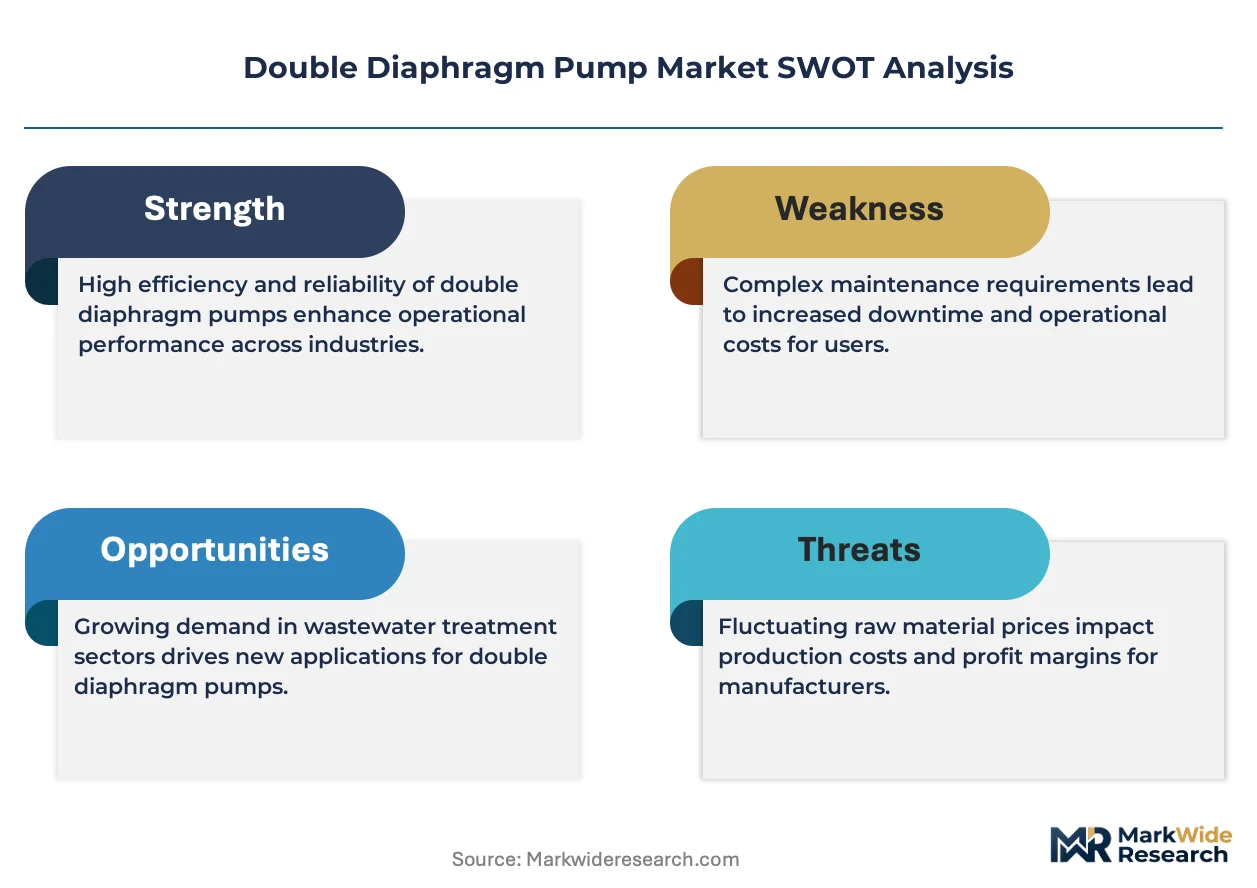
The convergence of stringent environmental regulations and advancements in material science is the central force shaping the double diaphragm pump market, compelling a move towards certified, application-specific solutions over general-purpose units to mitigate operational and compliance risks.
Growth Catalysts
- Regulatory Mandates:Stricter safety standards, such as the EU's ATEX directives for explosive atmospheres, compel chemical and petrochemical facilities to adopt sealless pump designs to prevent hazardous leaks, directly boosting demand.
- Water Treatment Expansion:Growing investment in municipal and industrial water and wastewater treatment infrastructure globally requires pumps capable of handling abrasive slurries, corrosive chemicals, and variable flow rates without frequent failure.
- Industrial Modernization:Replacement cycles and capacity expansions in manufacturing hubs, particularly in China's chemical sector and Germany's automotive industry, drive demand for more energy-efficient and reliable pump technologies to improve operational efficiency.
Market Restraints
- High Initial Investment:The upfront cost of pumps constructed from specialized materials like PVDF or Hastelloy, required for highly corrosive or high-purity applications, can be a significant barrier compared to lower-cost pump technologies.
- Inherent Pulsation:The reciprocating action of the diaphragms creates a pulsating flow, which can be detrimental to sensitive downstream processes and often requires the additional cost and complexity of pulsation dampeners to mitigate.
- Substitution from Peristaltic Pumps:In low-pressure, sanitary applications within the food, beverage, and pharmaceutical industries, peristaltic pumps present a strong alternative due to their gentle handling of fluids and ease of cleaning.
Strategic Opportunities
- Smart Pump Integration:Incorporating IoT sensors for predictive maintenance and remote monitoring allows for the development of outcome-based service models, offering uptime guarantees and reducing total cost of ownership for end-users.
- Battery Manufacturing Applications:The rapid expansion of electric vehicle battery production creates a new, high-growth application for chemically resistant pumps to handle abrasive and hazardous electrolyte slurries and precursor chemicals.
- Expansion in Southeast Asia:Rapid industrialization in countries like Vietnam and Indonesia presents an underpenetrated market for double diaphragm pumps, particularly in the growing food processing, textile, and chemical manufacturing sectors.
Industry Challenges
- Technician Skill Gaps:A shortage of maintenance personnel with dual expertise in both traditional mechanical pump repair and modern electronic control systems complicates diagnostics and servicing of increasingly sophisticated "smart" pumps.
- Certification Complexity:Navigating the lengthy and expensive certification pathways for different markets and applications, such as FDA food-contact compliance or 3-A Sanitary Standards, creates significant barriers to entry and slows product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Diaphragm Pump Market |
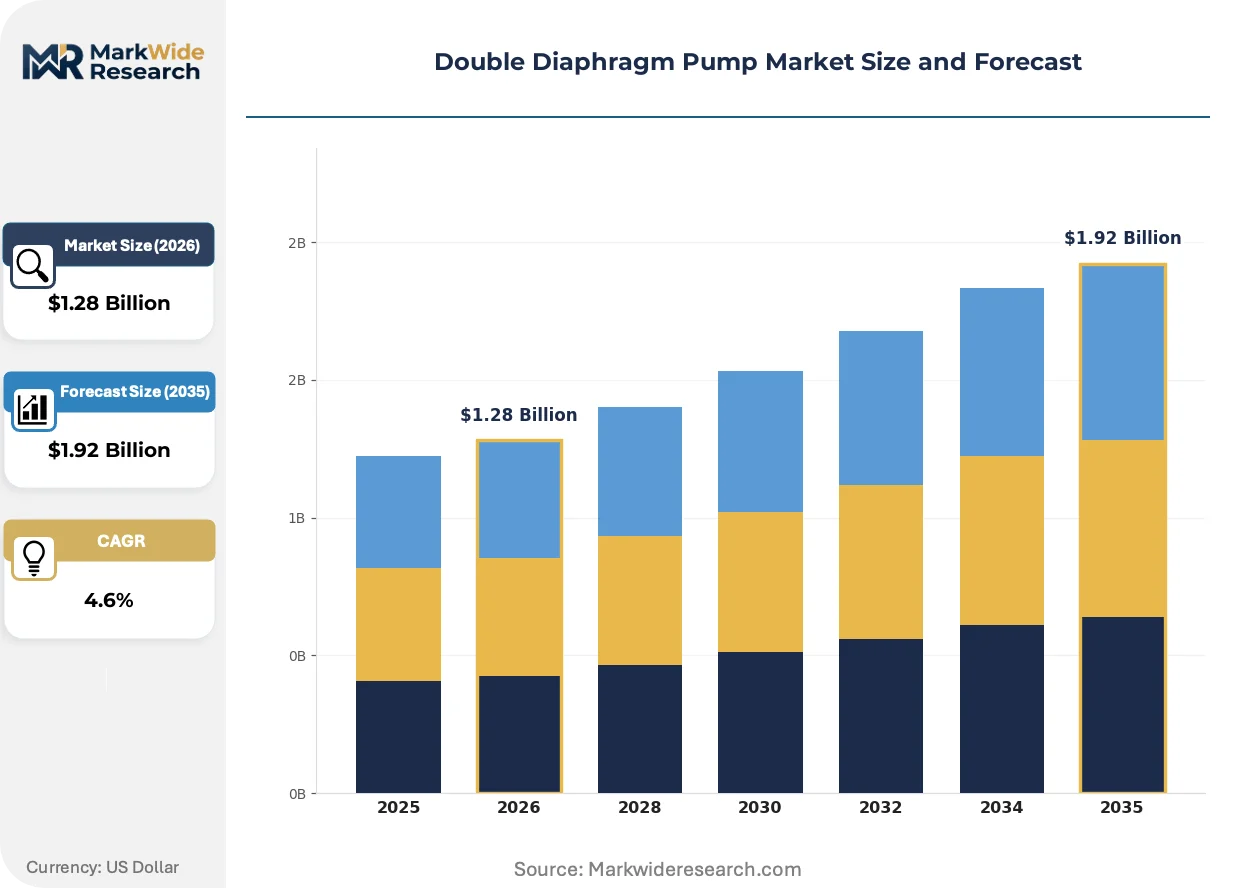
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Operated, Hydraulic-Operated, Electric-Operated, Solenoid-Operated Application: Chemical Processing, Water Treatment, Food & Beverage, Mining, Paint & Coating Material: Polypropylene, Stainless Steel, Aluminum, PVDF, Nylon End User: Oil & Gas, Pharmaceuticals, Pulp & Paper, Agriculture, Construction |
| Companies Covered | Ingersoll Rand Inc., Verder Group B.V., Graco Inc., All-Flo, Yamada Corporation, IDEX Corporation, Tapflo Group, ARO Inc., Dover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Diaphragm Pump Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards intelligent systems that enhance safety, efficiency, and process control. This shift prioritizes integrated solutions over standalone components, reflecting a deeper alignment with end-user operational goals like reduced downtime and verifiable compliance.
Smart control systems incorporating embedded sensors are becoming a key feature. These systems monitor critical parameters like flow rate, pressure, and diaphragm condition in real time. The chemical processing and biopharmaceutical sectors are early adopters, seeking to improve batch consistency and create a verifiable data trail for regulatory compliance. This integration of onboard diagnostics and remote connectivity is automating fault detection and preventative maintenance schedules, reducing unplanned downtime.
European Union regulations, particularly REACH, are tightening requirements for material composition in fluid handling equipment. This policy forces manufacturers to document and often restrict the use of certain substances in pump components that come into contact with process fluids. Consequently, pump suppliers targeting the EU must invest heavily in material science and certification to offer compliant models using materials like certified grades of PTFE and stainless steel.
A notable behavioral shift is occurring as end-users move from purchasing individual pumps to procuring complete, pre-engineered fluid transfer systems. This trend favors manufacturers and system integrators who can deliver fully assembled and tested skids, complete with valves, piping, and controls. This system-level procurement is most prominent in the semiconductor and pharmaceutical industries, where process integrity, cleanliness, and rapid deployment are critical priorities.
Double Diaphragm Pump Market Segmentation
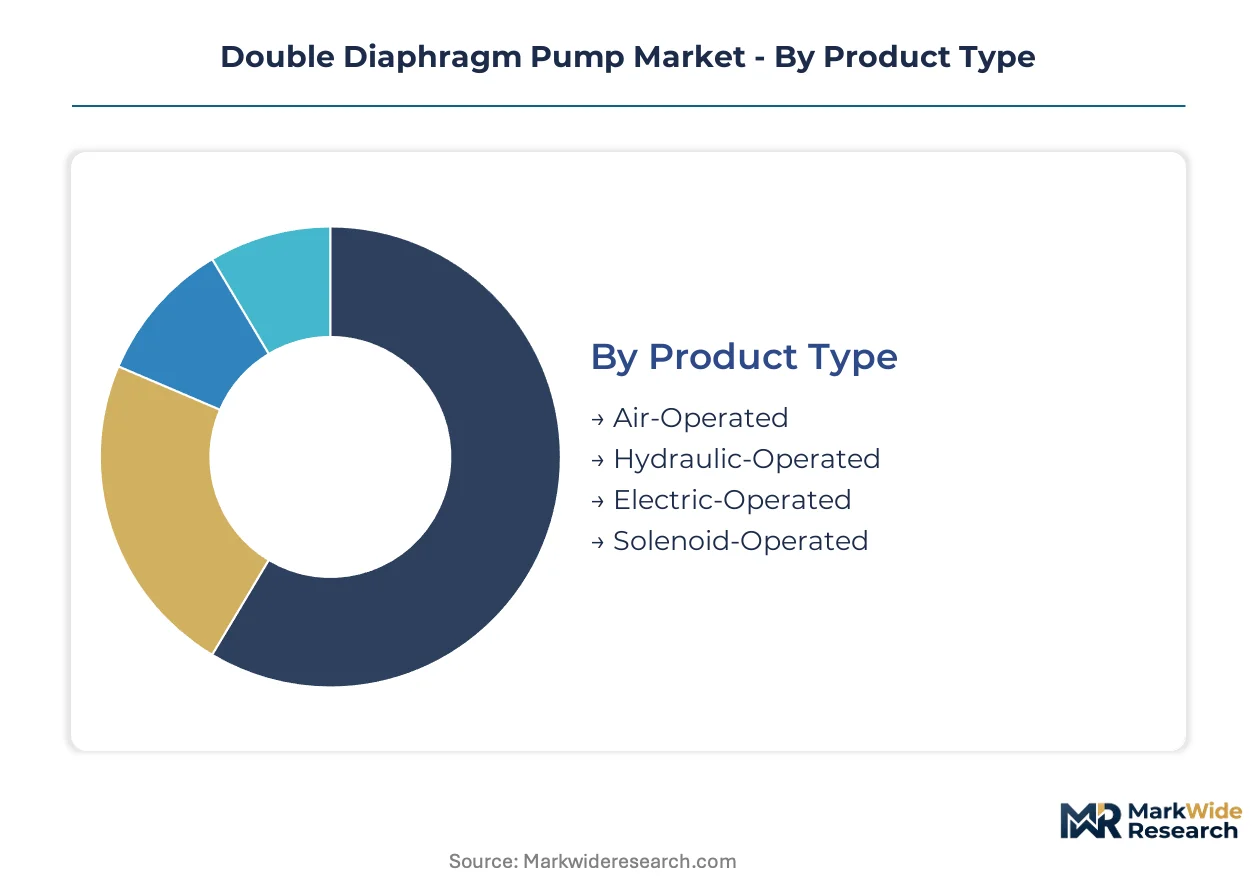
The double diaphragm pump market exhibits diverse segmentation, reflecting varied requirements across industrial applications and material compatibility needs. Understanding these distinct segments is crucial for manufacturers to tailor product development and for end-users to optimize procurement strategies.
Product Type:
Manufacturing for double diaphragm pump product types concentrates around established technology hubs, influencing market availability and pricing structures.
- Air-Operated:Utilizes compressed air to oscillate diaphragms, offering intrinsic safety for hazardous environments and intermittent operations. Demand concentrates in chemical processing facilities in Germany for robust fluid transfer.
- Electric-Operated:Employs an electric motor to drive diaphragms, providing precise flow control and enhanced energy efficiency. Demand is concentrating in pharmaceutical manufacturing in the US for batch consistency and automation.
- Hydraulic-Operated:Uses hydraulic fluid to actuate diaphragms, suitable for high-pressure and high-viscosity applications in heavy industry.
- Solenoid-Operated:Features an electromagnetic solenoid for precise, low-volume dosing in analytical and laboratory settings requiring accuracy.
Air-Operated pumps absorb the bulk of installed capacity; Electric-Operated units are expanding most quickly.
Application:
The functional demands of various applications dictate pump design and material selection, driving specialization across end-use sectors.
- Chemical Processing:Requires pumps capable of handling aggressive acids, solvents, and viscous polymers without leakage or contamination. Demand concentrates in China's industrial chemical complexes due to stringent environmental mandates.
- Water Treatment:Involves transferring abrasive slurries, corrosive chemicals, and disinfectants in municipal and industrial facilities. Demand is concentrating in India's expanding water infrastructure projects for reliable dosing.
- Food & Beverage:Demands hygienic designs for transferring edible liquids, sauces, and purees, ensuring product integrity and sanitation.
- Mining:Utilizes rugged pumps for dewatering, slurry transfer, and chemical dosing in harsh operational conditions and remote sites.
- Paint & Coating:Needs pumps that can handle abrasive pigments and shear-sensitive formulations in automotive and industrial painting operations.
Adoption is highest in chemical processing, while water treatment shows the most significant growth.
Material:
Material science advancements continuously refine the chemical compatibility and mechanical durability of pump components, influencing performance across diverse fluid types.
- Polypropylene:Offers excellent chemical resistance to many acids and bases at moderate temperatures, providing a cost-effective solution. Demand concentrates in general industrial applications in Vietnam for chemical transfer.
- Stainless Steel:Provides superior mechanical strength, corrosion resistance, and hygienic properties, critical for sanitary and high-purity applications. Demand is concentrating in pharmaceutical manufacturing in Germany for sterile processing.
- Aluminum:Offers a lightweight and economical option for non-corrosive fluid transfer, commonly found in general industrial settings.
- PVDF:Provides high resistance to aggressive chemicals and elevated temperatures, essential for specialized chemical processing.
- Nylon:Used for non-corrosive, abrasive applications where impact resistance and wear properties are important.
Material selection prioritizes polypropylene for broad utility, while specialized applications increasingly rely on PVDF.
End User:
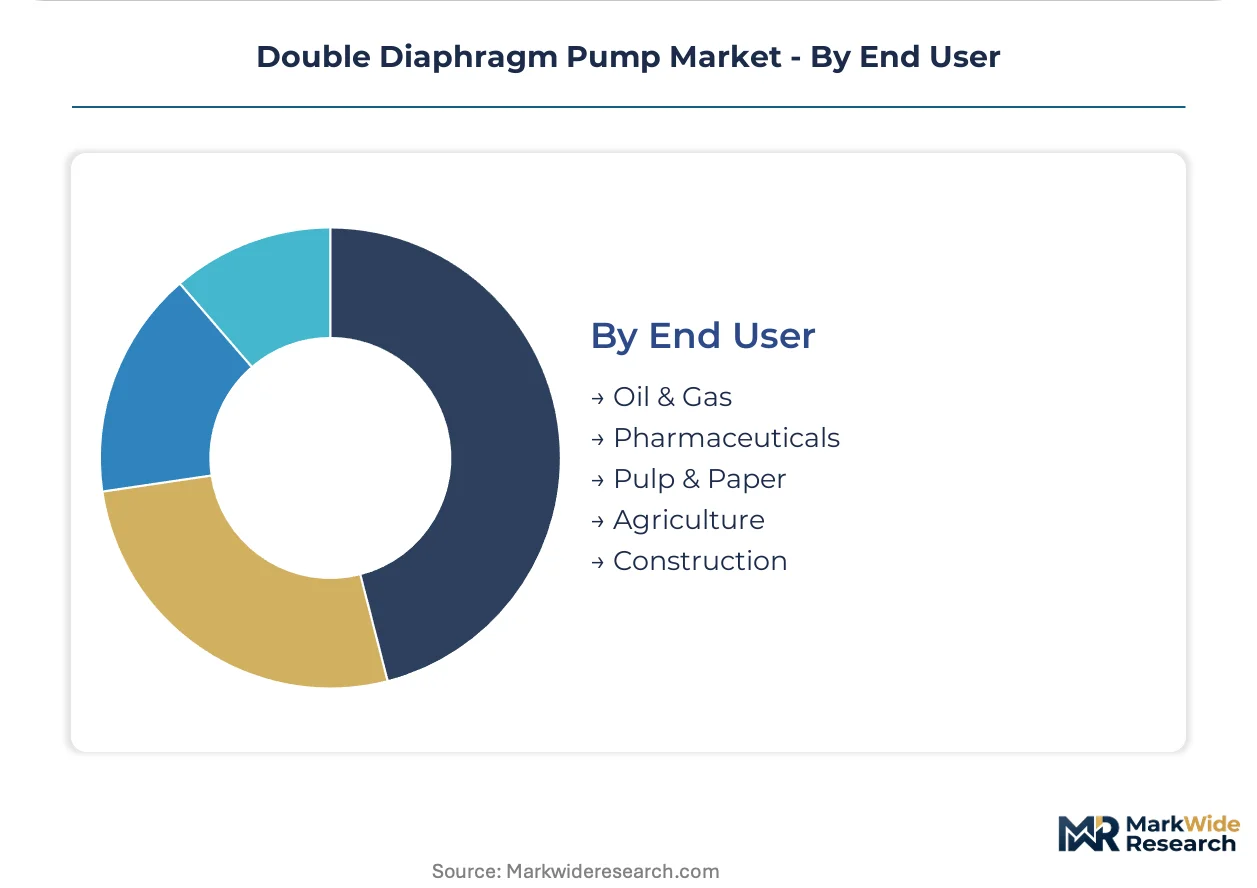
Distinct operational requirements and safety protocols within each end-user sector drive the specific configuration and performance demands for double diaphragm pumps.
- Oil & Gas:Requires robust pumps for transferring crude oil, drilling muds, and various chemicals in upstream and downstream operations. Demand concentrates in the US for fracking fluid management.
- Pharmaceuticals:Demands sterile, leak-free pumps for handling active pharmaceutical ingredients, solvents, and buffer solutions. Demand is concentrating in Ireland's biopharmaceutical manufacturing clusters.
- Pulp & Paper:Utilizes pumps for handling abrasive slurries, corrosive bleaching agents, and process water in paper production facilities.
- Agriculture:Employs pumps for transferring fertilizers, pesticides, and irrigation water across diverse farming operations.
- Construction:Uses durable pumps for dewatering, grout transfer, and concrete pumping on various job sites.
The largest volume of pumps serves the Oil & Gas sector, with the Pharmaceuticals sector exhibiting strong expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region in China leads global industrial activity, driving significant demand for double diaphragm pumps. This region's rapid industrialization and stringent environmental mandates necessitate advanced fluid transfer solutions. Manufacturing hubs across Europe and North America also contribute substantially to market expansion.
China
Demand for double diaphragm pumps in China stems from its expansive chemical processing sector and rapid industrial modernization. Beijing's dual carbon goals and the Ministry of Ecology and Environment (MEE) regulations push for safer, more efficient industrial processes. Industrial chemical complexes in the Yangtze River Delta actively invest in new installations and replacement cycles for compliant fluid handling.
Germany
Germany's advanced manufacturing and chemical industries generate substantial demand for high-performance double diaphragm pumps. The EU's REACH regulations and ATEX directives mandate sealless designs for hazardous fluid transfer, ensuring operational safety. Key industrial clusters in North Rhine-Westphalia and Bavaria show strong adoption for robust fluid transfer systems.
United States
The United States market is driven by robust pharmaceutical manufacturing and extensive oil & gas operations, particularly for fracking fluid management. The US Environmental Protection Agency (EPA) regulations govern industrial fluid handling, promoting leak-free and safe pump technologies. Biopharmaceutical manufacturing clusters in the Northeast Corridor and California utilize these pumps for precise, sterile processing.
India
India's booming water treatment infrastructure and expanding industrial base fuel the need for reliable double diaphragm pumps. The country's national water treatment policies and urban development initiatives require pumps for handling abrasive slurries and corrosive chemicals. Major infrastructure projects in Maharashtra and Gujarat increasingly specify these pumps for efficient dosing applications.
Ireland
Ireland's prominent biopharmaceutical manufacturing clusters create significant demand for sterile and leak-free pump solutions. The Health Products Regulatory Authority (HPRA) and EU Good Manufacturing Practices (GMP) drive stringent requirements for process integrity. Manufacturing sites in Dublin and Cork are early adopters of advanced pump technologies for handling active pharmaceutical ingredients.
Double Diaphragm Pump Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology and application specificity within the double diaphragm pump market. The market exhibits a tiered structure, with specialized manufacturers focusing on high-performance units for critical applications. Strategic archetypes include global diversified industrial conglomerates and niche specialists in fluid handling systems. Competitive moves often involve portfolio diversification into adjacent fluid technologies and geographic expansion into emerging industrial hubs.
Within the global industrial sector, Ingersoll Rand Inc. exemplifies a diversified approach, leveraging its extensive network to serve a broad spectrum of premium and standard segments. Graco Inc. occupies a position as a specialist in fluid handling systems, particularly for high-viscosity applications in manufacturing. Meanwhile, Yamada Corporation, a Japan-based entity, anchors the Asia-Pacific region with its reputation for durable and reliable air-operated models. These entities collectively represent the varied strategies employed to capture market share, from broad reach to specialized solutions.
| Leading Market Players |
|---|
| Ingersoll Rand Inc. |
| Verder Group B.V. |
| Graco Inc. |
| All-Flo |
| Yamada Corporation |
| IDEX Corporation |
| Tapflo Group |
| ARO Inc. |
| Dover Corporation |
| Others |
Cost & Logistics Intelligence
Specialized material costs, particularly for PVDF and PTFE, elevate production expenses for double diaphragm pumps. These upstream material prices directly translate into higher premium pricing for certified units in critical chemical processing.
Pricing Analysis
Uptime guarantees and reduced total cost of ownership anchor value-based pricing for advanced double diaphragm pumps. The dominant pricing structure is hybrid, combining value-based models for high-performance units with transactional pricing for standard models. Price differentiation stems from strict certification levels like ATEX and FDA compliance, alongside comprehensive after-sales service packages. Pricing pressure softens in standard segments due to increasing competition, while pharmaceutical and biopharmaceutical end-users exhibit low price sensitivity for specialized, compliant solutions.
Supply Chain Analysis
Dual-sourcing requirements for critical components like specialized diaphragm materials are increasingly mandated by end-users to mitigate supply risks. Geographic supply concentration for double diaphragm pumps centers in manufacturing hubs across Germany, Japan, and China. Raw material dependencies include advanced polymers such as PTFE, various grades of stainless steel, and electronic components for integrated smart systems. Geopolitical tensions impacting specialized material availability present a structural supply chain risk, while distribution runs through a combination of direct sales and extensive regional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The double diaphragm pump market operates within supply constraints, particularly for high-purity diaphragm materials. Limited production capacity for certified PTFE and PVDF components props up pricing for critical pharmaceutical and chemical processing applications.
For Market Incumbents: Cement market leadership by investing in proprietary material science R&D, particularly for advanced diaphragm polymers, to counter substitution threats from peristaltic pumps. Acquire specialized component manufacturers to secure critical supply chains and enhance control over quality. Deepen certification investments, including 3-A Sanitary Standards and FDA compliance, to reinforce premium positioning. Expand outcome-based service models, leveraging IoT for predictive maintenance, to reduce customer operational downtime.
For New Entrants and Emerging Players: Underserved small-to-medium enterprises (SMEs) in rapidly industrializing regions present significant white-space opportunities. Target the burgeoning battery manufacturing sector, particularly for electrolyte slurries, and expanding water treatment infrastructure in Southeast Asia. The most penetrable segment involves air-operated polypropylene pumps for general chemical transfer in countries like Vietnam. A strategic go-to-market angle involves localized distribution partnerships offering robust technical support and rapid spare parts availability.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in Europe, particularly Germany, offering long-term viability. Demand for certified, energy-efficient pump solutions will remain strong over the next decade, driven by regulatory mandates and industrial modernization. Acquisition targets should include niche specialists possessing strong intellectual property in smart pump technology or advanced material formulations. The signal to watch is accelerating consolidation activity among smaller, specialized manufacturers with proprietary compliance certifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses rising industrialization and localized demand for cost-effective pump solutions in Vietnam and India. |
| R&D in Advanced Diaphragm Polymers | Develops new materials offering superior chemical resistance and durability for hazardous chemical processing. |
| IoT Integration for Predictive Maintenance | Provides end-users with real-time operational data, reducing downtime and enhancing process control. |
| Acquisition of Control System Specialists | Enhances capabilities in smart pump technology, offering integrated fluid transfer systems to biopharmaceutical clients. |
| Certification for Battery Manufacturing Applications | Unlocks access to the rapidly expanding electric vehicle battery production sector for electrolyte slurries. |
Research Approach
Multi-period observation of pump sales volumes, material consumption rates, and regulatory compliance filings anchored the trend analysis, supplemented by interviews. Primary research involved discussions with plant managers, procurement leads, R&D directors, and environmental compliance officers across diverse industries. Secondary validation drew from industry association reports, national trade statistics, and company financial disclosures. This approach ensured robust bottom-up and top-down triangulation of market insights.
An input-output matrix framework was employed to model market dynamics across the analysis window. Segmentation dimensions included product type, application, material, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical growth patterns and projected shifts in industrial investment and infrastructure spending. Key industry-specific forecast inputs included CAPEX spending in chemical processing facilities and electric vehicle battery production forecasts throughout the forecast period.
Revisions become necessary when unforeseen shifts in global trade policies or significant breakthroughs in alternative fluid transfer technologies materialize. Forecasts reflect assumptions regarding stable regulatory enforcement and continued industrial modernization. Deviation in major raw material supply or new environmental mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Chemical Pump Market