
 Worm Pumps Market | 2026-2036
Worm Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Worm Pumps Market Insights
Maintenance-as-a-service is consolidating what operators purchase alongside hardware, shifting contract structures toward uptime guarantees and predictive replacement scheduling. SEEPEX leverages its digital monitoring platform to anchor recurring revenue in European municipal accounts. Sulzer competes through specialized aftermarket networks that control spare parts logistics across Middle Eastern petrochemical corridors. Xylem differentiates by integrating sensor diagnostics directly into helical rotor housings, reducing unplanned downtime for wastewater clients.
A worm pump is a positive displacement rotary pump employing a single helical rotor turning eccentrically within a double-helical elastomer stator, creating sealed cavities that progress axially to move viscous, abrasive, or shear-sensitive fluids at rates typically from fractions of a gallon per minute to thousands of gallons per minute with pressures reaching several hundred psi. Single-threaded designs dominate mature oil extraction applications where reliability under high solids loading justifies premium pricing, while magnetic drive technology represents the fastest-expanding segment as chemical processors eliminate seal leakage risks in hazardous fluid handling. Multi-threaded configurations occupy margin-rich niches in pharmaceutical manufacturing where gentle product transfer preserves biologic integrity.
EPA effluent limitations under the Clean Water Act shape U.S. municipal procurement specifications, while REACH compliance in Europe restricts stator elastomer chemistries and drives material substitution programs. China's MEE enforces tighter industrial discharge standards that accelerate pump replacement cycles in Shandong and Jiangsu chemical clusters. Buyers must weigh total lifecycle cost against upfront capital outlay as regulatory stringency tightens maintenance and monitoring obligations across jurisdictions.
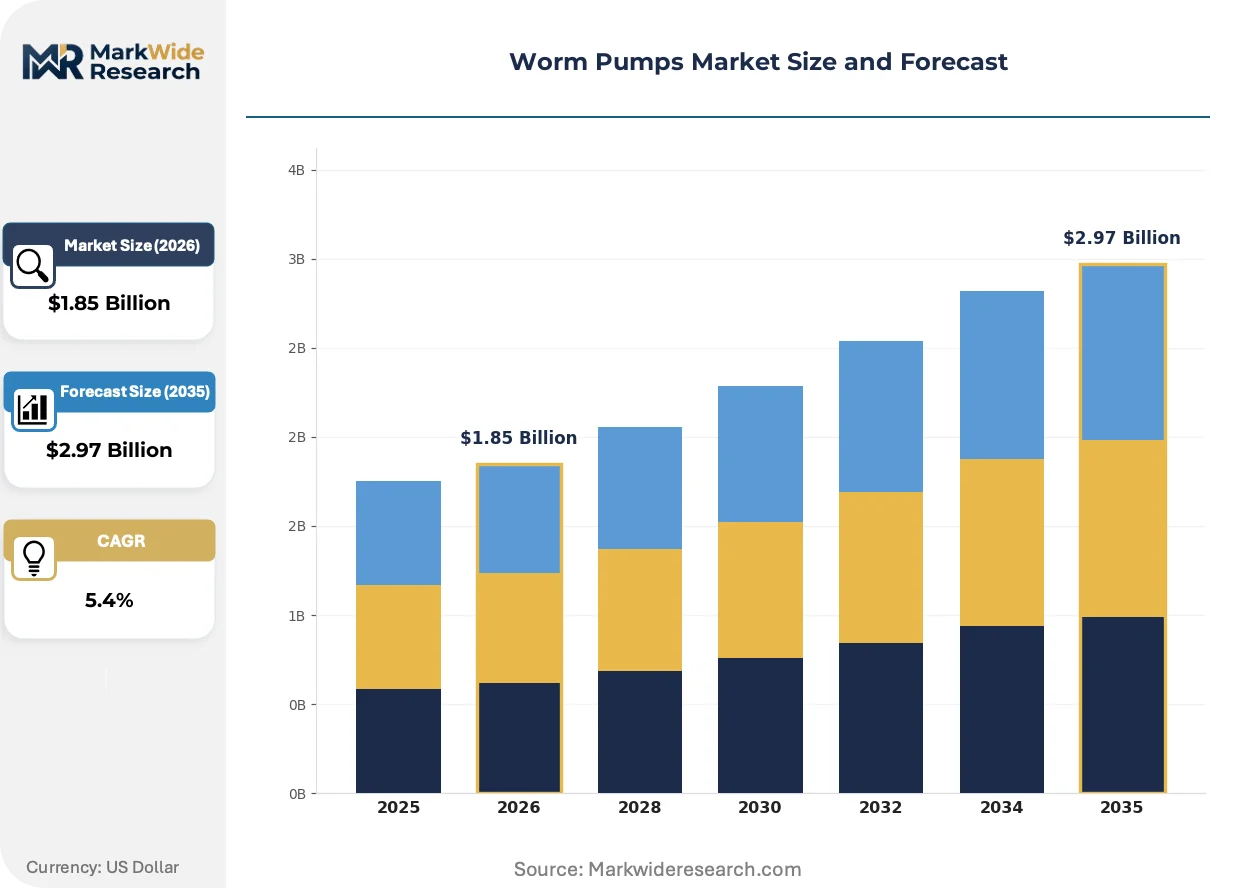
Market Dynamics
Maintenance-as-a-service contracting is compressing traditional equipment-only sales, forcing manufacturers to restructure revenue around uptime guarantees and predictive replacement scheduling rather than transactional hardware margins.
Growth Catalysts
- EU Green Deal effluent mandates:Wastewater treatment utilities in Germany are expanding progressive cavity pump fleets to meet tightening discharge standards, creating fleet renewal demand across municipal procurement cycles.
- Magnetic drive technology:Chemical processors are eliminating seal leakage risks in hazardous fluid handling, accelerating adoption in refineries and specialty chemical plants where containment failures carry catastrophic liability.
- Shandong and Jiangsu industrial clusters:China's MEE enforcement of tighter industrial discharge standards is accelerating pump replacement cycles in coastal chemical manufacturing corridors.
Market Restraints
- Elastomer input volatility:Stator rubber compounds face price instability tied to petroleum feedstock fluctuations and REACH compliance-driven material substitution costs in European manufacturing.
- Supply concentration in German stator production:Premium elastomer molding capabilities cluster with a limited supplier base, creating bottleneck risk for high-specification municipal and pharmaceutical orders.
- Centrifugal pump substitution:Lower-viscosity applications in water treatment increasingly migrate to centrifugal designs where abrasive solids loading permits, eroding addressable market for positive displacement units.
Strategic Opportunities
- India municipal infrastructure scaling:Urban wastewater treatment capacity expansion in tier-2 and tier-3 cities under central sanitation programs creates greenfield pump installation demand outside saturated metro markets.
- Biologics manufacturing:Multi-threaded gentle-transfer configurations serve pharmaceutical manufacturing where shear-sensitive protein integrity preservation commands premium positioning.
- Sensor-integrated predictive maintenance:Convergence of vibration monitoring with cloud analytics enables remote diagnostics contracts, shifting customer relationships toward recurring revenue models.
Industry Challenges
- Field service technician scarcity:Specialized stator replacement and rotor profiling skills concentrate with aging workforces in European and North American service networks, constraining aftermarket response capacity.
- Legacy SCADA integration friction:Digital monitoring platforms face protocol incompatibility with decades-old municipal control systems, delaying smart pump deployment in budget-constrained utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Worm Pumps Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Threaded, Multi-Threaded, Hollow Shaft, Split Casing Technology: Positive Displacement, Rotary, Helical Rotor, Dry Running, Magnetic Drive Application: Oil Extraction, Wastewater Treatment, Chemical Processing, Food & Beverage, Paper & Pulp End User Industry: Petrochemical Plants, Municipal Utilities, Pharmaceutical Manufacturing, Food Processing Units |
| Companies Covered | Grundfos, LEWA, KSB, Roto Pumps, SPX Flow, Sulzer, Flowserve, Xylem, SEEPEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Worm Pumps Market Trends and Innovations
Digital monitoring platforms are embedding directly into pump housings, transforming hardware vendors into service providers while compressing traditional aftermarket parts margins.
Magnetic drive sealless configurations are consolidating market share in chemical processing applications where fugitive emissions regulations tighten. Refinery operators in the US Gulf Coast and Rotterdam-Antwerp corridor are specifying magnetic drive progressive cavity units for benzene and xylene transfer, eliminating mechanical seal maintenance and enabling continuous duty cycles. This technology is consolidating supplier relationships around vendors with captive magnetic coupling design capabilities.
REACH compliance is restricting stator elastomer chemistries across European manufacturing, forcing material substitution programs for NBR and FKM compounds. ECHA substance evaluations are disqualifying legacy curatives and plasticizers, compelling reformulation investments that compress margins for mid-tier suppliers. German and Dutch pump OEMs are responding fastest, securing early regulatory acceptance for bio-based alternatives.
Outcome-based service contracting is displacing transactional spare parts purchasing in municipal wastewater accounts. European utilities now specify availability guarantees and penalty clauses for unplanned downtime, transferring operational risk to manufacturers. This restructuring concentrates purchasing power with vendors capable of predictive analytics and regional parts depots, squeezing smaller competitors from framework agreements.
Worm Pumps Market Segmentation
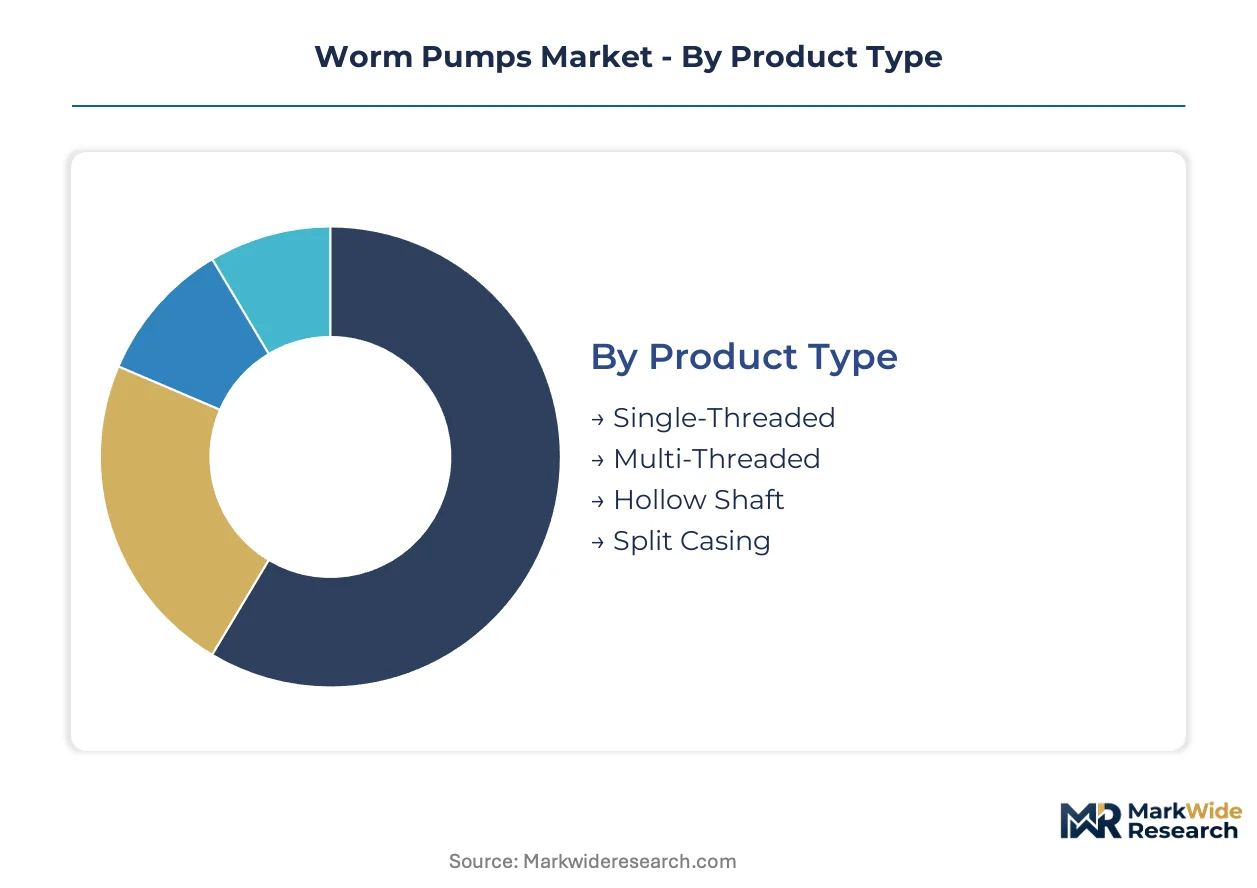
Worm pump procurement divides sharply between mature oilfield specifications and emerging magnetic drive chemical applications. Understanding these fault lines clarifies where manufacturers capture premium pricing versus commodity volume.
Product Type:
Single-threaded designs command the volume base, while multi-threaded and hollow shaft variants capture premium positioning in specialized transfer applications.
- Single-Threaded:One helical rotor engages a double-helical elastomer stator to create progressing sealed cavities. Oil extraction operations in mature fields across Texas and the North Sea specify these units for reliability under high solids loading and abrasive crude conditions.
- Multi-Threaded:Multiple thread starts reduce pulsation and shear rates during fluid transfer. Pharmaceutical biologics manufacturers in Switzerland and Massachusetts deploy these configurations where protein integrity preservation justifies substantial price premiums.
- Hollow Shaft:Central bore permits auxiliary functions like heating, cooling, or cleaning fluid circulation. Food processing lines handling viscous chocolate or dairy concentrates specify hollow shaft designs for CIP compatibility.
- Split Casing:Bisected housing enables rotor and stator access without full pump disassembly. Municipal wastewater utilities facing tight maintenance windows favor split casing geometry for reduced technician downtime.
Mature deployment sits with Single-Threaded configurations. Newer deployment is concentrated in Multi-Threaded pharmaceutical and food-grade specifications.
Technology:
Positive displacement principles anchor established applications, while magnetic drive sealless architectures are expanding most quickly in hazardous chemical handling.
- Positive Displacement:Fixed volume per revolution delivers consistent flow regardless of discharge pressure. Wastewater treatment facilities across Germany and the Netherlands specify positive displacement worm pumps for sludge transfer with variable solids content.
- Rotary:Continuous rotational motion eliminates reciprocating wear mechanisms. Paper and pulp mills in Finland and Canada deploy rotary helical designs for black liquor and stock handling where fiber consistency varies.
- Helical Rotor:Eccentric single-helix rotor within double-helix stator creates sealed progressing cavities. Standard municipal and industrial specifications default to helical rotor geometry for proven elastomer-stator sealing.
- Dry Running:Specialized stator materials tolerate transient loss of pumped fluid without catastrophic damage. Emergency drainage and intermittent duty applications in mining and construction specify dry-running capability.
- Magnetic Drive:Torque transmits through containment shell eliminating mechanical seals. US Gulf Coast and Rotterdam-Antwerp refineries specify magnetic drive progressive cavity units for benzene and xylene transfer under tightening fugitive emissions rules.
Helical rotor and positive displacement technologies dominate installed base maintenance cycles. Magnetic drive sealless configurations are gaining share fastest in chemical processing corridors.
Application:
Oil extraction and wastewater treatment represent the revenue foundation, while chemical processing and food-grade applications offer margin expansion potential.
- Oil Extraction:Artificial lift and surface transfer duties in heavy crude and oil sands operations. Canadian oil sands producers and Venezuelan heavy oil fields specify abrasion-resistant stator compounds for polymer-flooded production.
- Wastewater Treatment:Sludge transfer, thickened sludge handling, and dewatering feed applications. Municipal utilities under EU Green Deal and US EPA effluent mandates are renewing progressive cavity fleets for enhanced biological nutrient removal.
- Chemical Processing:Corrosive and hazardous fluid containment in specialty chemical and refinery operations. Magnetic drive adoption concentrates here as processors eliminate seal leakage risks.
- Food & Beverage:Gentle product transfer for viscous sauces, purees, and dairy concentrates. Hygienic design standards and 3A certification requirements shape procurement specifications.
- Paper & Pulp:Stock pumping, coating delivery, and black liquor handling in integrated mills. Abrasive fiber content and temperature cycling stress stator durability.
Oil extraction and wastewater treatment anchor replacement parts revenue. Food and beverage applications are climbing fastest on clean-label processing investments.
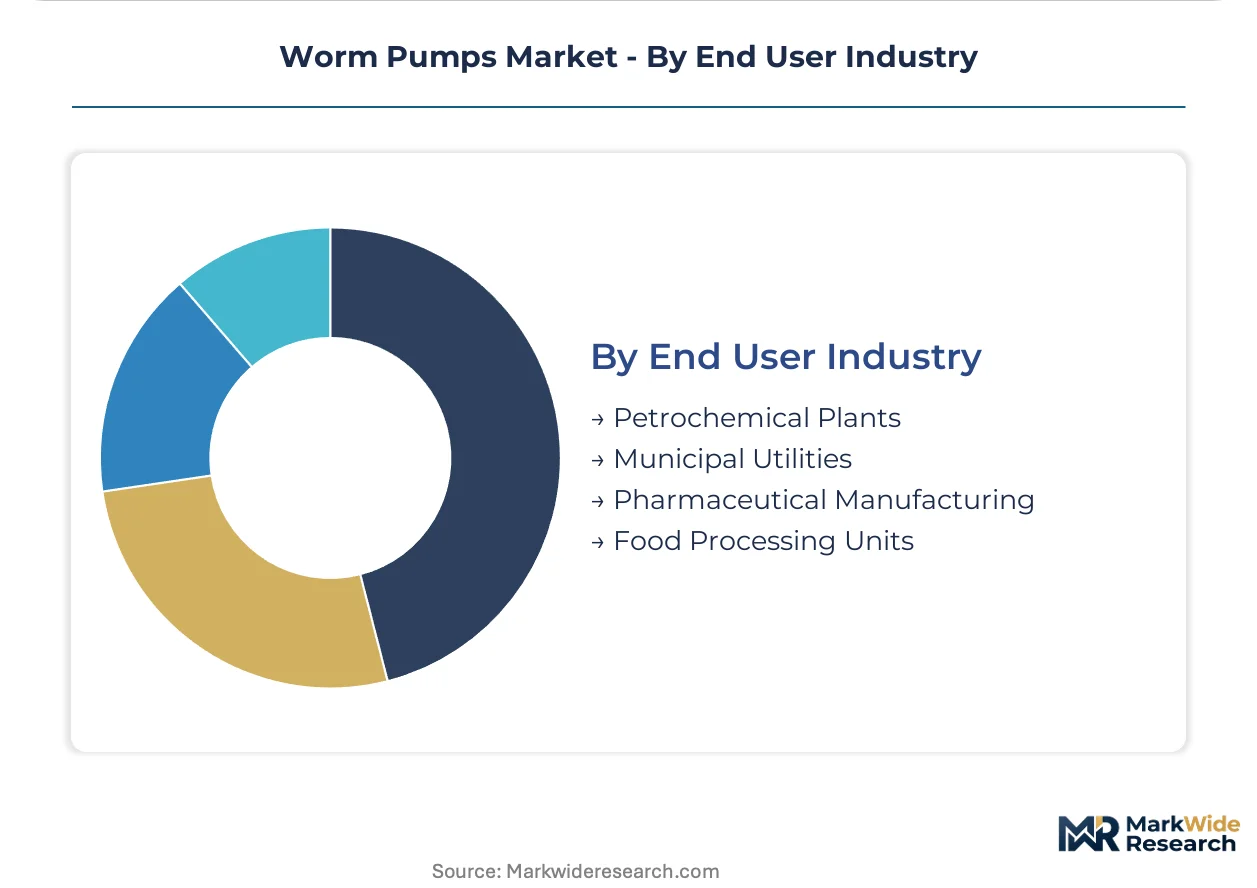
End User Industry:
Petrochemical and municipal accounts drive volume, while pharmaceutical manufacturing commands the steepest premium tiers.
- Petrochemical Plants:Integrated refineries and specialty chemical producers specify corrosion-resistant and sealless configurations. US and Middle Eastern petrochemical corridors prioritize magnetic drive technology for hazardous aromatic transfer.
- Municipal Utilities:Wastewater treatment authorities procure under public tender frameworks emphasizing lifecycle cost and availability guarantees. German utilities are expanding fleets under EU effluent mandates.
- Pharmaceutical Manufacturing:Biologics and sterile API production requires multi-threaded gentle-transfer designs with full validation documentation. FDA and EMA compliance requirements exclude commodity suppliers from qualified vendor lists.
- Food Processing Units:Dairy, beverage, and prepared food manufacturers specify hygienic designs with CIP/SIP compatibility. Clean-label trend investments are accelerating pump replacement cycles.
Municipal utilities and petrochemical plants represent the installed base core. Pharmaceutical manufacturing is expanding most quickly on biologics capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp petrochemical corridor anchors European demand for sealless pump configurations, while Shandong and Jiangsu industrial clusters in China concentrate replacement cycle activity under tightening discharge enforcement.
United States
Gulf Coast refineries specify magnetic drive progressive cavity units for benzene transfer under EPA fugitive emissions rules. The Clean Water Act shapes municipal procurement specifications for wastewater utilities. Houston and Beaumont petrochemical corridors drive premium specification demand for hazardous fluid containment.
Germany
Wastewater treatment utilities expand progressive cavity pump fleets under EU Green Deal effluent mandates. REACH compliance restricts stator elastomer chemistries and drives material substitution programs. North Rhine-Westphalia municipal authorities emphasize lifecycle cost frameworks in public tender processes.
China
Shandong and Jiangsu chemical manufacturing corridors accelerate pump replacement cycles under MEE enforcement of tighter industrial discharge standards. Municipal infrastructure scaling in tier-2 and tier-3 cities creates greenfield installation demand. Yangtze River Delta wastewater treatment capacity expansion concentrates procurement activity.
India
Urban wastewater treatment capacity expansion under central sanitation programs drives pump installation demand outside saturated metro markets. BIS standards shape equipment certification requirements for municipal procurement. Gujarat and Maharashtra industrial corridors specify progressive cavity units for chemical processing applications.
Switzerland
Pharmaceutical biologics manufacturers deploy multi-threaded gentle-transfer configurations where protein integrity preservation commands premium positioning. Swissmedic compliance requirements exclude commodity suppliers from qualified vendor lists. Basel and Zürich biotech clusters concentrate specialized pump specification activity.
Worm Pumps Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the worm pump landscape. Integrated European manufacturers with captive elastomer molding capabilities capture municipal framework agreements through availability guarantees. Three archetypes dominate: full-system vendors bundling predictive maintenance platforms, component specialists controlling premium stator supply, and regional fabricators serving price-sensitive replacement markets. Consolidation concentrates purchasing power with vendors capable of predictive analytics, while material substitution investments compress margins for mid-tier suppliers lacking regulatory acceptance for bio-based alternatives.
Among European integrated manufacturers, SEEPEX and Sulzer occupy positions anchored by digital monitoring platforms and specialized aftermarket networks respectively. Xylem represents the sensor-integrated diagnostic tier, embedding vibration analytics directly into helical rotor housings. These three exemplify the shift from transactional hardware margins toward recurring revenue models built on uptime guarantees and predictive replacement scheduling.
| Leading Market Players |
|---|
| Grundfos |
| LEWA |
| KSB |
| Roto Pumps |
| SPX Flow |
| Sulzer |
| Flowserve |
| Xylem |
| SEEPEX |
| Others |
Pricing and Supply Chain Analysis
Elastomer compound costs cascade from petroleum feedstock volatility through REACH-driven reformulation investments into three distinct pricing tiers for municipal, pharmaceutical, and industrial buyers. Stator rubber price instability compresses margins for mid-tier suppliers lacking early regulatory acceptance for bio-based alternatives, while premium vendors with captive molding capabilities capture framework agreements through availability guarantees.
Pricing Analysis
Uptime-based contracting anchors value pricing for progressive cavity pumps, with European utilities now specifying availability guarantees and penalty clauses that transfer operational risk to manufacturers. Price differentiation rests on certification tier—FDA-validated pharmaceutical configurations command substantial premiums over standard municipal specifications—and aftermarket service bundling, where predictive maintenance platforms justify recurring revenue premiums. Pricing pressure stems from centrifugal pump substitution in lower-viscosity water treatment applications, eroding addressable market for positive displacement units. Municipal procurement teams exhibit highest price sensitivity under public tender frameworks, while biologics manufacturers prioritize protein integrity preservation over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale petrochemical demand in the US Gulf Coast and Rotterdam-Antwerp corridors, while specialized distributors serve fragmented municipal replacement markets. Geographic supply concentrates in Germany, the Netherlands, and China for premium elastomer molding capabilities. Raw material dependencies center on petroleum-derived NBR and FKM compounds, specialty steel alloys for rotor machining, and rare-earth elements for magnetic drive couplings. Single-source vulnerability in German stator production creates bottleneck risk for high-specification pharmaceutical orders. Distribution runs through regional parts depots for aftermarket service contracts, with digital platforms compressing traditional spare parts margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium elastomer molding capacity scarcity props pricing power for integrated manufacturers with captive supply, constraining mid-tier competitors from framework agreement participation.
For Market Incumbents: Cement control over municipal framework agreements by expanding predictive maintenance platform deployment and securing early REACH acceptance for bio-based stator compounds. Magnetic drive technology substitution threatens traditional sealed configurations in chemical processing corridors; backward integration into specialty elastomer formulation preserves margin structure against commodity competitors. For New Entrants and Emerging Players: Digital-channel routes through cloud-based diagnostics platforms offer lower-friction entry into tier-2 and tier-3 Indian municipal markets, where sanitation program scaling outpaces incumbent service network coverage. Target pharmaceutical multi-threaded configurations as the most penetrable premium segment, where FDA and EMA compliance requirements have excluded commodity suppliers from qualified vendor lists. Pursue partnership-based go-to-market models with regional fabricators lacking predictive analytics capabilities. For Investors and Strategic Acquirers: Accelerated magnetic drive specification in US and Middle Eastern petrochemical corridors is the leading indicator that sealless technology share gains will concentrate vendor relationships around designers with captive magnetic coupling capabilities. Long-term viability favors vertically integrated manufacturers with elastomer molding and digital platform assets over asset-light component specialists. Monitor REACH substance evaluation timelines as inflection signals for material substitution investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Formulation | REACH compliance investments in German and Dutch manufacturing secure early regulatory acceptance for bio-based alternatives. |
| Predictive Maintenance Platform Deployment | Cloud analytics integration transforms municipal customer relationships from transactional hardware toward recurring uptime guarantees. |
| Magnetic Drive Coupling Capability Buildout | Sealless configurations capture refinery demand under EPA fugitive emissions rules and Rotterdam-Antwerp corridor regulations. |
| Regional Parts Depot Network Expansion | Proximity service infrastructure satisfies European utility penalty clause requirements for unplanned downtime response. |
| Multi-Threaded Pharmaceutical Validation Investment | FDA and Swissmedic documentation packages exclude commodity competitors from biologics manufacturing qualified vendor lists. |
Research Methodology
Trade association filings, customs and import-export databases, and regulatory submission records formed the secondary backbone, cross-referenced against primary interviews with municipal wastewater utility procurement directors, petrochemical plant maintenance engineers, pharmaceutical manufacturing equipment qualification specialists, and progressive cavity pump aftermarket service heads. Bottom-up unit shipment estimates triangulated against top-down value projections derived from OEM revenue disclosures and distributor channel audits.
Historical trendline analysis of replacement cycle patterns, technology adoption curves, and regulatory enforcement timelines informed projection modeling across the analysis window. Segmentation dimensions included product type configuration, technology architecture, application severity, and end-user industry regulatory tier. CAGRs were synthesized from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific forecast inputs incorporated MEE discharge standard enforcement intensity in Shandong and Jiangsu, and EU Green Deal effluent mandate implementation schedules.
The model holds under stable elastomer feedstock pricing and continued REACH substance evaluation timelines; deviation in petroleum market volatility or accelerated ECHA disqualifications would shift replacement cycle assumptions. Forecasts reflect documented base conditions subject to revision from regulatory, macroeconomic, or technological disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Oil and Gas Actuators Market