
 Heat Shrink Packaging Market | 2026-2036
Heat Shrink Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Packaging Market Foresight
Multi-sourcing of specialty polyolefin resins is expanding as converters seek supply security amid petrochemical volatility. Amcor Plc leverages its global film extrusion network to secure resin access across multiple geographies. Berry Global Inc anchors North American demand through high-volume blown film operations serving retail and industrial accounts. Sealed Air Corporation differentiates via integrated systems that pair shrink films with automated wrapping equipment.
Heat shrink packaging comprises polymer-based films, tubing, bags, and labels that contract uniformly when heated to conform tightly to product contours, typically manufactured through blown film extrusion with controlled orientation ratios to achieve 40-70% shrinkage in either single or biaxial directions. The primary commercial purpose centers on unitizing multi-packs, providing tamper evidence, and protecting surfaces during distribution. Films dominate value capture due to their ubiquity across food bundling and pallet stabilization, while polyolefin grades command margin premiums for their clarity and seal strength in pharmaceutical and electronics applications. Bags represent the fastest-growing configuration as e-commerce fulfillment drives demand for pre-formed shrink enclosures that eliminate manual wrapping steps.
FDA regulations governing indirect food contact materials shape resin selection and additive formulations for heat shrink films destined for edible goods. EPA emissions standards for blown film extrusion operations influence capital allocation toward energy-efficient ovens and solvent-free printing systems. ECHA REACH compliance requirements restrict certain plasticizers in PVC shrink formulations, redirecting formulation investment toward polyolefin alternatives. Stakeholders must monitor how packaging Extended Producer Responsibility frameworks in the European Union and individual US states alter the total cost of film ownership and recyclability certification requirements.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing formulation cycles as converters race to certify recyclable polyolefin alternatives before mandatory recyclability thresholds take effect. This regulatory compression is redrawing competitive advantage toward integrated film producers with in-house recycling verification capabilities.
Growth Catalysts
- Food bundling automation:Beverage and snack producers are deploying high-speed shrink-wrapping lines to replace corrugated secondary packaging. Polyolefin films with enhanced seal strength are capturing this demand surge.
- E-commerce fulfillment density:Pre-formed shrink bags are displacing manual wrapping in distribution centers serving direct-to-consumer channels. Warehouse operators in Germany and the Netherlands are standardizing on these configurations.
- REACH compliance migration:ECHA restrictions on phthalate plasticizers in PVC formulations are redirecting pharmaceutical and electronics packaging toward polyolefin shrink films with certified indirect food contact status.
Market Restraints
- Propylene feedstock volatility:Specialty polyolefin resin prices track naphtha and propane cracking economics, squeezing converter margins during petrochemical upcycles.
- German machinery cluster concentration:Blown film extrusion equipment and technical service capabilities concentrate around Düsseldorf and Cologne, creating geographic supply risk for distant converters.
- Mechanical recycling contamination:Multi-layer shrink films with EVOH oxygen barriers face limited end-of-life processing options under current EU sorting infrastructure.
Strategic Opportunities
- Pharmaceutical serialization integration:Shrink sleeve labels with embedded RFID and tamper-evident features are converging with track-and-trace mandates in regulated drug distribution.
- Industrial pallet stabilization:Automated stretch-hood and shrink-hood systems are penetrating chemical and building materials logistics in Poland and the Czech Republic.
- Bio-based polyolefin certification:Mass-balance ISCC PLUS certification for renewable feedstock films is creating premium positioning for converters serving brand-owner sustainability commitments.
Industry Challenges
- Extrusion technician scarcity:Blown film operators with expertise in orientation ratio control and bubble stability are in short supply across Central European manufacturing corridors.
- Extended Producer Responsibility registration:EU member state packaging registries impose divergent fee structures and data reporting requirements, complicating multi-national film distribution.
- Legacy oven retrofit compatibility:Conventional shrink tunnels with imprecise temperature zoning struggle to process next-generation thin-gauge films without wrinkling or burn-through.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Packaging Market |
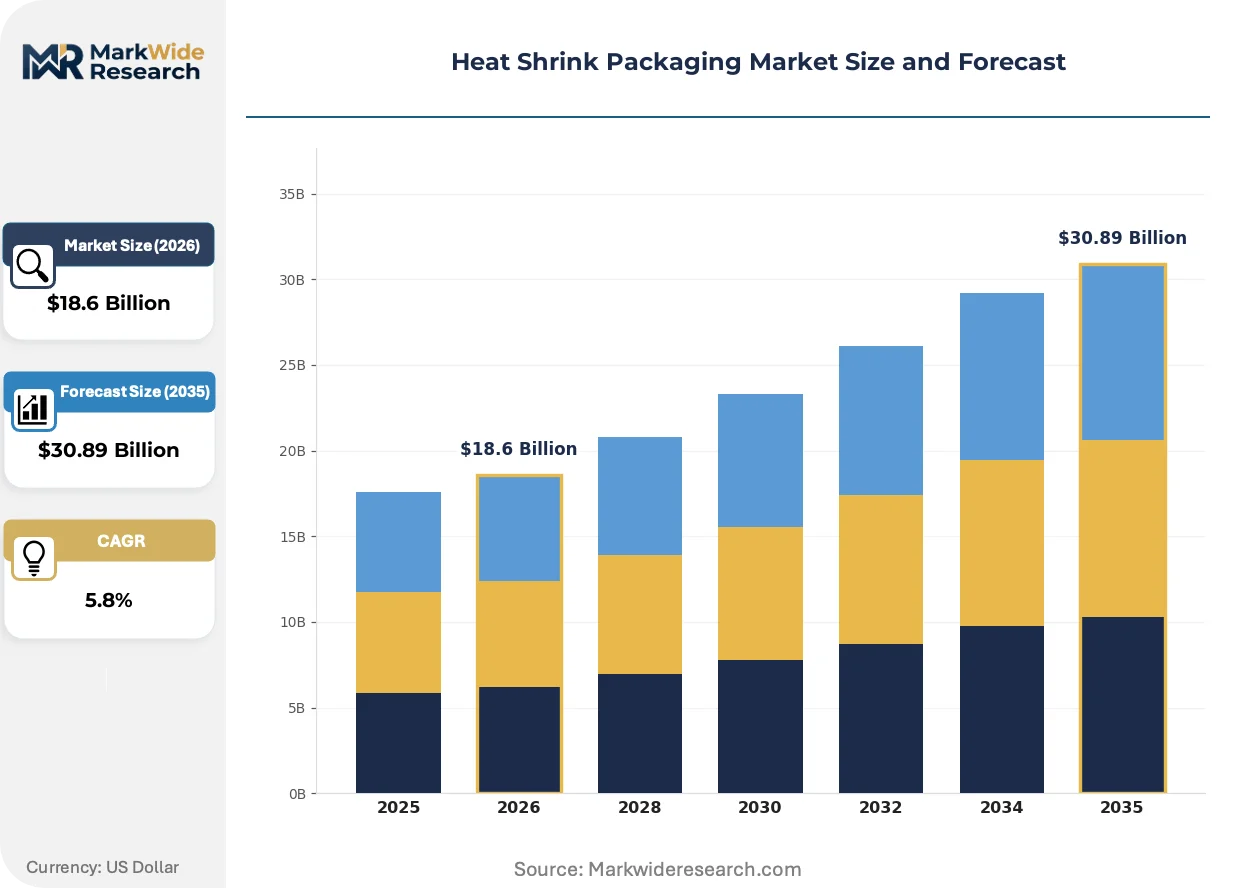
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Tubing, Bags, Labels Material: Polyethylene, Polyolefin, PVC, PET End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Thickness: Lightweight, Medium, Heavyweight, Ultra-Thick |
| Companies Covered | Amcor Plc, Sealed Air Corporation, Berry Global Inc, Sonoco Products, Mondi Group, ProAmpac, CCL Industries, Jindal Poly Films, INDEVCO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Packaging Market Shifts & Advancements
Active developments across materials science, regulatory compliance architecture, and fulfillment automation are restructuring how shrink packaging creates value. Three forces are particularly consequential for strategic positioning.
Mono-material polyolefin shrink films with controlled biaxial orientation are modularizing packaging system design. Food and beverage manufacturers are standardizing on these formulations to simplify recycling streams and reduce sorting costs. This modularization is compressing demand for multi-layer barrier films that require complex separation.
REACH Annex XVII restrictions on substances of very high concern are tightening disclosure requirements for additives in food-contact films. Industrial consequence includes mandatory supply chain auditing for antioxidant and slip agent chemistries. Pharmaceutical and organic food packaging segments are responding fastest, demanding full formulation transparency from resin suppliers.
Buyers are consolidating film procurement under sustainability scorecard criteria that weight recyclability certification above unit price. Large retail and foodservice distributors are displacing fragmented spot purchasing with multi-year supply agreements tied to verified recycled content thresholds. This concentration is most visible in German and French grocery supply chains.
Heat Shrink Packaging Market Segmentation
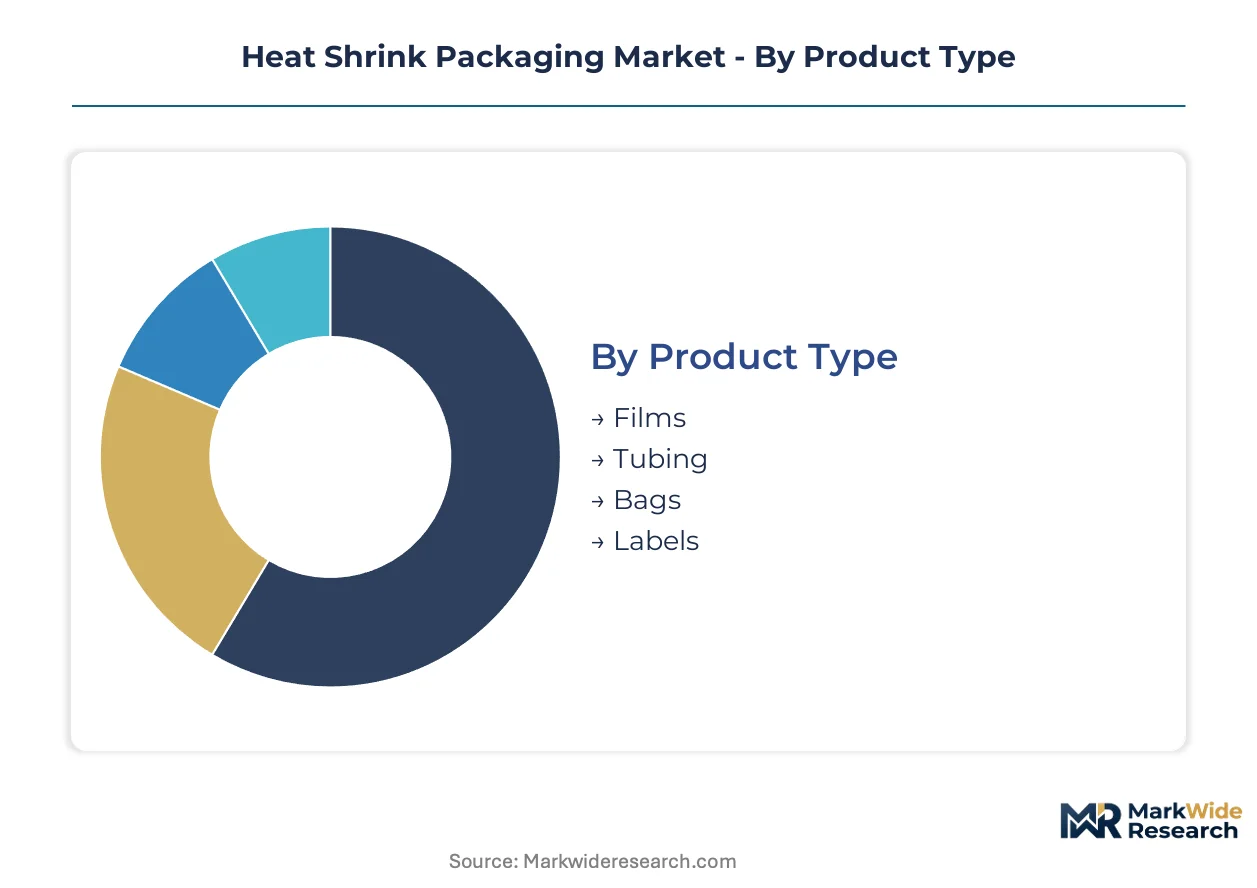
Segmentation in heat shrink packaging reveals how material science, end-use requirements, and processing economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, shaping where converters invest extrusion capacity.
Product Type:
Films operate as standalone consumables purchased separately from equipment, while tubing, bags, and labels embed into integrated packaging systems with tighter vendor lock-in.
- Films:Blown extrusion products with controlled biaxial orientation delivering 40-70% shrinkage ratios. Demand concentrates in Germany's industrial corridor around Düsseldorf and Cologne, where beverage multi-pack bundling and pallet stabilization consume high volumes. FDA indirect food contact compliance and EU recyclability certification create dual regulatory gates for suppliers.
- Bags:Pre-formed shrink enclosures eliminating manual wrapping steps in e-commerce fulfillment centers. Warehouse operators in the Netherlands and Germany are standardizing on these configurations to accelerate direct-to-consumer throughput. REACH-compliant polyolefin formulations displace PVC alternatives in pharmaceutical applications.
- Tubing:Continuous sleeve formats cut to length for wire harness protection and industrial component bundling.
- Labels:Shrink sleeve formats with tamper-evident and 360-degree graphic capabilities for branded consumer goods.
Films lead volumes today; bags are gaining share fastest.
Material:
Raw material selection determines clarity, seal strength, recyclability pathway, and exposure to ECHA REACH restrictions on plasticizers and additives.
- Polyolefin:Premium clarity and seal strength grades commanding margin premiums in pharmaceutical and electronics packaging. Specialty resin producers are expanding multi-sourcing arrangements to hedge naphtha and propane cracking volatility. ISCC PLUS mass-balance certification for renewable feedstock variants is creating sustainability differentiation.
- Polyethylene:Cost-optimized workhorse for industrial pallet wrap and basic food bundling where optical properties matter less.
- PVC:Legacy formulations facing ECHA Annex XVII phthalate restrictions, redirecting pharmaceutical and organic food segments toward polyolefin migration.
- PET:High-shrink precision grades for contoured container labeling with superior printability.
Polyolefin captures the highest unit margins; polyethylene moves the largest tonnage.
End User:
End-use segmentation maps divergent performance requirements against regulatory exposure, from FDA food contact rules to pharmaceutical serialization mandates.
- Food & Beverage:Dominant demand source with automation replacing corrugated secondary packaging. High-speed shrink-wrapping lines in snack and beverage plants specify polyolefin films with enhanced hot-tack seal strength. EU Packaging and Packaging Waste Regulation recyclability thresholds are compressing formulation cycles toward mono-material designs.
- Pharmaceuticals:Shrink sleeve labels with embedded RFID and tamper-evident features converging with track-and-trace distribution mandates. Full formulation transparency for antioxidant and slip agent chemistries is becoming standard procurement criteria.
- Electronics:Anti-static and cleanroom-compatible formulations for component protection during distribution.
- Consumer Goods:Graphic-intensive applications prioritizing shelf impact and 360-degree brand communication.
Food & Beverage anchors volume; Pharmaceuticals shows the steepest expansion trajectory.
Thickness:
Gauge selection reflects the tension between material cost, protection requirements, and compatibility with legacy shrink tunnel equipment.
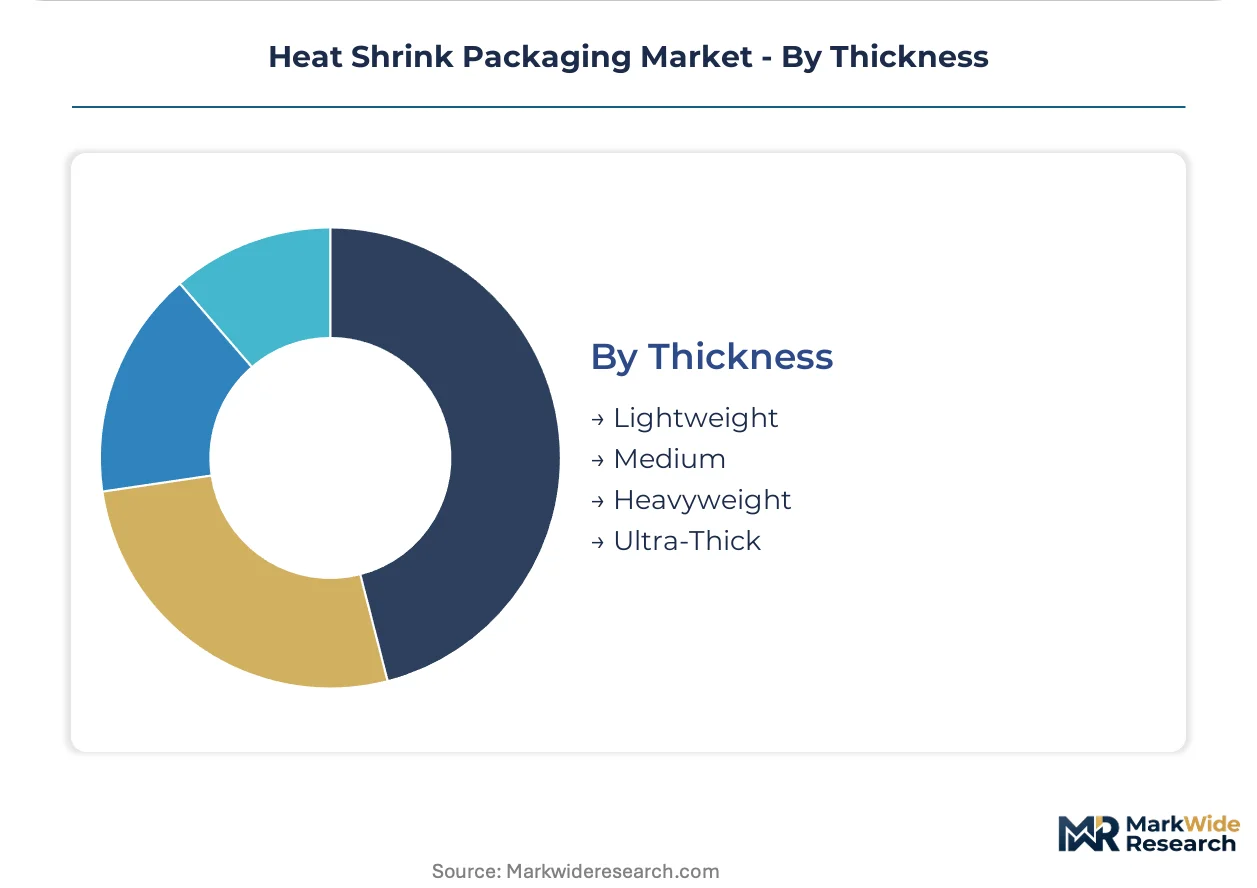
- Lightweight:Thin-gauge films below 30 microns reducing material cost and shipping weight. German grocery supply chains are adopting these for multi-pack bundling, though conventional ovens with imprecise temperature zoning struggle with wrinkling and burn-through.
- Medium:Standard 30-50 micron range balancing cost and puncture resistance for general industrial use.
- Heavyweight:50-100 micron grades for abrasive building materials and chemical logistics requiring puncture resistance.
- Ultra-Thick:Above 100 micron formulations for extreme industrial pallet stabilization and marine corrosion protection.
Medium gauges dominate installed equipment; lightweight films are climbing the fastest as tunnel retrofits proceed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial packaging corridor around Düsseldorf and Cologne anchors heat shrink packaging demand through dense clusters of beverage bottlers, machinery builders, and film converters. National sustainability mandates and automation investments are redrawing procurement patterns across the country. Four additional markets shape regional dynamics through distinct regulatory and industrial configurations.
United States
Food and beverage bundling automation drives film consumption across Midwestern snack production centers and Southeastern distribution hubs. FDA indirect food contact regulations govern resin selection and additive formulations for edible goods packaging. Chicago and Atlanta warehouse operators are standardizing on pre-formed shrink bags to accelerate e-commerce fulfillment throughput.
China
Industrial pallet stabilization and electronics component protection consume growing volumes of polyolefin shrink films in Yangtze River Delta manufacturing zones. NMPA and GB standards for pharmaceutical packaging materials influence track-and-trace label specifications. Shenzhen and Shanghai converters are expanding blown film capacity to serve domestic brand-owner sustainability commitments.
France
Grocery supply chain consolidation is concentrating film procurement under sustainability scorecard criteria in Île-de-France and Auvergne-Rhône-Alpes distribution networks. EU Packaging and Packaging Waste Regulation recyclability thresholds are compressing formulation cycles toward mono-material designs. Lyon-based logistics operators are retrofitting shrink tunnels to process lightweight thin-gauge films.
Netherlands
E-commerce fulfillment density in Randstad distribution corridors is accelerating adoption of pre-formed shrink enclosures for direct-to-consumer channels. REACH Annex XVII disclosure requirements for additives are tightening supply chain auditing protocols. Rotterdam warehouse operators are standardizing on REACH-compliant polyolefin formulations displacing legacy PVC alternatives.
India
Food and beverage multi-pack bundling is penetrating secondary packaging lines in Maharashtra and Gujarat processing facilities. BIS standards for plastic films in food contact applications shape converter qualification requirements. Mumbai and Ahmedabad machinery importers are deploying high-speed shrink-wrapping lines to replace corrugated packaging in snack and beverage plants.
Heat Shrink Packaging Market Competitive Landscape
Global majors compete with regional champions across film extrusion capacity and integrated packaging systems. The vendor base stratifies into three tiers: multinational converters with multi-continent extrusion networks, mid-cap specialists anchored in single-country industrial corridors, and equipment-integrated system providers. Two competitive moves dominate: backward integration into specialty resin sourcing to hedge feedstock volatility, and geographic expansion through technical service partnerships near German machinery clusters.
Within the multinational converter tier, Amcor Plc and Berry Global Inc exemplify scale-driven positioning through broad film extrusion footprints. Sealed Air Corporation occupies a distinct equipment-integrated archetype, pairing shrink films with automated wrapping systems. These three anchors represent divergent strategic postures: resin access security through geographic diversification, volume capture through high-throughput operations, and customer lock-in through system-level integration.
| Leading Market Players |
|---|
| Amcor Plc |
| Sealed Air Corporation |
| Berry Global Inc |
| Sonoco Products |
| Mondi Group |
| ProAmpac |
| CCL Industries |
| Jindal Poly Films |
| INDEVCO Group |
| Others |
Supply & Pricing Matrix
Thin-gauge film migration below 30 microns is compressing per-unit resin consumption while concentrating buyer power among German grocery chains and Dutch e-commerce operators capable of retrofitting shrink tunnel infrastructure. This production-method transition simultaneously erodes converter margins on legacy medium-gauge volumes and rewards integrated film producers with captive extrusion and recycling verification capabilities.
Pricing Analysis
Specialty polyolefin resin costs pass through to film pricing with a lag tied to naphtha and propane cracking economics. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS certified renewable feedstock films from FDA-compliant food-contact grades and basic industrial polyethylene workhorses. Cost compression in standard grades is intensifying because beverage multi-pack bundling buyers are consolidating procurement under sustainability scorecards. Warehouse operators and snack producers show highest price sensitivity; pharmaceutical serialization integrators show least.
Supply Chain Analysis
Post-industrial film scrap collection and mechanical reprocessing loops are gaining traction as EU Extended Producer Responsibility frameworks penalize linear material flows. Blown film extrusion capacity concentrates in Germany, the United States, and China, with technical service capabilities clustering around Düsseldorf and Cologne. The supply chain draws from propylene feedstocks, specialty antioxidant packages, and slip agent chemistries. Single-source vulnerability sits with German machinery clusters for high-speed orientation control equipment. Distribution runs through converter-direct relationships with beverage bottlers and third-party logistics packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation operates as a regulatory compounder, with mandatory recyclability thresholds compressing formulation cycles and redirecting procurement toward certified mono-material alternatives.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty polyolefin resin sourcing to hedge feedstock volatility, and accelerate in-house recycling verification capabilities before mandatory EU thresholds take effect. Emerging mid-cap converters with ISCC PLUS certification pose substitution threats in pharmaceutical and organic food segments.
For New Entrants and Emerging Players: REACH Annex XVII restrictions on phthalate plasticizers in the European Union open a window for polyolefin shrink film penetration in pharmaceutical and electronics packaging previously served by PVC formulations. Target thin-gauge bag configurations for Dutch and German e-commerce fulfillment centers where warehouse automation standardization creates vendor selection momentum. Pursue technical service partnerships near Düsseldorf machinery clusters to overcome geographic supply risk perceptions.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap blown film specialists with ISCC PLUS certification and established FDA food-contact compliance because brand-owner sustainability commitments are consolidating procurement under multi-year agreements. The 5-10 year viability window favors converters with verified recycling pathways and pharmaceutical serialization integration capabilities. Monitor EU member state packaging registry fee structures for divergence signals that would complicate multi-national film distribution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Sourcing | Captive polyolefin supply hedges naphtha volatility for German industrial corridor converters. |
| ISCC PLUS Mass-Balance Certification | Renewable feedstock verification unlocks premium positioning in French and Dutch grocery supply chains. |
| Thin-Gauge Film Capacity Expansion | Below-30-micron extrusion lines serve Dutch Randstad e-commerce fulfillment density requirements. |
| Pharmaceutical Serialization Integration | RFID-embedded shrink sleeve labels align with FDA track-and-trace mandates in regulated drug distribution. |
| Technical Service Partnership Near Machinery Clusters | Proximity to Düsseldorf and Cologne equipment builders reduces geographic supply risk for distant converters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blown film plant managers, procurement leads at beverage bottlers, technical R&D directors at resin suppliers, and distribution channel partners with secondary validation. Sources included customs and trade data, SEC filings from listed packaging converters, ECHA REACH substance restriction updates, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up capacity modeling and top-down demand aggregation were triangulated against one another.
Segment-weighting approaches modeled value and volume across material grades, product configurations, end-use industries, and geographic production hubs. The analytical framework applied CAGRs derived from installed equipment base expansion, automation penetration rates, and regulatory compliance cost absorption curves. Industry-specific inputs captured blown film extrusion capacity utilization, shrink tunnel retrofit cycles, and pharmaceutical serialization mandate timelines.
Revisions become necessary when EU member state packaging registry implementations diverge, when propylene feedstock volatility exceeds historical bands, or when mechanical recycling infrastructure deployment lags regulatory targets. Practitioners should monitor ECHA Annex XVII restriction expansion, German machinery cluster capacity constraints, and brand-owner sustainability scorecard weighting shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Face Stock Films Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
US Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
VCI Films Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Nonwoven Packaging Market