
 Polystyrene Packaging Market | 2026-2036
Polystyrene Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Polystyrene Packaging Market Analytics
Lightweighting through advanced bead expansion technology is tilting manufacturing economics toward higher-performance grades. BASF SE leverages its integrated styrenics chain to sustain cost leadership in expanded polystyrene feedstock. Dart Container Corporation anchors North American foodservice packaging through captive manufacturing scale. Alpek SAB de CV competes across Latin America via specialized extrusion capabilities for construction-adjacent protective applications.
Polystyrene packaging comprises rigid thermoplastic containers, protective foam structures, and cushioning elements manufactured through suspension polymerization or steam-molded bead expansion, typically exhibiting densities from 10 to 50 kg/m³ depending on end-use protection requirements. The material serves primarily to prevent mechanical damage, thermal degradation, and moisture ingress during product distribution. Expanded polystyrene dominates volume flows in food packaging and electronics protection, where its cellular structure delivers unmatched impact absorption per unit weight. High impact polystyrene captures premium positioning in medical packaging and consumer goods applications requiring sterilization compatibility and dimensional precision.
The EPA regulates volatile organic compound emissions from styrene polymerization facilities under Clean Air Act standards, while REACH restricts residual monomer content in food-contact applications across European markets. China's MEE enforces stricter waste classification rules that elevate compliance costs for non-recyclable foam disposal. India's BIS certification mandates for food-grade polymers further fragment market access requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in formulations that fail emerging recyclability thresholds.
Market Dynamics
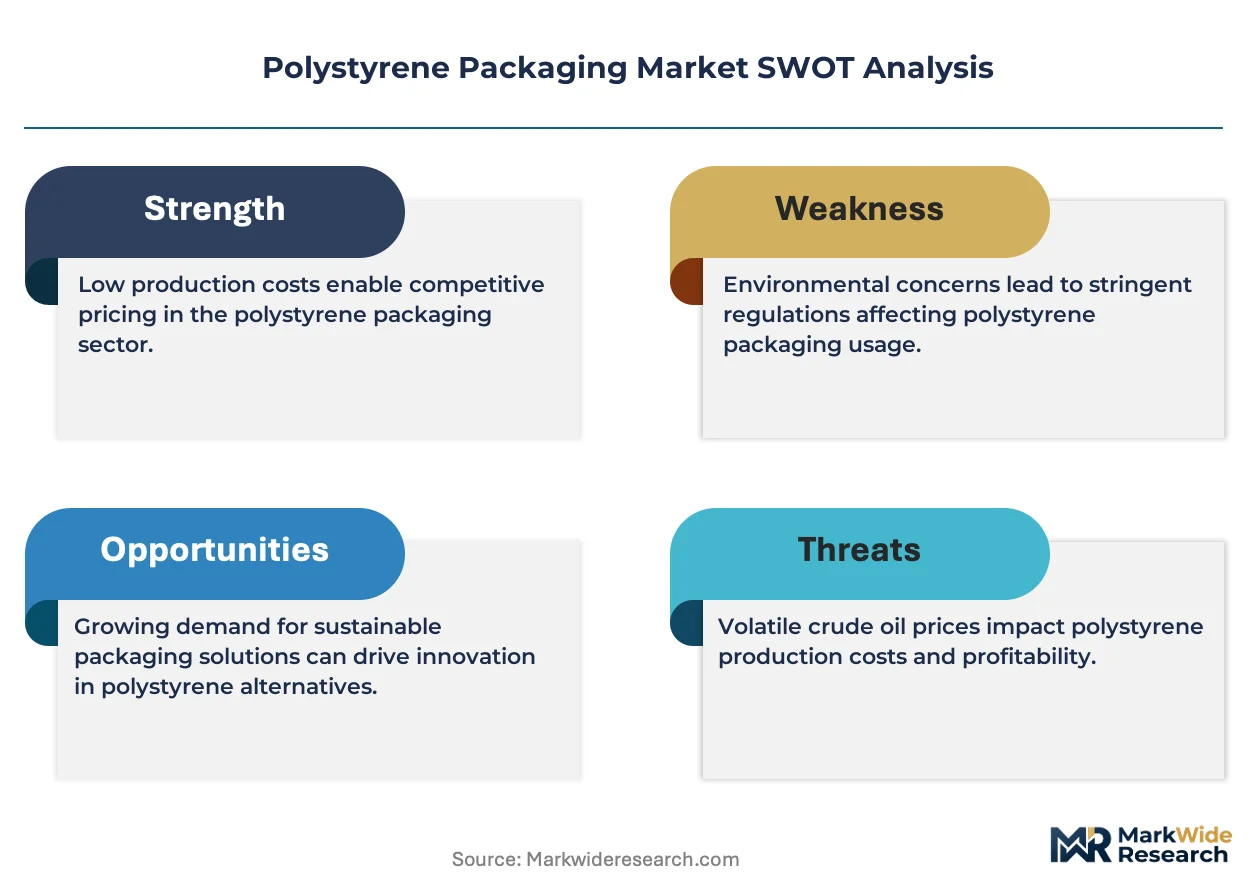
REACH restrictions on single-use plastics and China's MEE waste classification rules are forcing simultaneous reformulation toward recycled-content grades and elevated compliance costs for non-recyclable foam disposal across manufacturing footprints.
Growth Catalysts
- E-commerce fulfillment infrastructure:China's expanding logistics networks drive expanded polystyrene consumption for protective cushioning of fragile electronics shipments.
- EU Green Deal circularity mandates:Packaging producers reformulate toward post-consumer recycled content to maintain market access across European foodservice applications.
- Bead expansion technology:Advanced steam-molded processes enable lightweighting that tilts manufacturing economics toward higher-performance protective foam grades.
Market Restraints
- Styrene monomer price volatility:Crude oil-linked feedstock costs compress margins for expanded polystyrene manufacturers during energy price spikes.
- Single-use plastic bans:Municipal ordinances in California, New York, and Oregon restrict foodservice foam applications regardless of recyclability claims.
- Cellulose fiber substitution:Molded pulp alternatives capture share in premium electronics unboxing experiences where sustainability signaling commands buyer preference.
Strategic Opportunities
- Chemical recycling infrastructure:Pyrolysis partnerships with petrochemical complexes enable food-grade recycled polystyrene feedstock at scale.
- Medical cold-chain expansion:Temperature-stable expanded polystyrene shippers capture demand from biologics distribution networks requiring validated thermal protection.
- India's BIS certification pathways:Early compliance with food-grade polymer mandates secures preferential positioning ahead of domestic capacity expansion.
Industry Challenges
- Recyclability certification timelines:How2Recycle and EPBP approval processes delay market entry for novel foam formulations by 18-24 months.
- Legacy extrusion asset retrofitting:Converting rigid sheet lines to process recycled-content resins requires capital outlays that strain mid-tier processors.
- Cross-jurisdictional compliance fragmentation:Divergent state-level extended producer responsibility schemes in the US multiply labeling and reporting burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polystyrene Packaging Market |
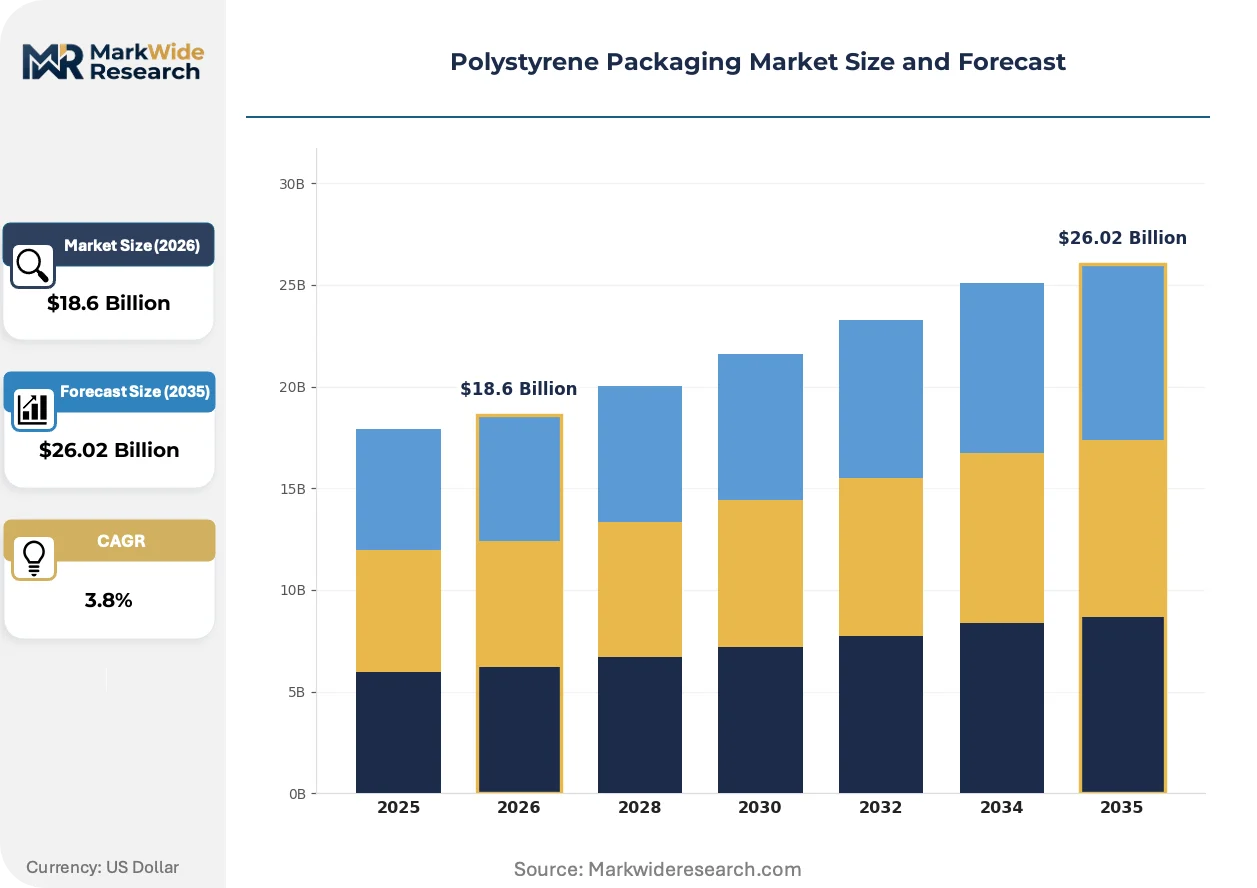
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Polystyrene, High Impact Polystyrene, Extruded Polystyrene, General Purpose Polystyrene Application: Food Packaging, Electronics Packaging, Medical Packaging, Consumer Goods Packaging End User: Food & Beverage Industry, Electronics Manufacturers, Healthcare Providers, Retail Sector Delivery Mode: Direct Delivery, Freight Shipping, Retail Distribution, Wholesale Distribution |
| Companies Covered | Synthos SA, DuPont, BASF SE, Versalis S.p.A., KANEKA CORPORATION, TotalEnergies SE, SABIC, Dart Container Corporation, Alpek SAB de CV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polystyrene Packaging Market Evolving Landscape
Active reformulation toward bio-attributed and chemically recycled feedstocks is compressing the addressable market for virgin polystyrene while creating premium positioning for certified sustainable grades.
Supercritical CO2 bead expansion is rendering obsolete steam-molded processes that rely on pentane blowing agents. Electronics manufacturers in South Korea and Taiwan are adopting these lines to eliminate volatile organic compound emissions from their supply chains. The technology is rendering obsolete legacy equipment investments across Southeast Asian contract manufacturers.
REACH Annex XVII restrictions on microplastics in synthetic polymer microparticles now cover expanded polystyrene fragments below five millimeters. Industrial users in Germany and France face mandatory containment protocols for cutting and shaping operations. Medical packaging segments are responding by specifying high-impact polystyrene alternatives with tighter dimensional tolerances that reduce post-processing waste.
Consolidated procurement by Amazon and Alibaba fulfillment networks is compressing supplier counts and mandating recycled-content minimums. Regional foam converters in Poland and Mexico are losing share to integrated multinationals with verified mass-balance certifications. This concentration is most visible in cross-border e-commerce corridors where sustainability scorecards determine vendor eligibility.
Polystyrene Packaging Market Segmentation
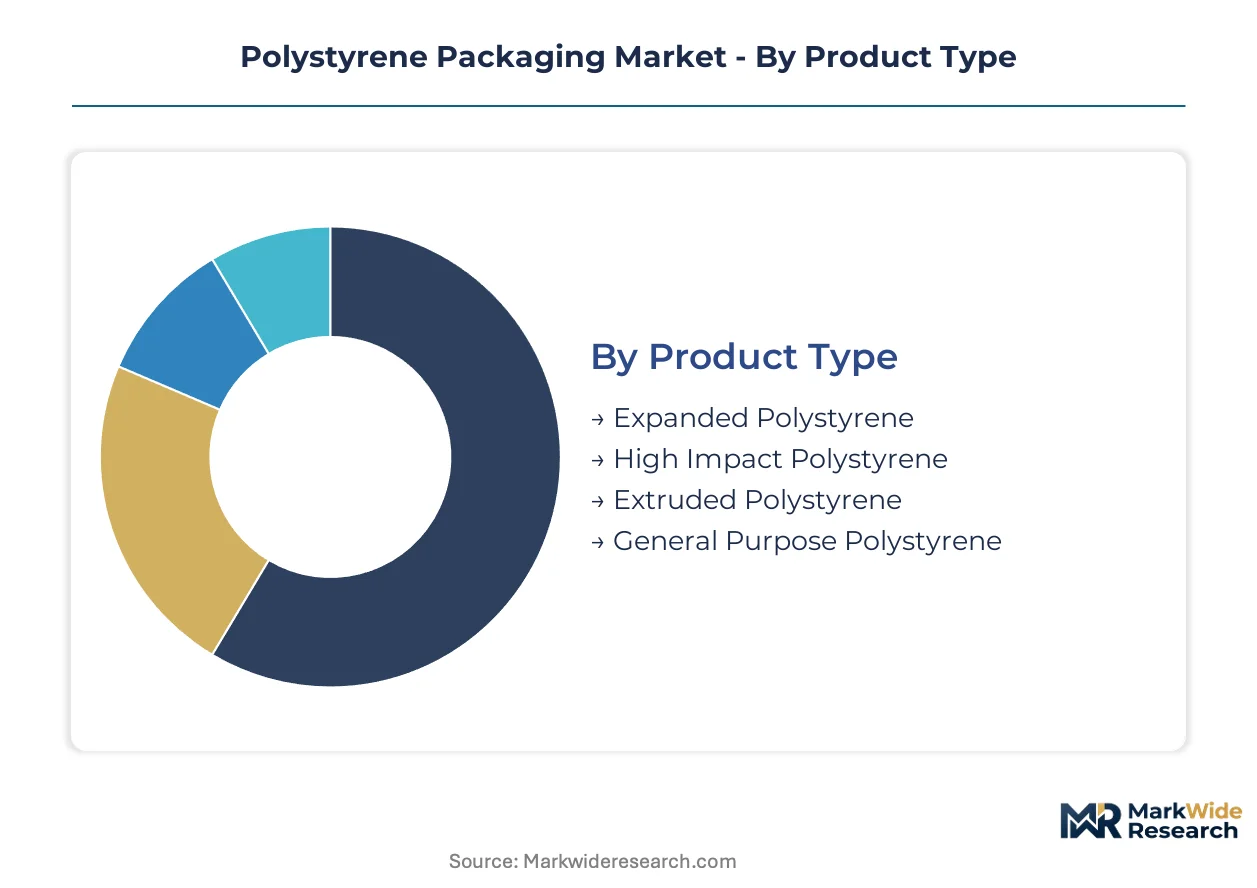
Segmentation in polystyrene packaging reveals divergent margin profiles and inventory velocities across material grades and end-use channels. Understanding these structural differences enables targeted capacity allocation and formulation investments.
Product Type:
Cycle times vary dramatically across polystyrene grades, with expanded polystyrene converting rapidly into disposable applications while high-impact grades endure longer in durable medical and consumer goods formats.
- Expanded Polystyrene:Cellular foam structure manufactured through steam-molded bead expansion delivers densities from 10 to 50 kg/m³ for impact absorption. Demand concentrates in China's e-commerce fulfillment infrastructure where protective cushioning requirements for fragile electronics shipments drive volume. The material's low thermal conductivity and moisture resistance sustain dominance in foodservice disposable applications despite regulatory pressure.
- High Impact Polystyrene:Rubber-modified thermoplastic combining polystyrene with polybutadiene for enhanced toughness and sterilization compatibility. Medical packaging specifications in Germany and France specify this grade for dimensional precision that minimizes post-processing waste under REACH microplastic containment protocols.
- Extruded Polystyrene:Continuous foam boards produced through single-screw extrusion with blowing agents for construction-adjacent protective applications.
- General Purpose Polystyrene:Unmodified crystal-grade resin serving cost-sensitive rigid container applications with faster formulation turnover cycles.
Expanded polystyrene anchors the volume base while high impact polystyrene gains share at the steepest rate.
Application:
Margin structures stratify sharply across application segments, with medical cold-chain formats commanding premium pricing over commoditized foodservice disposables facing substitution pressure.
- Food Packaging:Clamshell containers, cups, and trays for hot and cold foodservice applications. Municipal ordinances in California, New York, and Oregon restrict foam foodservice regardless of recyclability claims, compressing addressable market for virgin grades while elevating compliance costs for producers.
- Electronics Packaging:Molded protective foam for smartphones, semiconductors, and display panels during distribution. South Korean and Taiwanese manufacturers specify supercritical CO2 expanded grades to eliminate pentane-based volatile organic compound emissions from supply chains.
- Medical Packaging:Temperature-stable shippers for biologics distribution requiring validated thermal protection. Cold-chain expansion in North American and European pharmaceutical networks sustains premium positioning for expanded polystyrene formats despite sustainability scrutiny.
- Consumer Goods Packaging:Rigid containers and cushioning for cosmetics, appliances, and durables where unboxing experience influences brand perception.
Food packaging retains the largest installed base though medical packaging climbs the fastest as biologics distribution networks expand.
End User:
Procurement authority and volume concentration diverge across end-user categories, with integrated fulfillment networks consolidating supplier counts while fragmented retail maintains dispersed sourcing.
- Food & Beverage Industry:Quick-service restaurants, institutional catering, and prepared meal producers specifying disposable containers. EU Green Deal circularity mandates compel reformulation toward post-consumer recycled content to maintain market access across European foodservice applications.
- Electronics Manufacturers:OEMs and contract assemblers in Taiwan, South Korea, and China requiring precision-molded protective formats. Amazon and Alibaba fulfillment networks mandate recycled-content minimums that compress regional foam converter share in favor of integrated multinationals with verified mass-balance certifications.
- Healthcare Providers:Hospital systems, laboratories, and pharmaceutical distributors with validated cold-chain requirements.
- Retail Sector:Brick-and-mortar and omnichannel retailers sourcing private-label packaging with sustainability scorecard criteria.
Food and beverage anchors procurement volume while electronics manufacturers drive specification innovation at the most rapid pace.
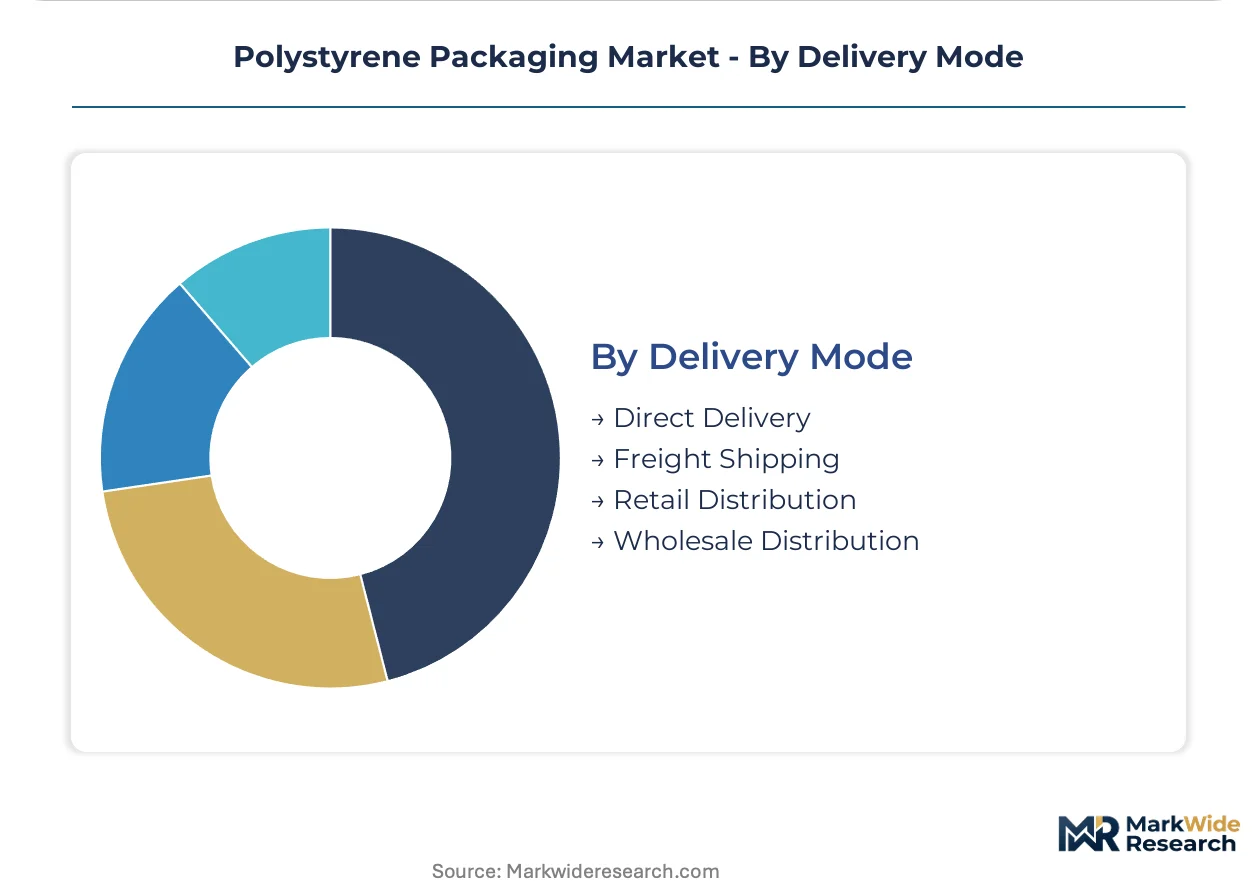
Delivery Mode:
Logistics configuration shapes working capital intensity and geographic reach, with direct delivery enabling just-in-time relationships while wholesale channels require inventory carrying capacity.
- Direct Delivery:Manufacturer-to-customer shipments bypassing intermediaries for large-volume accounts with predictable demand patterns.
- Freight Shipping:Consolidated long-haul movement of bulk foam blocks and sheet stock for downstream conversion.
- Retail Distribution:Packaged goods movement through big-box and specialty retailers with sustainability labeling requirements.
- Wholesale Distribution:Intermediary-stocked inventory serving fragmented small and medium enterprise accounts across dispersed geographies.
Freight shipping handles the greatest tonnage movements while direct delivery expands most quickly as large accounts consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated fulfillment networks in China concentrate procurement authority for protective foam formats, while foodservice buyers in Germany and the United States drive specification divergence between recycled-content mandates and single-use restrictions.
China
E-commerce logistics infrastructure in the Yangtze River Delta consumes expanded polystyrene for electronics cushioning at unmatched scale. MEE waste classification rules elevate disposal compliance costs for non-recyclable foam, pushing converters toward chemically recycled feedstocks. Shenzhen and Dongguan contract manufacturers specify supercritical CO2 expanded grades to eliminate pentane emissions from smartphone packaging lines.
Germany
REACH Annex XVII microplastic containment protocols now govern expanded polystyrene fragment management in industrial cutting operations. The EU Green Deal circularity mandates compel reformulation toward post-consumer recycled content for foodservice market access. Industrial clusters in North Rhine-Westphalia and Bavaria host specialized converters serving medical packaging specifications with high-impact polystyrene alternatives.
United States
Amazon fulfillment network consolidation compresses regional foam converter counts while mandating mass-balance certified recycled minimums. EPA Clean Air Act standards regulate styrene polymerization emissions from Texas and Louisiana petrochemical complexes. California municipal ordinances in Los Angeles and San Francisco prohibit foodservice foam regardless of recyclability claims, fragmenting state-level addressable markets.
South Korea
Electronics OEMs in the Seoul Capital Area specify pentane-free expanded polystyrene to eliminate volatile organic compound exposure from semiconductor packaging operations. MFDS medical device regulations validate temperature-stable foam formats for biologics cold-chain distribution. Busan-Ulsan industrial corridors host integrated converters with verified chemical recycling partnerships.
India
BIS certification mandates for food-grade polymers fragment market access ahead of domestic polystyrene capacity expansion. Quick-service restaurant chains in Maharashtra and Gujarat specify disposable containers under divergent state-level plastic waste rules. The Delhi-NCR logistics corridor drives protective foam consumption for electronics fulfillment as e-commerce penetration deepens.
Polystyrene Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures in polystyrene packaging. Consolidated procurement by Amazon and Alibaba fulfillment networks compresses supplier counts while elevating sustainability certification requirements. Three archetypes dominate: integrated petrochemicals producers with captive styrenics chains, specialized foam converters with regional extrusion capabilities, and diversified packaging conglomerates with cross-material portfolios. Competitive moves center on pyrolysis partnership formation for chemical recycling scale and supercritical CO2 bead expansion line deployment to eliminate pentane-based processes.
Within the integrated petrochemicals tier, BASF SE and TotalEnergies SE exemplify players leveraging upstream styrene monomer control to sustain cost leadership in expanded polystyrene feedstock. Among North American foodservice specialists, Dart Container Corporation occupies a position representing captive manufacturing scale across disposable container formats. Synthos SA anchors the European specialist converter segment with extrusion capabilities serving construction-adjacent protective applications.
| Leading Market Players |
|---|
| Synthos SA |
| DuPont |
| BASF SE |
| Versalis S.p.A. |
| KANEKA CORPORATION |
| TotalEnergies SE |
| SABIC |
| Dart Container Corporation |
| Alpek SAB de CV |
| Others |
Value Network & Pricing Analysis
Styrene monomer price volatility tied to crude oil indexation compresses margin spreads across all three pricing tiers while simultaneously forcing supply chain restructuring toward integrated petrochemical corridors in Texas, Louisiana, and the Yangtze River Delta.
Pricing Analysis
Cost-plus contracts with styrene monomer indexation to Brent crude benchmarks dominate procurement between expanded polystyrene converters and downstream buyers. Three-tier pricing structure across certified-recycled, standard virgin, and economy spot grades reflects mass-balance verification costs and volume scale commitments. Pricing pressure stems from Amazon and Alibaba fulfillment networks mandating recycled-content minimums that disqualify uncertified suppliers. Small and medium enterprise foodservice buyers exhibit highest price sensitivity due to thin operating margins, while medical cold-chain purchasers accept premium positioning for validated thermal protection formats.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for electronics packaging converters serving cross-border e-commerce corridors. Manufacturing concentrates in China, South Korea, and Germany, with raw material flows drawing from benzene and ethylene feedstocks anchored in Gulf Coast and Middle Eastern petrochemical complexes. Single-source vulnerability persists for supercritical CO2 bead expansion equipment supplied by specialized German and Japanese engineering firms. Distribution runs through consolidated freight shipping of bulk foam blocks for downstream conversion, with direct delivery expanding for large-volume Amazon and Alibaba fulfillment accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polystyrene packaging market functions as a defensive-moat story where regulatory entrenchment through REACH and BIS certification pathways creates switching costs that protect incumbent positioning.
For Market Incumbents: Build certification moats through early How2Recycle and EPBP approval investments that delay competitor entry by 18-24 months. Secure pyrolysis partnerships with petrochemical complexes to lock in food-grade recycled feedstock supply before capacity constraints emerge. Capacity addition in India ahead of domestic polystyrene expansion captures preferential BIS positioning. Channel control through Amazon and Alibaba supplier scorecards reinforces volume concentration against regional foam converters. For New Entrants and Emerging Players: India's state-level plastic waste rule fragmentation offers the most penetrable entry point for specialized medical cold-chain formats requiring validated thermal protection. Medical packaging specifications in Germany and France specify high-impact polystyrene alternatives with tight dimensional tolerances that reduce post-processing waste under REACH microplastic protocols. Partner with Busan-Ulsan integrated converters for chemical recycling technology transfer rather than greenfield steam-molded bead expansion investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated petrochemicals producers with captive styrenics chains and verified mass-balance certifications. Long-term viability hinges on pyrolysis infrastructure access and supercritical CO2 line deployment rather than legacy pentane-based asset ownership. Acquisition targets should demonstrate chemical recycling partnerships or medical cold-chain validation capabilities. Watch Amazon and Alibaba supplier count compression as the inflection indicator for regional converter distress.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Partnership Formation | Chemical recycling scale unlocks food-grade recycled polystyrene feedstock for EU Green Deal compliance. |
| Supercritical CO2 Line Deployment | Pentane elimination from South Korean and Taiwanese electronics packaging lines satisfies MFDS emissions protocols. |
| Mass-Balance Certification Investment | Verified recycled-content minimums secure Amazon and Alibaba fulfillment network supplier eligibility. |
| Medical Cold-Chain Validation | Temperature-stable expanded polystyrene shippers capture biologics distribution demand from North American pharmaceutical networks. |
| India BIS Early Compliance | Food-grade polymer certification ahead of domestic capacity expansion secures preferential market positioning. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at expanded polystyrene converters, procurement leads at Amazon and Alibaba fulfillment networks, distribution channel partners in European foodservice, and technical R&D directors at styrenics producers and refined through bottom-up and top-down triangulation. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemicals producers, EPA Clean Air Act enforcement records, and REACH Annex XVII regulatory updates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across material grade tiers, end-use industries, packaging formats, and regional production hubs. CAGRs were derived from production capacity utilization rates, feedstock cost trajectories, and regulatory implementation timelines. Industry-specific forecast inputs included e-commerce fulfillment infrastructure expansion rates in China and biologics cold-chain distribution network growth in North America and Europe.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated multinationals with chemical recycling partnerships would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
China Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Composite Packaging Market