
 Face Stock Films Market | 2026-2036
Face Stock Films Market Size, Share, and Industry Trends Forecast 2026-2036
Face Stock Films Market Analytics
Buyer concentration among large label converters and packaging houses is hardening as multinational food and beverage brands consolidate supplier rosters. Avery Dennison Corporation leverages its backward integration into adhesive and film production to secure volume commitments from these consolidated buyers. UPM Raflatac anchors its position through sustainable fiber-based and bio-polymer face stock portfolios aligned with buyer ESG mandates. CCL Industries Inc. competes by operating specialized coating facilities across multiple continents to guarantee regional supply security.
Face stock films are engineered substrates—typically polyester, polypropylene, or vinyl ranging from 25 to 100 microns in caliper—that receive pressure-sensitive adhesives and release liners to form functional label constructions. These films must deliver dimensional stability, print receptivity, and environmental resistance across flexographic, digital, and gravure printing processes. Polyester face stocks dominate high-performance applications where thermal stability and tensile strength command premium positioning. Polypropylene grades are displacing vinyl in decorative and promotional labels as brand owners phase out chlorine-containing materials. Digital printing compatibility represents the fastest-growing technology dimension, with film suppliers reformulating topcoats to optimize ink adhesion for UV inkjet and toner-based systems.
FDA food contact regulations and the EPA's evolving framework for per- and polyfluoroalkyl substances constrain material choices for U.S.-bound label stocks. REACH substance restrictions and the EU Packaging and Packaging Waste Regulation impose parallel compliance burdens on European suppliers, forcing reformulation of coatings and adhesives. California's Proposition 65 labeling requirements and Safer Consumer Products regulations add state-level complexity for products entering the U.S. West Coast. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redesign costs.
Market Dynamics
Label converters serving multinational food and beverage brands are consolidating supplier rosters, concentrating procurement power among fewer buyers and forcing film suppliers to secure backward integration into adhesive and release liner production to defend volume commitments.
Growth Catalysts
- REACH substance restrictions:European chemical regulations are phasing out legacy coating chemistries, creating replacement demand for compliant bio-based topcoats and waterborne adhesive systems.
- Digital printing compatibility:UV inkjet and toner-based label presses are penetrating mid-volume converter operations, requiring reformulated face stocks with optimized surface energy profiles.
- Germany's precision manufacturing clusters:Heidelberg and Stuttgart anchor concentrated demand from pharmaceutical and premium food labelers seeking dimensional stability in polyester and oriented polypropylene grades.
Market Restraints
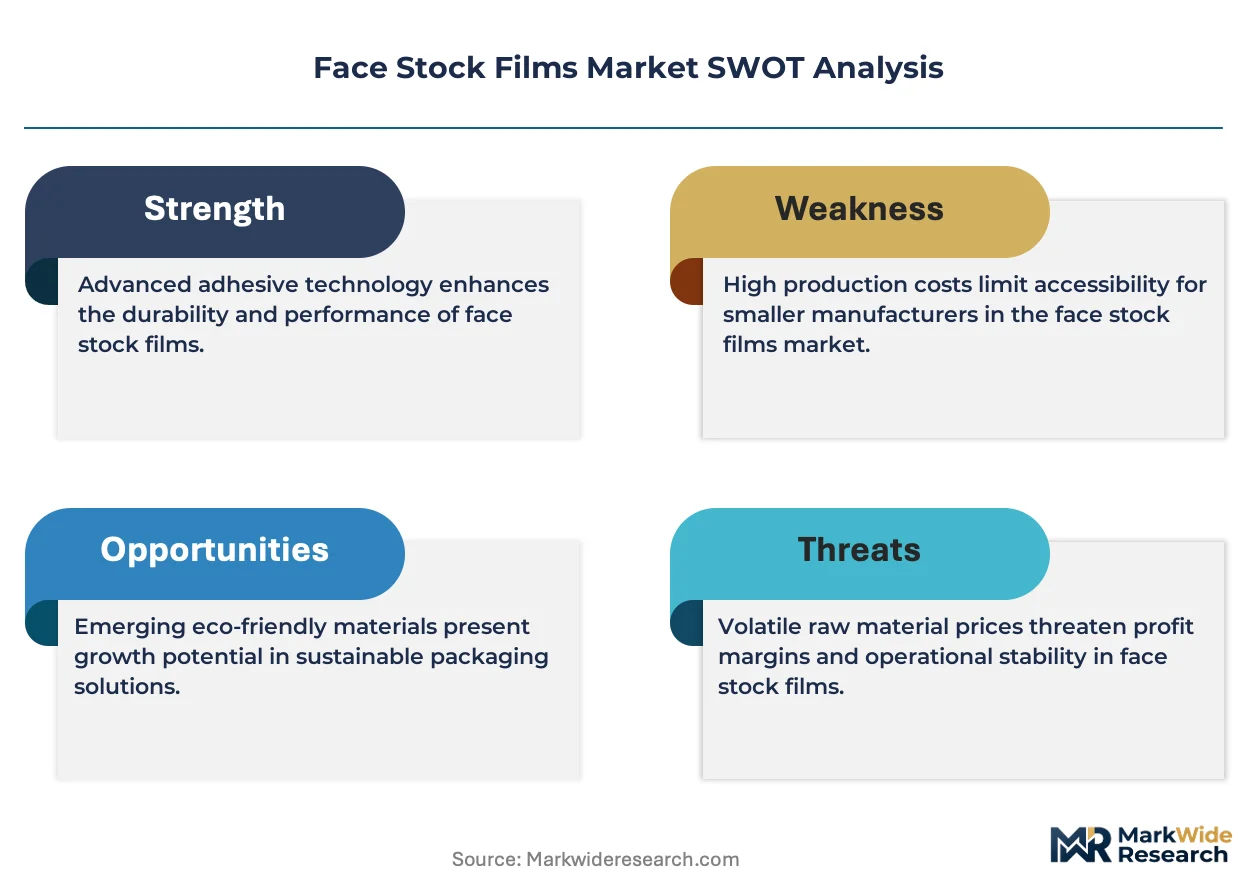
- Petrochemical feedstock volatility:Polypropylene and polyester resin prices fluctuate with crude oil derivatives, compressing margin predictability for film extruders lacking long-term supply contracts.
- Fluorochemical coating phase-outs:EPA restrictions on per- and polyfluoroalkyl substances eliminate low-surface-energy release coatings, forcing costly reformulation of silicone-based alternatives.
- Paper face stock substitution:Fiber-based labels with enhanced moisture barriers are recapturing shelf space in dry-goods applications where plastic reduction targets override performance requirements.
Strategic Opportunities
- India's packaged food expansion:FSSAI labeling mandates and organized retail growth are creating first-time demand for pressure-sensitive labels in regional languages and variable data formats.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility frameworks and recycled content mandates favor suppliers with certified post-consumer recycled film streams and mass-balance accounting systems.
- RFID inlay integration:Convergence of printed electronics with traditional face stock laminates enables smart packaging applications in pharmaceutical authentication and cold-chain monitoring.
Industry Challenges
- Coating technician scarcity:Specialized knowledge of solventless silicone curing and radiation-cured adhesive systems is concentrating among aging workforces in European and North American coating facilities.
- Dual jurisdiction compliance:Simultaneous FDA food contact notification and EFSA safety assessments for new film additives extend product qualification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Stock Films Market |
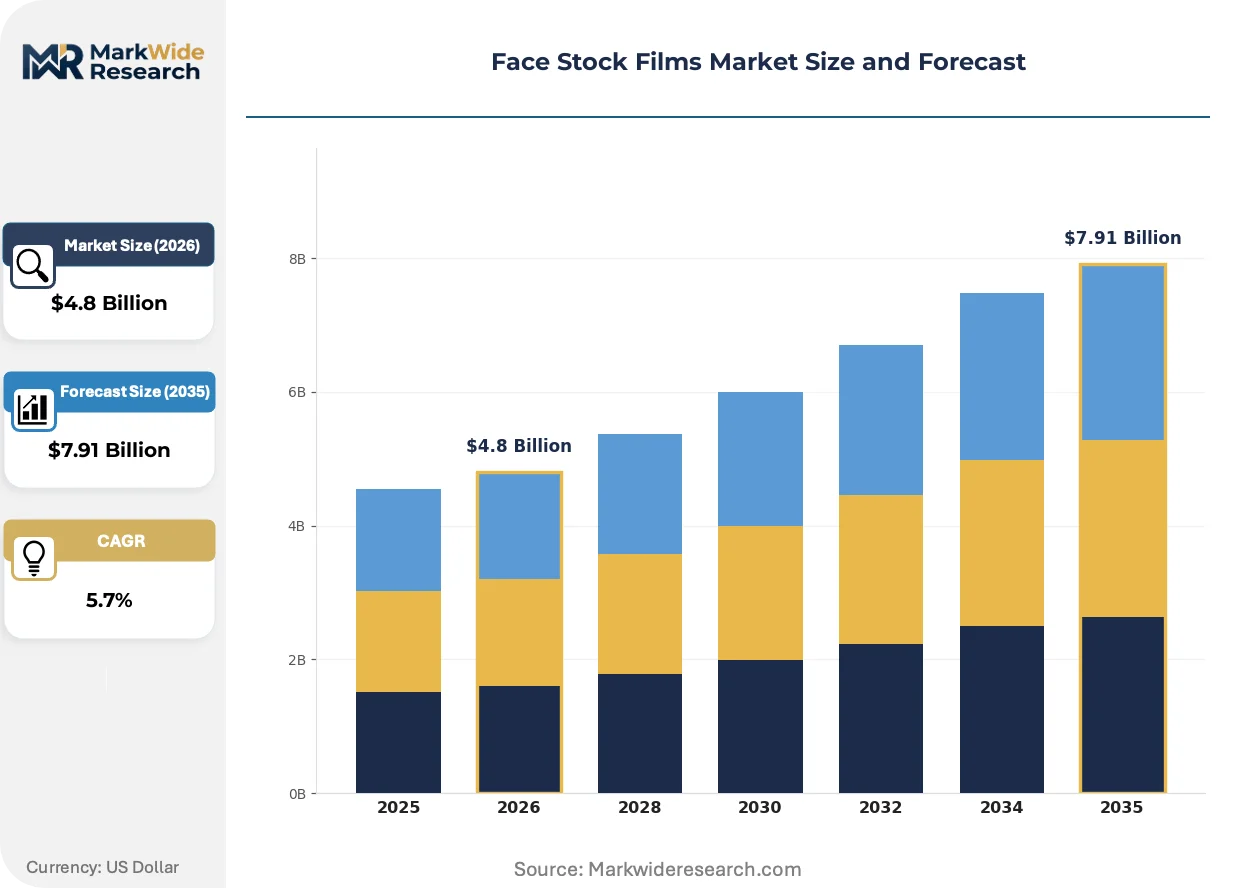
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, Vinyl, Paper Application: Labels, Packaging, Decoration, Surface Protection End User: Food & Beverage, Pharmaceuticals, Electronics, Retail Technology: Digital Printing, Flexographic Printing, Offset Printing, Gravure Printing |
| Companies Covered | Avery Dennison Corporation, UPM Raflatac, CCL Industries Inc., 3M Company, LINTEC Corporation, Mondi Group, Sappi Limited, Nippon Paper Industries Co., Ltd., Ritrama S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Stock Films Market Evolving Landscape
Film suppliers are reconfiguring manufacturing assets around digital printing workflows and circular material flows, compressing traditional equipment amortization cycles while opening new service revenue streams.
Water-based inkjet receptive coatings are decentralizing print production from centralized gravure houses to regional converter operations. Mid-tier label converters in the United States and Germany are adopting hybrid UV inkjet-flexographic presses that switch between technologies based on run length. This equipment flexibility is decentralizing geographic production patterns and reducing minimum order quantities for customized label campaigns.
REACH Annex XVII restrictions on microplastics and the EU Green Deal's carbon border adjustment mechanism are accelerating bio-polymer pilot lines. Film extruders are certifying polylactic acid and bio-polypropylene grades through ASTM D6400 and EN 13432 compostability protocols. European pharmaceutical and organic food brands are absorbing 15-40% price premiums for certified renewable-content face stocks to meet CSRD disclosure requirements.
Brand owners are unbundling label specification from packaging procurement, creating direct relationships with film suppliers. Nestlé and Unilever have established preferred supplier programs that bypass traditional converter intermediaries for sustainability-certified materials. This channel restructuring is most advanced in Germany and the Netherlands, where ESG audit requirements exceed converter certification capabilities.
Face Stock Films Market Segmentation
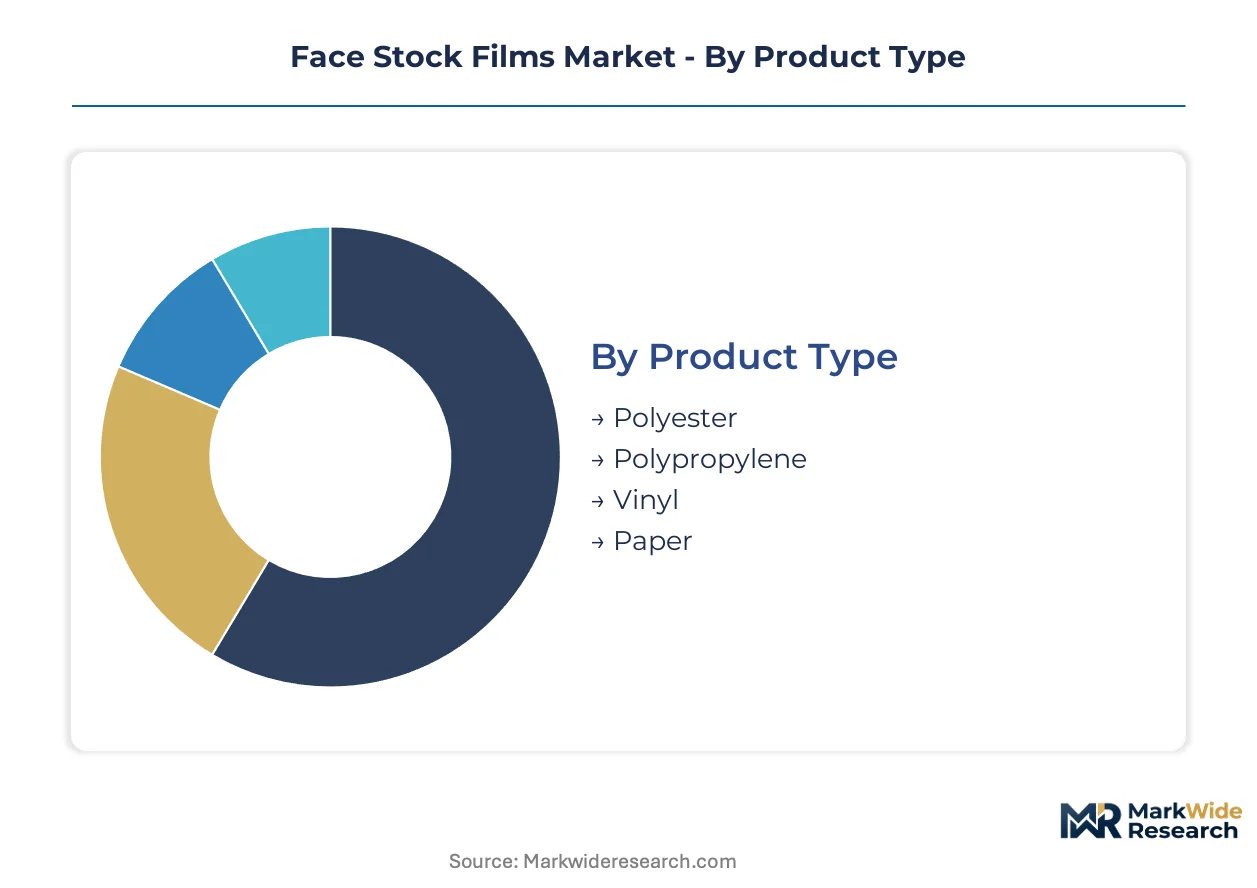
Face stock films serve distinct performance tiers across material chemistries and print technologies. Converter procurement patterns diverge sharply between commodity volume applications and precision-engineered specifications. Understanding these segment boundaries clarifies where margin compression concentrates versus where premium positioning holds.
Product Type:
Polyester commands premium pricing in high-stability applications while polypropylene captures volume share through cost-adjusted performance.
- Polyester:Biaxially oriented polyethylene terephthalate films deliver thermal stability above 150°C and dimensional integrity under tension. Demand concentrates in pharmaceutical serialization labels and automotive under-hood applications where Heidelberg and Stuttgart precision manufacturers specify 50-75 micron grades. FDA food contact notification requirements extend qualification timelines for new additive packages.
- Polypropylene:Oriented and cast polypropylene grades balance moisture resistance with yield economics. Label converters serving German beverage brands are displacing vinyl with chlorine-free alternatives in promotional and decorative segments. REACH substance restrictions on legacy coatings accelerate migration to waterborne adhesive-compatible surfaces.
- Vinyl:Polyvinyl chloride films retain niche positioning in outdoor durability and conformable graphics despite phase-out pressure from brand sustainability mandates.
- Paper:Fiber-based face stocks with extruded polyethylene moisture barriers recapture shelf space in dry-goods logistics where plastic reduction targets override synthetic performance advantages.
Mature deployment sits with polyester in pharmaceutical and industrial specifications. Newer deployment is concentrated in bio-polypropylene pilot lines certifying through EN 13432 compostability protocols.
Application:
Labels absorb the majority of film tonnage while packaging and protection segments split on performance-versus-commodity logic.
- Labels:Pressure-sensitive constructions dominate food and beverage primary labeling, with surface energy profiles engineered for UV inkjet and toner adhesion. German precision converters specify low-haze polyester for premium cosmetic and organic food positioning where shelf differentiation commands material premiums.
- Packaging:Flexible packaging face stocks integrate with barrier films in modified atmosphere applications. FSSAI labeling mandates in India are creating first-time demand for regional language variable data formats in organized retail expansion zones.
- Decoration:Conformable vinyl and soft-touch polypropylene films serve point-of-sale and vehicle wrap markets where visual impact justifies higher material costs.
- Surface Protection:Temporary protective films for electronics and appliance manufacturing prioritize clean removability over print receptivity, sourcing from distinct extrusion asset bases.
Label applications anchor established converter relationships. Packaging represents the steepest expansion trajectory as extended producer responsibility frameworks reshape material specifications.
End User:
Food and beverage procurement concentration drives volume commitments while pharmaceutical compliance requirements filter supplier资格.
- Food & Beverage:Multinational brand owners consolidate supplier rosters and bypass converter intermediaries for sustainability-certified materials. Nestlé and Unilever preferred supplier programs in Germany and the Netherlands demand mass-balance accounting for recycled content claims.
- Pharmaceuticals:Unit-dose and serialization labels require dimensional stability across temperature excursions. EMA guidance on tamper-evident features and FMD compliance drives specification rigor.
- Electronics:Static-dissipative and cleanroom-compatible films serve component labeling and temporary protection in semiconductor and display manufacturing.
- Retail:Variable data and promotional campaigns favor digital-print-compatible polypropylene for shorter run lengths and faster turnaround.
Pharmaceutical specifications favor incumbent polyester suppliers with established FDA master files. Retail applications are gaining share fastest as brand owners unbundle specification authority from packaging procurement.
Technology:
Digital printing workflows are reconfiguring film surface engineering priorities while conventional processes defend long-run economics.
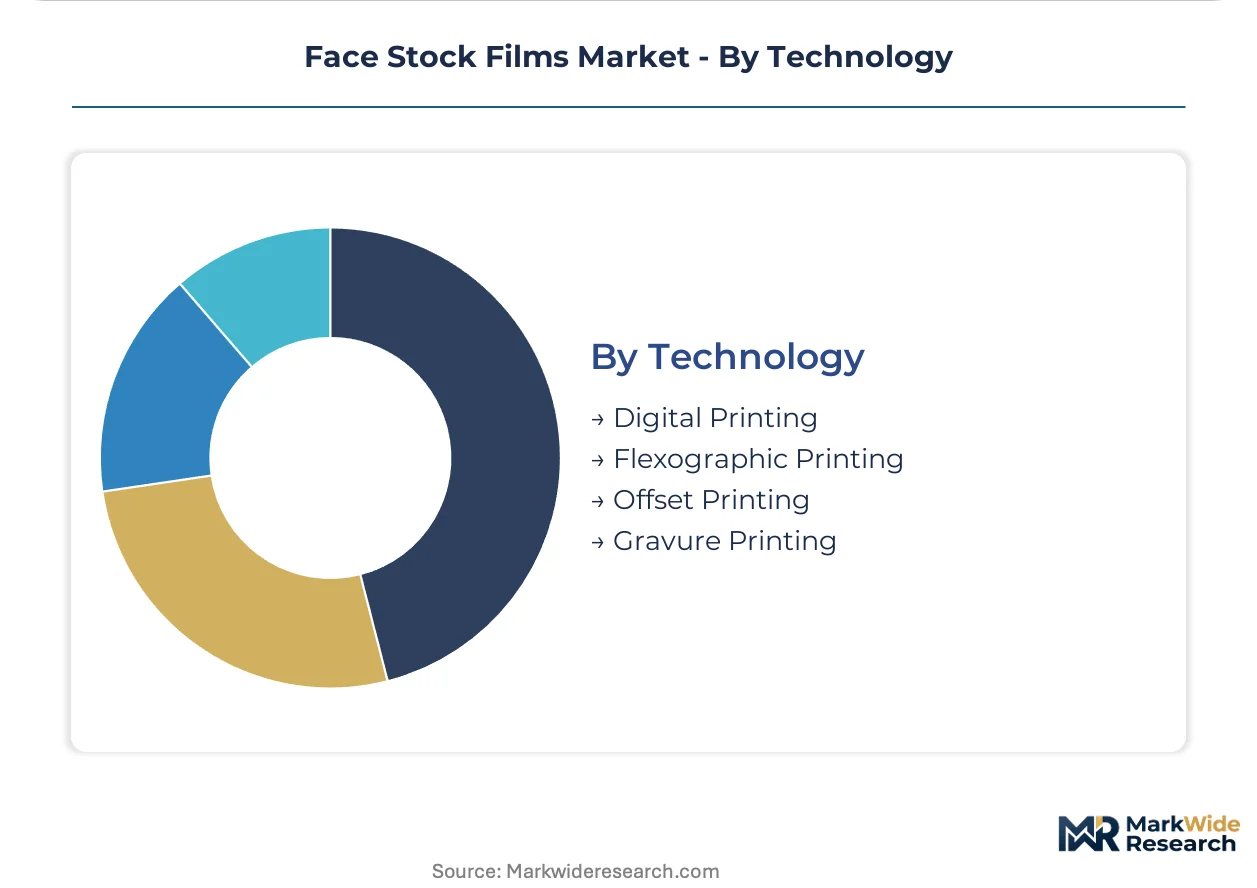
- Digital Printing:UV inkjet and toner-based systems demand controlled surface energy and porosity for immediate ink adhesion. Film suppliers reformulate topcoats to optimize dot gain and color gamut for hybrid press configurations.
- Flexographic Printing:Central impression drum presses remain dominant for food and beverage volume runs, with anilox specifications driving surface roughness requirements in polypropylene grades.
- Offset Printing:Sheet-fed offset for pressure-sensitive labelstock concentrates in premium cosmetic and pharmaceutical applications requiring fine screen rulings.
- Gravure Printing:Cylinder-engraved long-run decoration and packaging applications defend specialized asset bases with distinct film thickness and lay-flat specifications.
Gravure and offset anchor high-volume established production. Digital printing adoption is climbing the fastest as mid-tier converters in the United States and Germany deploy hybrid press configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Label converter procurement concentrates in Germany, where precision manufacturing clusters around Heidelberg and Stuttgart drive specification rigor for polyester and oriented polypropylene grades. This demand-side concentration shapes regional supply chain configuration across multiple continents.
Germany
Heidelberg and Stuttgart anchor pharmaceutical and premium food label manufacturing requiring dimensional stability in 50-75 micron polyester grades. REACH Annex XVII restrictions on microplastics accelerate bio-polymer pilot line investments. Baden-Württemberg precision converters specify low-haze films for organic food shelf differentiation.
United States
Mid-tier label converters deploy hybrid UV inkjet-flexographic presses for shorter run lengths and variable data campaigns. FDA food contact notification requirements and EPA per- and polyfluoroalkyl substance restrictions constrain coating chemistry choices. California's Proposition 65 and Safer Consumer Products regulations add state-level compliance complexity for West Coast-bound shipments.
India
Organized retail expansion and FSSAI labeling mandates create first-time demand for pressure-sensitive labels in regional languages. The PLI scheme for packaging materials attracts extrusion capacity investments. Maharashtra and Gujarat converter clusters serve emerging branded food and beverage distribution networks.
China
Flexible packaging integration with barrier films supports modified atmosphere food applications. NMPA pharmaceutical serialization requirements align with EMA tamper-evident guidance for export-bound label stocks. Yangtze River Delta film extruders certify mass-balance accounting for EU-bound recycled content claims.
Japan
Static-dissipative and cleanroom-compatible films serve semiconductor component labeling and electronics temporary protection. METI carbon neutrality roadmaps pressure coating facilities to reformulate solvent-based systems. Kansai region precision manufacturers specify ultra-low haze grades for cosmetic and pharmaceutical primary labels.
Face Stock Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and digital print compatibility as differentiation vectors. Market structure tilts toward consolidation among large converters and packaging houses, concentrating procurement leverage among fewer buyers. Three archetypes dominate: backward-integrated material suppliers controlling adhesive and release liner production; sustainability-focused portfolio builders with certified renewable content streams; and regional specialists guaranteeing supply security through distributed coating assets. Competitive moves center on securing volume commitments through captive supply integration and certifying mass-balance accounting systems for ESG-mandated buyers.
Within the backward-integrated tier, Avery Dennison Corporation and UPM Raflatac exemplify archetypes combining material production with converter relationship depth. CCL Industries Inc. occupies a position among regional supply security specialists. These three entities anchor competitive dynamics as multinational food and beverage brands consolidate supplier rosters and bypass traditional converter intermediaries for sustainability-certified materials.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM Raflatac |
| CCL Industries Inc. |
| 3M Company |
| LINTEC Corporation |
| Mondi Group |
| Sappi Limited |
| Nippon Paper Industries Co., Ltd. |
| Ritrama S.p.A. |
| Others |
Value Network & Pricing Analysis
Backward integration into adhesive and release liner production anchors both supply security and pricing leverage for film suppliers serving consolidated label converters. This structural choice separates volume-committed producers from spot-market participants in Germany's Heidelberg-Stuttgart precision manufacturing corridor, where REACH compliance costs and ESG certification premiums concentrate margin differentiation.
Pricing Analysis
Volume-margins split sharply between commodity polypropylene grades and certified bio-polymer premiums. Three-tier pricing structure across premium, standard, and economy levels reflects performance tier, certification level, and volume scale as primary differentiation drivers. Cost compression in standard grades is intensifying because paper face stock substitution and petrochemical feedstock volatility squeeze extruder margins. Large multinational food and beverage buyers exhibit lowest price sensitivity due to ESG mandate compliance requirements, while mid-tier converters in emerging markets remain most price-sensitive.
Supply Chain Analysis
Reverse-logistics flows for release liner recycling and post-consumer recycled film streams are emerging as supply chain differentiators under EU Packaging and Packaging Waste Regulation extended producer responsibility frameworks. Geographic supply concentration centers on Germany, the United States, and China as primary extrusion and coating hubs. Raw material dependencies draw from polypropylene resin, polyester terephthalate, and silicone release coatings as critical inputs. Single-source vulnerability in specialized coating technician knowledge creates structural risk for European and North American facilities. Distribution runs through converter intermediaries, though Nestlé and Unilever preferred supplier programs are disintermediating direct film procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The face stock films market sits in a technology-transition phase as UV inkjet digital printing displaces gravure and flexographic workflows in mid-volume converter operations. This equipment shift demands reformulated surface energy profiles and opens service revenue streams beyond commodity film supply.
For Market Incumbents: Acquire coating technician expertise and solventless silicone curing capabilities to defend against specialist coating facility scarcity. Secure backward integration into waterborne adhesive systems to offset REACH Annex XVII restriction impacts on legacy chemistries. Certify mass-balance accounting systems for ESG-mandated buyers before converter certification gaps widen.
For New Entrants and Emerging Players: Enter via India's organized retail expansion zones where FSSAI labeling mandates create first-time pressure-sensitive label demand in regional languages. Target bio-polypropylene pilot line investments with EN 13432 compostability certification to capture 15-40% price premiums from European pharmaceutical and organic food brands. Deploy direct-to-brand-owner sales models that bypass established converter channels in Germany and the Netherlands.
For Investors and Strategic Acquirers: Exit pathways concentrate in sustainability-focused portfolio builders with certified renewable content streams and mass-balance accounting capabilities. Long-term viability hinges on positioning for circular material flow mandates rather than linear production models. Monitor RFID inlay integration rates with traditional face stock laminates as inflection indicator for smart packaging premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Captures margin from REACH-restricted legacy coating chemistries while securing volume commitments from consolidated buyers. |
| Bio-Polymer Pilot Line Certification | Enables EN 13432 compostability claims that command premiums from CSRD-disclosing European brand owners. |
| Digital Print Surface Engineering | Reformulates topcoats for UV inkjet adhesion as hybrid press adoption climbs in United States and Germany converter bases. |
| Mass-Balance Accounting System Implementation | Satisfies Nestlé and Unilever preferred supplier program requirements for recycled content verification. |
| RFID Inlay Integration Capability | Converges printed electronics with face stock laminates for pharmaceutical authentication and cold-chain monitoring applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this face stock films analysis. Primary interviews with label converter procurement directors, film extruder plant managers, coating facility technical leads, and brand owner sustainability officers combined with secondary validation from ECHA REACH substance databases, FDA food contact notifications, and EU Packaging and Packaging Waste Regulation implementation documents. Bottom-up volume modeling across material grades and top-down value reconciliation through industry association statistics ensured cross-verified outputs.
Data-stream reconciliation across shipment volumes, resin price indices, and converter capacity utilization informed the analytical framework across the analysis window. Segmentation dimensions modeled include material chemistry, application type, end-use industry, print technology compatibility, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical volume movements adjusted for identified catalyst and restraint magnitudes. Forecast inputs incorporated digital press adoption curves and bio-polymer certification timelines as industry-specific variables.
Revisions become necessary when regulatory divergence between FDA and EFSA accelerates, petrochemical feedstock volatility exceeds historical bands, or paper face stock moisture barrier performance crosses synthetic substitution thresholds. Practitioners should monitor REACH Annex XVII microplastic restriction enforcement, EPA per- and polyfluoroalkyl substance phase-out pace, and hybrid press deployment rates in mid-tier converter operations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Window Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Foam Trays Market
Packaging Materials
Packaging Materials Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
US Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Sun Control Films Market