
 Big Bag Discharge Station Market | 2026-2036
Big Bag Discharge Station Market Size, Share, and Industry Trends Forecast 2026-2036
Big Bag Discharge Station Market Analytics
REACH chemical safety standards are consolidating the cost-of-entry calculus for Big Bag Discharge Station suppliers across Europe. AZO leverages its German manufacturing base to sustain dominance in automated discharge systems for pharmaceutical cleanrooms. Flexicon anchors North American demand through extensive distributor networks serving chemical manufacturing clusters. Spiroflow differentiates via specialized custom solutions for complex powder handling applications in food processing.
A Big Bag Discharge Station is an industrial material handling system designed to empty flexible intermediate bulk containers through controlled discharge mechanisms, typically incorporating vibration aids, fluidization systems, or mechanical agitators to ensure complete product evacuation. These stations serve primary industrial purposes in bulk powder and granular material transfer across food processing, chemical manufacturing, and pharmaceutical production environments where contamination control and operator safety are critical. Automated discharge systems command premium positioning due to labor cost reduction and precision dosing requirements, while manual configurations retain relevance in smaller-scale food processing operations where capital constraints limit technology uptake. Custom solutions capture concentrated margin pools in pharmaceutical applications where FDA and EMA validation protocols demand tailored engineering.
EMA pharmaceutical guidelines, FDA food safety modernization requirements, and OSHA dust exposure limits collectively shape equipment specifications and market access conditions for Big Bag Discharge Station manufacturers. EMA's emphasis on contained powder transfer is driving sealed-system demand in European pharmaceutical facilities, while OSHA combustible dust enforcement in US chemical plants is accelerating replacement cycles for legacy open-frame designs. Stakeholders must monitor evolving ATEX explosion protection standards and their divergence from OSHA interpretations, as compliance strategy choices will determine which product architectures achieve cross-border deployment economics.
Market Dynamics
Automated discharge architecture is consolidating market power as European food processors and chemical manufacturers confront simultaneous compliance mandates from REACH and EU hygiene directives. Capital deployment now favors sealed-system designs that satisfy multiple regulatory frameworks through single-platform engineering.
Growth Catalysts
- REACH chemical safety standards:Equipment upgrade cycles across European chemical manufacturing are accelerating replacement of open-frame discharge systems with contained architectures that prevent operator exposure.
- German industrial corridor concentration:Bulk material handling modernization programs in Rhineland manufacturing clusters are generating concentrated demand for high-throughput automated stations.
- Fluidization system advances:Pneumatic discharge technologies incorporating vibration aids and mechanical agitators are achieving complete product evacuation rates that manual configurations cannot match.
Market Restraints
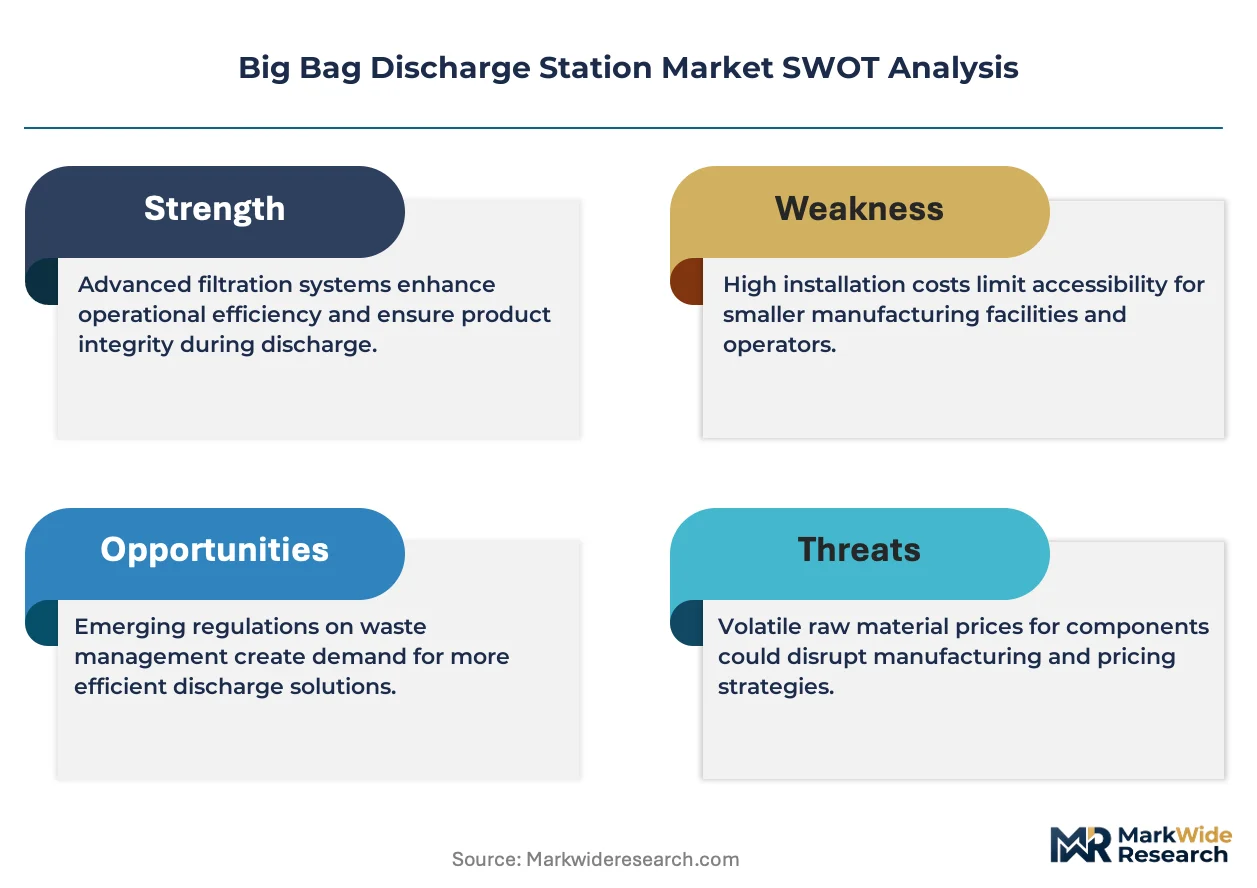
- Stainless steel input volatility:Grade 316L price fluctuations directly compress margins for pharmaceutical-grade discharge station fabricators serving FDA-regulated cleanrooms.
- Specialized component supply concentration:Precision dosing valves and sealed bearing assemblies for ATEX-rated systems depend on a narrow base of German and Swiss precision engineering suppliers.
- Legacy open-frame substitution ceiling:Smaller-scale food processors in Southern Europe retain manual configurations due to capital constraints, capping premium system penetration.
Strategic Opportunities
- Italian food processing modernization:Mid-tier pasta and ingredient manufacturers lag German automation rates, creating whitespace for modular discharge systems with phased upgrade pathways.
- EMA contained powder transfer mandate:Pharmaceutical facilities across France and the Netherlands require sealed-system retrofits that validate under cross-border deployment protocols.
- Condition monitoring convergence:Integration of vibration sensors with predictive maintenance platforms enables service unbundling and recurring revenue streams for equipment providers.
Industry Challenges
- ATEX-OSHA divergence complexity:Equipment architects must engineer dual-certification pathways as European explosion protection standards diverge from US interpretations.
- Cleanroom validation timeline compression:FDA and EMA protocol requirements extend pharmaceutical system commissioning cycles, straining working capital for project-based manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Bag Discharge Station Market |
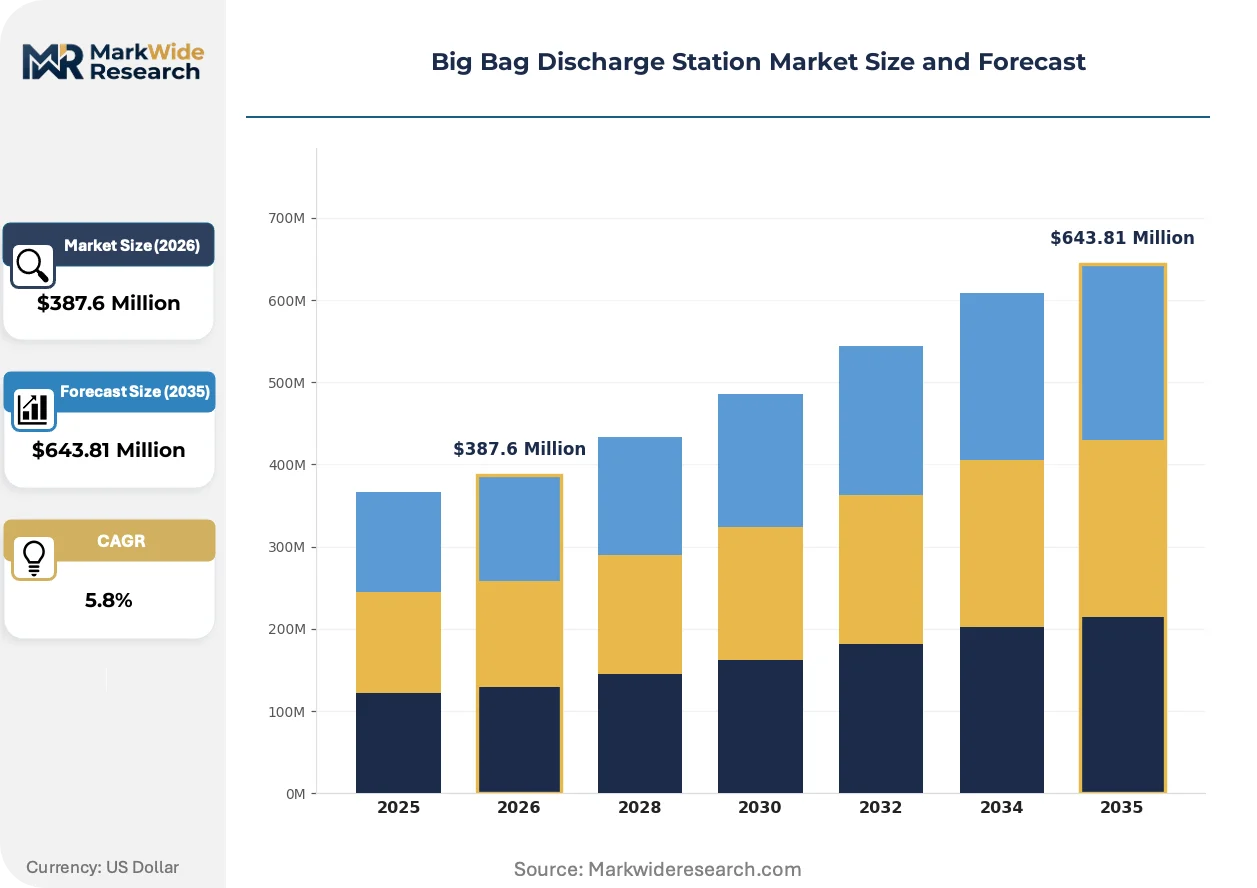
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Discharge, Automated Discharge, Semi-Automated Discharge, Custom Solutions Industry Vertical: Food Processing, Chemical Manufacturing, Pharmaceutical, Construction End User: Manufacturers, Distributors, Warehouses, Suppliers Installation Type: Fixed, Portable, Mobile, Integrated |
| Companies Covered | AZO, Flexicon, Spiroflow, Hapman, NBE, Schenck Process, Material Transfer, VAC-U-MAX, Gericke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Bag Discharge Station Market Evolving Landscape
Discharge station engineering is pivoting toward containment-centric architectures as regulatory pressure intensifies across food, chemical, and pharmaceutical verticals. System designers are prioritizing sealed transfer mechanisms that satisfy multiple compliance frameworks through unified platform strategies.
Integrated fluidization technology is consolidating competitive advantage in high-value pharmaceutical applications. These systems combine pneumatic vibration with controlled air injection to achieve complete powder evacuation without operator exposure. German cleanroom operators are adopting these configurations at accelerated rates. The technology is consolidating supplier margins by compressing commissioning timelines and reducing validation documentation burdens.
REACH chemical safety standards are mandating contained-system retrofits across European chemical manufacturing corridors. The regulation's emphasis on operator exposure limits is rendering open-frame discharge architectures non-compliant. Chemical processors in Belgium and the Netherlands are responding with capital programs that prioritize sealed-system designs capable of handling multiple hazardous powder classifications.
Service contracting patterns are evolving as pharmaceutical buyers unbundle equipment purchase from validation support. Large-scale API manufacturers now procure discharge stations through separate capital and service agreements, with validation documentation priced as a distinct deliverable. This bifurcation is most pronounced in German and Swiss production facilities where EMA audit frequencies have intensified.
Big Bag Discharge Station Market Segmentation
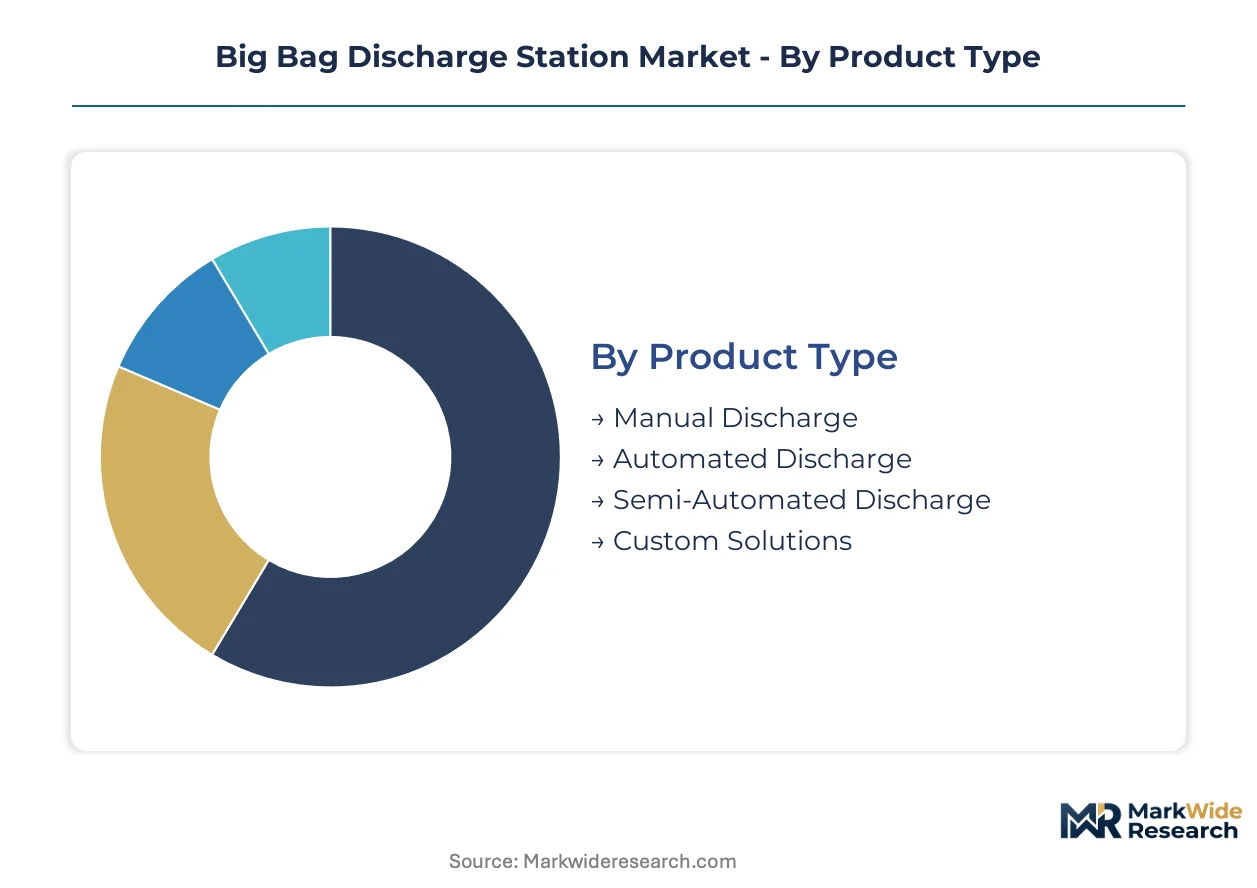
Segmentation in Big Bag Discharge Station procurement reflects divergent capital constraints and compliance burdens across end-use environments. Buyers sort architectures by labor substitution economics, containment requirements, and installation permanence rather than throughput specifications alone.
Product Type:
Customization intensity varies sharply across this category, from standardized manual units to engineered-to-order pharmaceutical systems requiring validation documentation.
- Manual Discharge:Basic frame-and-spout configurations rely on operator-controlled knife gates or untie boxes for powder release. Southern European pasta manufacturers and mid-tier ingredient blenders favor these units where REACH compliance permits open-frame designs and capital budgets constrain automation.
- Automated Discharge:Sealed architectures integrate pneumatic knife actuators, dust containment hoods, and load cell dosing for continuous operation without operator exposure. German chemical corridors and Dutch pharmaceutical facilities deploy these systems to satisfy simultaneous REACH and EMA mandates through single-platform engineering.
- Semi-Automated Discharge:Hybrid designs pair manual bag loading with automated discharge actuation, bridging cost and compliance gaps for mid-scale food processors.
- Custom Solutions:Engineered configurations address ATEX-rated hazardous powders, FDA-validated cleanrooms, or extreme temperature materials through bespoke fluidization and containment engineering.
Leading the category by volume: Automated Discharge. Growing fastest: Custom Solutions.
Industry Vertical:
Regulatory stringency and contamination risk tolerance segment demand into discrete specification tiers with minimal cross-purchasing.
- Food Processing:Hygienic stainless-steel construction dominates, with EU hygiene directives mandating smooth welds and clean-in-place compatibility. Italian and French ingredient manufacturers drive modular system demand with phased automation roadmaps.
- Chemical Manufacturing:REACH exposure limits and ATEX explosion protection requirements concentrate procurement in contained, grounded architectures. Belgian and Netherlands processors prioritize sealed-system retrofits for hazardous powder classifications.
- Pharmaceutical:EMA contained powder transfer mandates and FDA validation protocols specify isolator-integrated discharge with single-use containment options.
- Construction:Cement and mineral additive handling tolerates open-frame designs where dust exposure regulations permit cost-minimized configurations.
Dominant by procurement value: Pharmaceutical. Expanding most quickly: Food Processing.
End User:
Capital deployment patterns and maintenance capability differentiate procurement behavior across the buyer base.
- Manufacturers:Direct production integration demands high-availability architectures with predictive maintenance interfaces and OEM service contracts.
- Distributors:Batch flexibility requirements favor quick-changeover configurations serving multiple material specifications.
- Warehouses:Throughput-maximizing designs prioritize discharge rate over containment precision in bulk transfer applications.
- Suppliers:Rental and lease-fleet operators specify ruggedized portable units with minimal calibration dependencies.
Primary volume concentration: Manufacturers. Fastest adoption growth: Distributors.
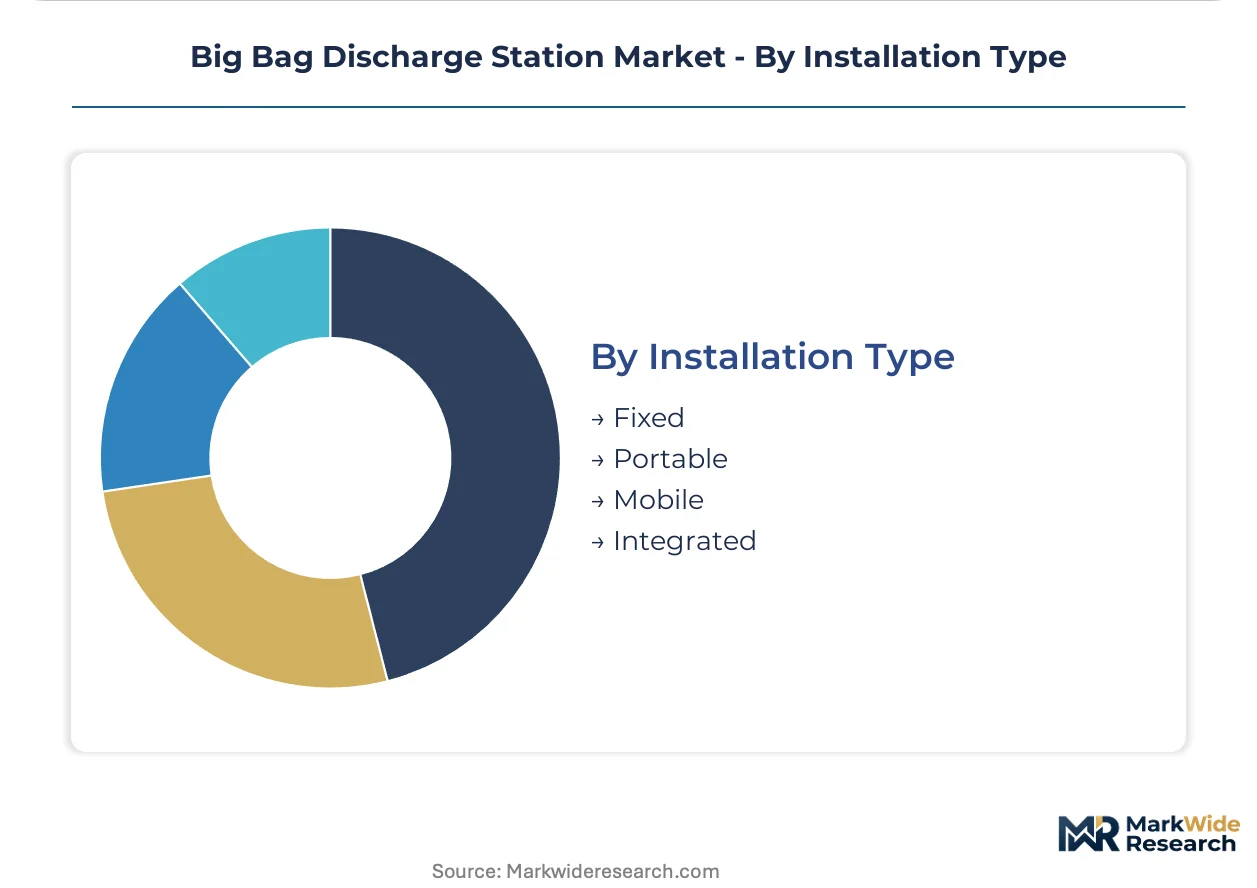
Installation Type:
Mobility requirements and facility permanence shape engineering trade-offs between structural integration and operational flexibility.
- Fixed:Permanent steel-frame installations anchor high-throughput production lines with dedicated dust collection and pneumatic conveying integration. German Rhineland chemical clusters favor these configurations for continuous operation.
- Portable:Forklift-transportable skid-mounted units enable seasonal production flexibility and multi-line deployment across Italian food processing facilities.
- Mobile:Castor-mounted configurations serve contract manufacturing and pilot-scale operations where rapid relocation outweighs throughput optimization.
- Integrated:Pre-engineered modules incorporating discharge, conveying, and dosing functions reduce commissioning timelines for greenfield pharmaceutical facilities in France and the Netherlands.
Highest installed base: Fixed. Steepest expansion trajectory: Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland manufacturing clusters concentrate European demand through German special economic zones offering accelerated depreciation for automation investments. These zones channel capital toward contained discharge architectures that satisfy overlapping regulatory mandates.
Germany
Rhineland chemical corridors drive automated station procurement for REACH-compliant hazardous powder handling. ECHA enforcement of exposure limits is rendering open-frame designs obsolete across Belgian border-adjacent facilities. Dortmund and Düsseldorf industrial zones anchor retrofit programs integrating sealed-system discharge with existing pneumatic conveying infrastructure.
France
Pharmaceutical API manufacturers in Île-de-France require EMA-validated contained powder transfer systems for cross-border deployment. ANSM audit intensification is extending commissioning timelines for isolator-integrated stations. Lyon biotech clusters are adopting modular discharge architectures that compress validation documentation burdens.
Italy
Mid-tier pasta and ingredient producers in Emilia-Romagna lag German automation rates, creating whitespace for phased upgrade pathways. EU hygiene directives mandate smooth-weld stainless construction for clean-in-place compatibility. Parma food processing corridors are deploying semi-automated configurations that bridge capital constraints with compliance requirements.
Netherlands
Belgian-adjacent chemical processors prioritize ATEX-rated sealed retrofits for multiple hazardous powder classifications. REACH enforcement through the Dutch chemicals authority is accelerating replacement cycles for legacy discharge architectures. Rotterdam port-adjacent bulk handling facilities are integrating mobile discharge units with seasonal flexibility requirements.
United States
OSHA combustible dust enforcement is driving replacement demand across Gulf Coast chemical manufacturing clusters. FDA food safety modernization requirements specify sanitary construction for ingredient handling operations. Houston and Louisiana industrial corridors are adopting automated dosing configurations that reduce operator exposure while maintaining throughput.
Big Bag Discharge Station Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base fragments between European engineering heritage players and North American distributor-anchored networks. Three archetypes dominate: German precision fabricators serving pharmaceutical cleanrooms, US-based systems integrators with extensive distribution reach, and specialized custom engineering houses for complex powder applications. Consolidation pressure is intensifying through strategic partnerships for ATEX certification access and geographic expansion into underpenetrated Southern European food processing markets.
Within the precision-engineering tier, AZO GmbH and Gericke AG exemplify German heritage positioning for EMA-validated pharmaceutical applications. Spiroflow occupies a specialist position for complex powder handling configurations in food processing environments. Flexicon anchors North American demand through distributor-network density rather than direct manufacturing presence. These three represent distinct competitive vectors: cleanroom validation capability, custom engineering responsiveness, and channel-scale coverage.
| Leading Market Players |
|---|
| AZO |
| Flexicon |
| Spiroflow |
| Hapman |
| NBE |
| Schenck Process |
| Material Transfer |
| VAC-U-MAX |
| Gericke |
| Others |
Value Network & Pricing Analysis
German pharmaceutical cleanroom operators concentrate procurement power for FDA-validated discharge stations, anchoring a project-based pricing model where validation documentation carries discrete value. This buyer concentration enables suppliers to unbundle equipment from service contracts, reshaping margin capture across the value chain.
Pricing Analysis
Short lead-time premiums apply to ATEX-rated systems requiring expedited German and Swiss precision component sourcing. Project-based pricing dominates, with differentiation resting on EMA validation tier and stainless steel grade certification. Cost compression in manual configurations intensifies as Southern European food processors defer automation investments. Distributors exhibit highest price sensitivity; pharmaceutical API manufacturers prioritize containment performance over capital outlay.
Supply Chain Analysis
Freight cost volatility from German and Swiss precision engineering suppliers elevates landed costs for North American and Asian end-users. Manufacturing concentrates in Germany, Switzerland, and the United States. Component sourcing draws from specialized valve fabricators and sealed bearing specialists. Single-source vulnerability persists for ATEX-certified dosing assemblies. Distribution runs through OEM-direct channels for pharmaceutical applications and distributor networks for chemical manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over validation documentation capabilities and precision component supply determines margin sustainability. Players are pursuing backward integration into stainless steel fabrication and captive certification laboratory capacity.
For Market Incumbents: Hedge against margin erosion in standardized manual configurations by deepening captive supply of Grade 316L stainless components. Consolidate position in pharmaceutical validation services as EMA audit frequencies intensify. Acquire Swiss or German precision valve specialists to secure ATEX component supply. For New Entrants and Emerging Players: Mid-tier Italian pasta and ingredient manufacturers represent accessible whitespace where phased semi-automated upgrade pathways outperform full-system displacement. Target Emilia-Romagna clusters with modular rental-to-own financing that bridges capital constraints. Pursue distributor partnerships rather than direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors custom engineering houses with EMA validation track records and established pharmaceutical relationships. Long-term viability centers on service revenue unbundling and predictive maintenance platform integration. Monitor REACH enforcement intensity as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Component Manufacturing | Captive supply of ATEX-rated dosing valves reduces exposure to Swiss and German supplier concentration. |
| Validation Documentation Unbundling | Separate pricing for EMA and FDA compliance packages creates recurring revenue from pharmaceutical API manufacturers. |
| Modular Semi-Automated Product Line Launch | Phased upgrade pathways address capital constraints among Italian and French mid-tier food processors. |
| Predictive Maintenance Platform Integration | Vibration sensor convergence enables service contracting and aftermarket revenue capture from German chemical corridors. |
| Dual-Certification Engineering Investment | ATEX-OSHA pathway convergence supports cross-border deployment economics for multinational chemical processors. |
Research Methodology
Independent corroboration across maintenance directors at German chemical plants, pharmaceutical procurement leads in France and the Netherlands, and Italian food processing engineers underwrites the qualitative findings. Primary fieldwork with OEM technical sales teams and aftermarket service heads supplements secondary validation through REACH enforcement disclosures, EMA inspection reports, and customs data on precision component trade flows. Bottom-up demand modeling triangulates against top-down industrial capital expenditure patterns.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions span automation tier, containment architecture, installation permanence, and regulatory validation cluster. CAGRs derive from equipment replacement cycle analysis and compliance mandate timing. Forecast inputs incorporate stainless steel price trajectory assumptions and EMA audit schedule intensification patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement variability and precision component supply disruptions. Outputs reflect documented assumptions regarding regulatory timeline adherence and capital availability among mid-tier food processors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Circular Industrial Bags Market