
 Bags and Containers Market | 2026-2036
Bags and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Bags and Containers Market Intelligence
Subscription-based packaging replenishment services is shifting how enterprises procure bags and containers, converting capital expenditure into recurring operational contracts. Amcor plc leverages its global manufacturing footprint to anchor multi-year supply agreements with beverage and food clients. Berry Global competes through vertical integration in resin production, controlling raw material costs across its container portfolio. Huhtamaki Oyj specializes in fiber-based molded containers, positioning its product line ahead of single-use plastic restrictions in European markets.
Bags and containers encompass portable enclosures fabricated from flexible films, rigid plastics, paper substrates, or composite laminates, engineered to protect, store, and transport goods across supply chains; specifications include tensile strength, moisture vapor transmission rates, and seal integrity measured under ASTM or ISO protocols. Kraft paper and jute segments sustain premium positioning in retail and agricultural applications where biodegradability commands price premiums. Polyethylene containers dominate industrial use due to chemical resistance and dimensional stability under load. Biodegradable containers represent the fastest-expanding material category as food packaging buyers face mandates from regulators and corporate sustainability targets.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications shape material selection and market access, with REACH compliance adding testing burdens for imported polymer formulations. China's GB standards for plastic food containers and India's BIS certification for packaging materials create divergent compliance pathways that fragment supplier qualification requirements. Stakeholders must monitor how extended producer responsibility schemes in the European Union and state-level plastic bans in the United States reshape cost structures and demand geography before committing capacity expansion decisions.
Market Dynamics
Subscription-based packaging replenishment services are converting capital expenditure into recurring operational contracts, fundamentally restructuring how enterprises procure bags and containers across food, beverage, and e-commerce verticals.
Growth Catalysts
- E-commerce logistics adoption:Durable shipping containers face accelerating pull from fulfillment networks handling higher return volumes and last-mile complexity.
- EU Packaging and Packaging Waste Regulation:Mandatory material recovery targets force brand owners into compliant sourcing, creating guaranteed demand for certified recyclable and reusable formats.
- Biodegradable material innovation:Polylactic acid and cellulose-based films achieve cost parity in food contact applications, opening substitution pathways against conventional polyethylene.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene prices fluctuate with naphtha and natural gas feedstock swings, compressing converter margins without pass-through mechanisms.
- China manufacturing concentration:Export-oriented container production clusters in Zhejiang and Guangdong provinces create geographic supply risk from trade policy shifts or logistics disruptions.
- Technical limitation in barrier performance:Fiber-based molded containers fail to match multilayer plastic films on moisture vapor transmission rates, restricting adoption in moisture-sensitive food categories.
Strategic Opportunities
- Underpenetrated cold-chain packaging in India:Temperature-sensitive pharmaceutical and fresh produce distribution lacks insulated container infrastructure, creating white space for phase-change material solutions.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms incentivize local production of low-emission containers, rewarding European-based fiber and biopolymer converters.
- Smart packaging convergence:Integration of RFID tags and temperature sensors into reusable shipping containers enables asset tracking and condition monitoring, unlocking premium pricing in high-value logistics.
Industry Challenges
- Composting infrastructure gap:Industrial composting facility scarcity limits end-of-life value proposition for biodegradable containers, forcing manufacturers to invest in collection partnerships.
- REACH compliance timeline:Polymer formulation testing and substance notification requirements extend new product qualification cycles by 12-18 months for European market entry.
- Legacy equipment retrofit costs:Converting extrusion and thermoforming lines to process novel biopolymers demands capital outlay that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bags and Containers Market |
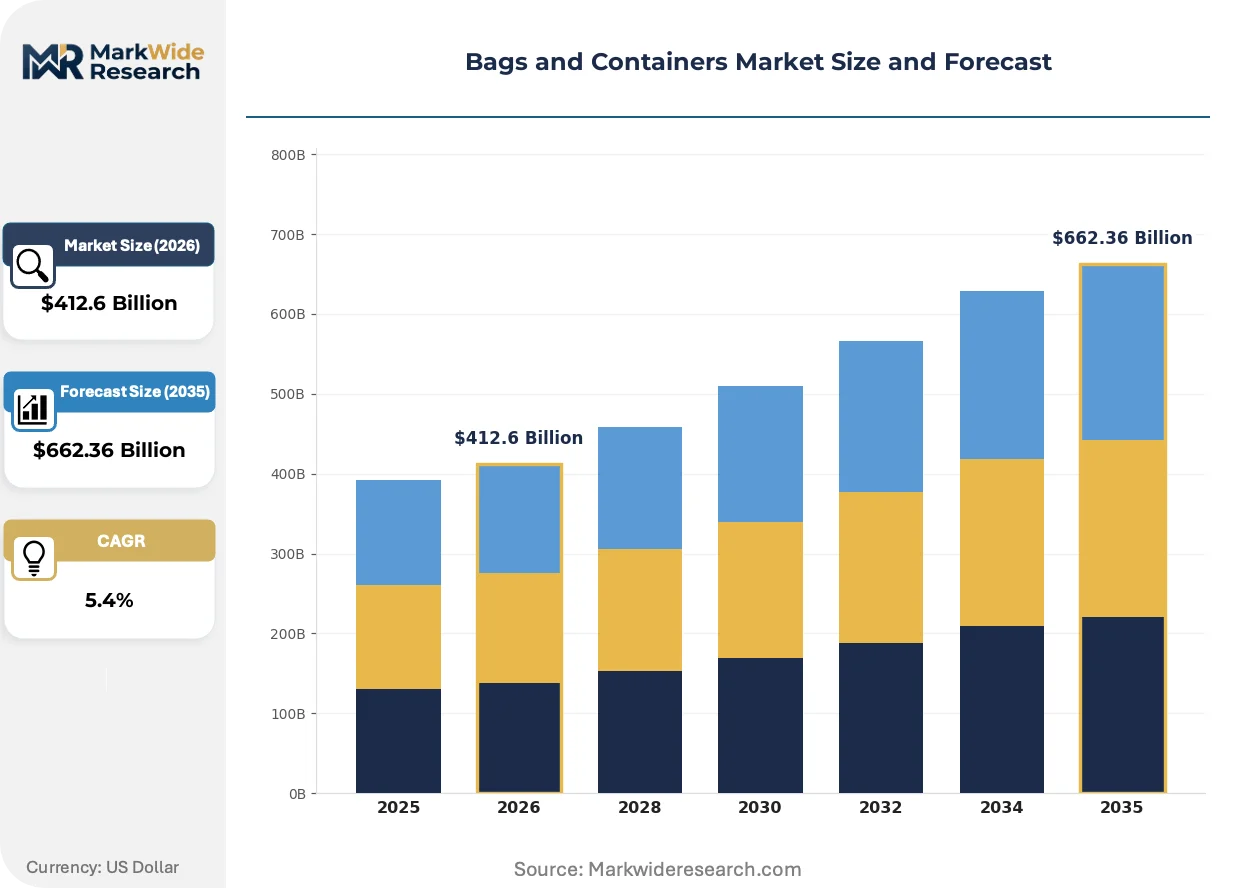
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $662.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Plastic Containers, Paper Bags, Biodegradable Containers Material: Polyethylene, Polypropylene, Kraft Paper, Jute Application: Food Packaging, Retail, Waste Management, Industrial Use Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global, International Paper Company, DS Smith Plc, Smurfit Kappa Group, WestRock Company, Novolex Holdings, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bags and Containers Market Strategic Shifts & Innovations
Active and intelligent packaging technologies are migrating from premium positioning toward mass-market deployment, while regulatory pressure on single-use formats accelerates material substitution across food service and retail channels.
Monomaterial polyethylene films engineered for full recyclability are expanding into frozen food and snack packaging where multilayer laminates previously dominated barrier performance. Major retail chains in Germany and France now specify monomaterial structures in private-label tenders, compressing demand for legacy metallized and coextruded formats. The technology is expanding into stand-up pouches and form-fill-seal applications previously considered incompatible with single-resin solutions.
REACH substance restrictions on per- and polyfluoroalkyl substances compel reformulation of grease-resistant paper and board containers across European food service. Manufacturers face accelerated substitution timelines as ECHA evaluates additional PFAS limitations, with Denmark and the Netherlands already enforcing stricter national standards. Fiber-based molded pulp formats with bio-based barrier coatings capture share in quick-service restaurant packaging as chains preempt regulatory exposure.
Direct-to-brand digital platforms enable small-batch container procurement with shorter lead times, displacing traditional distributor relationships in specialty food and cosmetic segments. These platforms aggregate demand from craft producers and regional brands, consolidating what was fragmented spot purchasing. The shift concentrates in North American and Western European markets where e-commerce penetration in B2B procurement already exceeds 40 percent in packaging categories.
Bags and Containers Market Segmentation
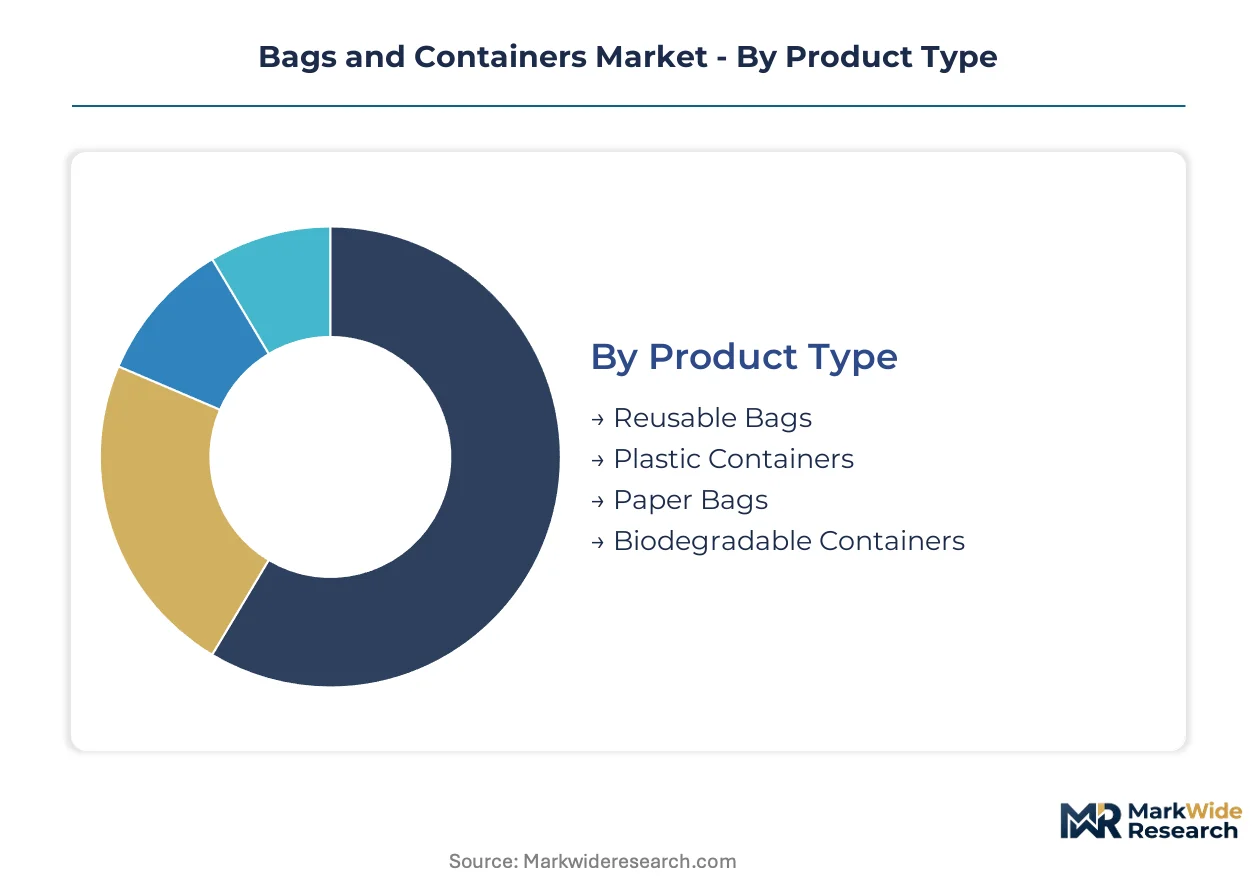
Segmentation in bags and containers reveals divergent capital requirements and margin profiles across material technologies. Product type and material composition determine equipment intensity, while application and size dimensions shape distribution economics and customer concentration.
Product Type:
Capital intensity varies sharply across product categories, with rigid plastic container molding requiring the heaviest upfront machinery investment versus flexible bag converting.
- Reusable Bags:Woven polypropylene and non-woven fabric constructions engineered for 50+ use cycles. Demand concentrates in German and French retail sectors where municipal bag bans and EPR schemes mandate durable alternatives. The EU Packaging and Packaging Waste Regulation creates guaranteed procurement pipelines for certified reusable formats.
- Plastic Containers:Injection-molded polyethylene and polypropylene vessels with tamper-evident closures and stackable geometries. Food packaging buyers in the United States drive specification intensity through FDA food contact substance notifications. Barrier multilayer variants command premium positioning in moisture-sensitive categories.
- Paper Bags:Kraft paper constructions with twisted or flat handles, serving quick-service restaurant and boutique retail channels.
- Biodegradable Containers:Polylactic acid and cellulose-based molded pulp formats targeting composting infrastructure markets.
Most installed capacity flows through Plastic Containers. Expansion is steepest in Biodegradable Containers.
Material:
Raw material cost exposure and supply security differentiate competitive positions, with petrochemical-derived resins facing volatility that bio-based alternatives partially hedge.
- Polyethylene:Linear low-density and high-density grades dominate industrial chemical resistance applications. China's Zhejiang manufacturing clusters process the majority of export-oriented polyethylene container production. GB standards compliance adds qualification burden for foreign suppliers accessing Chinese food packaging channels.
- Polypropylene:High crystallinity resin delivering dimensional stability under load and microwave transparency. India's BIS certification requirements for packaging materials fragment supplier qualification pathways versus European REACH protocols. Copolymer variants penetrate medical and pharmaceutical containment.
- Kraft Paper:Unbleached sulfate pulp constructions with high tear resistance and printability for brand messaging.
- Jute:Natural bast fiber woven into agricultural and premium retail sacks.
Polyethylene and Polypropylene together absorb the majority of material throughput. Jute is gaining share fastest in agricultural export packaging.
Application:
End-use concentration determines specification complexity and contract duration, with food contact applications demanding the most extensive compliance documentation.
- Food Packaging:Barrier-engineered containers and films meeting oxygen and moisture vapor transmission specifications. FDA notification pathways and EU EFSA compliance create divergent regional qualification timelines. Active packaging integration with oxygen scavengers and ethylene absorbers expands in premium fresh produce segments.
- Retail:Branded carry bags and point-of-sale containers with print quality and handle strength as primary specifications.
- Waste Management:Heavy-duty polyethylene sacks for municipal and industrial collection.
- Industrial Use:UN-certified drums and intermediate bulk containers for chemical and hazardous material transport.
Food Packaging commands the longest contract durations. Waste Management shows the steepest volume expansion trajectory.
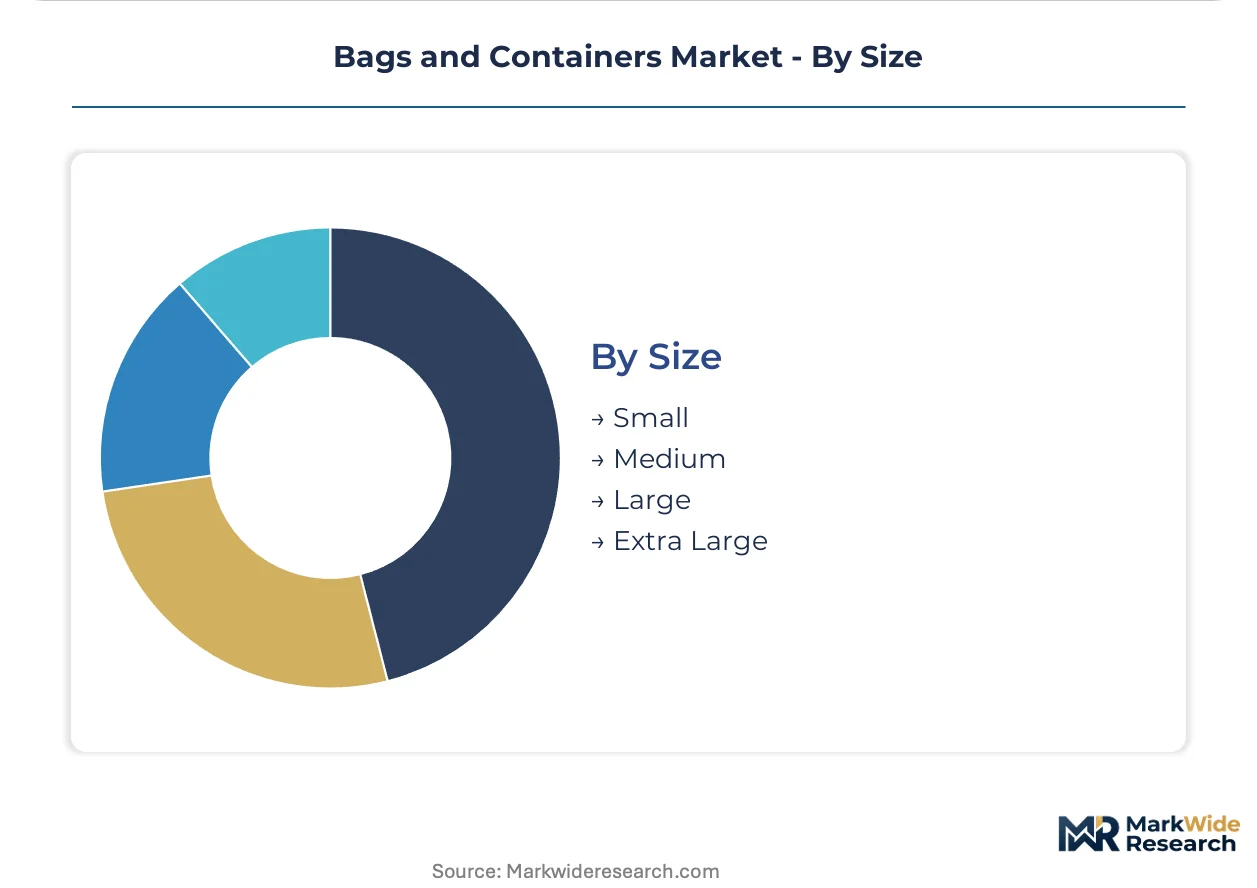
Size:
Dimensional segmentation correlates with logistics economics and automation compatibility, with mid-size formats optimizing pallet cube utilization.
- Small:Single-serve and sample-size containers under 500ml capacity.
- Medium:Standard retail and food service formats between 500ml and 5L.
- Large:Bulk retail and institutional packaging from 5L to 50L.
- Extra Large:Industrial totes, flexible intermediate bulk containers, and shipping sacks exceeding 50L.
Medium size formats dominate unit volume. Extra Large formats deliver the highest revenue per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China sustains heavier container throughput than Germany, yet the EU Packaging and Packaging Waste Regulation imposes stricter recovery mandates than China's GB standards. India's BIS certification requirements diverge from both pathways. Japan's METI guidelines and the United States' FDA notification systems add further fragmentation.
China
E-commerce logistics and export manufacturing sustain polyethylene container demand across Zhejiang and Guangdong clusters. GB standards for plastic food containers mandate specific migration limits and testing protocols. The Yangtze River Delta hosts injection-molding facilities supplying frozen food and beverage packaging to domestic and export markets.
Germany
Retail bag bans and extended producer responsibility schemes drive woven polypropylene reusable bag procurement. ECHA REACH compliance adds substance notification burdens for polymer formulations entering the market. The North Rhine-Westphalia region concentrates thermoforming operations serving food service and industrial chemical containment.
United States
FDA food contact substance notifications shape material selection for food packaging buyers across California and Texas industrial corridors. State-level plastic bans in California and New York fragment regulatory compliance requirements. The Midwest manufacturing belt hosts blow-molding facilities producing UN-certified drums for chemical transport.
India
Cold-chain pharmaceutical distribution and fresh produce logistics generate insulated container demand in Maharashtra and Gujarat. BIS certification for packaging materials creates qualification barriers for imported polymer formulations. The Delhi-NCR corridor aggregates converting operations serving quick-service restaurant and retail channels.
Japan
METI circular economy guidelines and convenience store packaging reduction targets drive fiber-based molded pulp adoption. JIS standards for food contact materials establish testing benchmarks distinct from FDA or EFSA pathways. The Kansai region around Osaka maintains specialty film converting for high-barrier snack and seafood packaging.
Bags and Containers Market Key Industry Players
Top-tier vendors anchor multi-year supply agreements with beverage and food clients, while mid-scale converters compete on regional proximity and customization speed. The market exhibits tiered concentration with global resin-integrated players, regional fiber-specialists, and local flexible-film converters occupying distinct competitive bands. Strategic archetypes include backward-integrated resin producers, fiber-based molded container specialists, and e-commerce logistics packaging innovators. Capacity expansion and portfolio diversification toward biodegradable formats constitute the dominant competitive moves.
Within the resin-integrated tier, Amcor plc and Berry Global exemplify global manufacturing footprint strategies that secure long-term supply contracts. Huhtamaki Oyj occupies a position representing fiber-based molded container specialization ahead of European single-use plastic restrictions. These three anchors demonstrate how geographic scope and material technology differentiation create defendable market positions against commodity pressure.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global |
| International Paper Company |
| DS Smith Plc |
| Smurfit Kappa Group |
| WestRock Company |
| Novolex Holdings |
| Huhtamaki Oyj |
| Others |
Cost & Logistics Intelligence
Naphtha price indices cascading through polyethylene and polypropylene resin markets split container procurement into contract-based long-term offtake for volume buyers and spot-market exposure for smaller converters. Cost pass-through mechanisms favor buyers with backward integration into resin production, while independent converters absorb margin compression from feedstock volatility.
Pricing Analysis
Capacity additions in China's Zhejiang province are reshaping price floors for standard-grade polyethylene containers, forcing European and North American molders into premium-mid-economy pricing differentiation. Certification under FDA food contact substance notifications and EU REACH compliance creates tiered pricing separating pharmaceutical-grade from industrial-grade formats. Pricing pressure stems from resin cost volatility compressing converter margins without full pass-through. Small-batch craft producers show highest price sensitivity, while multinational beverage clients prioritize supply security over unit cost.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang manufacturing clusters are tightening output elasticity for export-oriented container production. Supply concentrates in China, Germany, and the United States, with raw material flows drawing from Saudi Arabian and U.S. Gulf Coast petrochemical feedstocks. Single-source vulnerability runs through concentrated injection-molding equipment suppliers in Germany and Japan. Distribution runs through regional converting hubs that aggregate orders for last-mile fulfillment to retail and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bags and containers rests on biopolymer cost curves flattening against conventional resins, plus premium-tier pull from EU regulatory compliance mandates.
For Market Incumbents: Hedge resin price exposure through captive supply agreements or backward integration into polymer production. Anchor multi-year contracts with beverage and pharmaceutical clients before REACH substance restrictions tighten further. Defend share against fiber-based molded pulp substitutes by accelerating monomaterial recyclable format development.
For New Entrants and Emerging Players: Begin with cold-chain pharmaceutical packaging in India, where temperature-sensitive distribution infrastructure remains underdeveloped. Target quick-service restaurant chains preempting EU single-use plastic bans with compostable molded pulp solutions. Pursue direct-to-brand digital platforms that aggregate fragmented craft producer demand with short-lead-time procurement.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters lack capital to retrofit extrusion lines for biopolymer processing. Long-term viability favors resin-integrated players with global manufacturing footprints and fiber-specialists with European regulatory alignment. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as inflection signals for certified recyclable format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyethylene supply insulates Amcor and Berry Global from naphtha price swings. |
| Biopolymer Capacity Expansion | Polylactic acid molding lines position Huhtamaki ahead of EU single-use plastic restrictions. |
| Monomaterial Film Development | Full-recyclability certification unlocks German and French retail private-label procurement. |
| Smart Packaging Integration | RFID-enabled reusable containers command premium pricing in pharmaceutical cold-chain logistics. |
| Direct-to-Brand Platform Launch | Digital procurement aggregates fragmented specialty food and cosmetic producer demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with procurement managers at food and beverage multinationals, plant managers at Zhejiang and Guangdong converting facilities, regulatory affairs leads navigating REACH and FDA pathways, and sustainability officers at quick-service restaurant chains. Secondary validation drew from customs trade databases, SEC 10-K filings of resin-integrated players, EU ECHA substance restriction announcements, and BIS certification registries. Bottom-up volume modeling across product type, material composition, application, and size dimensions triangulated against top-down macroeconomic anchors.
Historical reference periods anchored growth rate derivation across the analysis window, with segmentation modeling spanning rigid versus flexible formats, petrochemical versus bio-based materials, food contact versus industrial applications, and dimensional tiers from single-serve to bulk industrial. CAGRs emerged from curve-fitting actual shipment volumes against macro drivers including e-commerce penetration indices and regulatory enforcement timelines. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation compliance cost assumptions and biodegradable material innovation diffusion rates.
Several conditions sit outside the modeled scope, including sudden trade policy shifts affecting China export flows, unanticipated feedstock price spikes from geopolitical supply disruptions, and composting infrastructure buildout delays that would strand biodegradable container value propositions. Forecasts reflect documented assumptions about regulatory enforcement pacing and technology cost curves. Practitioners should monitor EU ECHA substance restriction announcements and state-level U.S. plastic ban enactments for early signals of demand geography shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Baffle Bags Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market