
 Indonesia Plastic Caps and Closures Market | 2026-2036
Indonesia Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastic Caps and Closures Market Insights
Indonesia's plastic packaging belt is consolidating as domestic converters expand extrusion and injection molding capacity to serve ASEAN beverage brands. PT Hasil Raya Industries leverages integrated blow molding and cap production lines to anchor supply contracts with local soft drink bottlers. PT Indo Tirta Abadi sustains its position through specialized tamper-evident closure formats for mineral water. Pact Group Holdings Limited competes by extending regional technical support from its Southeast Asian hub.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polypropylene or polyethylene, designed to seal container openings against leakage, contamination, and tampering while enabling controlled dispensing. Polypropylene dominates material selection due to its chemical resistance and hinge flexibility in flip-top designs. Screw caps occupy the largest volume share across Indonesia's bottled water and cooking oil sectors, while tamper-evident variants capture expanding share in pharmaceutical and personal care applications where safety verification commands premium positioning.
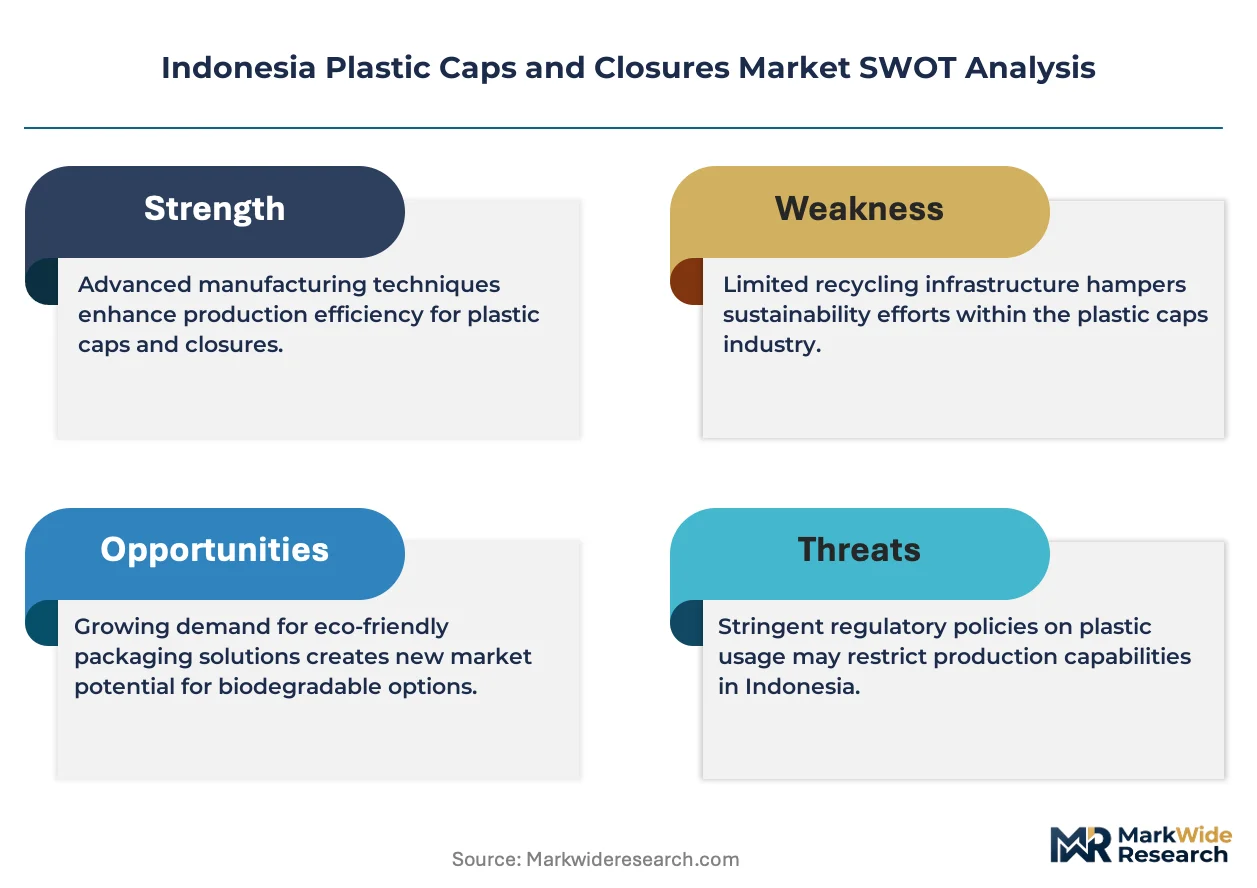
BIS-equivalent Indonesian National Standards and the Ministry of Environment and Forestry's extended producer responsibility framework shape product specifications and recyclability mandates for plastic closures entering domestic circulation. The National Agency of Drug and Food Control enforces child-resistant and anti-dispersal standards for pharmaceutical and household chemical packaging. Stakeholders must monitor regulatory tightening on single-use plastics and assess bio-based material substitutions before compliance deadlines crystallize.
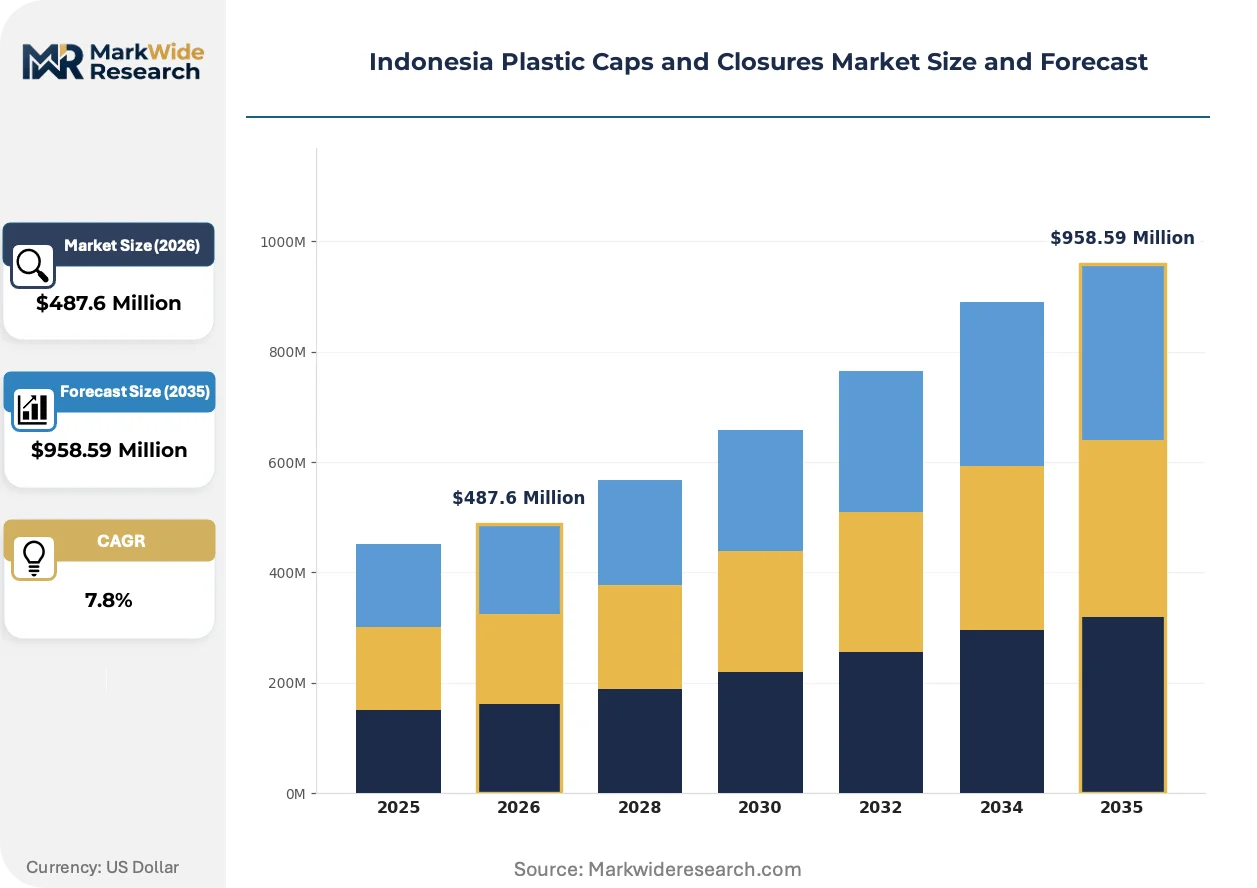
Market Dynamics
Indonesia's Ministry of Environment and Forestry is tightening extended producer responsibility enforcement, forcing converters to redesign closures for mono-material recyclability while maintaining barrier performance. This regulatory compression is accelerating capital redeployment toward compatible tooling and material formulations.
Growth Catalysts
- Extended Producer Responsibility Mandates:The Ministry of Environment and Forestry's EPR framework compels brand owners to source recyclable closures, creating pull-through demand for polypropylene-heavy designs that simplify post-consumer sorting.
- Java Beverage Belt Expansion:Bottled water and ready-to-drink tea production clusters in Greater Jakarta and Surabaya require tamper-evident screw caps at scale, anchoring injection molding capacity additions.
- Child-Resistant Standard Adoption:The National Agency of Drug and Food Control's push for pharmaceutical packaging safety is expanding addressable demand for specialized closure formats in over-the-counter and prescription segments.
Market Restraints
- Propylene Feedstock Volatility:Domestic polypropylene supply depends on naphtha-cracker economics tied to regional LNG pricing, exposing converters to margin compression without pass-through mechanisms.
- Import Dependency for High-Speed Tooling:Precision hot-runner molds and compression molding equipment concentrate with German and Austrian suppliers, creating capex bottlenecks and extended lead times for capacity expansion.
- Mechanical Recycling Contamination:Multi-component closures with linerless induction seals complicate Indonesia's nascent mechanical recycling infrastructure, limiting post-consumer resin availability for circular feedstock claims.
Strategic Opportunities
- Sumatra and Sulawesi Underpenetration:Bottled water consumption per capita in Medan and Makassar lags Java by significant margins, offering whitespace for regional distribution partnerships with emerging local bottlers.
- Bio-Based Polypropylene Pilots:The Ministry of Environment and Forestry's roadmap for bio-content verification creates early-mover positioning for converters sourcing certified renewable feedstocks from Southeast Asian agricultural waste streams.
- E-Commerce Bulk Format Adoption:Direct-to-consumer cooking oil and condiment shipments through Tokopedia and Shopee favor larger closure formats with enhanced seal integrity, opening specialized tooling demand.
Industry Challenges
- Hot-Runner Maintenance Skill Scarcity:Indonesia's technical vocational pipeline produces insufficient mold technicians capable of diagnosing valve-gate timing issues in high-cavitation tools, forcing reliance on foreign service contracts.
- Food-Contact Certification Timelines:National Agency of Drug and Food Control migration testing protocols for new polypropylene grades extend validation cycles, delaying product launches and locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastic Caps and Closures Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $958.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Screw Caps, Sport Caps, Tamper Evident Caps Material: Polyethylene, Polypropylene, PET, PVC End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Closure Design: Standard Closure, Custom Closure, Child-resistant Closure, Anti-dispersal Closure |
| Companies Covered | PT Hasil Raya Industries, PT Indo Tirta Abadi, Pact Group Holdings Limited, Aptar Group Inc., Weener Plastics Group BV, Amcor Group GmbH, Albea Services SAS, PT Solusi Prima Packaging, PT Hokkan Deltapack Industri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastic Caps and Closures Market Trends and Innovations
Digital manufacturing integration and material science advances are compressing development cycles for closure systems. Converters now balance speed-to-market against recyclability mandates that reshape design constraints.
Compression molding technology is converging with in-mold labeling systems to produce decorated closures in single-cycle operations. Mid-tier beverage bottlers in Bandung and Semarang are adopting these hybrid lines to eliminate secondary printing stages. The convergence is collapsing total production cost structures for premium-positioned water brands seeking differentiated shelf presence.
The Ministry of Environment and Forestry's draft regulation on single-use plastic reduction is mandating minimum recycled content thresholds for non-food contact closures by the mid-2030s. Industrial chemical and automotive fluid packaging segments face immediate compliance pressure. Converters are qualifying post-industrial polypropylene regrind streams to secure certification ahead of enforcement windows.
Direct procurement relationships between brand owners and specialized closure converters are displacing traditional distributor intermediaries in Greater Jakarta. Large mineral water producers now negotiate volume commitments with molders possessing captive resin compounding capabilities. This channel consolidation is most pronounced among multinational bottlers operating integrated supply chains across Java's northern corridor.
Indonesia Plastic Caps and Closures Market Segmentation
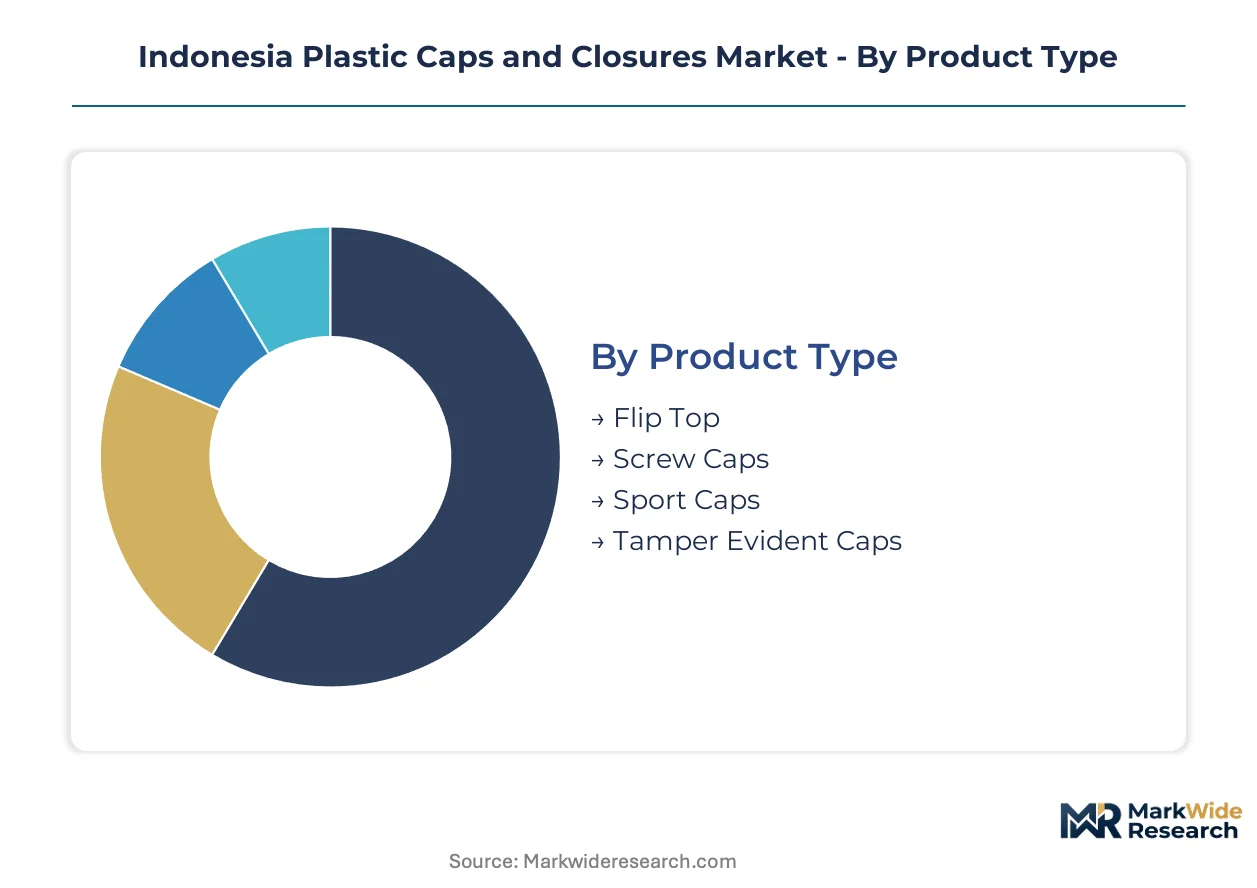
Indonesia's plastic caps and closures market fragments across functional specifications, material chemistry, and regulatory compliance tiers. Converters must align tooling investments with precise end-use requirements spanning Java's beverage belt and emerging regional markets.
Product Type:
Closure mechanisms differentiate by dispensing control, tamper evidence, and user ergonomics.
- Screw Caps:Helical-thread thermoplastic closures dominate volume through standardized 28mm and 38mm neck finishes. Mineral water bottlers in Greater Jakarta and Surabaya specify these for high-speed capping lines. Polypropylene homopolymer grades withstand repeated torque cycles without thread deformation.
- Tamper Evident Caps:Break-band or shrink-sleeve integrated designs provide visual integrity verification. The National Agency of Drug and Food Control mandates these for pharmaceutical and sensitive food applications. Demand concentrates in Bandung's pharmaceutical packaging cluster.
- Flip Top:Living-hinge polypropylene constructions enable single-hand dispensing for personal care and condiment applications. Hinge fatigue resistance determines specification acceptance.
- Sport Caps:Push-pull or squeeze-valve mechanisms target active-consumption scenarios. Bottled isotonic drink producers specify these for differentiated positioning.
Screw Caps lead on scale; Tamper Evident Caps lead on momentum.
Material:
Resin selection balances chemical resistance, processability, and recyclability compliance under Ministry of Environment and Forestry directives.
- Polypropylene:Isotactic homopolymer and random copolymer grades dominate through chemical inertness and hinge flexibility. Injection molding converters across Tangerang and Bekasi prefer melt-flow indices between 20-35 g/10min for thin-wall cap production. Extended producer responsibility rules favor mono-material PP designs for mechanical recycling compatibility.
- Polyethylene:HDPE and LDPE variants serve compression-molded large-format closures for industrial chemical containers. Lower stiffness versus PP limits thread precision in small-diameter applications.
- PET:Crystalline polyester closures appear in specialty carbonated beverage applications requiring CO2 barrier performance. Higher material cost restricts penetration.
- PVC:Rigid vinyl formulations persist in limited household chemical segments despite recyclability concerns and regulatory pressure.
Polypropylene leads on scale; Polyethylene leads on momentum in industrial bulk formats.
End User:
Application sectors impose divergent performance standards and certification requirements.
- Food & Beverage:Bottled water, cooking oil, and ready-to-drink tea producers generate base demand. Java's northern manufacturing corridor houses concentrated filling capacity requiring tamper-evident and standard screw formats.
- Pharmaceuticals:Over-the-counter and prescription packaging demands child-resistant and anti-dispersal closure compliance. National Agency of Drug and Food Control migration testing extends qualification timelines.
- Personal Care:Shampoo and conditioner brands specify flip-top and disc-top dispensers. Aesthetic differentiation drives custom color compounding requirements.
- Household Products:Bleach, detergent, and surface cleaner packaging prioritizes chemical resistance and venting features for pressure equalization.
Food & Beverage leads on scale; Pharmaceuticals leads on momentum.
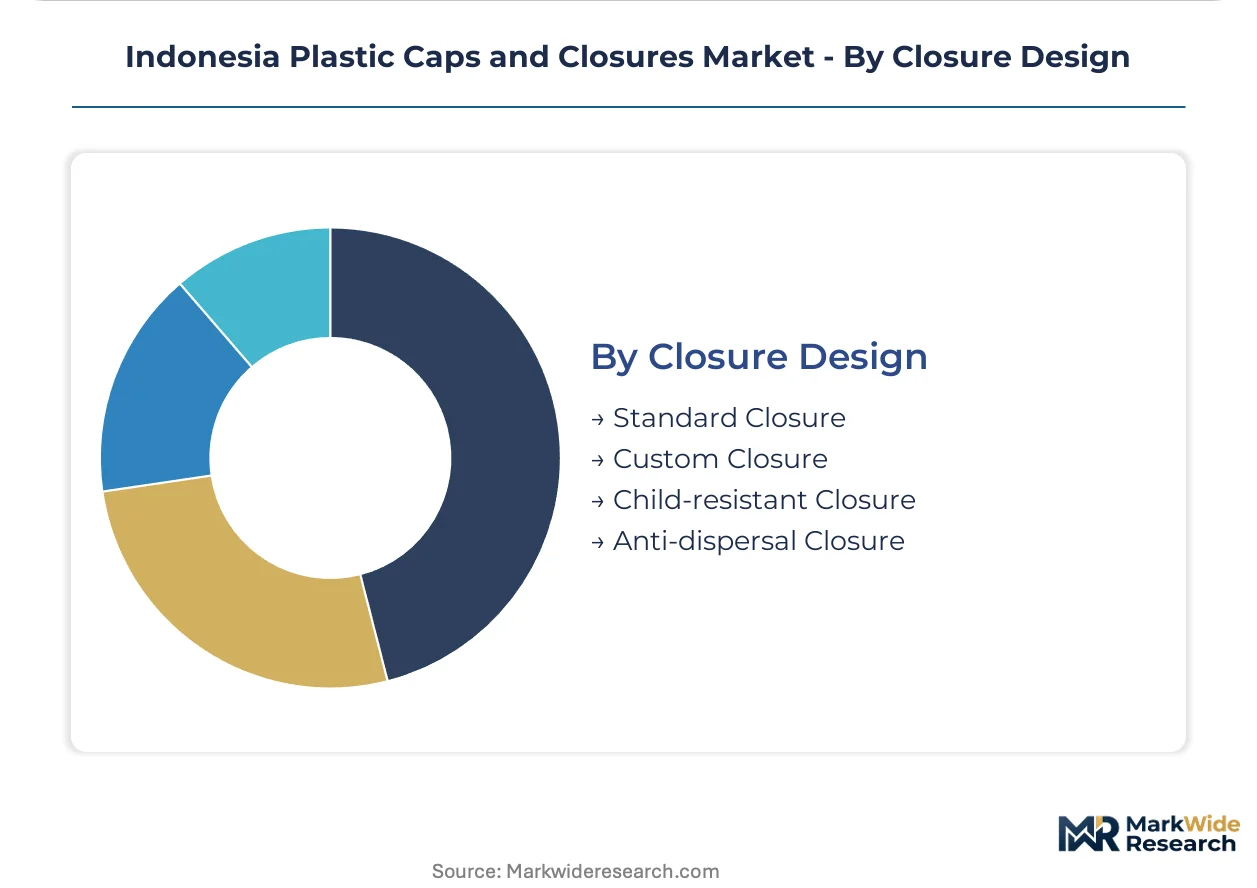
Closure Design:
Design complexity stratifies by safety regulation intensity and brand differentiation requirements.
- Standard Closure:Generic thread profiles and smooth skirt designs serve cost-sensitive commodity segments. High-volume mineral water producers in Greater Jakarta negotiate these on resin-plus-conversion pricing.
- Child-resistant Closure:Push-and-turn or squeeze-and-turn mechanisms require dual-action dexterity. Pharmaceutical and household chemical regulations mandate these for toxic substance containment.
- Custom Closure:Proprietary thread systems, embossed branding, and specialized dispensing orifices support premium positioning. Regional beverage brands in Semarang and Malang adopt these for shelf differentiation.
- Anti-dispersal Closure:Flow restrictors and orifice reducers limit accidental ingestion or spillage. Pediatric liquid medicine packaging specifies these under National Agency of Drug and Food Control guidance.
Standard Closure leads on scale; Child-resistant Closure leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing plastic closure production across Southeast Asia as Indonesia's extended producer responsibility rules tighten faster than regional peers, drawing investment toward compliant manufacturing zones while pushing non-compliant capacity toward neighboring jurisdictions with lagging enforcement timelines.
Java
Greater Jakarta and Surabaya host Indonesia's densest beverage bottling corridors, consuming tamper-evident screw caps at scale for mineral water and ready-to-drink tea. The Ministry of Environment and Forestry's EPR enforcement concentrates here first, forcing Tangerang and Bekasi converters to retool for mono-material recyclability. Bandung's pharmaceutical packaging cluster demands child-resistant closure formats under National Agency of Drug and Food Control mandates.
Sumatra
Medan's bottled water consumption per capita trails Java by substantial margins, creating whitespace for regional distribution partnerships with emerging local bottlers. The island's palm oil-derived bio-feedstock streams attract pilot programs for renewable polypropylene sourcing. Batam's free trade zone positioning enables duty-advantaged resin importation for converters serving cross-border ASEAN customers.
Sulawesi
Makassar anchors underpenetrated demand for packaged beverages across eastern Indonesia's archipelago geography. Logistics costs from Java dominate landed closure pricing, incentivizing local molding capacity investment. The city's emerging industrial estates offer tax holidays for packaging material producers meeting Ministry of Environment and Forestry sustainability criteria.
Kalimantan
Balikpapan and Samarinda serve mining and energy sector chemical packaging needs with industrial-format HDPE closures for lubricants and solvents. The region's nascent mechanical recycling infrastructure struggles with multi-component closure contamination. Provincial environmental agencies are drafting localized EPR implementation rules ahead of national deadlines.
Indonesia Plastic Caps and Closures Market Competitive Landscape
Indonesian domestic producers anchor the mid-market tier; Australian and European specialists hold premium positioning through technical closure formats. The vendor base stratifies across three layers: integrated resin-to-closure converters with captive compounding, specialized tamper-evident and child-resistant format molders, and commodity screw cap suppliers competing on resin-plus-conversion pricing. Consolidation pressure is accelerating through direct procurement relationships displacing distributor intermediaries, alongside capacity expansion in Greater Jakarta's northern corridor.
Among domestic integrated producers, PT Hasil Raya Industries and PT Indo Tirta Abadi exemplify the converter archetype combining blow molding and cap production lines to anchor supply contracts with local bottlers. Pact Group Holdings Limited represents the regional multinational model, extending technical support from its Southeast Asian hub to capture premium-format demand. These three occupy positions spanning the cost-engineered to specification-grade spectrum, with domestic players consolidating around Java beverage belt density and foreign-owned specialists targeting pharmaceutical and personal care compliance tiers.
| Leading Market Players |
|---|
| PT Hasil Raya Industries |
| PT Indo Tirta Abadi |
| Pact Group Holdings Limited |
| Aptar Group Inc. |
| Weener Plastics Group BV |
| Amcor Group GmbH |
| Albea Services SAS |
| PT Solusi Prima Packaging |
| PT Hokkan Deltapack Industri |
| Others |
Pricing and Supply Chain Analysis
Brand-owner direct procurement mandates from Danone-Aqua and Coca-Cola bottlers across Java's northern corridor are collapsing traditional distributor markups and forcing converters to absorb logistics costs while maintaining resin-plus-conversion pricing discipline. This channel compression is accelerating margin bifurcation between integrated producers with captive compounding and commodity molders competing on spot polypropylene pricing.
Pricing Analysis
Distributor margin compression now runs through Greater Jakarta's beverage packaging corridor as multinational bottlers negotiate volume commitments directly with Tangerang and Bekasi converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with pharmaceutical-grade child-resistant formats commanding substantial premiums over mineral water screw caps. Pricing pressure stems from propylene feedstock volatility tied to regional LNG pricing without full pass-through mechanisms. Commodity screw cap buyers in bottled water show highest price sensitivity; pharmaceutical and personal care segments demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Post-consumer closure collection and mechanical recycling flows remain underdeveloped across Indonesia, limiting circular feedstock availability for converters qualifying recycled content claims under Ministry of Environment and Forestry guidelines. Manufacturing concentration centers on China, Germany, and Austria for precision hot-runner molds and compression molding equipment, while domestic polypropylene compounding draws from Singapore and Thailand resin supply. Single-source vulnerability concentrates in high-cavitation tooling where German and Austrian suppliers control lead times. Distribution runs through Java's northern manufacturing corridor with emerging hub development in Surabaya and Bandung.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plastic caps and closures market functions as a stable compounder anchored by non-discretionary beverage consumption growth and regulatory-driven specification upgrades that resist cyclical compression.
For Market Incumbents: Acquire specialized tamper-evident and child-resistant tooling capabilities to defend against multinational specialists capturing pharmaceutical compliance premiums. PT Hasil Raya Industries and PT Indo Tirta Abadi should deepen backward integration into polypropylene compounding to offset feedstock volatility exposure while securing Ministry of Environment and Forestry recyclability certifications ahead of enforcement windows. For New Entrants and Emerging Players: Compression molding technology with integrated in-mold labeling offers entry wedge against established injection molders serving mid-tier beverage brands in Semarang and Malang. Target Sumatra and Sulawesi bottled water bottlers with regional distribution partnerships; these geographies show substantial per-capita consumption gaps versus Java. Pursue bio-based polypropylene pilot programs leveraging Sumatra's palm oil waste streams to differentiate on sustainability credentials. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized converters possessing pharmaceutical-grade certification infrastructure and captive resin compounding capabilities. Long-term viability over the five-to-ten year window favors integrated producers with demonstrated compliance navigation under National Agency of Drug and Food Control protocols. Monitor Ministry of Environment and Forestry EPR enforcement timelines and recycled content mandate announcements as inflection indicators for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | Captive resin supply insulates margin compression from naphtha-cracker volatility and LNG pricing swings. |
| Pharmaceutical Certification Investment | National Agency of Drug and Food Control child-resistant approval unlocks premium positioning in OTC and prescription segments. |
| Regional Distribution Partnership in Sumatra and Sulawesi | Medan and Makassar bottled water consumption gaps offer whitespace expansion beyond Java's saturated corridor. |
| Bio-Based Polypropylene Pilot Program | Ministry of Environment and Forestry bio-content verification creates early-mover positioning for renewable feedstock claims. |
| Direct Procurement Relationship with Multinational Bottlers | Danone-Aqua and Coca-Cola volume commitments displace distributor intermediaries and secure capacity utilization. |
Research Methodology
Bottom-up beverage and pharmaceutical packaging modeling reconciled against top-down resin consumption and import tracking forms the analytical core of this study. Primary interviews with injection molding plant managers, procurement leads at bottled water bottlers, pharmaceutical packaging engineers, and Ministry of Environment and Forestry compliance officers combined with secondary validation from Indonesian customs records, BIS-equivalent National Standards documentation, National Agency of Drug and Food Control regulatory filings, and ASEAN plastics trade association data. Triangulation across supply-side capacity audits and demand-side procurement surveys ensures cross-verification of volume estimates.
Historical trendline analysis of closure production volumes, resin pricing indices, and regulatory implementation timelines established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, material chemistry, end-use sector, and closure design complexity dimensions with regional disaggregation across Java, Sumatra, Sulawesi, and Kalimantan. CAGRs derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules, with specific inputs including bottled water consumption per capita trajectories and EPR compliance cost pass-through assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ministry of Environment and Forestry regulatory tightening timelines and mechanical recycling infrastructure development pace. Forecasts reflect documented assumptions regarding propylene feedstock pricing stability and multinational bottler procurement consolidation continuity. Practitioners should monitor National Agency of Drug and Food Control certification backlog durations and provincial EPR implementation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Foam End Caps Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Benelux Plastic Caps and Closures Market