
 Heat Shrink Bands Market | 2026-2036
Heat Shrink Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Bands Market Foresight
Medical-grade specification upgrades across pharmaceutical and healthcare packaging is unwinding premiumization across the value chain. TE Connectivity leverages its materials science depth to sustain high-purity product lines for sterile environments. 3M anchors North American supply through vertically integrated polymer compounding and converting operations. Panduit competes on channel density, controlling distribution access across industrial maintenance sectors.
Heat shrink bands are thermoplastic sleeves, typically manufactured from polyolefin, PVC, or PET substrates, that contract radially when exposed to controlled heat to form a tight mechanical bond over containers, caps, or cable assemblies. The primary commercial purpose centers on tamper evidence, environmental sealing, and unit identification across consumer and industrial goods. Polyolefin formulations lead volume due to balanced shrink ratios and chemical resistance, while PET variants capture margin pools in high-temperature electronics protection. End-user demand concentrates in food and beverage packaging where regulatory-driven tamper-evidence requirements sustain replacement cycles, with healthcare applications representing the fastest-expanding segment as biologics packaging intensifies barrier performance needs.
FDA serialization rules and EPA material safety standards govern substrate selection and migration limits in US-bound pharmaceutical and food applications, while REACH compliance in Europe restricts certain plasticizer chemistries in PVC-based bands. ISO 9001 and medical-device quality system registrations shape supplier qualification thresholds, filtering market access for non-specialized manufacturers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and substrate-specific recycling mandates that threaten to fragment material specifications across regional supply chains.
Market Dynamics
FDA serialization mandates for pharmaceutical traceability are compressing closure integrity standards across North American packaging lines, forcing substrate upgrades and supplier consolidation in the heat shrink band value chain.
Growth Catalysts
- Drug Traceability Mandates:FDA serialization rules for pharmaceutical packaging are tightening tamper-evidence requirements, accelerating specification upgrades across sterile fill-finish operations.
- Biologics Packaging Intensification:Cell and gene therapy cold-chain demands are driving barrier performance needs that conventional seals cannot satisfy.
- Midwest Manufacturing Corridor Concentration:United States pharmaceutical packaging lines cluster in Illinois, Indiana, and Ohio, creating dense demand nodes for regional converters.
Market Restraints
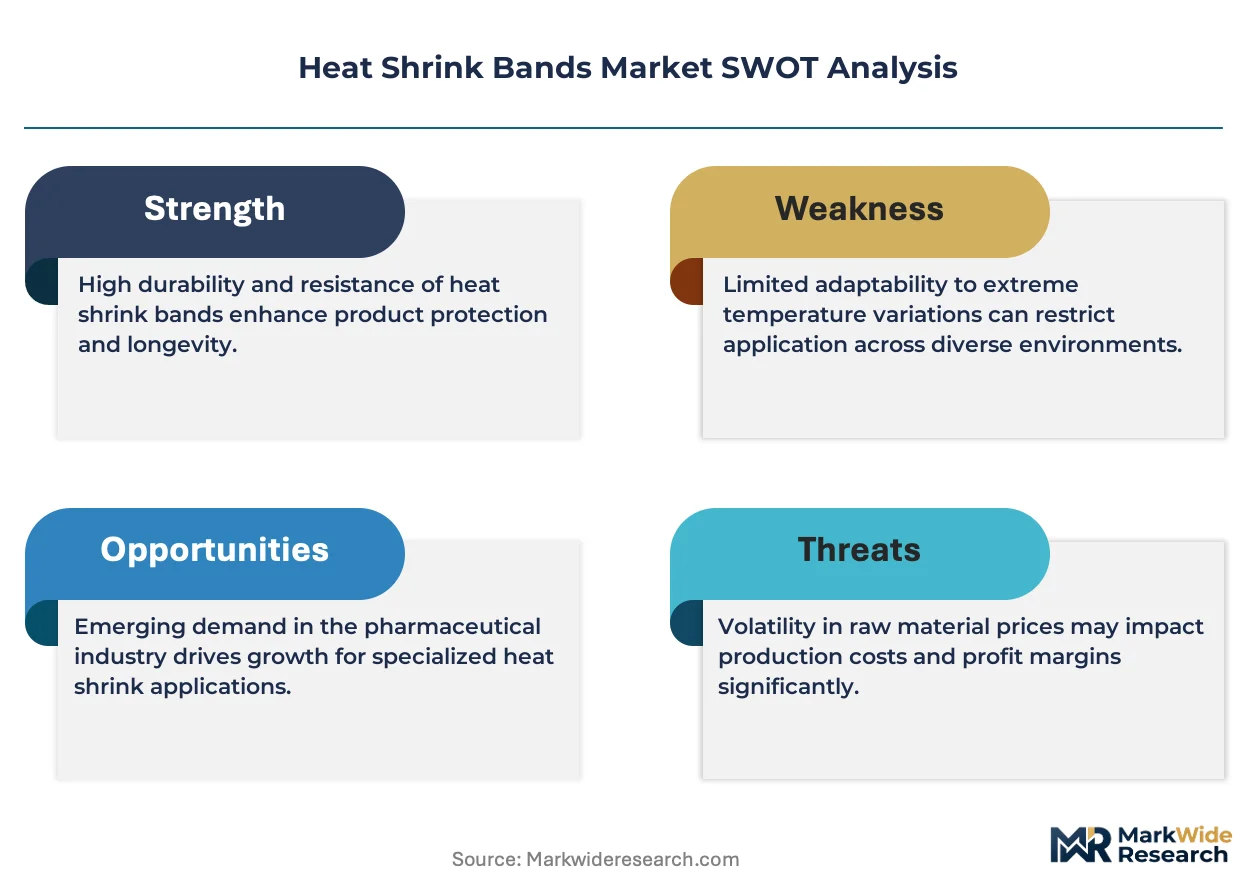
- Petrochemical Feedstock Volatility:Polyolefin resin prices fluctuate with ethylene and propylene spot markets, compressing converter margins during upstream spikes.
- Specialized Compounder Concentration:Medical-grade polymer supply concentrates among a handful of North American compounders, creating single-source vulnerability for sterile-grade bands.
- PVC Substitution Pressure:REACH restrictions on phthalate plasticizers in Europe are fragmenting material specifications, forcing dual-sku inventory strategies.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:State-level packaging recycling mandates in California and New York are creating first-mover advantage for mono-material PET band formulations.
- Radio-Frequency Identification Convergence:Integration of printed electronics with shrink sleeve substrates enables unit-level authentication without secondary labels.
- Specialty Pharmacy Distribution Channels:Direct-to-patient biologics delivery models in the United States are opening specification windows for temperature-indicating tamper seals.
Industry Challenges
- Medical-Device Quality System Certification Timelines:ISO 13485 registration processes stretch 12-18 months, filtering market access for non-specialized converters.
- Legacy Serialization Infrastructure Integration:Pharmaceutical packagers face friction retrofitting existing lines for aggregation-compatible band application systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Bands Market |
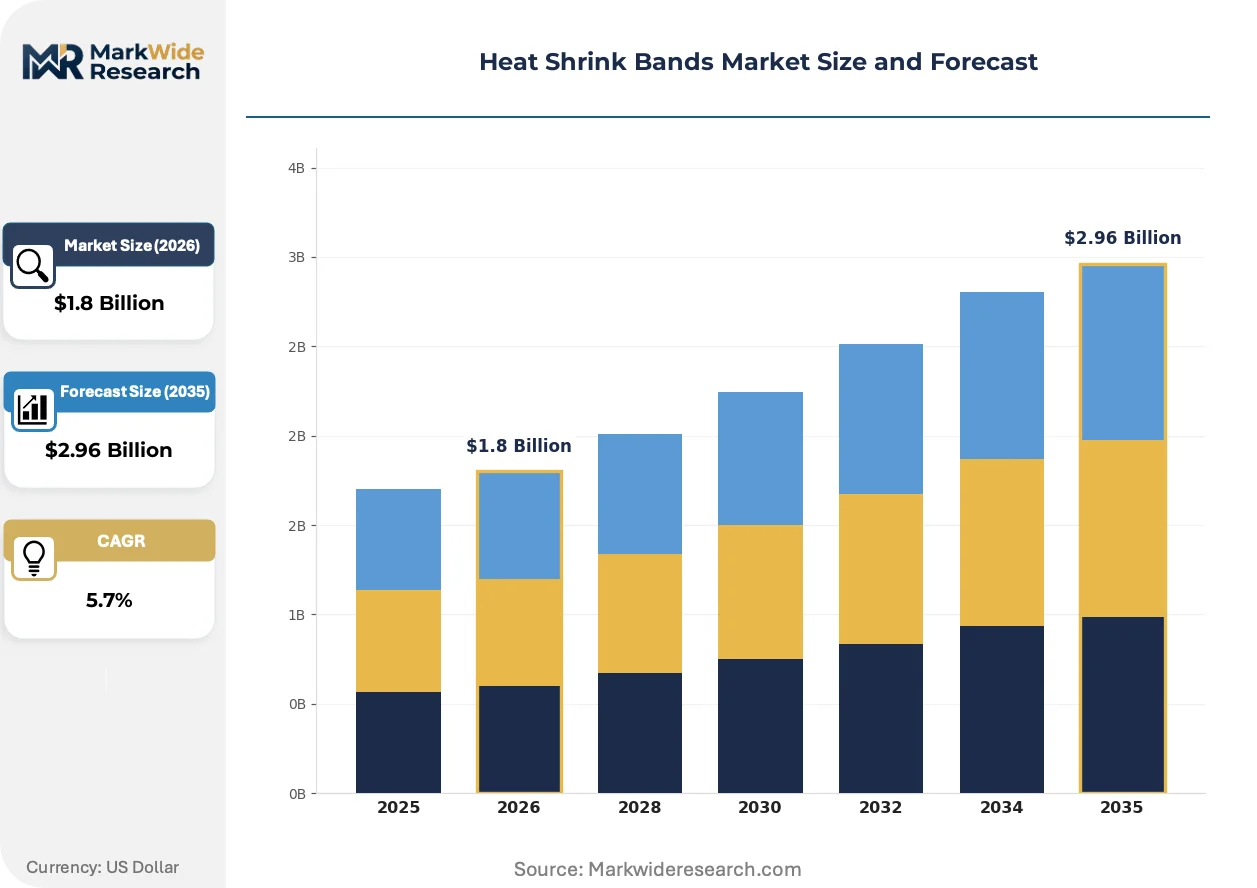
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PET, Nylon End User: Food & Beverage, Cosmetics, Healthcare, Electronics Application: Packaging, Labeling, Bundling, Protection Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | TE Connectivity, 3M, Sumitomo Electric Industries, ABB, HellermannTyton, Alpha Wire, Panduit, Qualtek, Zeus Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Bands Market Shifts & Advancements
Active material science development is compressing substrate thickness while maintaining barrier performance, reshaping competitive differentiation around purity certification and application speed rather than commodity resin supply.
Laser-perforated micro-venting technology is miniaturizing breathable seal structures for lyophilized biologics. Sterile injectable manufacturers in Massachusetts and North Carolina are piloting these formats at commercial scale. The technology is miniaturizing the functional boundary between primary container closure and secondary tamper evidence, collapsing former multi-component assemblies into single-sleeve solutions.
EPA material safety standards for food-contact substances are tightening migration testing protocols for polyolefin substrates. Converter qualification cycles are lengthening as packagers demand expanded extraction studies. Infant formula and nutritional supplement categories in the United States face the steepest compliance ramps, with several brands accelerating supplier audits ahead of anticipated rule finalization.
Consolidated buying desks at multinational pharmaceutical packagers are compressing supplier rosters and unbundling technical service from material supply. Regional converters in the Midwest report contract structures shifting toward performance-guarantee frameworks with penalty clauses for lot-failure rates. This pattern concentrates most visibly among top-ten sterile fill-finish operators, where procurement teams now mandate dedicated quality engineers at converter facilities.
Heat Shrink Bands Market Segmentation
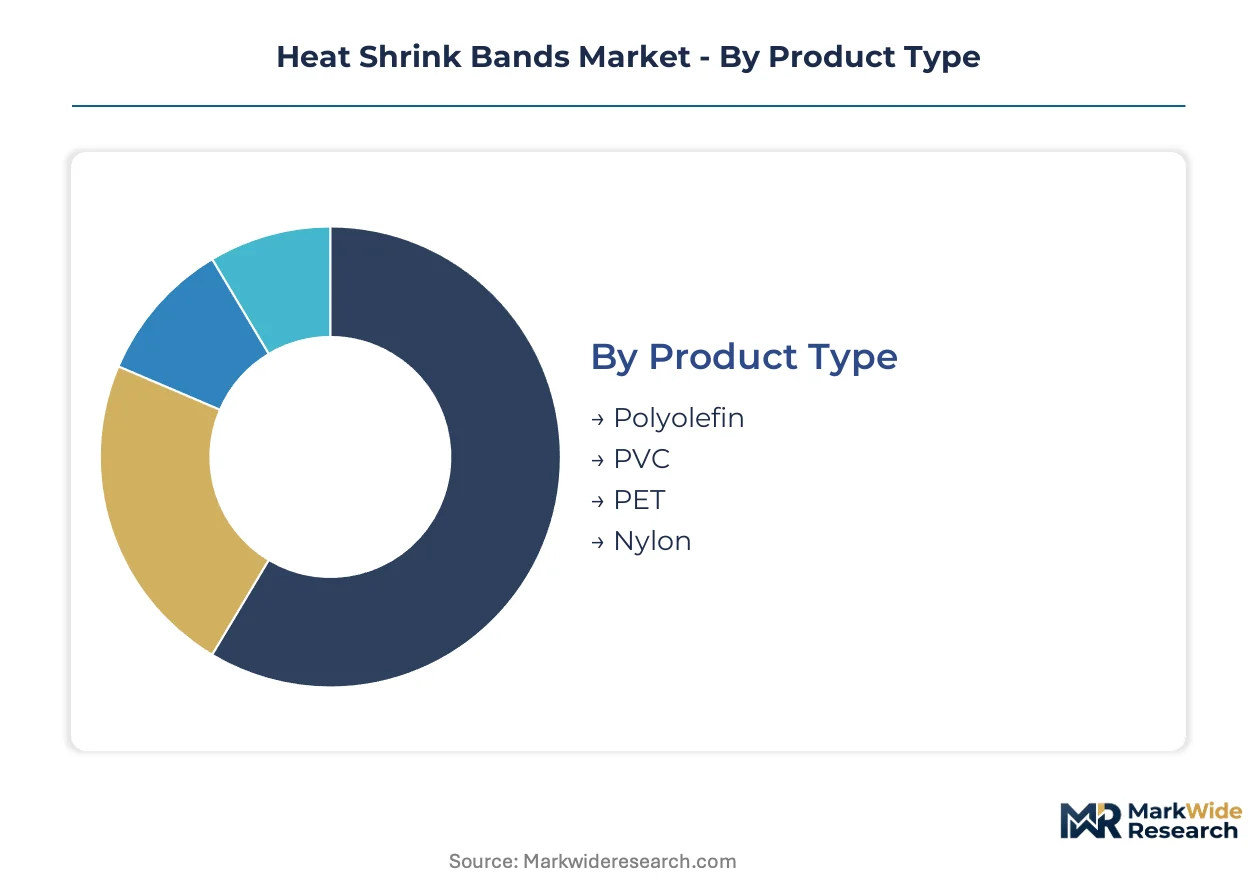
Heat shrink band purchasing decisions split across material chemistry, regulatory exposure, and application mechanics. Procurement teams at pharmaceutical packagers weight substrate purity against line speed compatibility. Food manufacturers prioritize migration compliance and optical clarity for retail shelf presence.
Product Type:
Substitution pressure from regulatory bans on plasticizer chemistries is fragmenting PVC demand toward polyolefin and PET alternatives, with compounders reformulating to retain medical-grade certification windows.
- Polyolefin:Cross-linked polyethylene and polypropylene formulations deliver balanced shrink ratios between 40% and 70% with broad chemical resistance. FDA food-contact approvals and low-temperature flexibility sustain dominance across Midwest pharmaceutical packaging corridors where sterile fill-finish lines require consistent seal integrity.
- PVC:Plasticized vinyl substrates offer cost-efficient tamper evidence for beverage and household chemical applications. REACH restrictions on phthalate plasticizers in European markets are forcing dual-sku inventory strategies and accelerated reformulation timelines among legacy converters.
- PET:Polyester variants tolerate sustained temperatures above 150°C for electronics protection and high-heat sterilization cycles. Mono-material recyclability aligns with California and New York extended producer responsibility mandates.
- Nylon:Polyamide substrates provide abrasion resistance and oil compatibility for industrial cable bundling and under-hood automotive harnesses. Limited heat shrink ratios constrain adoption in contour-following container applications.
Polyolefin retains volume leadership across pharmaceutical and food packaging; PET holds the steepest expansion curve driven by electronics thermal protection and recycling compliance tailwinds.
End User:
Customer procurement sophistication varies sharply across end-use sectors, with healthcare buyers mandating ISO 13485-certified supply chains while cosmetics brands prioritize optical differentiation.
- Food & Beverage:Tamper-evident sealing for dairy, juice, and condiment containers sustains replacement cycles driven by FDA food defense regulations. High-volume bottling lines in Illinois and Ohio demand consistent shrink initiation temperatures for thermal efficiency.
- Healthcare:Sterile injectable and biologics packaging commands the most stringent barrier performance specifications. Cell and gene therapy cold-chain requirements are collapsing multi-component closures into single-sleeve solutions with integrated breach detection.
- Cosmetics:Premium fragrance and skincare brands leverage shrink sleeves for 360-degree decorative labeling with metallic and holographic finishes. SKU proliferation pressures converters toward shorter run lengths and faster changeover capabilities.
- Electronics:Cable assemblies and battery packs require flame-retardant formulations with precise dielectric properties. Electric vehicle wiring harness growth in Michigan and Tennessee is concentrating demand for medium-wall nylon and polyolefin tubing.
Food and beverage sustains absolute volume; healthcare commands the steepest expansion curve as biologics packaging intensifies barrier requirements.
Application:
Mechanical function determines substrate selection and thickness specification, with packaging applications demanding optical clarity and bundling operations prioritizing tensile strength.
- Packaging:Container closure sealing for pharmaceuticals, food, and cosmetics represents the core revenue pool. Tamper-evidence regulations across FDA and state-level frameworks sustain replacement demand regardless of macroeconomic cycles.
- Labeling:Full-body shrink sleeves enable 360-degree brand communication with contour-following graphics. Digital printing adoption is shortening design-to-market timelines for seasonal and promotional campaigns.
- Bundling:Multi-pack collation for beverage cases and industrial product grouping requires high-tensile formulations. Warehouse automation demands consistent band placement for robotic handling compatibility.
- Protection:Environmental sealing for electronics, automotive, and marine applications prioritizes moisture and chemical ingress resistance. Military and aerospace specifications mandate lot traceability and material certification documentation.
Packaging commands volume leadership; labeling holds the steepest expansion curve as brand owners convert from adhesive labels to sleeve-based decoration.
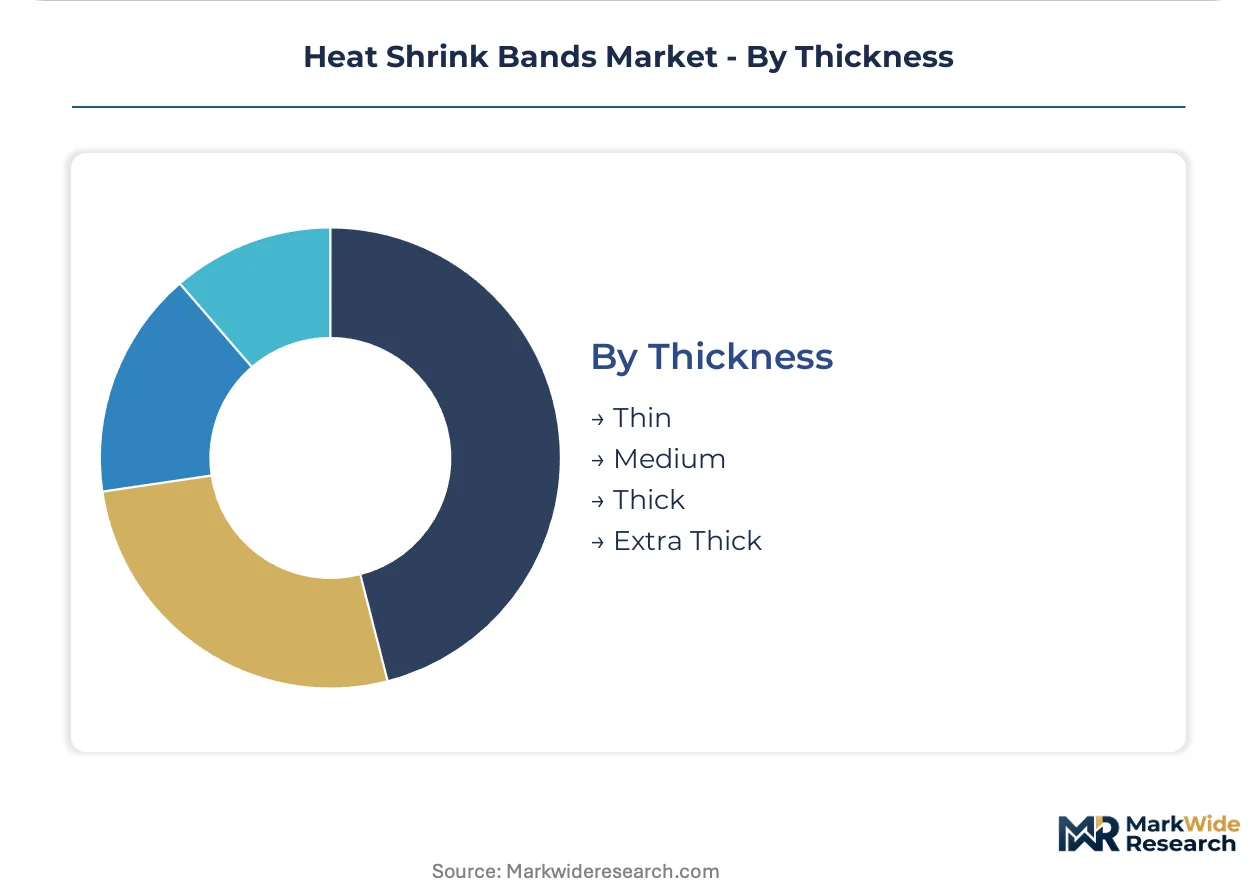
Thickness:
Caliber selection directly correlates with mechanical load requirements and heat application window constraints, with thin films enabling faster line speeds and thick walls ensuring structural rigidity.
- Thin:Sub-50 micron films optimize material yield and heat transfer efficiency for high-speed pharmaceutical and food lines. Massachusetts and North Carolina biologics manufacturers are piloting laser-perforated micro-venting variants for lyophilized products.
- Medium:50-100 micron specifications balance durability and conformability across general-purpose packaging and light industrial bundling. Midwest converters report this caliber capturing the broadest cross-sector demand.
- Thick:100-200 micron walls provide puncture resistance for abrasive contents and heavy-duty cable protection. Industrial maintenance sectors in Indiana and Ohio specify this range for outdoor electrical infrastructure.
- Extra Thick:Above-200 micron formulations serve extreme mechanical and environmental protection for subsea cables, mining equipment, and military applications. Limited volume concentrates among specialty compounders with custom extrusion capabilities.
Medium thickness retains volume leadership across diversified end-use; thin films hold the steepest expansion curve driven by biologics packaging miniaturization and line speed optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in the United States Midwest manufacturing corridor, with Illinois, Indiana, and Ohio hosting the densest clusters of pharmaceutical packaging lines demanding sterile-grade tamper-evident seals.
United States
FDA serialization mandates for drug traceability are tightening closure integrity standards across Massachusetts and North Carolina biologics facilities. EPA material safety standards govern polyolefin substrate selection for food-contact applications. The Midwest corridor spanning Illinois, Indiana, and Ohio anchors North American converter capacity serving sterile fill-finish operations.
Germany
REACH restrictions on phthalate plasticizers are fragmenting PVC-based band specifications toward polyolefin alternatives. ECHA compliance windows are accelerating reformulation timelines among legacy compounders. The Rhine-Ruhr industrial region hosts specialized extrusion capacity serving automotive and electronics bundling applications.
China
SAMR packaging safety standards are tightening substrate migration limits for food and pharmaceutical exports. NMPA traceability requirements for domestic drug distribution are elevating tamper-evidence specifications. The Yangtze River Delta manufacturing belt concentrates converter capacity serving export-oriented electronics protection demand.
Japan
METI circular economy guidelines are driving mono-material PET adoption for recyclability compliance. PMDA pharmaceutical packaging regulations mandate lot-level traceability integration with closure systems. The Kanto region around Tokyo hosts precision extrusion specialists serving medical-device and electronics OEMs.
India
CDSCO serialization mandates for pharmaceutical exports are accelerating specification upgrades among domestic converters. BIS material standards for food-contact applications are tightening testing protocols for polyolefin substrates. The Maharashtra-Gujarat industrial corridor is expanding compounding capacity to serve regional pharmaceutical packaging growth.
Heat Shrink Bands Market Competitive Landscape
Concentration sits with diversified materials science conglomerates and specialized cable management fabricators. The vendor base splits between vertically integrated polymer compounders controlling resin supply and regional converters competing on application speed. Two archetypes dominate: multinational industrial conglomerates with captive polymer operations, and mid-scale specialists with ISO 13485-certified sterile production lines. Competitive moves center on backward integration into medical-grade compounding and strategic partnerships with pharmaceutical packaging OEMs for line-integration services.
Among diversified industrial conglomerates, TE Connectivity and 3M exemplify the materials-science-deep archetype with captive polymer operations. Sumitomo Electric Industries represents the Asia-Pacific industrial conglomerate model with integrated cable and protection systems. Panduit occupies a position within the specialized cable management tier competing on channel density across industrial maintenance sectors.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M |
| Sumitomo Electric Industries |
| ABB |
| HellermannTyton |
| Alpha Wire |
| Panduit |
| Qualtek |
| Zeus Industrial Products |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles at Midwest pharmaceutical packagers concentrate purchasing leverage among sterile-grade compounders while compressing margin buffers for regional converters serving spot-market buyers. This lead-time asymmetry between contracted healthcare supply and industrial spot demand anchors pricing power with ISO 13485-certified manufacturers.
Pricing Analysis
FDA serialization mandates dictate the pricing tier structure across pharmaceutical-grade heat shrink bands. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical supply from FDA food-contact grades and uncertified industrial commodity bands. Price differentiation centers on certification level and volume scale, with sterile fill-finish operators least price-sensitive due to lot-failure penalty clauses. Cost compression in industrial-grade polyolefin is intensifying because resin spot volatility transfers directly to converter margins.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical procurement, with sterile-grade buyers maintaining 60-90 day safety stocks against single-source compounder vulnerability. Raw material supply concentrates in the United States, Germany, and China, with ethylene and propylene feedstock drawing from Gulf Coast petrochemical complexes. Medical-grade polymer supply rests on specialized North American compounders, creating single-source risk for biologics packaging lines. Distribution runs through regional converter networks anchored in the Midwest manufacturing corridor, with direct mill relationships for high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat shrink band incumbents face substitution pressure from integrated sleeve-label hybrids that collapse tamper-evidence and decoration into single-pass application, threatening standalone band volumes in cosmetics and beverage segments.
For Market Incumbents: Consolidate backward integration into medical-grade polymer compounding to secure sterile supply chains against single-source vulnerability. Lock exclusive line-integration partnerships with top-ten sterile fill-finish operators in Illinois and Indiana, embedding application equipment and dedicated quality engineers at converter facilities to raise switching costs for pharmaceutical procurement teams.
For New Entrants and Emerging Players: Temperature-indicating tamper seal integration for direct-to-patient biologics delivery represents an underserved service layer where incumbents under-serve specialty pharmacy channels. Target the Massachusetts and North Carolina biologics clusters with pilot-scale laser-perforated micro-venting capabilities for lyophilized products, leveraging shorter qualification timelines against entrenched Midwest suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade extrusion capacity as FDA serialization mandates lengthen converter qualification cycles. The viable acquisition window centers on mid-scale ISO 13485-certified specialists with captive polymer relationships and existing pharmaceutical OEM line-integration contracts. Watch for CDSCO serialization mandate acceleration in India as the signal indicating regional supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Compounding | Captive polymer supply secures sterile certification windows against REACH and FDA migration rule tightening. |
| Line-Integration Partnership with Pharmaceutical OEMs | Embedded application equipment and quality engineers raise switching costs for sterile fill-finish procurement teams. |
| Mono-Material PET Formulation Development | California and New York extended producer responsibility mandates create first-mover recyclability compliance advantage. |
| RFID-Enabled Shrink Sleeve Integration | Printed electronics convergence enables unit-level authentication without secondary label application steps. |
| Regional Capacity Expansion in Midwest Corridor | Proximity to Illinois, Indiana, and Ohio pharmaceutical packaging clusters reduces logistics lead times. |
Research Methodology
Desk research of FDA guidance documents, EPA material safety standards, and REACH regulatory filings preceded structured interviews with sterile fill-finish operations managers, pharmaceutical packaging procurement directors, polymer compounding technical leads, and regional converter sales executives. Secondary validation drew from customs trade data, SEC 10-K disclosures of diversified materials conglomerates, and ISO certification registry databases. Bottom-up volume estimates from individual converter capacity and top-down demand segmentation triangulated to produce market sizing across the analysis window.
Variance decomposition across material chemistry, regulatory exposure tier, and application mechanics shaped the analytical framework. Modeled segmentation dimensions included substrate type, end-use sector, thickness caliber, and regional production hub cluster. CAGRs were derived from regression analysis of historical pharmaceutical packaging capital expenditure patterns and biologics cold-chain infrastructure buildout trajectories, with explicit modeling of FDA serialization mandate phase-in effects and EPA rule finalization timelines.
Forecasts assume regulatory continuity in FDA serialization schedules and REACH plasticizer restrictions; material policy shifts would require re-modeling. Specific risks that could revise projections include state-level extended producer responsibility acceleration, ethylene-propylene feedstock price spikes exceeding historical volatility bands, and pharmaceutical packager consolidation compressing supplier rosters faster than modeled. Revision becomes warranted when biologics packaging miniaturization adoption crosses commercial-scale thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Drop Sealers Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
End Cap Market
Caps and Closures
North America Plastic Caps and Closures Market