
 Fixed Length Seals Market | 2026-2036
Fixed Length Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Length Seals Market Foresight
Buyer concentration among petrochemical plants and power generation utilities is shifting toward fewer, larger procurement frameworks that bundle fixed length seals into multi-year maintenance contracts. Tyden Brooks leverages its security-seal heritage to extend credibility into industrial-grade fixed length sealing solutions for critical infrastructure. Mega Fortris specializes in tamper-evident architectures that compete on reliability in aeronautics and oil & gas channels. Essentra anchors European supply through its polymer compounding capabilities and REACH-compliant material formulations.
Fixed length seals are precision-engineered sealing devices manufactured to predetermined dimensions using elastomeric compounds, PTFE, or metal alloys, designed to maintain dimensional stability under thermal cycling and pressure differentials in static or slow-dynamic joint applications. Their primary purpose is preventing fluid or gas leakage in piping systems, pressure vessels, and rotating equipment where custom-cut seals would introduce variability. Rubber and silicone formulations dominate volume in HVAC and water treatment applications where flexibility and chemical resistance offset premium pricing. PTFE and metal segments command margin concentration in aerospace and petrochemical end uses where extreme temperature tolerance and regulatory traceability justify higher unit economics. Mechanical seals and O-rings represent the most mature product categories, while lip seals and valve seals capture accelerated replacement demand in aging power generation infrastructure across North America and Western Europe.
FDA regulations govern silicone and rubber material contact in food processing applications, while EPA emissions standards drive seal specification upgrades in petrochemical and power generation facilities to reduce fugitive leaks. The EU Green Deal's industrial decarbonization targets, enforced through ECHA REACH compliance pathways, are redirecting procurement toward low-VOC fluoropolymer alternatives in European manufacturing plants. Stakeholders must monitor how diverging transatlantic chemical safety frameworks reshape material qualification timelines and supplier certification burdens.
Market Dynamics
Power generation utilities and aerospace OEMs are consolidating procurement into multi-year framework agreements, compressing supplier margins while demanding REACH-compliant material traceability and thermal cycling performance guarantees.
Growth Catalysts
- EU Green Deal industrial decarbonization:ECHA REACH compliance pathways redirect European manufacturing toward low-VOC fluoropolymer seal formulations, expanding addressable demand for qualified suppliers.
- Aging power infrastructure replacement cycles:North American and Western European utilities face accelerated valve seal and lip seal replacement schedules as generation assets exceed design lifespans.
- Precision engineering corridor concentration:Germany's OEM ecosystem sources high-specification seals for aeronautics and turbine applications, creating anchor demand for validated supply chains.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE resin prices fluctuate with fluorspar mining output and Chinese export quotas, compressing margins on aerospace-grade seals.
- European supply chain concentration:REACH-compliant polymer compounding capacity clusters in Germany and the Netherlands, creating single-source vulnerability for qualified material streams.
- Mechanical seal substitution:Advanced labyrinth and magnetic bearing technologies displace fixed length seals in high-speed rotating equipment above 10,000 RPM.
Strategic Opportunities
- India thermal power expansion:CEA-mandated supercritical boiler installations create demand for metal-alloy seals rated above 600°C in coal and combined-cycle plants.
- Hydrogen economy infrastructure:Hydrogen-compatible elastomer formulations open replacement markets in pipeline compression stations and fuel cell manufacturing.
- Digital inventory integration:OEMs adopt vendor-managed inventory systems with IoT-enabled consumption tracking, locking in sole-source positions for integrated suppliers.
Industry Challenges
- Material scientist talent scarcity:Formulation chemists with fluoropolymer and high-temperature elastomer expertise command premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EPA, and ECHA qualification for food-contact and emissions-critical applications extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Length Seals Market |
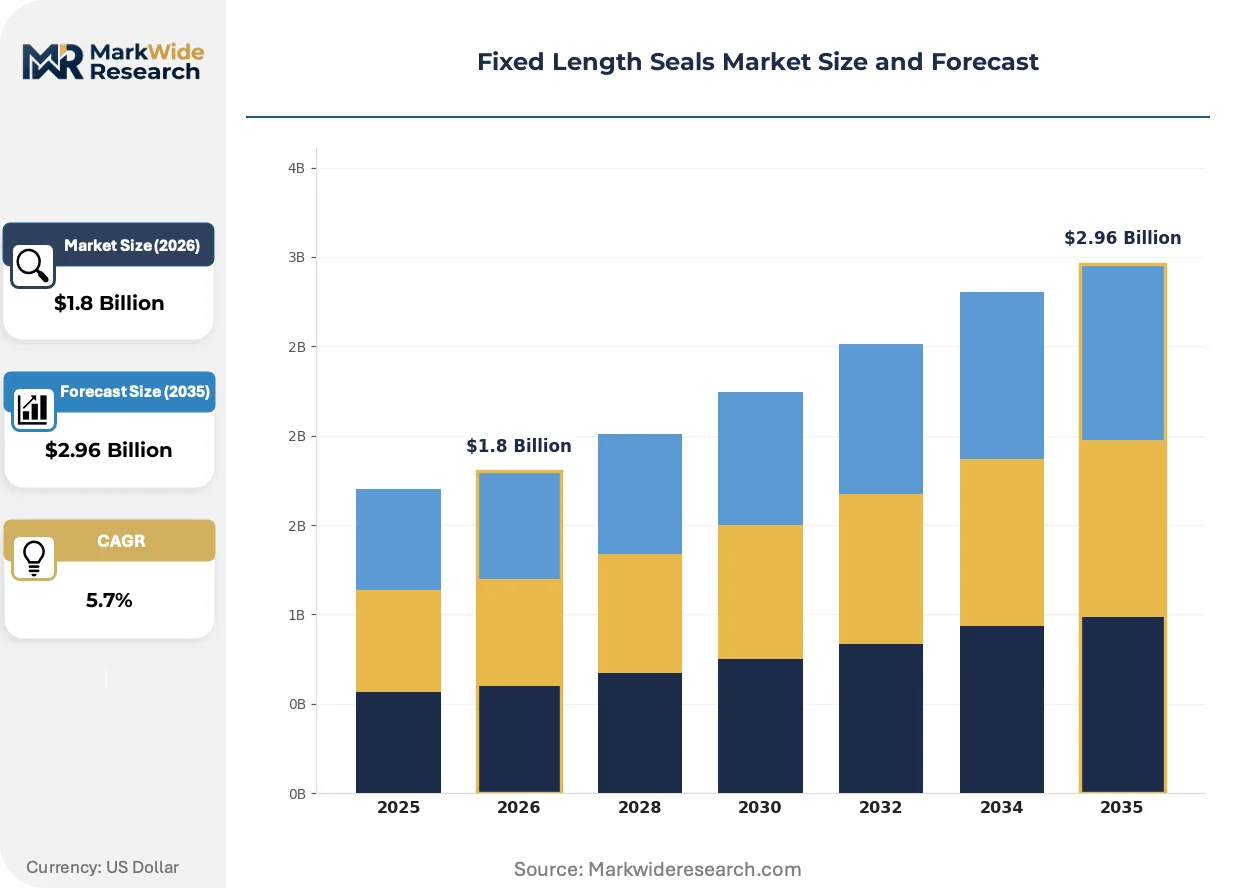
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Mechanical Seals, Lip Seals, Valve Seals Material: Rubber, Silicone, PTFE, Metal, Polyurethane Application: Oil & Gas, Water Treatment, HVAC Systems, Aerospace, Food Processing End User Industry: Petrochemical Plants, Power Generation, Aeronautics, Manufacturing Plants, Processing Facilities |
| Companies Covered | Tyden Brooks, Gunnebo Security Group, Acme Seals, Unisto, Mega Fortris, Versapak Security Seals, Cambridge Security Seals, American Casting & Manufacturing, Essentra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Length Seals Market Shifts & Advancements
Material science breakthroughs and regulatory tightening are converging to reshape competitive advantage around thermal performance certification and supply chain transparency rather than unit cost alone.
Perfluoroelastomer (FFKM) compounds with graphene thermal conductivity enhancement are electrifying seal performance in aerospace turbine applications. Pratt & Whitney and Rolls-Royce procurement teams specify these formulations for next-generation geared turbofan architectures. The technology is electrifying supplier qualification barriers, consolidating specification authority among compounders with in-house polymerization capabilities.
EPA fugitive emissions standards under the Clean Air Act New Source Performance Standards are forcing petrochemical facilities to upgrade seal specifications in valve and flange applications. Refineries along the US Gulf Coast face inspection mandates every 12 months for leaking components. Mechanical seal and packing manufacturers are capturing this upgrade cycle with EPA-compliant low-emission valve stem seal designs.
Consolidated procurement frameworks now bundle fixed length seals into predictive maintenance contracts with uptime guarantees. Power generation utilities in Texas and California negotiate total-cost-of-ownership pricing that internalizes seal replacement labor and inventory carrying costs. This model compresses spot-market opportunities while rewarding suppliers with regional service infrastructure and certified installation capabilities.
Fixed Length Seals Market Segmentation
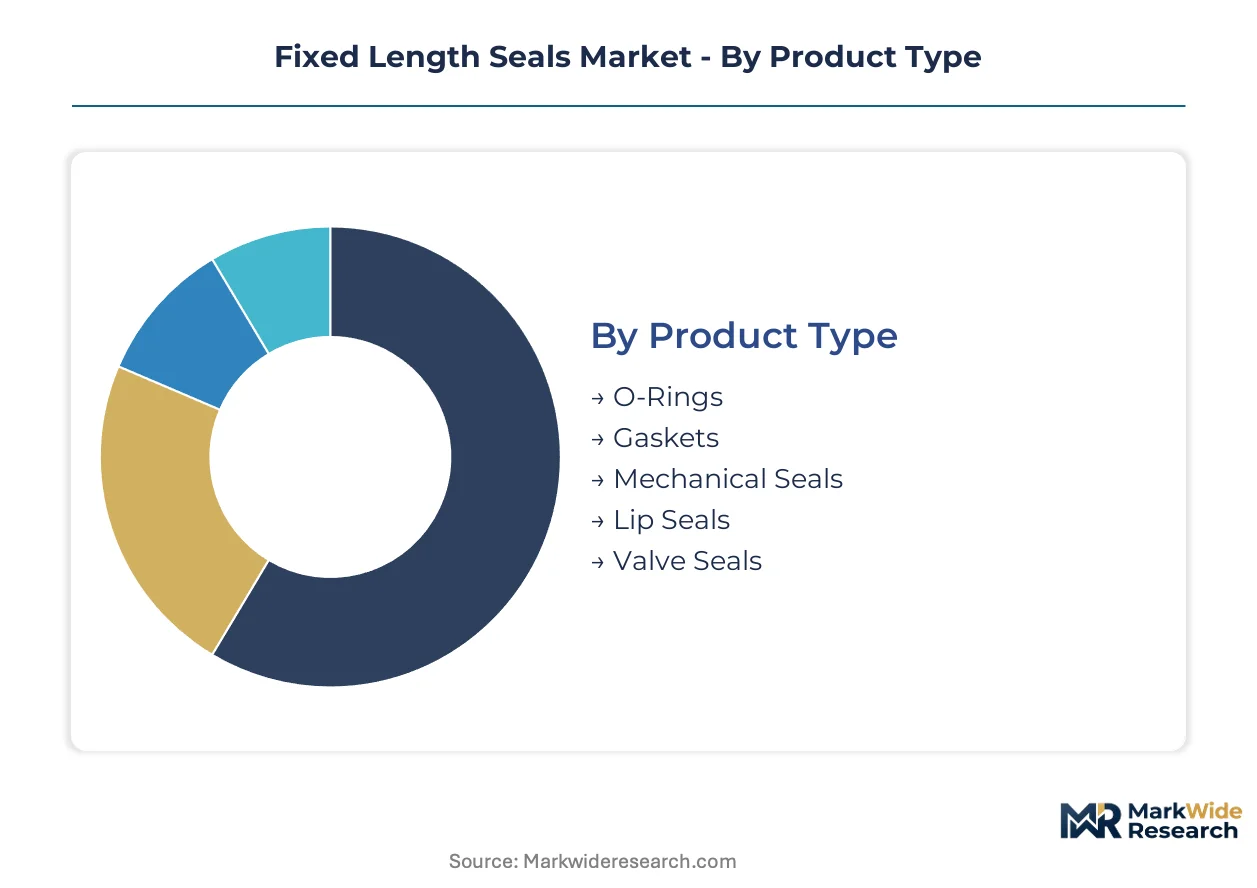
Fixed length seals serve divergent performance requirements across pressure ratings, temperature extremes, and regulatory exposure. Segmentation reveals how material science capabilities and end-use certification burdens reshape supplier economics and customer switching costs.
Product Type:
Standardization dominates high-volume categories while precision-engineered variants command customization premiums and sole-source positions.
- O-Rings:Circular elastomeric loops compressed into grooves create static seals across plumbing, hydraulics, and pneumatic systems. Demand concentrates in water treatment utilities across Germany and the Netherlands, where DIN-standard dimensions simplify procurement but EPA and REACH compliance documentation now extends qualification cycles.
- Mechanical Seals:Multi-component assemblies pair rotating faces with spring-loaded secondary seals to contain process fluids in pumps and compressors. Petrochemical facilities along the US Gulf Coast specify API 682-compliant cartridge designs, bundling fixed length secondary seals into predictive maintenance contracts with uptime penalties.
- Gaskets:Flat sealing elements cut from sheet stock or molded to flange patterns fill irregular mating surfaces.
- Lip Seals:Flexible elastomeric lips maintain contact with rotating shafts to exclude contaminants and retain lubricants.
- Valve Seals:Precision-molded seats and packing sets control fugitive emissions in process isolation equipment.
Most installed capacity flows through O-Rings. Expansion is steepest in Mechanical Seals.
Material:
Cost tiers separate commodity elastomers from fluoropolymer and metal alloys where thermal performance justifies 10-20x unit economics.
- Rubber:Nitrile and EPDM formulations balance oil resistance, weathering, and cost for general industrial service. HVAC OEMs in Texas and Florida specify sulfur-cured compounds for compressor discharge lines, though temperature ceilings near 120°C limit migration into turbine applications.
- PTFE:Sintered fluoropolymer structures deliver chemical inertness and low friction across pH extremes. Aerospace turbine manufacturers in the UK and France mandate virgin PTFE with glass or carbon fillers for bearing seals in geared turbofan architectures, where 300°C operating environments exclude elastomer alternatives.
- Silicone:VMQ and FVMQ compounds maintain flexibility across -60°C to 230°C spans.
- Metal:Stainless steel, Inconel, and cobalt-chrome alloys withstand 600°C+ in supercritical boiler and gas turbine applications.
- Polyurethane:Cast or machined urethane structures combine abrasion resistance with load-bearing capacity.
Volume concentrates in Rubber. Value expansion is fastest in PTFE.
Application:
Regulatory exposure intensity varies sharply—food-contact and emissions-critical applications impose certification burdens that commodity suppliers cannot absorb.
- Oil & Gas:Upstream, midstream, and downstream operations require seals rated for sour gas, high-pressure CO2 injection, and cryogenic LNG service. EPA fugitive emissions mandates drive quarterly leak detection surveys at US refineries, forcing specification upgrades to low-emission valve stem designs.
- Aerospace:Commercial and defense airframers impose AS9100 quality systems with full material traceability. Pratt & Whitney and Rolls-Royce procurement teams specify perfluoroelastomer compounds with graphene thermal conductivity enhancement for next-generation geared turbofan seals.
- Water Treatment:Municipal and industrial filtration systems specify NSF/ANSI 61 certified compounds for potable water contact.
- HVAC Systems:Residential and commercial climate equipment prioritizes cost-optimized nitrile and HNBR formulations.
- Food Processing:FDA 21 CFR 177.2600 compliance governs silicone and rubber materials in dairy, beverage, and meat handling equipment.
Procurement value concentrates in Oil & Gas. Certification complexity is highest in Food Processing.
End User Industry:
Customer scale and contracting sophistication separate fragmented maintenance-spend accounts from consolidated framework agreements.
- Power Generation:Utilities operating coal, gas, nuclear, and renewable assets negotiate multi-year seal procurement with vendor-managed inventory provisions. Germany's RWE and Uniper anchor European demand for turbine valve seals, while Texas and California independent power producers adopt total-cost-of-ownership pricing that internalizes installation labor.
- Petrochemical Plants:Integrated refiners and chemical producers specify seals under corporate engineering standards with approved manufacturer lists. Reliance Industries and SABIC operate captive technical teams that audit compounder polymerization capabilities before qualification.
- Aeronautics:Airframers and tier-1 systems suppliers impose AS9100 and NADCAP special process requirements.
- Manufacturing Plants:Discrete manufacturing operations source seals through distributor channels with limited technical specification.
- Processing Facilities:Mining, pulp and paper, and cement operations prioritize abrasion resistance and rapid availability.
Contract value concentrates in Power Generation. Procurement sophistication is deepest in Petrochemical Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer formulation chemists cluster in Germany's industrial heartland, anchoring European supply capabilities for high-temperature seal applications. Aerospace engineering talent concentrates in the UK and France, driving specification authority for next-generation turbine architectures. Precision manufacturing skills in Japan and the United States support AS9100-certified production for defense and commercial aviation programs.
United States
Petrochemical refineries along the Texas and Louisiana Gulf Coast drive demand for EPA-compliant low-emission valve seals under Clean Air Act inspection mandates. The EPA enforces quarterly leak detection surveys, forcing specification upgrades to fugitive emissions control designs. Houston anchors procurement concentration for power generation utilities adopting total-cost-of-ownership maintenance contracts.
Germany
RWE and Uniper operate supercritical turbine fleets requiring metal-alloy valve seals rated above 550°C in the Rhine-Ruhr industrial corridor. ECHA REACH compliance pathways redirect manufacturing toward low-VOC fluoropolymer formulations under EU Green Deal decarbonization targets. Bavaria's precision engineering ecosystem sources validated supply chains for aeronautics and power generation OEMs.
United Kingdom
Rolls-Royce procurement teams specify perfluoroelastomer compounds with graphene thermal conductivity enhancement for geared turbofan seal applications. The UK Civil Aviation Authority enforces AS9100 quality system mandates with full material traceability requirements. Derby and Bristol manufacturing clusters concentrate aerospace seal qualification authority for next-generation engine architectures.
China
State Power Investment Corporation and Huaneng Group expand supercritical coal capacity, creating demand for Inconel and cobalt-chrome seals in 600°C boiler environments. The Ministry of Ecology and Environment tightens industrial emissions standards through dual carbon policy implementation. Shanghai and Jiangsu province compounders scale PTFE resin processing for domestic aerospace and petrochemical supply chains.
India
NTPC and Adani Power execute CEA-mandated supercritical boiler installations requiring metal-alloy seals in combined-cycle and coal-fired plants. The Central Electricity Authority enforces efficiency standards that accelerate valve seal replacement cycles in aging thermal assets. Gujarat and Maharashtra industrial corridors concentrate procurement for process industries adopting predictive maintenance frameworks.
Fixed Length Seals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between security-seal heritage players extending into industrial applications and polymer compounders with in-house formulation capabilities. Three archetypes dominate: integrated material-science compounders, security-seal specialists leveraging tamper-evident credibility, and regional fabrication houses serving distributor channels. Consolidation pressures favor backward integration into polymerization capacity and geographic expansion through qualified installation networks.
Among security-seal heritage players, Tyden Brooks and Mega Fortris occupy positions that bridge tamper-evident architectures into critical infrastructure sealing. Essentra anchors European supply through REACH-compliant material capabilities. These three exemplify how regulatory certification burdens and polymer compounding depth determine competitive viability in emissions-critical and aerospace-grade segments.
| Leading Market Players |
|---|
| Tyden Brooks |
| Gunnebo Security Group |
| Acme Seals |
| Unisto |
| Mega Fortris |
| Versapak Security Seals |
| Cambridge Security Seals |
| American Casting & Manufacturing |
| Essentra |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements from power generation utilities and aerospace OEMs are compressing supplier margins while demanding REACH-compliant material traceability and thermal cycling guarantees, forcing compounders to absorb certification costs or cede share to integrated competitors with captive polymerization capacity.
Pricing Analysis
Capacity additions in China's PTFE resin processing sector are reshaping price floors for aerospace-grade seals. Three-tier pricing structure across premium AS9100-certified, standard industrial-grade, and economy HVAC tiers separates suppliers by thermal performance certification and material traceability depth. Price differentiation hinges on fluoropolymer formulation complexity and EPA emissions compliance documentation. Cost compression in standard rubber O-rings is intensifying because of Chinese compounder scale advantages. Water treatment utilities exhibit highest price sensitivity; aerospace turbine manufacturers show least.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes is amplifying landed cost spreads for REACH-compliant formulations. Supply concentrates in Germany, the Netherlands, and China for polymer compounding; fluorspar mining feeds from China and Mexico. Raw material dependencies center on PTFE resin, high-purity fluorspar, and specialty elastomer curatives. Single-source vulnerability in German REACH-compliant compounding capacity creates qualification bottlenecks. Distribution runs through authorized distributor networks with certified installation capabilities for predictive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between ECHA REACH compliance costs in Europe and EPA emissions-driven upgrade cycles in the United States, with regulatory divergence creating margin capture potential for dual-certified suppliers.
For Market Incumbents: Hedge fluoropolymer feedstock exposure through long-term offtake agreements with Chinese fluorspar processors. Defend AS9100-certified positions by acquiring regional installation service networks in Texas and California power markets. Magnetic bearing substitution above 10,000 RPM threatens mechanical seal volumes; prioritize graphene-enhanced FFKM development for next-generation turbofan architectures. For New Entrants and Emerging Players: Independent power producers in India represent the most penetrable buyer archetype for metal-alloy valve seals in CEA-mandated supercritical installations. Hydrogen pipeline compression stations offer white-space demand for compatible elastomer formulations. Pursue vendor-managed inventory partnerships with IoT-enabled consumption tracking to lock sole-source positions. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier compounders possessing in-house polymerization capabilities and pending dual FDA-EPA qualifications. Five-to-ten year viability favors suppliers with backward integration into fluorspar processing or captive high-temperature elastomer R&D. Monitor ECHA REACH substance restriction proposals as inflection signal for material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Processing | Captive supply of critical feedstock hedges Chinese export quota volatility for PTFE compounders. |
| Dual FDA-EPA Certification Investment | Simultaneous qualification slashes 18-24 month launch cycles for food-contact and emissions-critical applications. |
| Vendor-Managed Inventory Partnerships | IoT-enabled consumption tracking locks sole-source positions with Texas and California power utilities. |
| Graphene-Enhanced FFKM Development | Thermal conductivity breakthroughs meet Pratt & Whitney and Rolls-Royce next-generation turbofan specifications. |
| Hydrogen-Compatible Elastomer Formulation | Pipeline compression station demand opens replacement markets ahead of infrastructure buildout cycles. |
Research Methodology
Direct dialogue with plant engineers at power generation utilities, procurement leads at petrochemical facilities, technical R&D directors at polymer compounders, and aftermarket service heads at aerospace distributors grounded qualitative findings. Secondary validation drew from ECHA REACH substance databases, EPA Clean Air Act enforcement records, API equipment standards, and customs trade data for fluoropolymer resin flows. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Segment-level projections across material type, product architecture, end-use industry, and regional regulatory cluster fed into analytical framework calculations over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating supercritical boiler installation mandates, fugitive emissions inspection frequencies, and turbine fleet replacement schedules. Modeled inputs included REACH compliance cost trajectories and fluorspar price volatility indices.
Inputs from utility procurement officers and aerospace tier-1 suppliers were available through the study window; gaps in real-time Chinese fluorspar export quota data introduce uncertainty bands around PTFE resin price assumptions. Forecasts reflect documented elasticity parameters and regulatory implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Child Resistant Pipette Closures Market