
 Child Resistant Dropper Caps Market | 2026-2036
Child Resistant Dropper Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Dropper Caps Market Outlook
Multi-source procurement is hardening across the child resistant dropper caps supply base as brand owners diversify away from single-supplier concentration risk. Berry Global Inc. leverages its North American manufacturing footprint to anchor contracts with large pharmaceutical packagers. AptarGroup, Inc. differentiates through precision molding capabilities that yield consistent torque-release performance. Gerresheimer AG extends its glass-primary packaging dominance into complementary closure systems for injectable and oral liquid formats.
Child resistant dropper caps are engineered closure systems incorporating a dual-action or press-and-turn mechanism that requires coordinated adult hand strength to open, typically manufactured through injection molding of polypropylene or polyethylene with integrated silicone or thermoplastic elastomer bulbs. Their primary purpose is to prevent accidental ingestion by children under five years while maintaining accessibility for adults, particularly for liquid medications, essential oils, and concentrated household chemicals. Plastic caps dominate unit volume due to cost scalability and color customization flexibility, though combination caps that integrate glass droppers with child-resistant overcaps capture premium margin pools in pharmaceutical applications. Single-use configurations lead in regulated pharmaceutical channels where sterility and tamper evidence take precedence, while multi-use formats sustain growth in cosmetics and nutraceutical segments where consumer retention and brand aesthetics matter.
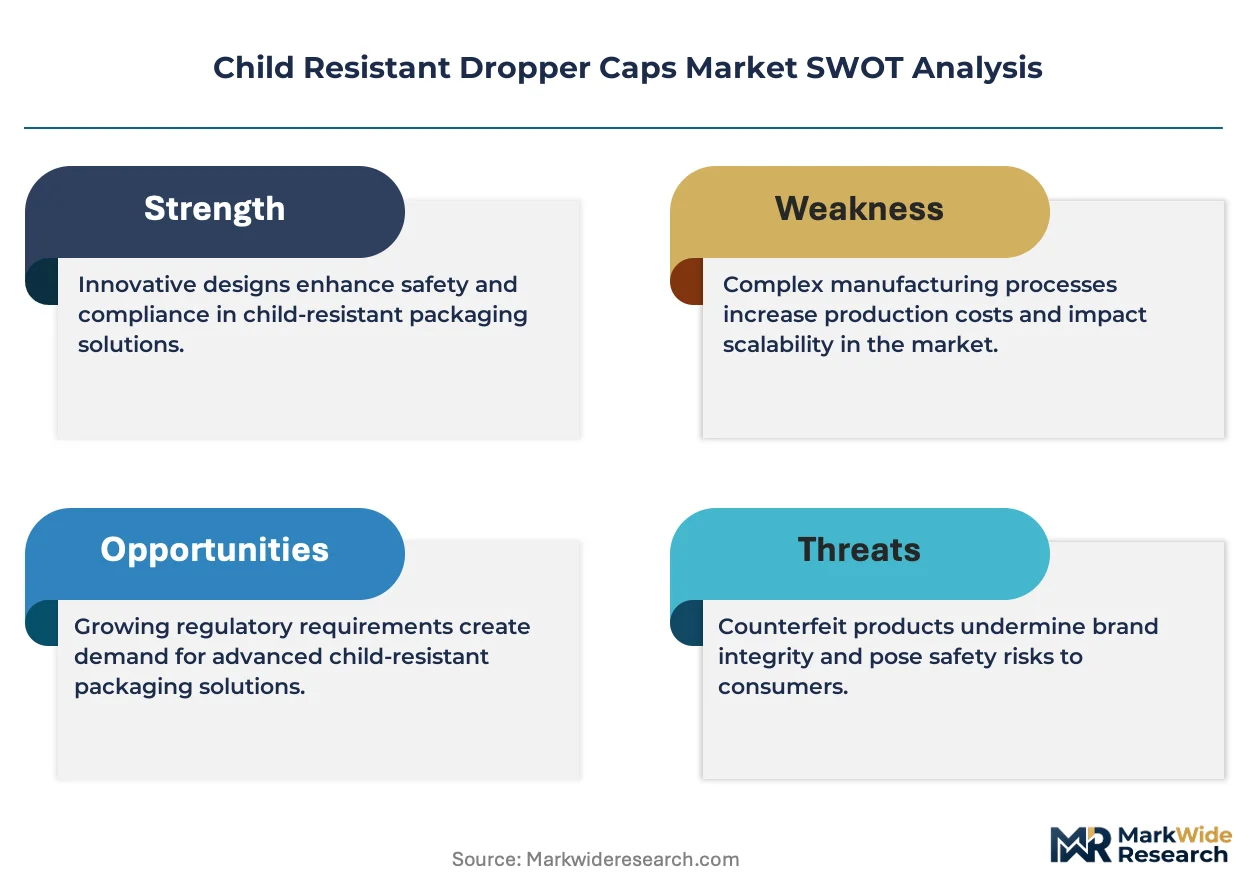
The US Consumer Product Safety Commission enforces the Poison Prevention Packaging Act, which mandates child-resistant closures for hazardous household substances including certain medications and chemicals. The European Medicines Agency incorporates child-resistant packaging requirements into its broader pharmaceutical quality guidelines, while ISO 8317 provides international testing protocols that manufacturers must pass to certify compliance. Stakeholders should monitor evolving state-level cannabis packaging regulations in the United States, as these rules frequently adopt stricter child-resistant standards than federal baseline requirements and create new specification demand across emerging product categories.
Market Dynamics
Pharmaceutical packaging mandates from the US Consumer Product Safety Commission and the European Medicines Agency are compressing certification timelines and forcing manufacturers to retool molding lines for dual-action closure mechanisms. This regulatory tightening concentrates purchasing power among packagers with in-house testing capabilities.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US CPSC maintains strict testing protocols for household substances, compelling pharmaceutical and essential oil brands to specify certified child-resistant closures in procurement tenders.
- Injectable liquid formats:Biologic drug delivery systems require tamper-evident, sterile dropper assemblies that integrate glass droppers with compliant overcaps, expanding specification complexity and unit value.
- State-level cannabis packaging rules:California, Colorado, and Illinois impose child-resistant standards exceeding federal baselines, creating dedicated specification demand across emerging adult-use product categories.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings for injection-molded cap bodies compress margin predictability for mid-tier converters without long-term supply agreements.
- ISO 8317 certification backlog:Third-party testing laboratory capacity constraints in Western Europe extend time-to-market for new closure designs by four to eight weeks.
- Single-use plastic directives:The EU Single-Use Plastics Regulation creates compliance friction for standard polypropylene configurations without approved recycling pathways or biodegradable alternatives.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned packaging requirements for oral liquid formulations destined to regulated markets create upgrade demand among domestic contract manufacturers.
- Connected closure systems:Integration of near-field communication tags with child-resistant mechanisms enables dose-tracking and adherence monitoring for chronic disease therapies.
- Direct-to-consumer nutraceutical channels:Subscription-based wellness brands prioritize retention-optimized multi-use droppers with aesthetic customization, bypassing traditional pharmaceutical distributor markups.
Industry Challenges
- Precision molding talent scarcity:Tooling engineers capable of maintaining 0.05mm tolerance bands for torque-release consistency command premium wages and limited geographic mobility.
- Legacy line integration:Pharmaceutical packagers running 1990s-era capping equipment face mechanical incompatibility with newer dual-action closure geometries, requiring capital-intensive retrofits or greenfield investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Dropper Caps Market |
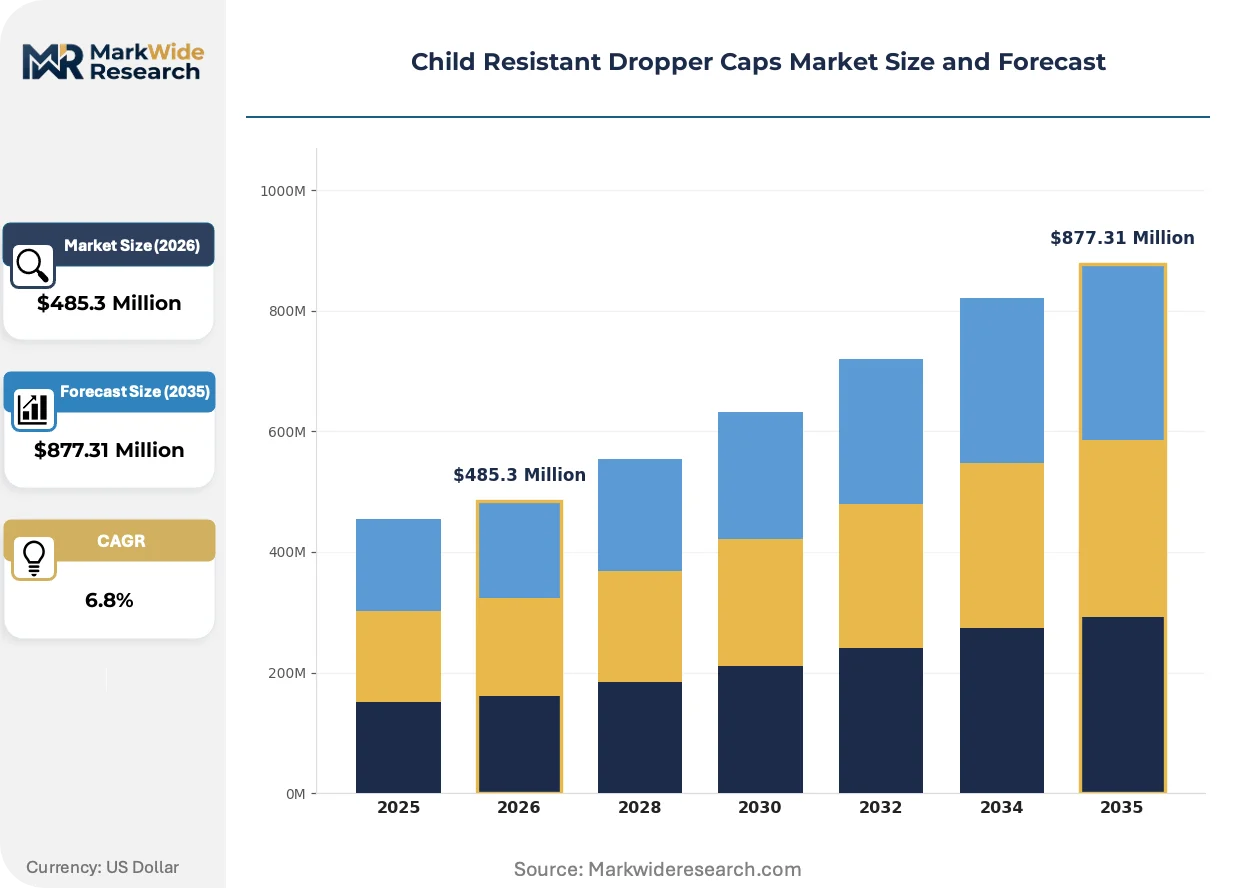
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Glass Caps, Metal Caps, Combination Caps Application: Pharmaceuticals, Nutraceuticals, Cosmetics, Household Products Usage Type: Single-Use, Multi-Use, Bulk Packaging, Retail Packaging End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Berry Global Inc., AptarGroup, Inc., Origin Pharma Packaging, Gerresheimer AG, Comar LLC, VIROSPACK, SGD Pharma, Thermo Fisher Scientific, FH Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Dropper Caps Market Strategic Shifts
Thermoplastic elastomer formulation advances and connected packaging integration are compressing traditional procurement cycles. Manufacturers now compete on torque-release precision and digital traceability rather than unit cost alone.
Biobased polypropylene derived from renewable feedstocks is rewriting material specification norms for premium pharmaceutical applications. European packagers under CSRD disclosure requirements are accelerating adoption to meet Scope 3 emissions targets. This transition is compressing the addressable market for conventional petroleum-based resins in high-visibility brand portfolios.
The EU Medical Device Regulation expands child-resistant packaging requirements to a broader class of liquid drug-device combination products. German and French notified bodies are interpreting MDR Annex I general safety requirements to encompass closure integrity testing. Injectable format manufacturers are responding by consolidating supplier panels to those with MDR-compliant quality management systems.
Brand owners now specify outcome-based performance guarantees rather than component-level purchasing. Large pharmaceutical packagers in the United States are shifting to total-cost-of-ownership contracts that penalize torque-failure rates and reward lot-traceability integration. This restructuring is most visible in parenteral and ophthalmic liquid segments where FDA 21 CFR Part 11 compliance requirements intersect with child-resistant functionality.
Child Resistant Dropper Caps Market Segmentation
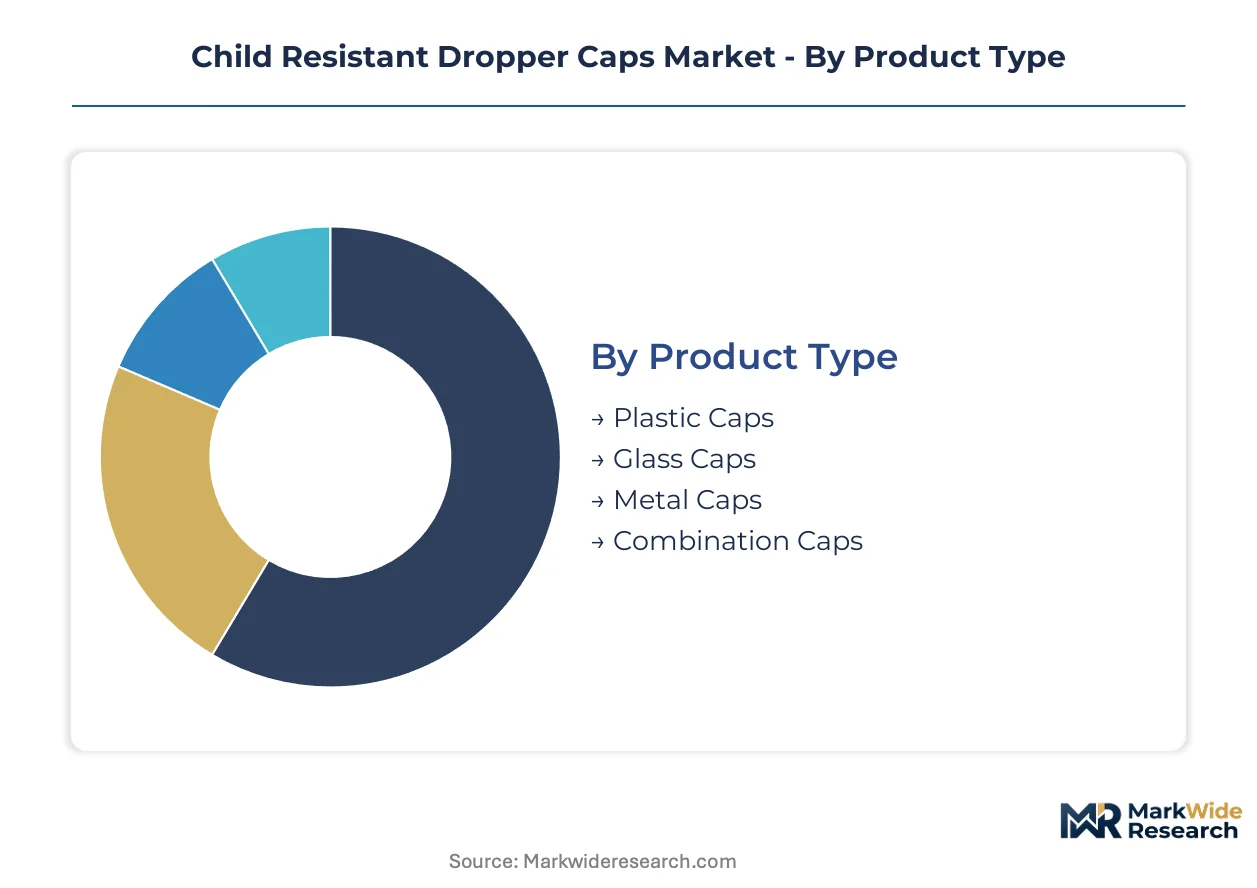
Child resistant dropper caps serve divergent compliance and functional requirements across pharmaceutical, cosmetic, and household chemical channels. Segmentation reveals how material selection, application stringency, and usage patterns reshape procurement specifications and supplier capabilities.
Product Type:
Material cost tiers and regulatory certification depth drive buyer selection between commodity and premium closure configurations.
- Plastic Caps:Injection-molded polypropylene or polyethylene bodies with integrated thermoplastic elastomer bulbs dominate unit economics. Pharmaceutical packagers in the United States specify these for oral liquid medications under CPSC Poison Prevention Packaging Act mandates, prioritizing batch-to-batch torque consistency over material prestige.
- Combination Caps:Glass droppers paired with child-resistant overcaps command specification in biologic injectables and ophthalmic formulations where sterility and tamper evidence intersect. German notified bodies under EU MDR Annex I requirements are accelerating consolidation toward suppliers with medical device quality management systems for this configuration.
- Glass Caps:Borosilicate dropper assemblies with threaded metal collars serve premium essential oil and serum applications where chemical inertness and aesthetic clarity outweigh unit cost considerations.
- Metal Caps:Aluminum overcaps with press-and-turn mechanisms retain niche positioning in industrial chemical and agricultural concentrate packaging where mechanical durability exceeds polymer alternatives.
Volume sits with Plastic Caps; growth tilts toward Combination Caps.
Application:
Regulatory enforcement intensity and liability exposure create divergent specification barriers across end-use channels.
- Pharmaceuticals:FDA 21 CFR Part 11 traceability requirements intersect with child-resistant functionality in parenteral and ophthalmic liquid segments. Large US packagers now impose total-cost-of-ownership contracts penalizing torque-failure rates.
- Cosmetics:Subscription-based wellness brands prioritize retention-optimized multi-use droppers with aesthetic customization, bypassing traditional pharmaceutical distributor markups and compressing procurement cycles.
- Nutraceuticals:Direct-to-consumer channels demand mid-tier certification compliance without pharmaceutical-grade documentation overhead, creating a specification middle ground.
- Household Products:Concentrated cleaning solutions and pesticides trigger CPSC enforcement in the United States, though certification stringency lags pharmaceutical baselines.
Revenue concentrates in Pharmaceuticals; expansion accelerates fastest in Cosmetics.
Usage Type:
Sterility requirements and consumer retention economics split procurement between disposable and durable configurations.
- Single-Use:Pre-sterilized, tamper-evident assemblies dominate regulated pharmaceutical channels where lot traceability and contamination control override per-unit cost. ISO 8317 certification backlog in Western European testing laboratories extends time-to-market for new designs.
- Multi-Use:Refillable droppers with reinforced thread engagement sustain growth in cosmetics and nutraceutical segments where brand aesthetics and consumer loyalty drive repeat purchase economics.
- Bulk Packaging:Unassembled cap and bulb components shipped to contract fillers reduce freight cube and customs complexity for high-volume oral liquid manufacturers.
- Retail Packaging:Shelf-ready blister or clamshell configurations incorporate theft-deterrent features alongside child-resistant functionality for mass-market distribution.
Unit volume favors Single-Use; margin expansion tracks Multi-Use.
End User:
Supply chain position determines whether procurement prioritizes component cost, assembly integration, or regulatory documentation.
- Manufacturers:Pharmaceutical and chemical formulators with in-house filling lines specify raw torque-release tolerances and resin grades, consolidating purchasing power among packagers with captive testing capabilities.
- Distributors:Wholesalers serving mid-tier nutraceutical brands aggregate demand across multiple SKUs, favoring suppliers with flexible minimum order quantities and rapid color-matching turnaround.
- Retailers:Pharmacy chains and specialty wellness stores increasingly specify outcome-based performance guarantees rather than component-level purchasing, shifting liability upstream.
- Consumers:Direct-to-consumer subscription models bypass traditional distribution tiers, enabling specification of premium multi-use configurations with aesthetic differentiation.
Procurement authority concentrates with Manufacturers; channel disruption emanates from Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin production clusters in Texas and Louisiana anchor North American supply chains for injection-molded cap bodies. European converters source feedstock from Rotterdam and Antwerp petrochemical hubs. Asian pharmaceutical contract manufacturers in India and China drive specification upgrades for export compliance.
United States
Pharmaceutical packagers in New Jersey and Pennsylvania dominate procurement volume for oral liquid medications. The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act testing protocols that compress certification timelines. Chicago-area converters retool molding lines for dual-action closure mechanisms to serve CPG brands.
Germany
Injectable biologic manufacturers in Bavaria and Baden-Württemberg specify combination caps with glass droppers and child-resistant overcaps. German notified bodies under EU Medical Device Regulation Annex I interpret general safety requirements to encompass closure integrity testing. The Rhine-Main cluster concentrates suppliers with MDR-compliant quality management systems.
India
Contract manufacturers in Maharashtra and Gujarat upgrade packaging for oral liquid formulations destined to regulated markets. The Central Drugs Standard Control Organization aligns packaging requirements with export destination standards. Hyderabad's pharmaceutical corridor drives demand for certified closure systems among generic drug exporters.
China
Essential oil and nutraceutical producers in Guangdong and Zhejiang source child-resistant droppers for domestic and export channels. The National Medical Products Administration strengthens packaging standards for liquid drug formulations. The Yangtze River Delta concentrates molding capacity serving both pharmaceutical and cosmetic end-users.
France
Ophthalmic and parenteral liquid specialists in the Île-de-France region impose torque-failure rate penalties in supplier contracts. The French National Agency for Food, Environmental and Occupational Health Safety enforces child-resistant packaging for hazardous household substances. The Lyon-Saint-Étienne corridor hosts precision molding operations serving premium pharmaceutical applications.
Child Resistant Dropper Caps Market Competitive Environment
Global majors compete with regional champions across certification depth and molding precision. The vendor base stratifies into three tiers: integrated packaging conglomerates with captive resin supply, mid-cap specialists with medical-device quality systems, and regional converters serving cosmetic and nutraceutical channels. Consolidation pressure intensifies as pharmaceutical packagers consolidate supplier panels to those with in-house ISO 8317 testing capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing long-term resin agreements or co-developing connected closure systems with dose-tracking functionality.
Among North American packaging conglomerates, Berry Global Inc. and AptarGroup, Inc. occupy positions exemplifying scale-driven and precision-molding archetypes respectively. Berry Global Inc. anchors contracts with large pharmaceutical packagers through its continental manufacturing footprint. AptarGroup, Inc. represents the torque-consistency specialist tier. European glass-primary packaging leader Gerresheimer AG exemplifies backward integration into complementary closure systems, extending dominance from injectable vials into dropper assemblies. These three entities illustrate how geographic coverage, certification depth, and vertical control separate competitive positions.
| Leading Market Players |
|---|
| Berry Global Inc. |
| AptarGroup, Inc. |
| Origin Pharma Packaging |
| Gerresheimer AG |
| Comar LLC |
| VIROSPACK |
| SGD Pharma |
| Thermo Fisher Scientific |
| FH Packaging |
| Others |
Value Chain & Pricing Dynamics
Large pharmaceutical packagers in New Jersey and Pennsylvania anchor procurement volume through total-cost-of-ownership contracts that penalize torque-failure rates, compressing margin pools for mid-tier converters without in-house ISO 8317 testing capabilities. This buyer concentration forces suppliers to bundle certification guarantees and lot-traceability integration into quoted pricing rather than competing on unit cost alone.
Pricing Analysis
Warranty and service bundling separates premium suppliers from commodity converters in this market, with MDR-compliant quality management systems and ISO 8317 certification guarantees packaged into long-term supply agreements. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and torque-release precision, with pharmaceutical-grade documentation commanding substantial premiums over cosmetic-channel equivalents. Cost compression in standard polypropylene configurations is intensifying because EU Single-Use Plastics Regulation compliance requires approved recycling pathways or biobased alternatives. Contract manufacturers serving direct-to-consumer nutraceutical channels exhibit highest price sensitivity, while Bavarian injectable biologic manufacturers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical corridor and state-level cannabis packaging rules in California, Colorado, and Illinois are reshaping sourcing patterns toward regional molding capacity with aligned certification capabilities. Polypropylene resin production clusters in Texas and Louisiana anchor North American supply chains, while European converters draw from Rotterdam and Antwerp petrochemical hubs and Asian contract manufacturers source from Guangdong and Zhejiang molding centers. Feedstock price volatility for injection-molded cap bodies creates margin unpredictability for converters without long-term supply agreements. Distribution runs through pharmaceutical packagers with captive testing capabilities, direct-to-consumer subscription channels, and wholesale distributors serving mid-tier nutraceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected closure systems integrating near-field communication tags are displacing conventional mechanical-only configurations, creating a technology-transition window where digital traceability capabilities determine competitive survival.
For Market Incumbents: Extend MDR-compliant quality management systems and ISO 8317 in-house testing capabilities to defend against mid-tier converters losing access to oversubscribed third-party laboratories. Consolidate supplier panels among pharmaceutical packagers running 1990s-era capping equipment by offering capital-intensive retrofit partnerships or greenfield co-investment structures. Backward integration into biobased polypropylene feedstocks addresses CSRD disclosure requirements and Scope 3 emissions targets pressing European brand portfolios. For New Entrants and Emerging Players: State-level cannabis packaging rules in the United States open a window for specialized converters with rapid color-matching turnaround and flexible minimum order quantities serving emerging adult-use product categories. Target direct-to-consumer nutraceutical subscription channels where aesthetic customization and retention-optimized multi-use droppers bypass traditional pharmaceutical distributor markups. Pursue white-label partnerships with Indian contract manufacturers in Maharashtra and Gujarat upgrading packaging for CDSCO-aligned export compliance. For Investors and Strategic Acquirers: The window for entry favors precision molding specialists with medical-device quality systems and captive ISO 8317 testing capabilities. Long-term viability hinges on consolidation plays where torque-consistency engineering talent and MDR Annex I interpretation expertise concentrate in German and French notified body jurisdictions. Watch for inflection when pharmaceutical packagers shift from component-level purchasing to outcome-based performance guarantees with penalty structures for torque-failure rates.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Closure System Development | NFC tag integration enables dose-tracking for chronic disease therapies under FDA 21 CFR Part 11. |
| Biobased Polypropylene Transition | Renewable feedstock adoption meets CSRD Scope 3 targets for European pharmaceutical brand owners. |
| MDR-Compliant Quality System Investment | Annex I closure integrity testing requirements concentrate purchasing among notified body-aligned suppliers. |
| In-House ISO 8317 Testing Capability | Third-party laboratory backlog in Western Europe extends time-to-market for uncertified converters. |
| Direct-to-Consumer Channel Partnership | Subscription wellness brands prioritize retention-optimized multi-use droppers with aesthetic differentiation. |
Study Parameters
Regulatory filings from FDA, EMA, and CDSCO, trade data from customs authorities, and pharmaceutical packaging tender databases formed the secondary backbone for this analysis. Primary interviews with pharmaceutical packaging procurement managers, tooling engineers maintaining torque-release tolerances, regulatory affairs leads at notified bodies, and contract manufacturing executives at Indian generic exporters validated secondary findings. Bottom-up and top-down triangulation cross-checked unit volume estimates against resin consumption patterns and certification database records.
Bottom-up modeling built forecasts from product-type, application, usage-type, and end-user segmentations across the analysis window, while top-down validation anchored against pharmaceutical packaging expenditure trends and regulatory enforcement intensity indicators. CAGRs derived from segment-level growth drivers including Poison Prevention Packaging Act enforcement, EU MDR Annex I expansion, and state-level cannabis packaging rule adoption. Forecast inputs incorporated polypropylene resin price volatility assumptions and third-party testing laboratory capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for connected closure systems with dose-tracking functionality would alter the outlook if NFC integration costs compress faster than projected or pharmaceutical adherence monitoring requirements shift toward smartphone-based solutions. Forecasts reflect assumptions about regulatory enforcement continuity, resin supply agreement stability, and precision molding talent mobility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Crown Caps Market
Caps and Closures
Cover Caps Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Linerless Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
PCR Closures Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
IBC Caps Market
Caps and Closures
Flapper Caps Market