
 US Caps and Closure Market | 2026-2036
US Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
US Caps and Closure Market Analytics
Midwest manufacturing expansion is reshaping domestic supply availability for injection-molded closures. Berry Global Group, Inc. leverages large-scale thermoforming operations across multiple states to serve national beverage accounts. Silgan Holdings Inc. anchors its position through metal closure dominance in food canning segments. AptarGroup, Inc. specializes in precision-dispensing systems for pharmaceutical and cosmetic applications.
Caps and closures are mechanical sealing devices manufactured from plastic resins, metal alloys, or composite substrates, typically featuring threaded, snap-fit, or crimped geometries designed to contain, protect, and dispense packaged contents. Injection molding and compression molding constitute the primary conversion processes, with torque specifications and seal integrity measured against ASTM and ISO performance protocols. Screw caps retain the largest volume share across beverage and food channels, while spout caps capture expanding demand in on-the-go liquid formats. Plastic materials dominate unit economics due to lightweighting advantages, though metal closures sustain premium positioning in wine and spirits packaging where oxygen ingress control determines shelf stability.
FDA food-contact notifications, EPA resin emissions guidelines, and California's recycled-content mandates under SB 54 collectively dictate material selection and design validation cycles for domestic suppliers. OSHA workplace exposure limits further constrain solvent-based decorating processes in closure finishing operations. Stakeholders must monitor evolving state packaging EPR legislation and bioplastics certification pathways to preserve market access.
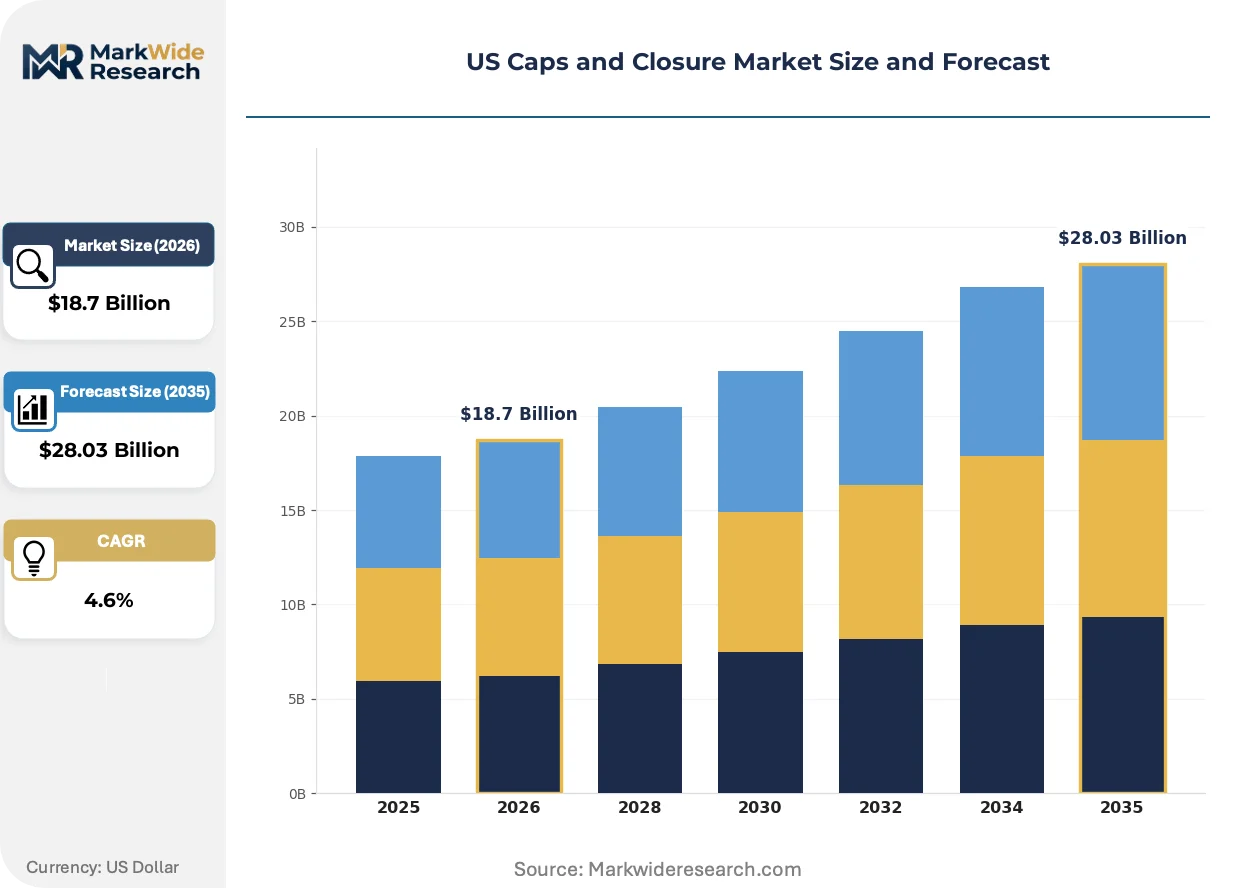
Market Dynamics
California's SB 54 recycled-content mandates and FDA food-contact notification requirements are forcing material selection redesigns across domestic injection-molding operations, compressing validation cycles and reshaping supplier qualification protocols for beverage and pharmaceutical packagers.
Growth Catalysts
- State-Level Recycled-Content Mandates:California SB 54 establishes minimum post-consumer resin thresholds for rigid plastic packaging, compelling closure manufacturers to certify recycled feedstock streams and invest in compatibilizer technologies.
- Pharmaceutical Contract Packaging Concentration:New Jersey corridor packagers are expanding sterile filling capacity for biologics, driving demand for precision-dispensing closures with validated seal integrity and child-resistant functionality.
- Midwest Beverage Bottling Expansion:Regional bottlers are retrofitting lines for tamper-evident closures, creating localized demand surges for 28mm PCO neck finishes and linerless sealing systems.
Market Restraints
- Resin Price Volatility:Polypropylene and high-density polyethylene feedstock costs fluctuate with Gulf Coast petrochemical capacity, compressing margin predictability for high-volume screw cap producers.
- Tooling Lead Time Concentration:Domestic mold fabrication capacity concentrates among Ohio and Michigan tool shops, creating 16-24 week bottlenecks for new closure geometry validation.
- Metal Substitution Ceiling:Aluminum roll-on closures retain oxygen barrier advantages for wine and spirits applications, limiting plastic displacement in premium shelf-stable segments despite lightweighting pressure.
Strategic Opportunities
- Bioplastics Certification Pathways:USDA BioPreferred and ASTM D6400 compostability standards create premium positioning for polylactic acid and bio-based polyethylene closures in organic food and natural personal care channels.
- Single-Use Biologic Vial Integration:Prefilled syringe and vial formats for mRNA therapies require specialized elastomeric closures with extractables testing, opening high-margin niches for validated cleanroom manufacturers.
- Direct-to-Consumer E-Commerce Packaging:Leak-resistant spout caps and child-resistant dispensing systems address last-mile durability requirements for liquid household products shipped through Amazon and Target fulfillment networks.
Industry Challenges
- Multi-Layer Material Sorting Infrastructure:Post-industrial regrind from colored and lined closures lacks standardized near-infrared identification protocols, complicating closed-loop recycling commitments under extended producer responsibility frameworks.
- Validation Timeline Compression:FDA food-contact notification reviews for novel barrier coatings now extend 180-270 days, delaying product launches for seasonal beverage contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Caps and Closure Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap-On Caps, Screw Caps, Spout Caps, Corks Material: Plastic, Metal, Wood, Glass End User: Beverage Industry, Food Packaging, Pharmaceuticals, Cosmetics Size: Small, Medium, Large, Custom |
| Companies Covered | AptarGroup, Inc., Berry Global Group, Inc., Silgan Holdings Inc., Closure Systems International, Amcor Plc, Crown Holdings, Inc., BERICAP, Guala Closures Group, O.Berk Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Caps and Closure Market Evolving Landscape
Thermoformed and injection-molded closure designs are converging with smart packaging and sustainability verification systems, creating new performance specifications that extend beyond mechanical seal integrity into digital traceability and circular economy compliance.
Mono-material polyethylene closures with integrated induction heat-seal liners are migrating from standard beverage applications into pharmaceutical oral solid dose packaging. Contract packagers along the New Jersey corridor are qualifying these formats for moisture-sensitive tablets, eliminating aluminum foil lidding complexity. The shift is compressing secondary packaging material requirements while demanding tighter torque tolerance controls.
EPA resin emissions guidelines under the Clean Air Act are tightening volatile organic compound thresholds for solvent-based decorating processes in closure finishing operations. Ohio and Indiana manufacturing plants face retrofit requirements for digital printing and laser marking alternatives. Food canning segments with metal closure dominance are absorbing compliance costs through line-speed adjustments rather than capital-intensive equipment replacement.
Direct-store-delivery beverage distributors are consolidating supplier relationships around single-source closure-to-bottle compatibility guarantees. Regional bottlers in Michigan and Wisconsin now require torque testing documentation and seal integrity certifications as standard procurement terms, displacing fragmented multi-vendor purchasing patterns. The concentration is most visible in craft brewing and kombucha segments where package failure rates directly impact retail shelf access negotiations.
US Caps and Closure Market Segmentation
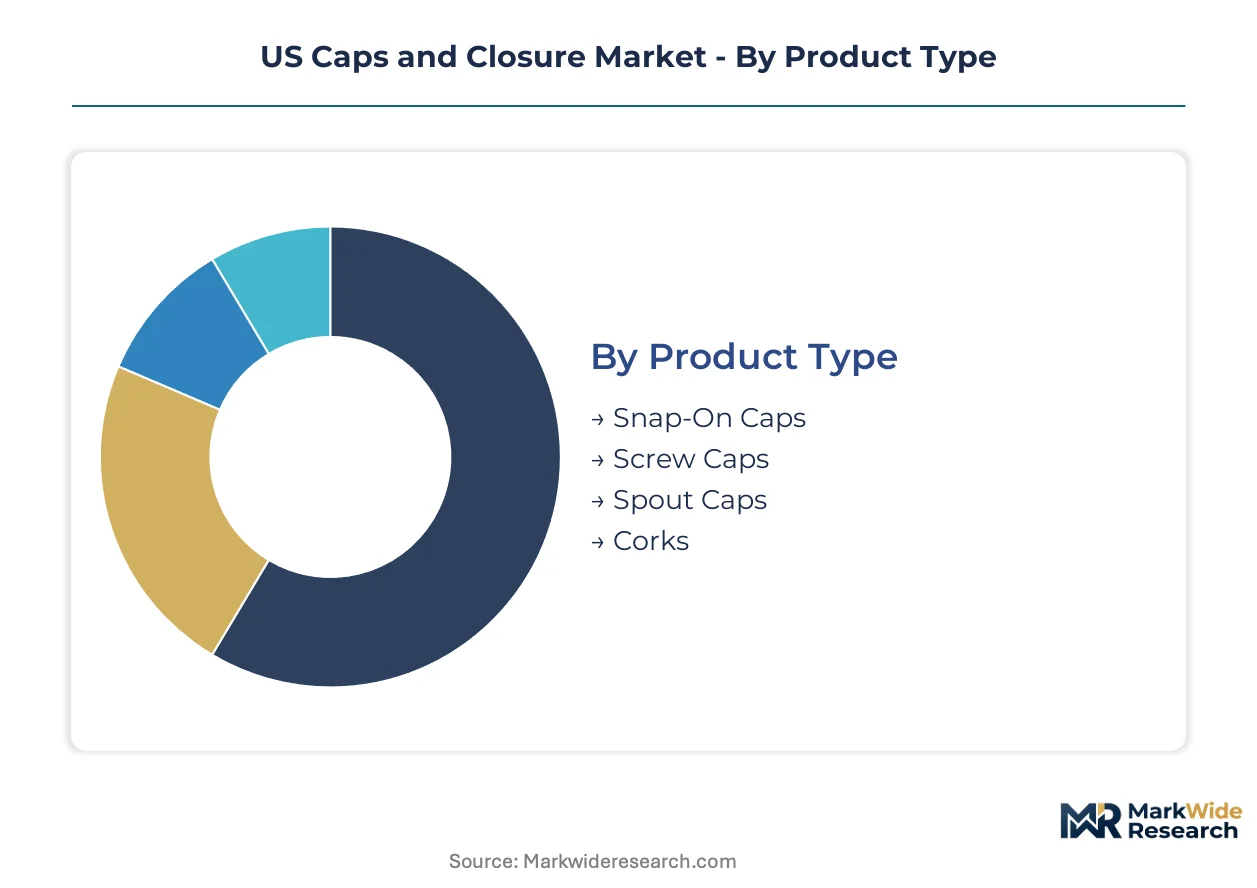
Caps and closures serve divergent performance requirements across beverage containment, pharmaceutical sterility, and cosmetic dispensing. Segmentation reveals how material selection and geometry specifications align with end-use validation protocols and regional manufacturing concentration.
Product Type:
Mature screw formats dominate high-volume throughput, while emerging spout geometries capture on-the-go consumption shifts.
- Screw Caps:Threaded geometries manufactured through injection molding deliver repeatable torque performance and seal integrity. Beverage bottlers across Michigan and Wisconsin specify 28mm PCO neck finishes with linerless induction seals, driven by direct-store-delivery consolidation requiring documented torque testing. Screw caps handle the majority of throughput; spout caps are the fastest mover on share.
- Spout Caps:Integrated dispensing geometries with flip-top or push-pull actuation serve liquid formats demanding controlled portioning. Kombucha and cold-brew coffee packagers in the Midwest retrofit lines for these formats, responding to retail shelf access negotiations that penalize package failure rates.
- Snap-On Caps:Radial interference fits with audible engagement feedback suit dry goods and pharmaceutical oral solid dose applications where child-resistant functionality meets senior-friendly accessibility requirements.
- Corks:Natural and synthetic elastomeric plugs retain premium positioning in wine and spirits segments where oxygen ingress control determines shelf stability.
Volume concentrates in threaded formats; controlled dispensing geometries climb fastest on share expansion.
Material:
Cost tier differentiation separates commodity resin systems from metal and glass alternatives serving barrier-critical applications.
- Plastic:Polypropylene and high-density polyethylene resins dominate unit economics through lightweighting advantages and compatibility with high-speed capping equipment. California SB 54 recycled-content mandates now compel post-consumer resin certification and compatibilizer technology investment across domestic injection-molding operations.
- Metal:Aluminum roll-on and twist-off closures sustain premium positioning in food canning and wine applications where oxygen barrier properties exceed plastic capabilities. Silgan Holdings anchors metal closure supply through national canning segment relationships.
- Wood:Natural cork and wooden stopper formats serve artisanal spirits and premium cosmetic packaging where tactile differentiation supports brand positioning.
- Glass:Ground glass stoppers and precision-machined closures deliver chemical inertness for laboratory reagents and high-purity pharmaceutical applications requiring extractables minimization.
Plastic resins carry the volume base; metal formats defend the premium tier on barrier performance.
End User:
Customer type segmentation maps closure specifications to validation intensity and procurement scale.
- Beverage Industry:Carbonated soft drink, bottled water, and alcoholic beverage packagers drive standardized neck finish adoption. Midwest bottling expansion for tamper-evident formats creates localized demand surges with concentrated supplier qualification requirements.
- Food Packaging:Metal closure dominance in canning segments absorbs EPA resin emissions compliance costs through line-speed adjustments rather than capital-intensive equipment replacement.
- Pharmaceuticals:New Jersey corridor contract packagers expand sterile filling capacity for biologics, demanding precision-dispensing closures with validated seal integrity and child-resistant functionality per FDA requirements.
- Cosmetics:Precision-dispensing systems from AptarGroup serve skincare and fragrance applications where dosing accuracy and airless pump integration determine formulation stability.
Beverage procurement scales largest; pharmaceutical validation requirements expand most quickly on regulatory tightening.
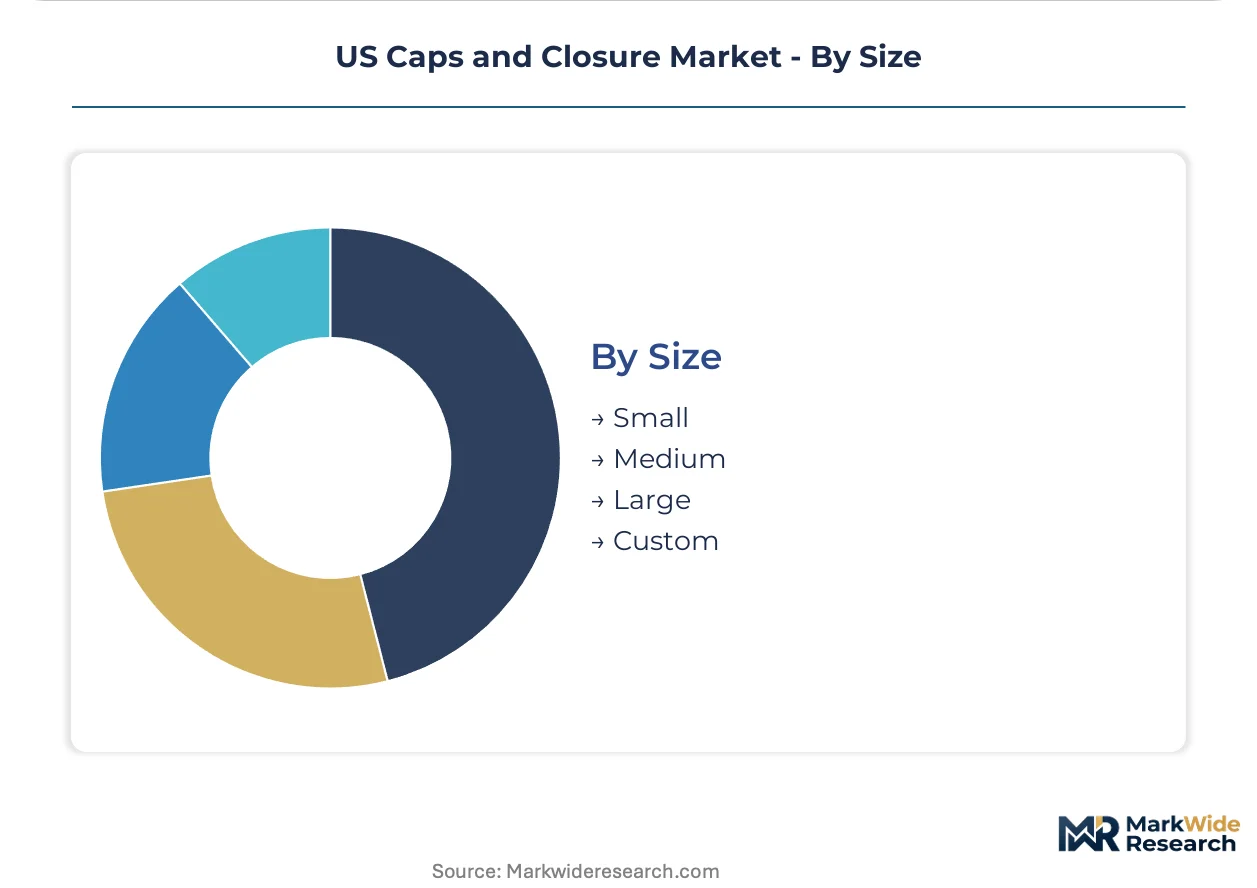
Size:
Application geometry dictates dimensional specification across containment and dispensing functions.
- Small:Vial and sample container closures for pharmaceutical and cosmetic trial formats.
- Medium:Standard beverage and food jar neck finishes comprising the majority of injection-molded volume.
- Large:Industrial and institutional containers for chemical and cleaning product applications.
- Custom:Proprietary neck finishes and dispensing geometries developed for brand differentiation and compatibility lock-in.
Medium formats command production throughput; custom specifications gain traction on private-label differentiation strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact notifications and EPA resin emissions guidelines anchor regulatory pressure across the United States, while state-level mandates in California and manufacturing expansion in the Midwest reshape supply chain geography.
California
SB 54 recycled-content mandates compel post-consumer resin certification for rigid plastic packaging. The state's environmental regulator enforces minimum thresholds that compress validation cycles for injection-molded closures. Los Angeles and Bay Area manufacturing plants invest in compatibilizer technologies to preserve market access.
Midwest
Regional beverage bottlers expand orders for tamper-evident closures with 28mm PCO neck finishes. OSHA workplace exposure limits constrain solvent-based decorating processes in Ohio and Indiana finishing operations. Michigan and Wisconsin craft brewing clusters now require documented torque testing as standard procurement terms.
New Jersey Corridor
Pharmaceutical contract packagers drive demand for precision-dispensing closures with validated seal integrity. FDA requirements for sterile filling capacity expansion tighten qualification protocols for child-resistant functionality. The corridor's biologics manufacturing concentration absorbs premium pricing for elastomeric closure systems.
Texas
Gulf Coast petrochemical capacity fluctuations transmit directly to polypropylene and high-density polyethylene feedstock costs. EPA Clean Air Act oversight affects resin emissions from regional polymer production. Houston-area distribution hubs manage inventory positioning against margin compression for high-volume screw cap producers.
Pacific Northwest
Direct-to-consumer e-commerce fulfillment networks demand leak-resistant spout caps for liquid household products. Amazon and Target distribution requirements drive specifications for last-mile durability. Seattle and Portland packaging innovation clusters test mono-material polyethylene formats with integrated induction heat-seal liners.
US Caps and Closure Market Competitive Landscape
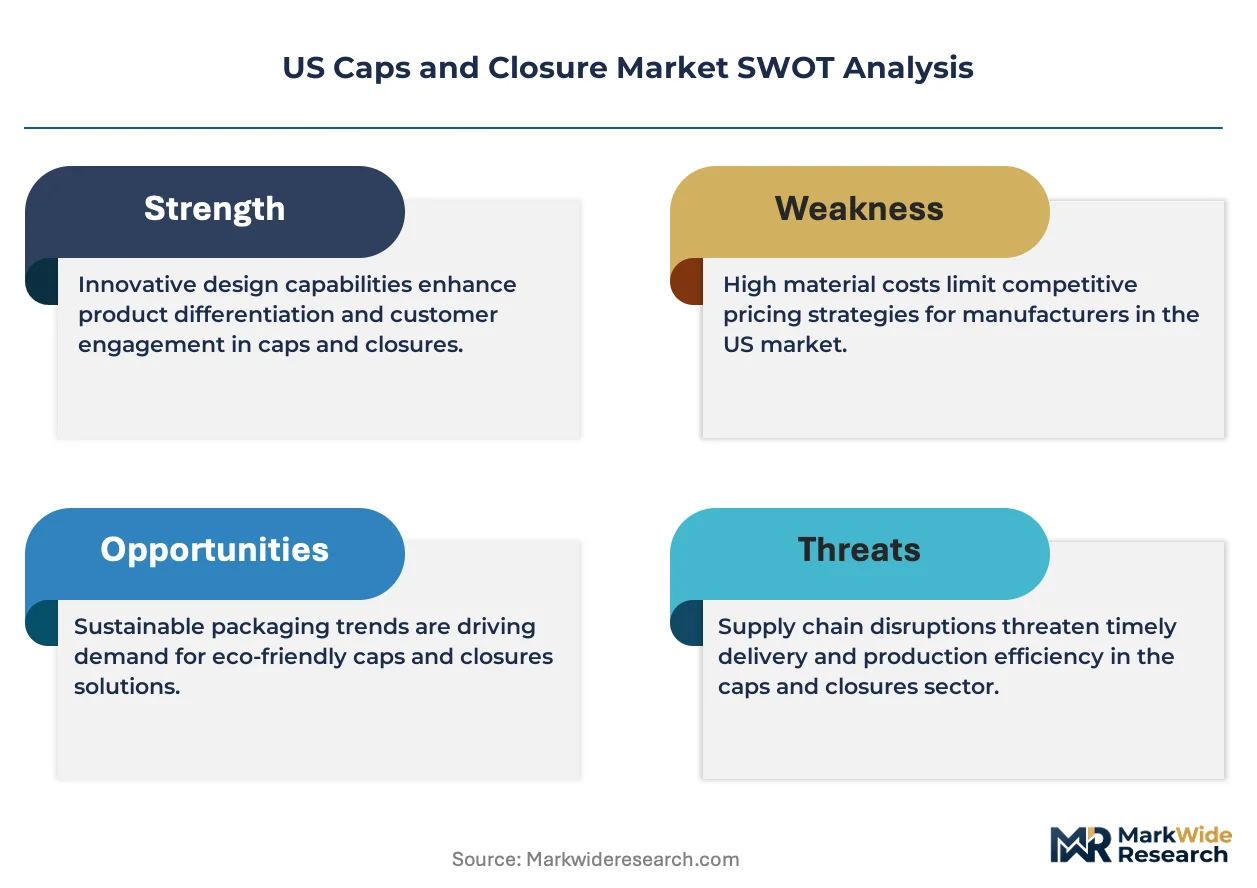
Multi-platform conglomerates and specialized component fabricators split the market along capability depth versus scale breadth. The vendor base concentrates among thermoforming operators with national beverage accounts and metal closure specialists anchored in food canning relationships. Two strategic archetypes dominate: integrated packaging conglomerates with resin-to-retail vertical control, and precision-dispensing specialists with validated cleanroom manufacturing. Competitive moves center on M&A for recycled feedstock security and strategic partnerships for bioplastics certification pathways.
Within the integrated conglomerate tier, Berry Global Group, Inc. and Silgan Holdings Inc. exemplify divergent material strategies—thermoforming scale against metal closure dominance. AptarGroup, Inc. occupies the precision-dispensing specialist position, representing the validated manufacturing archetype for pharmaceutical and cosmetic applications. These three anchors demonstrate how strategic positioning around material technology and end-use validation intensity determines competitive boundaries.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Berry Global Group, Inc. |
| Silgan Holdings Inc. |
| Closure Systems International |
| Amcor Plc |
| Crown Holdings, Inc. |
| BERICAP |
| Guala Closures Group |
| O.Berk Company |
| Others |
Value Network & Pricing Analysis
Gulf Coast petrochemical concentration anchors resin cost volatility for domestic injection-molders, compressing margin predictability and forcing tiered pricing stratification across high-volume screw cap producers serving beverage and pharmaceutical accounts.
Pricing Analysis
Midwestern manufacturing plants command 8-12% premiums over Gulf Coast equivalents due to freight absorption and torque-testing documentation requirements. Pricing stratifies across premium, standard, and economy tiers based on FDA food-contact certification status and recycled-content compliance under California SB 54. Cost compression in commodity polypropylene grades is intensifying because of propylene feedstock volatility linked to regional refinery utilization. Beverage bottlers exhibit highest price sensitivity due to direct-store-delivery consolidation, while pharmaceutical contract packagers absorb premium pricing for validated cleanroom manufacturing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing risk for specialty compatibilizers and precision mold components. Domestic supply draws from Ohio and Michigan tool shops, Gulf Coast resin producers, and New Jersey corridor pharmaceutical packaging clusters. Polypropylene pellets, high-density polyethylene resin, and induction heat-seal liners constitute critical input dependencies. Single-source vulnerability concentrates in domestic mold fabrication capacity. Distribution runs through Houston petrochemical hubs, Chicago regional distribution centers, and New Jersey pharmaceutical logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across validated pharmaceutical closure manufacturing and bioplastics certification pathways, as state-level recycled-content mandates and sterile filling capacity expansion create structurally defensible niches for specialized suppliers.
For Market Incumbents: Pre-empt resin price volatility through backward integration into Gulf Coast polymer production or captive recycling operations serving California SB 54 compliance. Secure Ohio and Michigan tool shop capacity through long-term mold fabrication partnerships to defend against 16-24 week validation bottlenecks. Anchor position through M&A for post-consumer resin certification capabilities before FDA notification timelines extend further. For New Entrants and Emerging Players: The Pacific Northwest e-commerce fulfillment corridor offers underpenetrated demand for leak-resistant spout caps serving Amazon and Target distribution requirements. Target bioplastics certification pathways through USDA BioPreferred and ASTM D6400 standards for organic food and natural personal care channels. Pursue strategic partnerships with Seattle and Portland packaging innovation clusters testing mono-material polyethylene formats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-dispensing specialists lacking validated cleanroom expansion capital for biologics manufacturing growth. Five-to-ten year viability favors suppliers with demonstrated FDA food-contact notification success and state-level recycled-content compliance infrastructure. Monitor EPA resin emissions guideline enforcement intensity as inflection indicator for digital printing and laser marking equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Certification | California SB 54 compliance preserves market access for rigid plastic packaging suppliers. |
| Cleanroom Manufacturing Scale-Up | FDA sterile filling requirements absorb premium pricing for elastomeric closure systems. |
| Digital Printing Retrofit | EPA Clean Air Act compliance eliminates solvent-based decorating processes in Midwest finishing plants. |
| Mono-Material Format Development | Integrated induction heat-seal liners reduce secondary packaging complexity for pharmaceutical oral solid dose. |
| Regional Distribution Consolidation | Direct-store-delivery beverage networks demand single-source closure-to-bottle compatibility guarantees. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with closure manufacturing executives, pharmaceutical contract packaging procurement leads, beverage bottling operations managers, and EPA compliance officers; alongside secondary validation through FDA food-contact notification databases, SEC 10-K filings of publicly traded packaging conglomerates, California Department of Resources Recycling and Recovery enforcement records, and American Chemistry Council resin production reports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Forecast inputs considered injection-molded and thermoformed volume trajectories, material substitution elasticity between plastic and metal formats, and regulatory compliance cost absorption capacity across the projection horizon. Segmentation dimensions modeled include product type geometry, resin material grade, end-use industry validation intensity, and regional manufacturing cluster concentration. CAGRs derived from historical shipment data correlation with downstream packaging demand indices and petrochemical feedstock pricing cycles.
Practitioners should monitor EPA emissions guideline enforcement intensity, FDA food-contact notification review timeline extension, and state-level extended producer responsibility legislation passage for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Crown Closures Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
PVC-Free Cap Liners Market