
 North America Plastic Caps and Closures Market | 2026-2036
North America Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Caps and Closures Market Analytics
The capital-intensity divergence between high-volume injection molders and specialty closure designers is collapsing as mid-tier competitors acquire multi-cavity tooling and automated assembly lines. Silgan Holdings Inc. leverages its captive resin compounding and metal-plastic hybrid expertise to sustain margin advantages in beverage applications. Berry Global Group Inc. anchors its position through thermoforming and injection molding scale across Midwestern US production campuses. AptarGroup Inc. differentiates via precision dispensing mechanisms for pharmaceutical and cosmetic brands.
Plastic caps and closures are threaded or snap-fit sealing devices manufactured through injection molding, compression molding, or thermoforming from thermoplastic resins, typically featuring specified torque-release thresholds, seal liner compositions, and dimensional tolerances measured in millimeters to ensure package integrity against contamination, leakage, and oxidation. Their primary commercial purpose spans containment, consumer access control, shelf-life extension, and regulatory compliance verification across packaged goods supply chains. Screw caps retain dominance in carbonated and still beverage applications where resealability and line-speed compatibility matter most, while dispensing caps capture faster expansion in personal care and household products where controlled dosing drives replacement frequency. Polypropylene occupies the largest material share due to its chemical resistance, hinge-flex durability for flip-top designs, and broad recycling code acceptance across North American municipal streams.
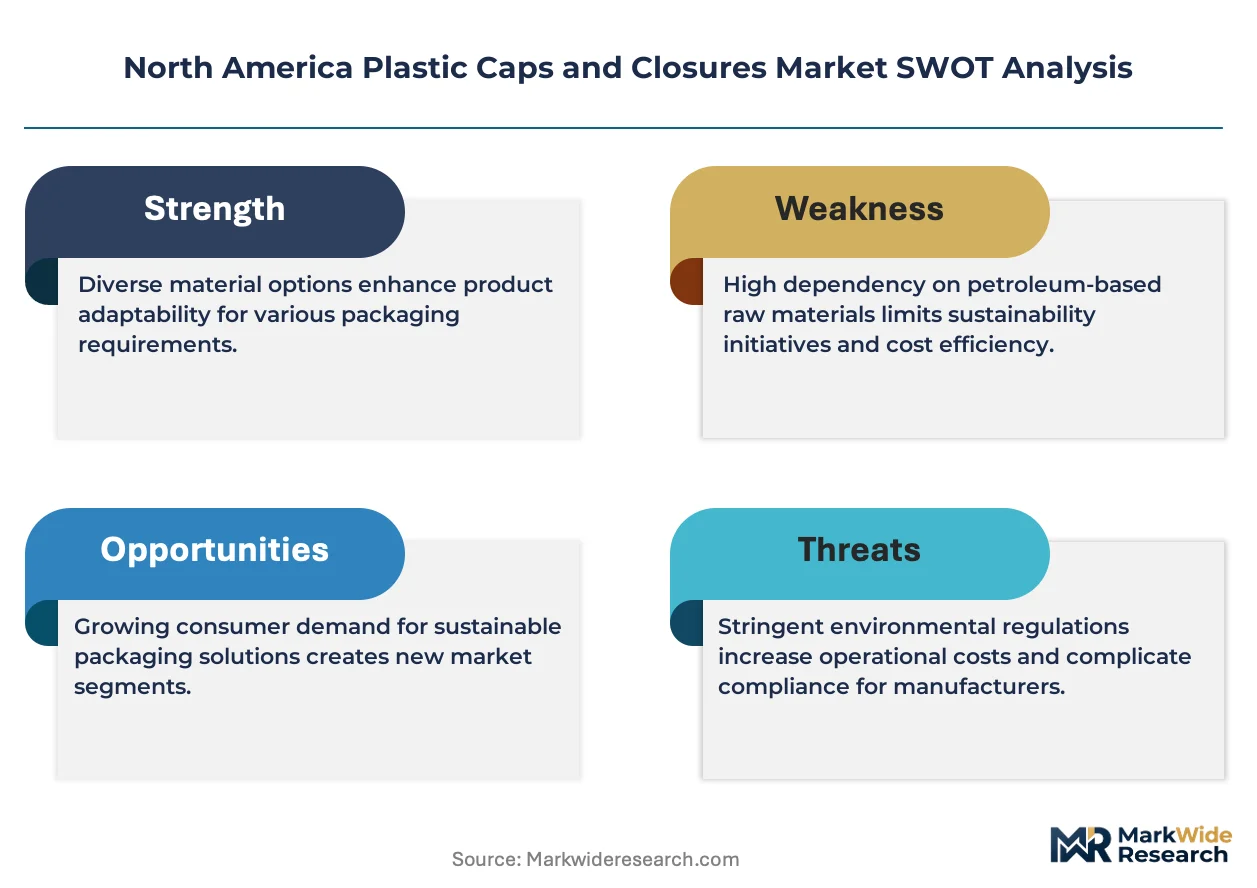
The US FDA regulates indirect food additives and closure-substance migration limits under 21 CFR, while EPA rules on resin production emissions and post-consumer recycling targets, and Canada's PMRA aligns pesticide-container closure standards with US protocols. These frameworks elevate testing documentation burdens, accelerate shifts toward mono-material recyclable designs, and restrict certain PVC applications in food contact. Stakeholders must monitor pending state-level extended producer responsibility legislation and resin price volatility to time capacity investments and material qualification programs.
Market Dynamics
Lightweight dispensing caps are compressing material throughput per unit while tamper-evident designs raise compliance documentation burdens across beverage bottling lines in Mexico and the United States.
Growth Catalysts
- 21 CFR migration limits:FDA food-contact substance rules accelerate mono-material recyclable designs that simplify municipal recycling streams across Midwestern production corridors.
- Personal care dispensing:Controlled-dose flip-top mechanisms drive replacement frequency in shampoo and lotion segments where hinge-flex durability commands premium positioning.
- Monterrey industrial parks:Northern Mexico's manufacturing clusters attract injection molding capacity to serve cross-border beverage supply chains with reduced logistics friction.
Market Restraints
- Propylene feedstock volatility:Crude-linked resin pricing compresses margin predictability for mid-tier molders lacking captive compounding capabilities.
- US Great Lakes corridor concentration:Tooling and assembly capacity clusters within a 400-mile radius, exposing bottlers to regional weather disruptions and labor pool competition.
- Multi-layer barrier limitations:Co-extruded liners containing EVOH or aluminum foil fragments complicate mechanical recycling and trigger state-level extended producer responsibility scrutiny.
Strategic Opportunities
- Canadian PMRA alignment:Pesticide-container closure standards harmonized with US protocols open cross-border agricultural chemical packaging contracts for qualified suppliers.
- Pharmaceutical precision dispensing:Metered-dose mechanisms for OTC liquids and ophthalmic solutions command technical qualification premiums beyond commodity beverage caps.
- Post-consumer recycled content mandates:Pending state legislation in California and New York creates first-mover advantage for molders with qualified rPP supply chains and FDA non-objection letters.
Industry Challenges
- Multi-cavity tooling talent scarcity:Tool and die makers with hot-runner expertise command wage premiums that inflate capital project timelines for automated assembly line deployments.
- Torque-release certification delays:ASTM D3198 and D3810 testing protocols for carbonated beverage applications extend qualification cycles, freezing design iterations until regulatory documentation clears.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Caps and Closures Market |
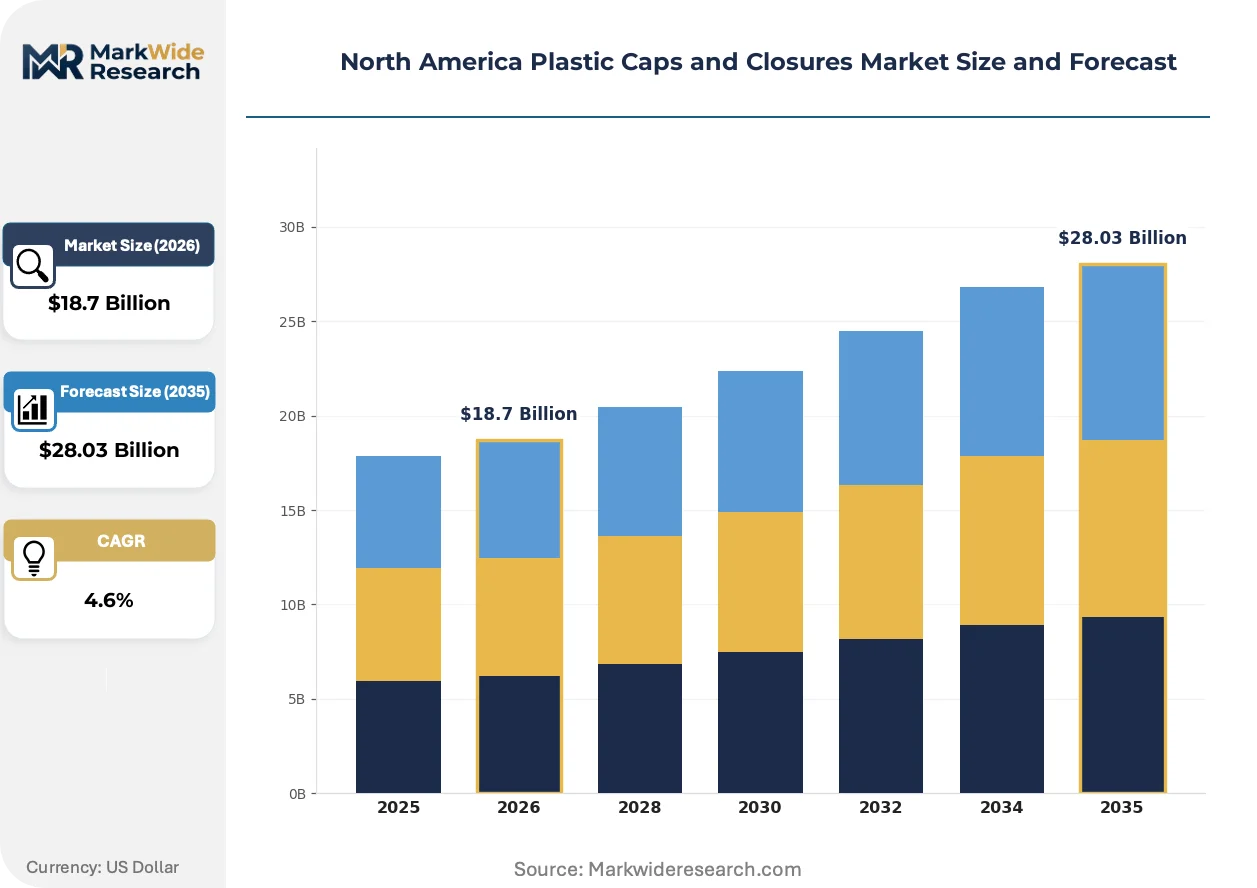
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-on Caps, Dispensing Caps, Rigid Caps Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Closure Design: Child-resistant, Tamper-evident, Non-refillable, Specialty |
| Companies Covered | Silgan Holdings Inc., Amcor PLC, AptarGroup Inc., Closure Systems International Inc., TriMas Corporation, Berry Global Group Inc., Sonoco Products Company, Crown Holdings Inc., Phoenix Closures Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Caps and Closures Market Evolving Landscape
Material substitution and regulatory compression are reconfiguring competitive advantage away from pure scale toward recyclability certification and dispensing precision.
Mono-material polypropylene constructions with integrated living hinges are supplanting multi-component assemblies in personal care and household product categories. Unilever and Procter & Gamble procurement teams now specify single-resin designs for 70% of new SKU launches. This shift collapses disassembly requirements and streamlines curbside recycling acceptance across fragmented North American municipal systems.
EPA resin production emission rules under the Clean Air Act tighten volatile organic compound thresholds for polypropylene and polyethylene manufacturing facilities. The industrial consequence forces compounders to retrofit thermal oxidizers or relocate capacity to permitted greenfield sites. Food-contact closure producers face the steepest compliance costs, as their documentation trails must satisfy both EPA source rules and FDA indirect additive limits simultaneously.
Beverage bottlers now consolidate supplier panels from twelve-plus vendors to four preferred partners with full-service design, tooling, and logistics capabilities. This concentration eliminates spot-buying flexibility but secures capacity allocation during resin shortage periods. The pattern is most visible in the United States, where Coca-Cola and PepsiCo bottling networks have completed supplier rationalization programs across their Midwestern and Southwestern territories.
North America Plastic Caps and Closures Market Segmentation
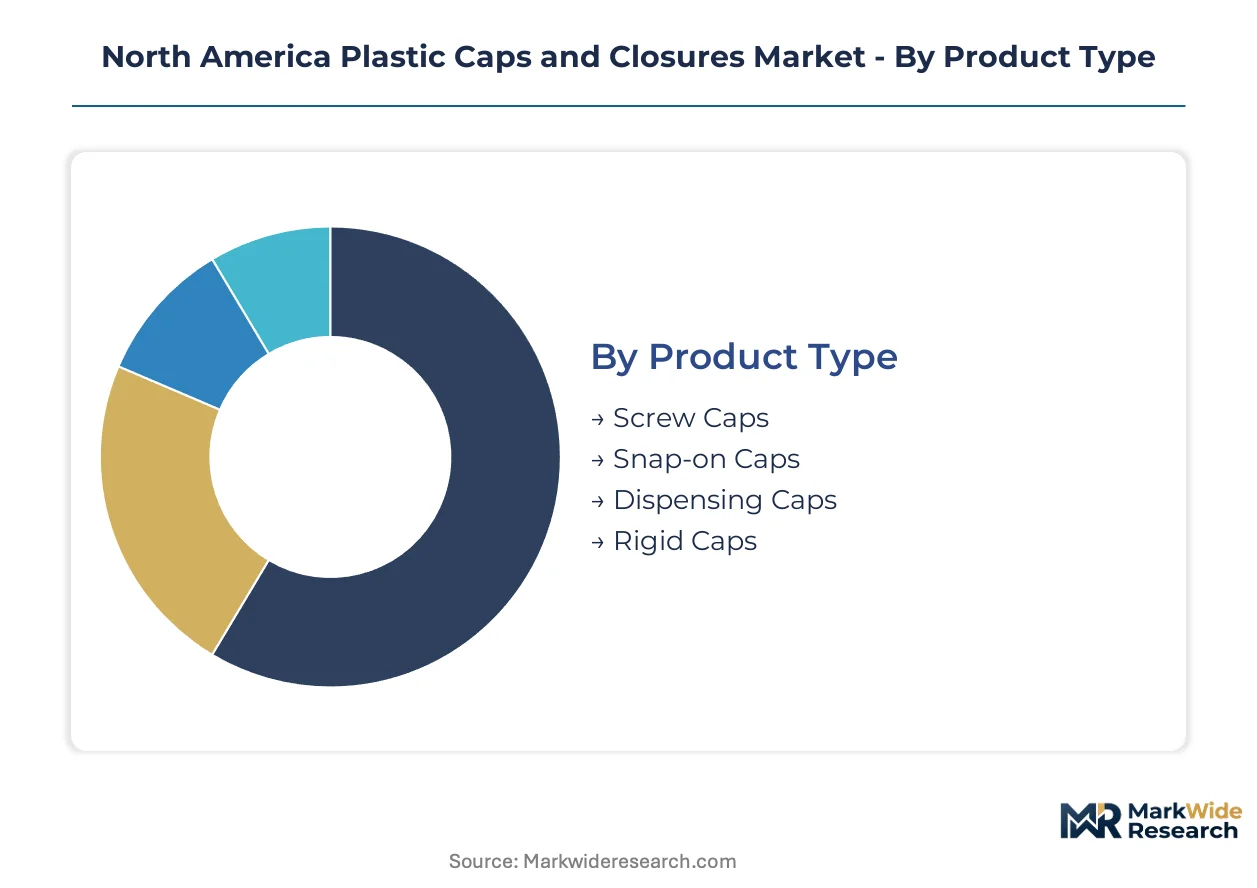
Segmentation in North American plastic caps and closures reveals how torque specifications, resin selection, and regulatory compliance requirements fragment procurement strategies across beverage bottlers, pharmaceutical packagers, and personal care manufacturers. Understanding these divisions exposes where tooling investments concentrate and which material streams face recycling infrastructure constraints.
Product Type:
Screw caps dominate domestic beverage production lines across the US Great Lakes corridor, while dispensing caps drive export-oriented growth from Monterrey industrial parks serving cross-border personal care supply chains.
- Screw Caps:Threaded closures with specified torque-release thresholds measured in inch-pounds, typically molded from polypropylene homopolymer for carbonated beverage applications. Midwestern US bottlers favor these for line-speed compatibility with existing capping equipment, though lightweighting initiatives are compressing gram-weight specifications and challenging seal integrity margins.
- Dispensing Caps:Flip-top and push-pull mechanisms integrating living hinges with defined flex-cycle durability, commanding premium positioning in shampoo and lotion segments. Northern Mexico's manufacturing clusters specialize in these designs for export to US personal care brands, where controlled dosing drives higher replacement frequency and recurring revenue streams.
- Snap-on Caps:Compression-fit closures eliminating threaded engagement, common in single-serve dairy and juice applications where resealability is secondary to cost minimization.
- Rigid Caps:Non-flexible sealing devices for industrial chemical containers requiring dimensional stability under stack-load pressures.
Screw caps hold the largest share; momentum sits with dispensing caps.
Material:
Resin selection divides along FDA food-contact certification requirements versus EPA emission compliance burdens, with polypropylene commanding premium positioning and polyethylene serving cost-sensitive volume applications.
- Polypropylene:Semi-crystalline thermoplastic with hinge-flex durability for flip-top designs and broad recycling code acceptance across North American municipal streams. US FDA indirect additive limits under 21 CFR favor this resin for beverage applications, though propylene feedstock volatility compresses margin predictability for molders lacking captive compounding.
- Polyethylene:Lower-density alternative for snap-fit closures where chemical resistance requirements are moderate. Canadian agricultural chemical packagers favor HDPE for pesticide containers aligned with PMRA standards harmonized to US protocols, creating cross-border contract opportunities.
- PVC:Restricted in food-contact applications by FDA migration limits, retained primarily for industrial closures where cost minimization outweighs recyclability concerns.
- PET:Crystal-clear resin for cosmetic and pharmaceutical applications requiring visual content inspection, though mechanical recycling complications limit post-consumer stream acceptance.
Polypropylene anchors revenue concentration; PET is expanding most quickly in pharmaceutical precision dispensing.
End User:
Demand concentration splits between high-volume beverage bottlers pursuing supplier consolidation and specialty pharmaceutical packagers requiring metered-dose qualification documentation.
- Food & Beverage:Carbonated soft drink and bottled water applications driving screw cap standardization, with Coca-Cola and PepsiCo bottling networks completing supplier rationalization programs across Midwestern and Southwestern US territories.
- Pharmaceuticals:OTC liquid and ophthalmic solution packaging requiring ASTM D3198 torque-release certification and child-resistant mechanism compliance.
- Cosmetics:Premium skincare and fragrance segments where dispensing precision and aesthetic finish command technical qualification premiums.
- Household Products:Bleach and cleaning chemical containers where chlorine resistance and non-refillable designs dominate procurement specifications.
Food & Beverage generates the highest unit volumes; Pharmaceuticals delivers the steepest expansion trajectory.
Closure Design:
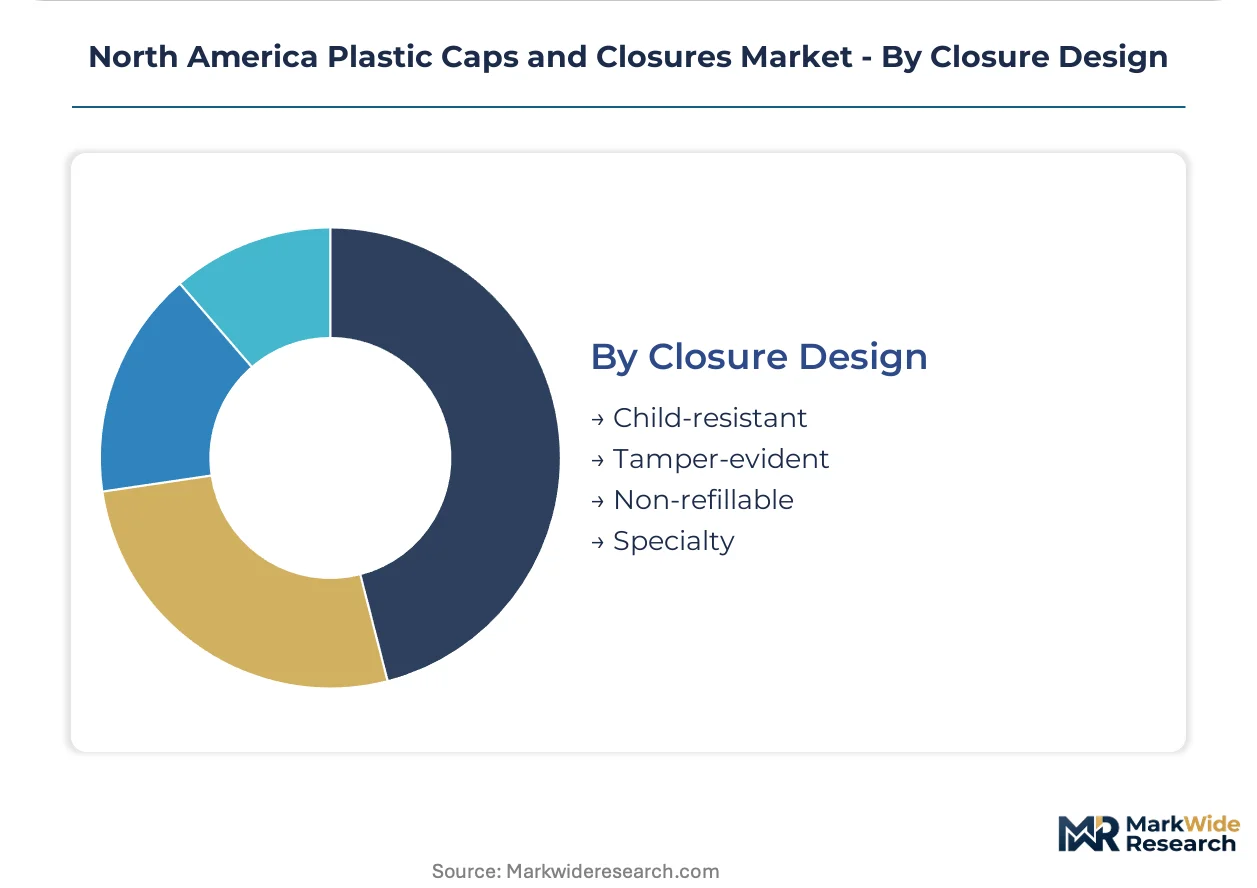
Regulatory compliance burdens differentiate tamper-evident and child-resistant designs from commodity sealing functions, with documentation requirements extending qualification cycles.
- Tamper-evident:Break-ring or shrink-band integrated designs satisfying FDA food safety protocols and EPA pesticide container standards, now mandatory for beverage and agricultural chemical applications across US and Canadian jurisdictions.
- Child-resistant:Push-and-turn or squeeze-and-turn mechanisms for pharmaceutical and household chemical segments, requiring US Consumer Product Safety Commission protocol testing.
- Non-refillable:One-way valve designs preventing container reuse for regulated substances, common in automotive fluid and agricultural chemical packaging.
- Specialty:Custom-engineered mechanisms for medical devices and diagnostic reagents where precision dosing or sterile barrier functions override cost considerations.
Tamper-evident designs command the broadest regulatory mandate; specialty closures are gaining share fastest in medical device packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border resin flows and finished closure exports define North America's trade position, with Mexican manufacturing parks supplying US bottlers while Canadian compounders feed Great Lakes molders. Regional integration compresses lead times but concentrates weather and labor risks in shared corridors.
United States
Beverage bottlers in the Great Lakes corridor drive screw cap standardization for carbonated applications. FDA migration limits under 21 CFR accelerate mono-material qualification programs across Midwestern production campuses. Chicago and Detroit anchor injection molding clusters where Silgan Holdings and Berry Global operate multi-cavity tooling facilities.
Mexico
Lightweight dispensing cap demand from personal care exporters fuels capacity expansion in northern industrial parks. EPA-aligned environmental permits for polypropylene compounding attract cross-border investment near Monterrey. Nuevo León's manufacturing zones specialize in flip-top mechanisms for US-bound shampoo and lotion supply chains.
Canada
Agricultural chemical packagers leverage PMRA standards harmonized with US protocols to capture cross-border contract opportunities. Health Canada food-contact regulations mirror FDA indirect additive limits, simplifying qualification for Ontario-based molders. Toronto and Montreal corridors concentrate HDPE closure production for pesticide container applications.
North America Plastic Caps and Closures Market Competitive Landscape
Concentration sits with diversified packaging conglomerates holding captive resin compounding and multi-cavity tooling capabilities. The vendor base splits between high-volume beverage specialists and precision dispensing designers serving pharmaceutical and cosmetic brands. Strategic archetypes include integrated resin-to-closure operators, precision mechanism specialists, and regional logistics optimizers. Competitive moves center on supplier panel consolidation by major bottlers and automated assembly line deployment to offset labor scarcity.
Among North American packaging conglomerates, Silgan Holdings Inc., Berry Global Group Inc., and AptarGroup Inc. exemplify the three dominant competitive positions. Silgan occupies the integrated operator archetype through captive resin capabilities and metal-plastic hybrid expertise. Berry Global anchors scale-driven thermoforming and injection molding across Midwestern production networks. AptarGroup represents the precision dispensing specialist tier, with mechanism design credentials qualifying it for pharmaceutical and cosmetic technical specifications. These three structures—vertical integration, manufacturing scale, and precision engineering—define the competitive vectors that mid-tier competitors must match through multi-cavity tooling acquisition or automated assembly investment.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Amcor PLC |
| AptarGroup Inc. |
| Closure Systems International Inc. |
| TriMas Corporation |
| Berry Global Group Inc. |
| Sonoco Products Company |
| Crown Holdings Inc. |
| Phoenix Closures Inc. |
| Others |
Value Network & Pricing Analysis
Long-term resin offtake agreements between polypropylene compounders and Midwestern injection molders lock in feedstock access and compress margin volatility for beverage closure suppliers operating across the US Great Lakes corridor.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures with volume-scaled tiering. Three-tier pricing separates FDA-certified food-contact grades from standard industrial specifications and economy non-refillable designs. Cost compression in commodity screw caps is intensifying because propylene feedstock volatility transfers downstream to molders lacking captive compounding. Brand owners with consolidated supplier panels exhibit lowest price sensitivity; spot-buying regional bottlers face steepest margin pressure.
Supply Chain Analysis
Strategic stockpiling of polypropylene resin prevails among tier-one molders buffering against propylene price spikes, while just-in-time raw material flows dominate mid-tier competitors with thinner working capital. Supply concentrates in the United States, Mexico, and Canada, with Nuevo León industrial parks feeding cross-border personal care demand. The chain draws from crude-linked propylene monomer, hot-runner tooling components, and seal liner adhesives. Single-source vulnerability sits with specialized hot-runner systems from European tooling houses. Distribution runs through direct ship-to-line arrangements with major bottlers and regional distributor networks serving smaller personal care packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supplier consolidation by Coca-Cola and PepsiCo bottling networks fragments procurement access, creating niches for specialized dispensing cap designers and rPP-qualified molders serving sustainability-focused brand owners.
For Market Incumbents: Compound defensive positioning through backward integration into captive resin compounding and automated assembly line deployment across Monterrey industrial parks. Silgan Holdings and Berry Global anchor scale advantages that emerging competitors must match through multi-cavity tooling acquisition. Threat from pharmaceutical precision dispensing specialists like AptarGroup encroaching on beverage applications demands counter-investment in metered-dose mechanism R&D. For New Entrants and Emerging Players: FDA non-objection letter fast-tracks for post-consumer recycled polypropylene unlock first-mover positioning in California and New York compliance markets. White-space targets include pharmaceutical OTC liquid dispensing and agricultural chemical closures aligned with Canadian PMRA standards. Go-to-market through co-development partnerships with sustainability-focused personal care brands accelerates qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap molders with qualified rPP supply chains and hot-runner tooling expertise across the analysis window. Acquisition archetype: regional injection specialists with FDA food-contact certification and untapped capacity in northern Mexico. Signal to watch: state-level extended producer responsibility legislation triggering mandatory recycled content thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply shields margin compression from crude-linked feedstock volatility. |
| Automated Assembly Line Deployment | Multi-cavity tooling with robotic handling offsets wage premiums for scarce tool-and-die talent. |
| rPP Supply Chain Qualification | FDA non-objection letters for post-consumer recycled content secure positioning in pending state mandates. |
| Precision Dispensing Mechanism R&D | Metered-dose expertise commands technical qualification premiums in pharmaceutical and cosmetic segments. |
| Cross-Border Manufacturing Expansion | Monterrey industrial park capacity reduces logistics friction for US-bound personal care exporters. |
Research Methodology
A spread of perspectives from injection molding plant managers, beverage bottler procurement leads, personal care brand supply planners, and resin compounding technical directors converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 21 CFR filings, EPA Clean Air Act enforcement records, SEC 10-K disclosures by packaging conglomerates, and Canadian PMRA pesticide container standards. Bottom-up capacity modeling across Midwestern US and northern Mexican production corridors triangulated against top-down demand aggregation by end-use segment.
Segmentation dimensions modeled include product type, resin material, closure design, end-use industry, and geographic production cluster across the projection horizon. CAGRs derive from volume-outcome modeling tied to resin price elasticity, supplier consolidation patterns, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate propylene feedstock futures curves and state-level extended producer responsibility legislative tracking.
Underlying assumptions cover stable FDA migration limit enforcement and propylene supply continuity, with deviation risk concentrated in feedstock price spikes and hot-runner tooling delivery delays. Revision becomes warranted when recycled content mandate thresholds or EPA emission rule stringency crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
End Cap Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Spout Closures Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Box Latch Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Vietnam Plastic Caps and Closures Market