
 Respirator Fit Tester Market | 2026-2036
Respirator Fit Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Respirator Fit Tester Market Outlook
Certified industrial hygienist shortages is bifurcating the market between automated self-service platforms and technician-dependent service models. TSI Incorporated leverages its optical measurement expertise to sustain leadership in quantitative fit testing instrumentation. MSA Safety Incorporated anchors its position through integrated respiratory protection ecosystems that bundle fit testers with supplied-air systems. Occupational Health Dynamics competes via specialized service networks targeting mid-sized manufacturing facilities lacking in-house safety expertise.
A respirator fit tester is a device that measures the seal integrity between a respirator facepiece and the wearer's facial skin, typically employing particle counting, pressure differential, or aerosol detection methods to calculate a quantitative fit factor. Its primary purpose is verifying that tight-fitting respirators achieve the minimum protective performance required by occupational health mandates before hazardous exposure. Quantitative systems command the dominant share of product type revenue due to their defensible documentation for regulatory audits, while hybrid systems represent the fastest-growing segment as vendors combine optical measurement with pressure differential sensing in single units. Workplace safety applications generate the largest usage scenario volume, though medical facilities are expanding fastest as post-pandemic hospital preparedness programs institutionalize annual fit testing requirements.
OSHA's Respiratory Protection Standard (29 CFR 1910.134) mandates annual fit testing for all tight-fitting respirator wearers, directly sustaining replacement demand for testing consumables and calibration services. The FDA's oversight of N95 respirators for healthcare use intersects with CDC guidelines requiring fit verification before clinical deployment, creating dual compliance pressure on hospital procurement. Stakeholders must monitor whether NIOSH updates its fit test protocol specifications to accommodate emerging elastomeric respirator designs, as such revisions would force instrument recertification and open replacement cycles.
Market Dynamics
OSHA's updated respiratory protection standards are compressing fit testing cycles across US healthcare systems, forcing hospitals to replace qualitative methods with quantitative instrumentation that generates auditable compliance records.
Growth Catalysts
- 29 CFR 1910.134:OSHA's annual fit testing mandate sustains replacement demand for calibration services and testing consumables in manufacturing facilities.
- Healthcare preparedness programs:Post-pandemic hospital systems are institutionalizing annual fit testing requirements, expanding quantitative system deployments.
- Optical measurement:Advances in particle counting technology enable faster test cycles, reducing labor costs per employee screened.
Market Restraints
- Certified industrial hygienist scarcity:Technician shortages constrain service model scalability, pushing buyers toward automated platforms with higher upfront capital requirements.
- Instrument calibration dependencies:NIOSH protocol specifications require periodic recertification, creating recurring compliance friction for equipment owners.
- Elastomeric respirator design divergence:Emerging facepiece geometries risk obsoleting existing test fixtures before full depreciation cycles complete.
Strategic Opportunities
- Mid-sized manufacturing:Facilities lacking in-house safety expertise represent underserved demand for specialized service networks and outsourced testing programs.
- Hybrid system convergence:Combining optical measurement with pressure differential sensing in single units addresses multi-protocol compliance needs.
- Industrial manufacturer bundling:Integrated respiratory protection ecosystems that pair fit testers with supplied-air systems capture higher lifetime customer value.
Industry Challenges
- Technician training pipelines:The gap between certified industrial hygienist supply and employer testing volume requirements is widening, compressing service availability.
- Legacy system integration:Hospitals with existing qualitative protocols face workflow disruption when migrating to quantitative platforms requiring IT connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respirator Fit Tester Market |
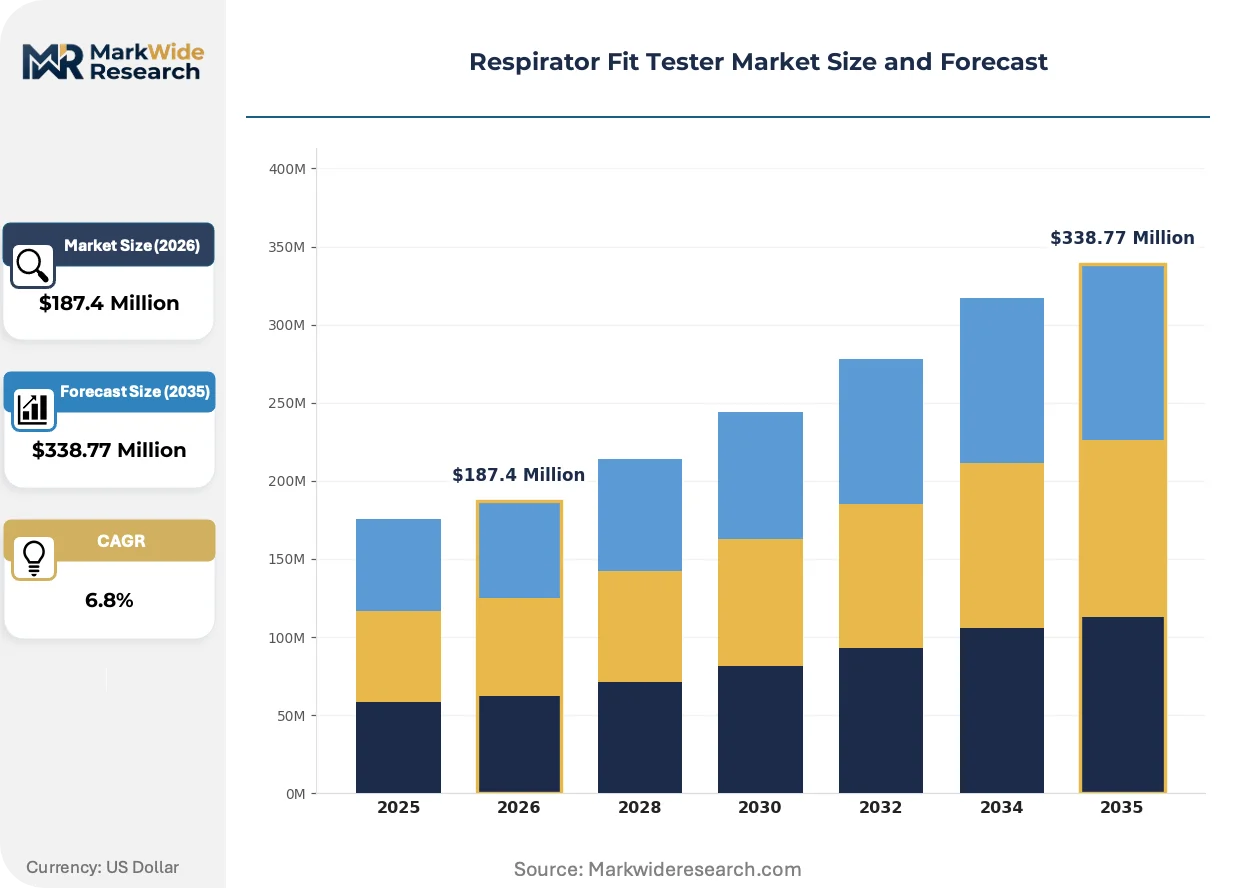
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantitative Systems, Qualitative Systems, Hybrid Systems, Accessories Usage Scenario: Workplace Safety, Medical Facilities, Construction Sites, Research Laboratories Technology: Optical Measurement, Pressure Differential, Acoustic Measurement, Respiratory Simulation End User: Healthcare Providers, Industrial Manufacturers, Government Agencies, Educational Institutions |
| Companies Covered | 3M Company, TSI Incorporated, Occupational Health Dynamics, Honeywell International Inc., MSA Safety Incorporated, Moldex-Metric Inc., Allegro Industries, AccuTec-IHS Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respirator Fit Tester Market Strategic Shifts
Portable fit testing hardware is compressing the addressable market for centralized testing facilities, enabling point-of-use deployment in manufacturing floor environments.
Condensation nuclei counting technology is miniaturizing. These particle detection systems now fit handheld enclosures previously requiring cart-mounted instrumentation. Automotive and aerospace manufacturers are adopting portable units for on-floor testing during shift changes. The technology is miniaturizing compliance infrastructure, eliminating dedicated testing room requirements and reducing per-site capital deployment by half.
CDC guidelines for N95 fit verification in healthcare settings are tightening documentation standards. The policy mandates recordable fit factors before clinical deployment, disqualifying subjective qualitative methods. Hospital procurement teams are responding by specifying quantitative systems with automated data logging for Joint Commission audits.
Buying patterns are consolidating around multi-year service contracts that bundle hardware, calibration, and technician dispatch. Mid-sized manufacturers lacking internal safety departments are displacing transactional equipment purchases with subscription models. This shift is most visible in the Midwest industrial corridor, where staffing constraints make in-house certification unsustainable.
Respirator Fit Tester Market Segmentation
Respirator fit tester procurement channels diverge sharply by segment. Hospital systems route quantitative systems through GPO contracts, while industrial buyers favor direct manufacturer relationships for service bundling.
Product Type:
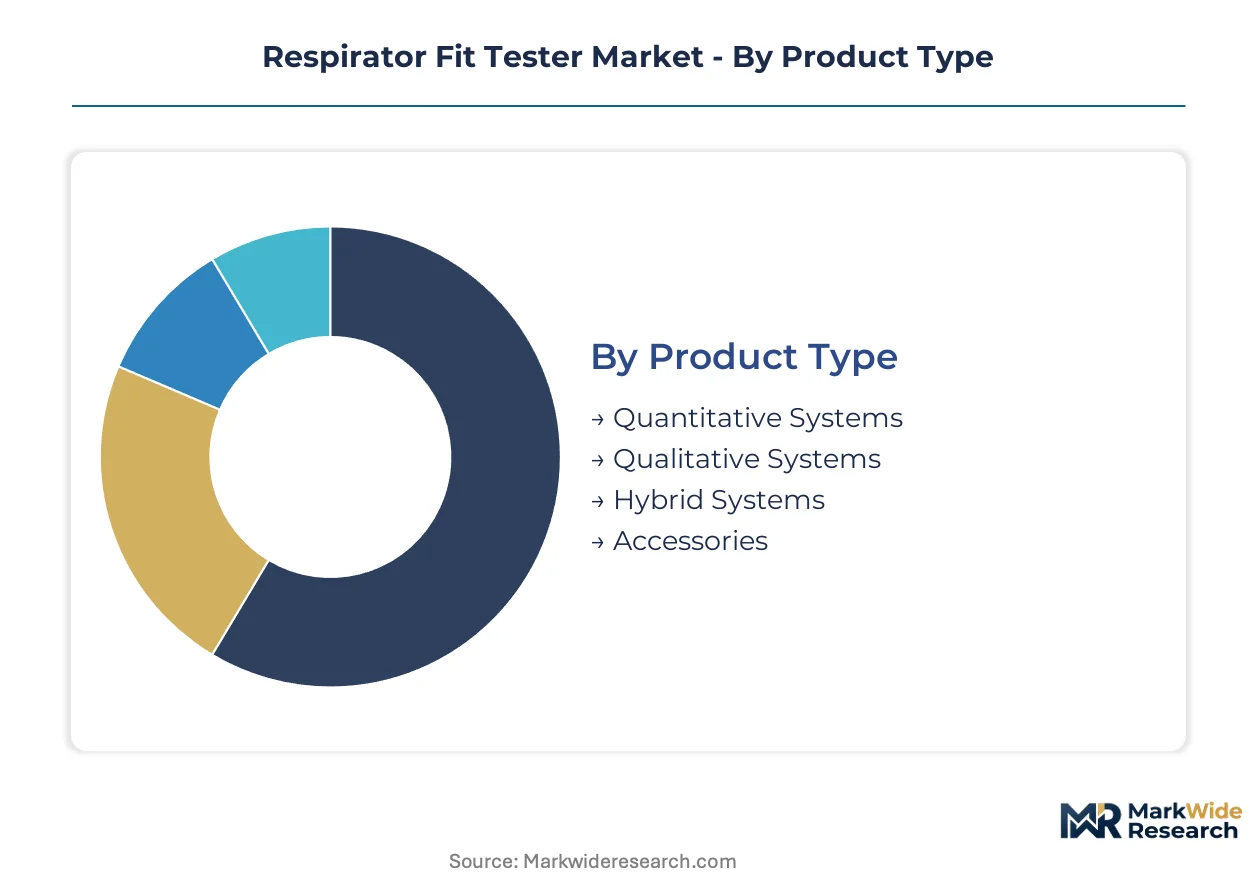
Channel mix varies dramatically: quantitative systems flow primarily through safety distributors with calibration service attachments, qualitative systems through industrial supply catalogs, and hybrid systems via direct OEM sales with multi-year maintenance agreements.
- Quantitative Systems:These instruments employ particle counting or aerosol detection to calculate numerical fit factors with objective, recordable outputs. Demand concentrates in US hospital systems following OSHA's updated respiratory protection standards that mandate auditable compliance documentation. The systems command premium positioning through defensible data for Joint Commission audits.
- Hybrid Systems:Single units combine optical measurement with pressure differential sensing to address multi-protocol compliance needs. Automotive and aerospace manufacturers in Michigan and Ohio are adopting these for flexible floor deployment. The convergence eliminates redundant capital expenditure for facilities managing diverse respirator inventories.
- Qualitative Systems:Subjective methods relying on wearer sensory detection of test agents.
- Accessories:Testing consumables, replacement probes, and calibration reference materials.
By volume, quantitative systems lead. By growth pace, hybrid systems are expanding most quickly.
Usage Scenario:
Cost tier stratification separates high-compliance medical deployments from price-sensitive construction applications. Medical facilities absorb 3-4x per-unit expenditure for automated documentation capabilities that construction contractors reject.
- Workplace Safety:Manufacturing floor programs with high employee turnover require rapid throughput. Midwest automotive plants deploy portable condensation nuclei counters for shift-change testing without dedicated rooms.
- Medical Facilities:Post-pandemic hospital preparedness programs institutionalize annual fit testing with IT-integrated quantitative platforms. The CDC's N95 verification guidelines disqualify qualitative methods, forcing capital replacement cycles.
- Construction Sites:Mobile workforces favor disposable qualitative kits over capital equipment investment.
- Research Laboratories:Biosafety level facilities require validated protocols with traceable documentation chains.
Workplace safety generates the largest absolute volume. Medical facilities show the steepest expansion trajectory.
Technology:
Application requirements dictate technology selection. Pharmaceutical cleanrooms specify optical particle counting for sensitivity, while firefighter training centers prioritize pressure differential for full-facepiece elastomeric testing.
- Optical Measurement:Condensation nuclei counting technology miniaturizes into handheld enclosures previously requiring cart-mounted instrumentation. The advances compress per-site capital deployment by half.
- Pressure Differential:Measures seal integrity through controlled pressure decay rates. Fire service applications in Texas and California specify this method for SCBA facepiece validation.
- Acoustic Measurement:Emerging ultrasonic detection methods for real-time seal monitoring during wear.
- Respiratory Simulation:Advanced manikin-based testing for respirator design validation rather than individual fit verification.
Optical measurement dominates current installed base. Pressure differential is gaining share fastest in industrial safety applications.
End User:
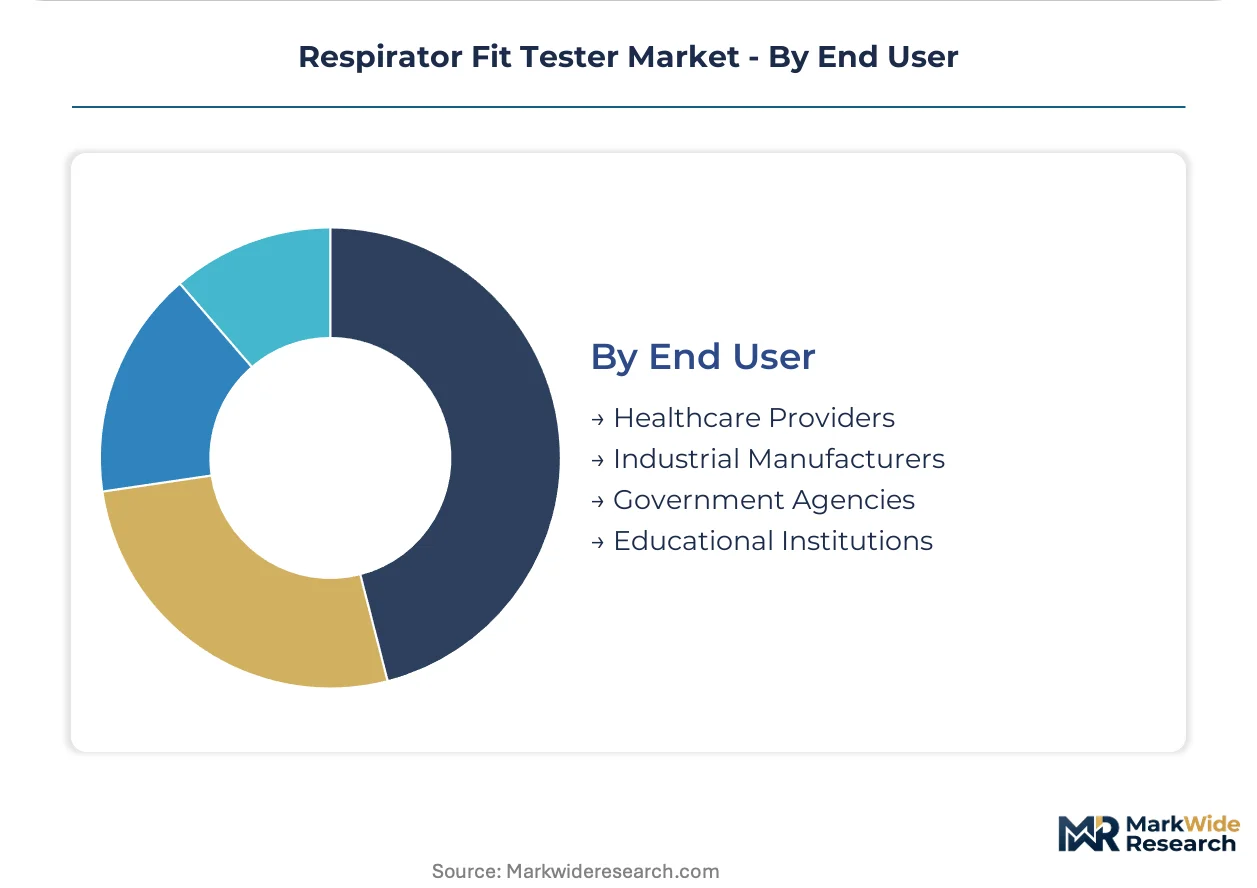
Customer type determines procurement modality. Healthcare providers consolidate through group purchasing organizations, while government agencies mandate competitive bidding with domestic content preferences.
- Healthcare Providers:Hospital networks in New York, California, and Texas are expanding quantitative fit testing programs. OSHA compliance audits and Joint Commission accreditation drive specification of systems with automated data logging.
- Industrial Manufacturers:Automotive and chemical processors in the Gulf Coast region favor bundled service contracts covering hardware, calibration, and technician dispatch.
- Government Agencies:Federal procurement specifications require NIOSH protocol compliance with periodic recertification documentation.
- Educational Institutions:University research programs with biosafety committees require validated fit testing for laboratory personnel.
Industrial manufacturers represent the largest customer base by unit volume. Healthcare providers are climbing the fastest on compliance mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States deploy quantitative systems for OSHA compliance documentation, while industrial buyers in Germany favor bundled service contracts integrating calibration and technician dispatch. This consumption-mix differential separates medical regulatory documentation priorities from manufacturing workflow efficiency optimization.
United States
Healthcare providers in New York, California, and Texas are expanding quantitative fit testing programs following OSHA's updated respiratory protection standards. The CDC's N95 verification guidelines disqualify qualitative methods, forcing capital replacement cycles in hospital procurement. Midwest automotive plants in Michigan and Ohio deploy portable condensation nuclei counters for shift-change testing without dedicated rooms.
Germany
Industrial manufacturers in Bavaria and North Rhine-Westphalia favor bundled service contracts covering hardware, calibration, and technician dispatch. REACH compliance protocols for chemical processors mandate documented fit verification for elastomeric respirator deployments. Stuttgart's automotive engineering cluster specifies hybrid systems combining optical measurement with pressure differential sensing for multi-protocol flexibility.
China
Manufacturing facilities in the Yangtze River Delta and Pearl River Delta are adopting automated self-service platforms to address certified technician shortages. GB standards for occupational respiratory protection are tightening documentation requirements for industrial safety audits. Shenzhen's electronics assembly corridor is deploying portable fit testing hardware for point-of-use floor deployment.
Japan
Pharmaceutical cleanrooms in the Kanto region specify optical particle counting for sensitivity in biosafety level applications. METI guidelines for manufacturing workplace safety are accelerating quantitative system adoption among precision equipment producers. Osaka's chemical processing cluster requires validated protocols with traceable documentation chains for regulatory submission.
United Kingdom
Hospital networks in London and the Southeast are consolidating quantitative system procurement through NHS supply chain frameworks. HSE regulations for healthcare respiratory protection align with tightened documentation standards post-pandemic. Manchester's research university cluster requires validated fit testing for laboratory personnel under biosafety committee oversight.
Respirator Fit Tester Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the respirator fit tester market. The upper tier commands premium positioning through bundled respiratory protection ecosystems and multi-year service contracts. Specialist competitors occupy niche positions in portable hardware, calibration services, and outsourced testing programs for mid-sized facilities. Consolidation pressure is intensifying as M&A activity absorbs regional service networks, while technology licensing agreements spread optical measurement capabilities across second-tier instrumentation vendors.
Within the integrated systems tier, 3M Company and Honeywell International Inc. exemplify the bundled ecosystem approach, while TSI Incorporated anchors the precision instrumentation specialist position. These three represent distinct competitive archetypes: diversified industrial conglomerates leveraging cross-product respiratory portfolios, and focused measurement technology developers sustaining leadership in quantitative fit factor calculation. MSA Safety Incorporated occupies a position between these poles, integrating supplied-air systems with fit testing capabilities.
| Leading Market Players |
|---|
| 3M Company |
| TSI Incorporated |
| Occupational Health Dynamics |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Moldex-Metric Inc. |
| Allegro Industries |
| AccuTec-IHS Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at optical sensor foundries in the United States and Germany shapes both component availability floors and system pricing tiers, concentrating bargaining power with vendors who have secured multi-year silicon allocations.
Pricing Analysis
Long-term service contracts dominate procurement for mid-sized manufacturers lacking in-house safety expertise, while spot purchases persist in construction and mobile workforce segments. Three-tier pricing structure across premium, standard, and economy levels separates NIOSH-certified quantitative systems with automated data logging from basic qualitative kits and portable condensation nuclei counters. Cost compression in the standard tier is intensifying because hybrid system vendors are converging optical and pressure differential capabilities in single units. Hospital systems in New York and California show the least price sensitivity, absorbing premium positioning for Joint Commission audit defensibility.
Supply Chain Analysis
The United States anchors precision optical component fabrication for particle counting sensors, while China and Malaysia concentrate printed circuit board assembly and handheld enclosure manufacturing. German suppliers in Bavaria control pressure differential transducer production for elastomeric facepiece validation systems. Silicon photodetector supply draws from Taiwan and South Korea, creating single-source vulnerability for condensation nuclei counting modules. Distribution runs through safety equipment distributors with calibration service attachments for quantitative systems, direct OEM sales for hybrid platforms, and industrial supply catalogs for qualitative consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as bundled respiratory protection ecosystems displace standalone instrument sales, with interoperability between fit testers and supplied-air systems becoming the primary customer lock-in mechanism.
For Market Incumbents: Secure multi-year calibration service contracts with Midwest automotive manufacturers before automated self-service platforms achieve technical parity. Deepen backward integration into optical sensor production to insulate margins from silicon photodetector allocation constraints. Defend against emerging portable hardware specialists by accelerating IT connectivity features that embed quantitative systems into hospital procurement workflows.
For New Entrants and Emerging Players: Differentiate on technician-dispatch service models for mid-sized chemical processors in the Gulf Coast region where certified industrial hygienist scarcity constrains incumbent scalability. Target construction contractor segments with subscription-based portable hardware programs that displace capital expenditure with per-test operational models. Penetrate through direct sales partnerships with regional safety distributors lacking quantitative system expertise.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid system specialists with converged optical-pressure differential architectures over pure-play quantitative instrument vendors facing commoditization pressure. Long-term viability rests on regulatory compliance automation capabilities that integrate with hospital IT infrastructure and manufacturing ERP systems. Watch for NIOSH protocol specification revisions accommodating elastomeric respirator designs as the signal triggering replacement cycle acceleration and vendor recertification costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Convergence | Combining optical measurement with pressure differential sensing addresses multi-protocol compliance needs in automotive and aerospace manufacturing clusters. |
| Service Contract Bundling | Multi-year agreements covering hardware, calibration, and technician dispatch capture lifetime customer value from mid-sized manufacturers lacking internal safety departments. |
| Portable Hardware Miniaturization | Condensation nuclei counting technology in handheld enclosures enables point-of-use deployment without dedicated testing rooms, compressing per-site capital requirements. |
| IT Connectivity Integration | Automated data logging capabilities satisfy Joint Commission audit requirements and embed quantitative systems into hospital procurement workflows. |
| Calibration Infrastructure Expansion | NIOSH protocol recertification dependencies create recurring revenue streams and customer switching costs for established service network operators. |
Study Parameters
Operator-level perspectives from hospital biomedical engineers, plant safety managers at Midwest automotive facilities, GPO contracts managers, certified industrial hygienists, and respiratory protection product managers anchored the qualitative base. Primary interview findings triangulated against OSHA enforcement data, FDA 510(k) filings for N95 respirator-related devices, NIOSH fit test protocol documentation, hospital procurement databases, and SEC filings from diversified industrial conglomerates. Bottom-up demand modeling from end-user segments converged with top-down market sizing across product type and technology dimensions.
Sensitivity analysis tested forecast outputs against alternative scenarios for certified industrial hygienist supply constraints, NIOSH protocol revision timing, and elastomeric respirator design divergence rates. Segmentation dimensions modeled included product type, usage scenario, technology platform, and end-user category across the analysis window. CAGRs derived from instrument replacement cycle analysis, compliance mandate expansion trajectories, and technology adoption curve positioning for portable versus cart-mounted systems.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity, stable NIOSH protocol specifications, and continued hospital preparedness program funding would require recalibration. Forecasts reflect assumptions regarding technician training pipeline development and hybrid system technical maturation. Recalibration cycles align with material shifts in respiratory protection regulatory frameworks and particle counting technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market