
 Disposable Respirator Market | 2026-2036
Disposable Respirator Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Respirator Market Intelligence
Healthcare procurement is rotating toward industrial buyers as pandemic-era stockpiling normalizes. MSA Safety Incorporated leverages its fixed gas detection heritage to cross-sell respiratory protection into energy sector contracts. Honeywell International Inc. sustains manufacturing scale across multiple NIOSH-certified production lines in the United States. Dragerwerk AG and Co. KGaA anchors European demand through its specialized breathing apparatus distribution network.
A disposable respirator is a single-use filtering facepiece that removes airborne particulates through melt-blown polypropylene fiber layers meeting specified filtration efficiency thresholds, designed to protect the wearer from hazardous aerosols in occupational environments. N95 and FFP2 variants dominate procurement volumes where oil-free particulate filtration governs specification sheets, while carbon filter configurations command premium positioning in chemical processing applications where nuisance vapor removal extends utility. Surgical respirators occupy a mature demand corridor in hospital infection control, whereas KN95 sourcing patterns reflect ongoing recalibration of supply chain qualification protocols.
NIOSH certification under 42 CFR Part 84 governs United States market access, while CE marking under the EU Personal Protective Equipment Regulation frames European commercialization requirements. OSHA respiratory protection standards mandate fit testing and program administration that inflate total cost of ownership beyond unit pricing alone. Stakeholders must monitor evolving filtration efficiency benchmarks as regulators weigh harmonization between N95, FFP2, and KN95 testing methodologies.
Market Dynamics
Pharmaceutical cleanroom protocols are tightening filtration efficiency requirements, forcing procurement departments to requalify entire supplier bases around NIOSH and CE-certified production lines rather than price alone.
Growth Catalysts
- OSHA respiratory protection standards:United States enforcement mandates expand fit-testing programs across manufacturing facilities, creating recurring demand for certified disposable units beyond initial stockpiling cycles.
- Melt-blown polypropylene fiber optimization:Advances in electrostatic charging techniques improve particulate capture efficiency without increasing breathing resistance, opening adoption in extended-wear pharmaceutical operations.
- China industrial safety enforcement:Provincial-level inspections of chemical processing facilities accelerate KN95 and GB-certified respirator procurement as domestic production scales to meet compliance deadlines.
Market Restraints
- Polypropylene feedstock volatility:Petrochemical input cost swings compress margin structures for manufacturers lacking backward integration into polymer resin supply.
- NIOSH certification backlog:United States approval timelines for new product variants extend to 12-18 months, freezing commercialization of incremental filtration improvements.
- Reusable elastomeric respirators:Industrial buyers in heavy manufacturing pivot toward half-mask alternatives with replaceable cartridges, eroding addressable volume for single-use disposables in certain occupational settings.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-aligned cleanroom requirements at active pharmaceutical ingredient facilities create qualified demand for FFP2-equivalent surgical respirators with documented lot traceability.
- Carbon filter integration:Nuisance vapor removal capabilities extend utility into chemical processing applications where standard particulate filtration proves insufficient for worker protection.
- Direct hospital system contracting:Bypassing traditional distribution layers through GPO-negotiated frameworks captures margin otherwise lost to medical supply intermediaries.
Industry Challenges
- Fit-testing technician shortage:OSHA-mandated qualitative and quantitative fit assessment programs require certified personnel that industrial hygiene departments struggle to recruit and retain at scale.
- Harmonization delays between N95 and FFP2 protocols:Divergent test agent specifications and flow rate requirements complicate single-SKU strategies for manufacturers serving both United States and European markets.
- Legacy inventory obsolescence:Healthcare systems face write-downs on pandemic-era stockpiles as expiration dates approach and filtration efficiency claims degrade in storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Respirator Market |
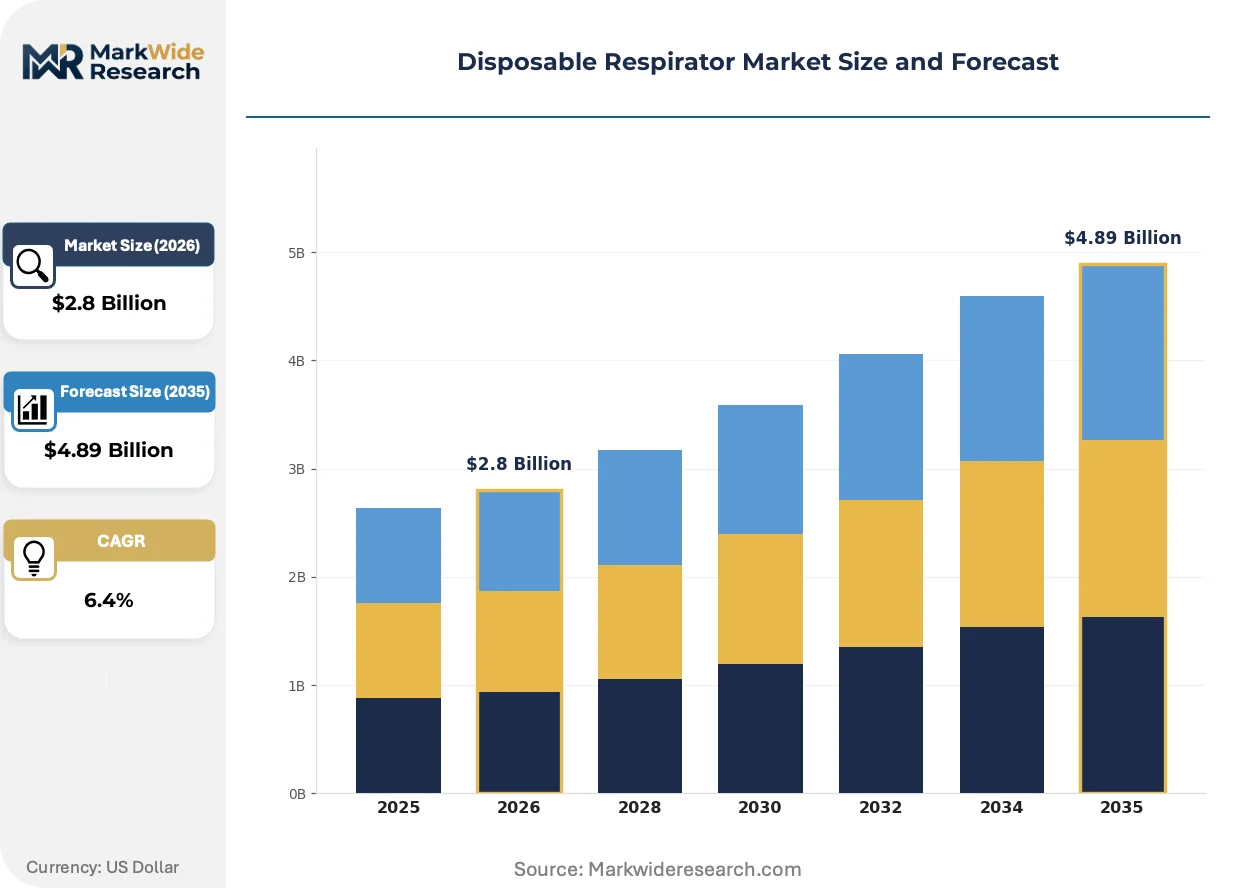
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N95, FFP2, KN95, Surgical, Carbon Filter Application: Mining, Construction, Chemical Processing, Firefighting, Pharmaceutical Manufacturing End User: Occupational Safety, Laboratory Personnel, Emergency Responders, Industrial Workers, Cleanroom Operators Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Industrial Equipment Suppliers, Wholesale Distributors |
| Companies Covered | MSA Safety Incorporated, Dragerwerk AG and Co. KGaA, 3M Co., Prestige Ameritech, Alpha Pro Tech Ltd., Honeywell International Inc., Moldex-Metric Inc., The Gerson Co., Kimberly-Clark Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Respirator Market Strategic Shifts & Innovations
Filtration material science and regulatory harmonization pressures are converging to reshape product architecture and procurement specifications across occupational health applications.
Electrospun nanofiber membranes are fragmenting the traditional melt-blown polypropylene hierarchy by enabling thinner pressure-drop profiles at equivalent particulate capture ratings. Pharmaceutical cleanroom operators in Switzerland and Singapore are piloting these layers for extended-duration donning protocols. The structural consequence is fragmenting established supply relationships as buyers requalify around nanofiber-enabled SKUs that command premium positioning.
EU MDR recertification timelines are compressing the window for legacy CE-marked respirators to remain in distribution, forcing manufacturers to accelerate technical documentation updates and clinical evaluation reports. Industrial PPE distributors in Germany and France are prioritizing inventory positions around MDR-compliant product lines ahead of enforcement deadlines. Surgical respirator categories face the steepest compliance burden given their medical device classification under the expanded scope.
Hospital supply chain directors are unbundling infection control procurement from pandemic-era emergency frameworks, restoring standard competitive bidding cycles with 12-18 month contract horizons. United States health systems are consolidating respiratory protection spend under fewer supplier relationships to extract volume-based service commitments. The behavioral shift is most pronounced in integrated delivery networks spanning multiple states, where standardization across facilities overrides local sourcing preferences.
Disposable Respirator Market Segmentation
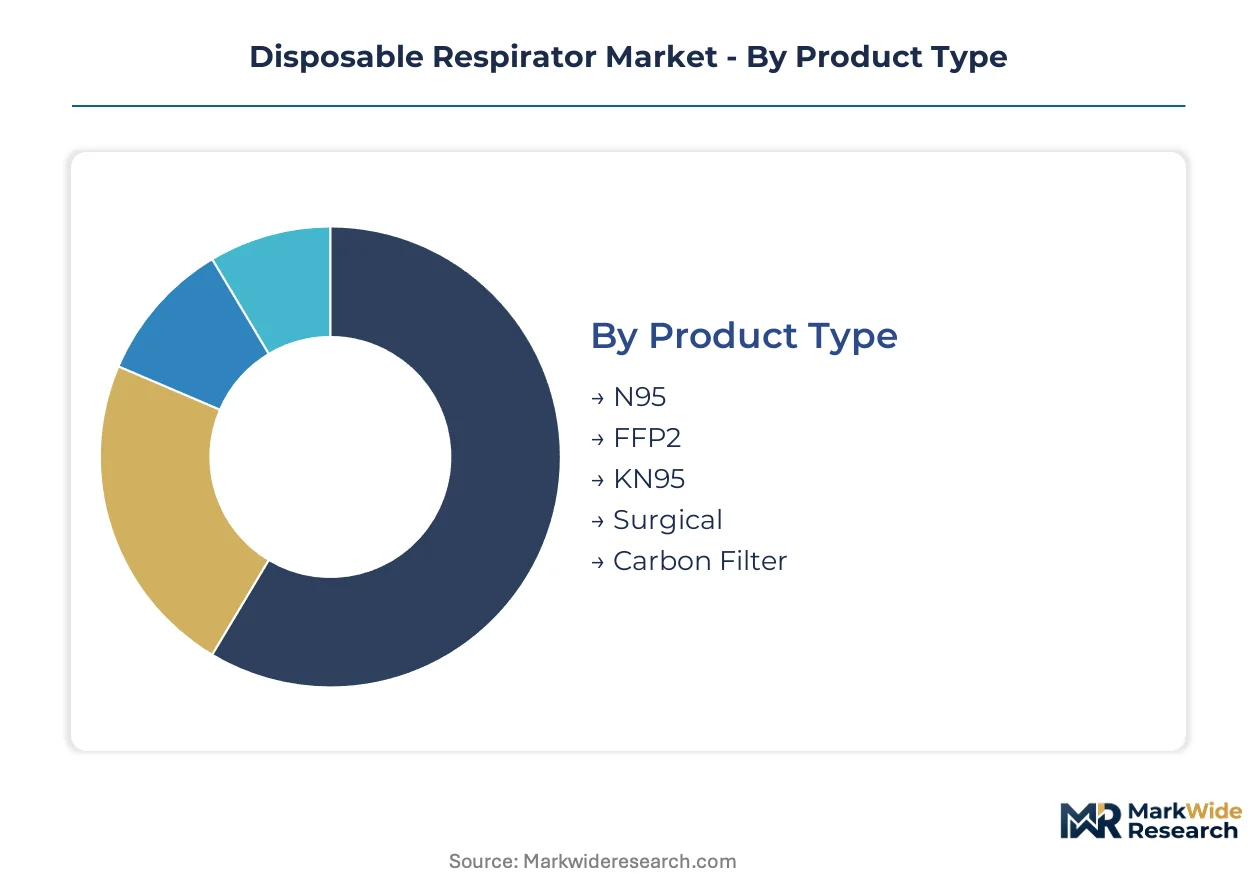
Respirator procurement varies sharply across user environments, with certification requirements and exposure risks dictating product selection. Segmentation reveals where reusable elastomeric alternatives threaten single-use volumes and where regulatory compliance locks in disposable demand.
Product Type:
Substitution pressure from half-mask elastomeric respirators hits standard particulate segments hardest, while specialized configurations retain pricing power through technical differentiation.
- N95:Melt-blown polypropylene construction meeting NIOSH 42 CFR Part 84 filtration efficiency thresholds. United States hospital systems and manufacturing facilities anchor procurement volumes under OSHA respiratory protection program mandates, though fit-testing technician shortages constrain program expansion.
- FFP2:European CE-marked equivalent with EN 149 testing protocols governing penetration and breathing resistance. German and French industrial distributors prioritize MDR-compliant product lines as recertification deadlines approach, compressing legacy inventory windows.
- KN95:GB 2626-certified Chinese standard with divergent flow rate specifications complicating cross-border qualification. Domestic chemical processing inspections in China accelerate procurement as provincial enforcement deadlines tighten.
- Surgical:Fluid-resistant outer layers designed for hospital infection control with FDA 510(k) or CE medical device classification. United States health systems unbundle pandemic-era emergency frameworks, restoring competitive bidding cycles with documented lot traceability requirements.
- Carbon Filter:Activated carbon layers adsorbing nuisance vapors below OSHA permissible exposure limits in chemical processing environments. Premium positioning reflects extended utility where standard particulate filtration proves insufficient.
N95 anchors the volume base while carbon filter configurations gain share at the steepest rate.
Application:
Cost tier stratification separates commodity procurement in high-turnover environments from premium specification in contamination-sensitive operations.
- Mining:Dust exposure regulations govern underground and surface operations with emphasis on silica particulate capture. Australian and South African regulatory frameworks mandate fit-testing programs that sustain recurring demand cycles.
- Construction:Silica rule enforcement drives respirable crystalline silica protection across demolition and concrete cutting operations. United States OSHA inspections accelerate procurement as compliance deadlines phase in across state plans.
- Chemical Processing:Nuisance vapor and toxic particulate exposure requiring carbon filter integration or supplied-air alternatives. Swiss pharmaceutical cleanroom operators pilot electrospun nanofiber membranes for extended-duration protocols.
- Firefighting:Self-contained breathing apparatus dominates structural fire entry, limiting disposable respirators to overhaul and wildland smoke exposure. NFPA standards govern cartridge compatibility with full-facepiece configurations.
- Pharmaceutical Manufacturing:Cleanroom ISO classification dictates filtration efficiency requirements at active pharmaceutical ingredient facilities. India CDSCO-aligned standards create qualified demand for FFP2-equivalent surgical respirators with full supply chain documentation.
Construction and mining represent the highest-volume procurement tiers while pharmaceutical manufacturing commands the steepest premium expansion trajectory.
End User:
Customer type fragmentation reflects divergent purchasing authority structures, from centralized industrial hygiene departments to decentralized laboratory procurement.
- Occupational Safety:Corporate industrial hygiene programs administering OSHA-mandated respiratory protection across manufacturing and energy facilities. Fit-testing technician scarcity constrains program scalability despite regulatory enforcement expansion.
- Laboratory Personnel:Research and diagnostic settings requiring biosafety level-appropriate protection with emphasis on comfort during extended wear protocols.
- Emergency Responders:Fire departments and hazardous materials teams balancing disposable convenience against reusable apparatus durability in unpredictable exposure scenarios.
- Industrial Workers:Frontline manufacturing and maintenance personnel in metalworking, food processing, and general fabrication. High turnover drives unit volume but compresses margin through price-sensitive procurement.
- Cleanroom Operators:Pharmaceutical and semiconductor fabrication personnel requiring particulate control alongside sterile gowning protocols. Singapore and Switzerland facilities lead nanofiber membrane pilot adoption for reduced breathing resistance.
Occupational safety departments control the largest budget pools while cleanroom operators drive the fastest technology upgrade cycles.
Distribution Channel:
Margin capture varies sharply by channel control, with direct contracting bypassing traditional distributor markups in consolidated health systems.
- Direct Sales:Manufacturer relationships with integrated delivery networks and multinational industrial accounts. United States hospital system consolidation under GPO-negotiated frameworks extracts volume-based service commitments.
- Online Retail:E-commerce platforms serving small-to-mid industrial buyers and individual professionals. Counterfeit product risks complicate qualification protocols for KN95 sourcing.
- Medical Supply Stores:Regional distributors serving outpatient clinics and dental practices with lower-volume, higher-service requirements.
- Industrial Equipment Suppliers:Safety distributors bundling respiratory protection with gas detection and fall protection portfolios. MSA Safety leverages fixed gas detection heritage for cross-selling into energy sector contracts.
- Wholesale Distributors:Broadline medical and industrial distributors carrying multi-manufacturer portfolios. EU MDR recertification timelines compress inventory positions around compliant product lines.
Direct sales channels capture margin expansion while online retail faces steepest counterfeit qualification headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hygiene procurement concentrates in manufacturing-intensive economies where OSHA-style enforcement frameworks mandate recurring fit-testing programs. Pharmaceutical cleanroom expansion and chemical processing compliance deadlines concentrate demand across three continents.
United States
Hospital system consolidation and manufacturing reshoring drive N95 procurement volumes. OSHA respiratory protection standards mandate fit-testing programs across 26 states with delegated enforcement authority. Texas and Ohio industrial corridors anchor demand from petrochemical and automotive assembly operations.
Germany
EU MDR recertification timelines compress distribution windows for legacy CE-marked respirators. Industrial PPE distributors in Baden-Württemberg and North Rhine-Westphalia prioritize MDR-compliant inventory positions ahead of enforcement deadlines. BASF and Bayer facility clusters sustain premium-tier demand for carbon-filter configurations.
China
Provincial chemical processing inspections accelerate KN95 and GB-certified procurement as domestic production scales. Jiangsu and Shandong manufacturing belts face compliance deadlines under expanded industrial safety enforcement. Yangtze River Delta pharmaceutical facilities pilot electrospun nanofiber membranes for extended-wear protocols.
India
CDSCO-aligned cleanroom requirements at active pharmaceutical ingredient facilities create qualified demand for FFP2-equivalent surgical respirators. Gujarat and Maharashtra pharmaceutical clusters require documented lot traceability for export-oriented production. Karnataka biotechnology parks drive technology upgrade cycles for biosafety-level appropriate protection.
Switzerland
Pharmaceutical cleanroom ISO classifications tighten filtration efficiency requirements at Novartis and Roche manufacturing sites. Swissmedic medical device oversight frames procurement specifications for surgical respirator categories. Basel and Zurich metropolitan areas lead European pilot adoption of nanofiber-enabled SKUs.
Disposable Respirator Market Key Industry Players
Player mix skews toward diversified industrial safety conglomerates with cross-selling capabilities into respiratory protection. Consolidation pressure favors manufacturers with captive melt-blown polypropylene supply or NIOSH-certified production line scale. Three archetypes dominate: gas detection heritage players leveraging fixed-installation relationships, medical device specialists with FDA 510(k) pathways, and polymer science conglomerates with backward integration into fiber production. Competitive moves center on M&A for certification portfolio expansion and strategic partnerships with industrial distributors for GPO-negotiated hospital contracts.
Among diversified industrial safety players, MSA Safety Incorporated and Honeywell International Inc. exemplify archetypes built on cross-selling infrastructure. MSA leverages its fixed gas detection heritage to anchor respiratory protection within energy sector contracts. Honeywell sustains manufacturing scale across multiple NIOSH-certified production lines. Dragerwerk AG and Co. KGaA occupies a position within the European specialist tier, anchoring demand through breathing apparatus distribution networks concentrated in German-speaking industrial markets.
| Leading Market Players |
|---|
| MSA Safety Incorporated |
| Dragerwerk AG and Co. KGaA |
| 3M Co. |
| Prestige Ameritech |
| Alpha Pro Tech Ltd. |
| Honeywell International Inc. |
| Moldex-Metric Inc. |
| The Gerson Co. |
| Kimberly-Clark Corp. |
| Others |
Cost & Logistics Intelligence
NIOSH-certified production line scale in the United States anchors price floors across global respirator markets, as manufacturers amortize 12-18 month approval timelines across high-volume contracts. Polypropylene resin input costs transmit directly to unit pricing through petrochemical indexation clauses in industrial procurement agreements.
Pricing Analysis
Cost-plus contracts with polypropylene indexation dominate industrial procurement agreements, linking unit prices to resin futures movements. Three-tier pricing structure across NIOSH-certified premium, CE-marked standard, and uncertified economy levels separates pharmaceutical cleanroom buyers from construction contractors. Cost compression in standard particulate tiers intensifies as reusable elastomeric alternatives capture heavy manufacturing accounts. Construction contractors exhibit the highest price sensitivity, while pharmaceutical cleanroom operators prioritize filtration efficiency documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling preferences among United States hospital systems contrast with just-in-time procurement patterns in European industrial distribution. Melt-blown polypropylene fiber production concentrates in China, the United States, and Germany, with electrostatic charging equipment sourcing from Japan and Switzerland. Single-source vulnerability in NIOSH certification testing capacity creates approval bottlenecks for new product variants. Distribution runs through industrial safety distributors bundling respiratory protection with gas detection portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable respirator market traces a cyclical recovery pattern as pandemic-era inventory drawdowns complete and OSHA enforcement mandates restore recurring fit-testing demand.
For Market Incumbents: Compound defensive positioning through captive melt-blown polypropylene supply and accelerated MDR technical documentation updates ahead of European enforcement deadlines. Reusable elastomeric respirators threaten single-use volumes in heavy manufacturing; counter with carbon filter integration for chemical processing applications. Certification investment in electrospun nanofiber membranes captures pharmaceutical cleanroom upgrade cycles. For New Entrants and Emerging Players: Differentiate on electrospun nanofiber membrane performance for extended-wear pharmaceutical protocols where breathing resistance governs procurement specifications. Target India pharmaceutical manufacturing expansion under CDSCO-aligned cleanroom requirements with FFP2-equivalent surgical respirators and full lot traceability documentation. Bypass traditional distribution layers through direct GPO-negotiated hospital system contracting. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with backward integration into polymer resin supply or NIOSH-certified production line scale. Long-term viability rests on regulatory harmonization between N95 and FFP2 protocols enabling single-SKU strategies. Watch NIOSH certification backlog clearance rates as inflection indicator for new product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | 12-18 month approval timelines lock in competitive moats for certified production lines. |
| Carbon Filter Integration | Nuisance vapor removal extends utility into BASF and Bayer chemical processing clusters. |
| MDR Technical Documentation Update | EU recertification deadlines compress legacy inventory windows for CE-marked respirators. |
| Direct Hospital System Contracting | GPO-negotiated frameworks bypass distributor markups in consolidated United States health systems. |
| Electrospun Nanofiber Membrane Development | Reduced breathing resistance captures Novartis and Roche cleanroom upgrade cycles in Switzerland. |
Research Approach
Desk research of FDA 510(k) filings, OSHA enforcement databases, and EU MDR technical documentation preceded structured interviews with industrial hygiene directors, GPO contracts managers, and pharmaceutical cleanroom operators. Primary fieldwork with NIOSH-certified manufacturers and European PPE distributors combined with secondary validation through customs trade data and SEC filings. Bottom-up volume modeling across product tiers triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within product type, application, and end user segments. Modeled dimensions span certification grade, exposure risk tier, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to OSHA enforcement expansion timelines and pharmaceutical cleanroom construction pipelines. Forecast inputs include provincial inspection schedules in China and CDSCO facility approval rates in India.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or MDR recertification deadline adherence would require recalibration. Forecasts reflect assumptions around melt-blown polypropylene capacity expansion and fit-testing technician availability. Revision becomes warranted when NIOSH certification backlog duration or electrospun nanofiber membrane qualification timelines cross threshold deviations from baseline trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market