
 US Smart PPE Technology Market | 2026-2036
US Smart PPE Technology Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart PPE Technology Market Insights
Buyer concentration among large construction and oilfield services firms is hardening as tier-one contractors standardize connected-worker programs across multi-site portfolios. Honeywell International Inc. leverages its integrated safety software stack to anchor enterprise accounts requiring unified command-center visibility. MSA Safety Incorporated differentiates through gas-detection fusion with wearable hardware, while RealWear Inc. specializes in voice-controlled augmented-reality headsets for hands-free field operations.
US Smart PPE Technology encompasses sensor-embedded protective equipment with wireless connectivity, microprocessor-driven environmental monitoring, and real-time biometric feedback systems engineered to prevent occupational injury and exposure. Smart helmets with integrated proximity alarms and connected vests with physiological strain gauges serve primarily to reduce recordable incidents in hazardous industrial settings. Smart helmets currently occupy the largest product segment as hard-hat replacement cycles accelerate, while wearable sensors represent the fastest-expanding category driven by biometric monitoring adoption in manufacturing. IoT technology leads the connectivity layer, though augmented reality is capturing disproportionate investment in training and remote-assistance applications.
OSHA enforceable standards, NHTSA guidelines for connected fleet-worker interfaces, and FCC spectrum allocations for industrial IoT collectively shape product certification requirements and deployment timelines. The EPA's emerging chemical-exposure monitoring mandates are pushing manufacturers toward multi-sensor platform architectures capable of simultaneous vapor, particulate, and thermal detection. Stakeholders must weigh the capital intensity of integrated platform bets against the operational flexibility of modular, best-of-breed sensor ecosystems.
Market Dynamics
OSHA's 2024 electronic incident reporting mandate for large employers is compressing procurement cycles as general contractors race to deploy connected-worker platforms before enforcement deadlines. Tier-one construction and oilfield services firms are consolidating vendor relationships around integrated safety stacks that unify biometric monitoring, proximity detection, and command-center analytics.
Growth Catalysts
- OSHA Electronic Reporting Mandate:Large construction employers must submit detailed injury data digitally, accelerating adoption of sensor-embedded hard hats and connected vests that auto-log near-misses and physiological strain events.
- Heat-Stress Monitoring:Texas and Gulf Coast petrochemical operators face intensifying operational priority for real-time biometric tracking as summer temperature records strain existing hydration protocols.
- 5G Private Networks:Industrial facilities in Houston and Corpus Christi are deploying campus-scale connectivity that eliminates latency barriers for streaming video from augmented-reality headsets and continuous biometric feeds.
Market Restraints
- Semiconductor Supply Concentration:Microprocessor and MEMS sensor fabrication remains concentrated in East Asian foundries, exposing US smart PPE manufacturers to geopolitical disruption and extended lead times for biometric chipsets.
- Lithium-Ion Cell Volatility:Wearable device batteries face raw material cost swings and thermal runaway certification requirements that complicate compact power pack design for intrinsically safe environments.
- FCC Spectrum Licensing Friction:Industrial IoT deployments in the 3.5 GHz CBRS band require coordinated access system approvals that delay multi-site rollouts by six to twelve months in congested metropolitan markets.
Strategic Opportunities
- EPA Chemical-Exposure Monitoring:Emerging vapor and particulate detection mandates are creating white space for multi-sensor platform architectures that fuse gas detection with thermal and biometric monitoring in single wearable units.
- Appalachian Shale Basin Penetration:Mid-size oilfield services contractors in Pennsylvania and West Virginia remain underpenetrated by connected-worker programs, presenting first-mover advantage for modular sensor ecosystems.
- AR-Enabled Remote Assistance:Voice-controlled augmented-reality headsets are expanding from training applications into live maintenance workflows, converging field technician support with real-time safety oversight.
Industry Challenges
- Industrial IoT Cybersecurity Skill Gap:Facility safety managers lack embedded systems security expertise to harden wireless sensor networks against ransomware targeting operational technology environments.
- Multi-Sensor Certification Timelines:NIOSH and ANSI approval processes for integrated smart helmets combining proximity alarms, gas detection, and biometric tracking extend product launch cycles by eighteen to twenty-four months.
- Legacy SCADA Integration Complexity:Brownfield manufacturing plants require costly middleware development to stream wearable sensor data into decades-old control architectures without disrupting production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart PPE Technology Market |
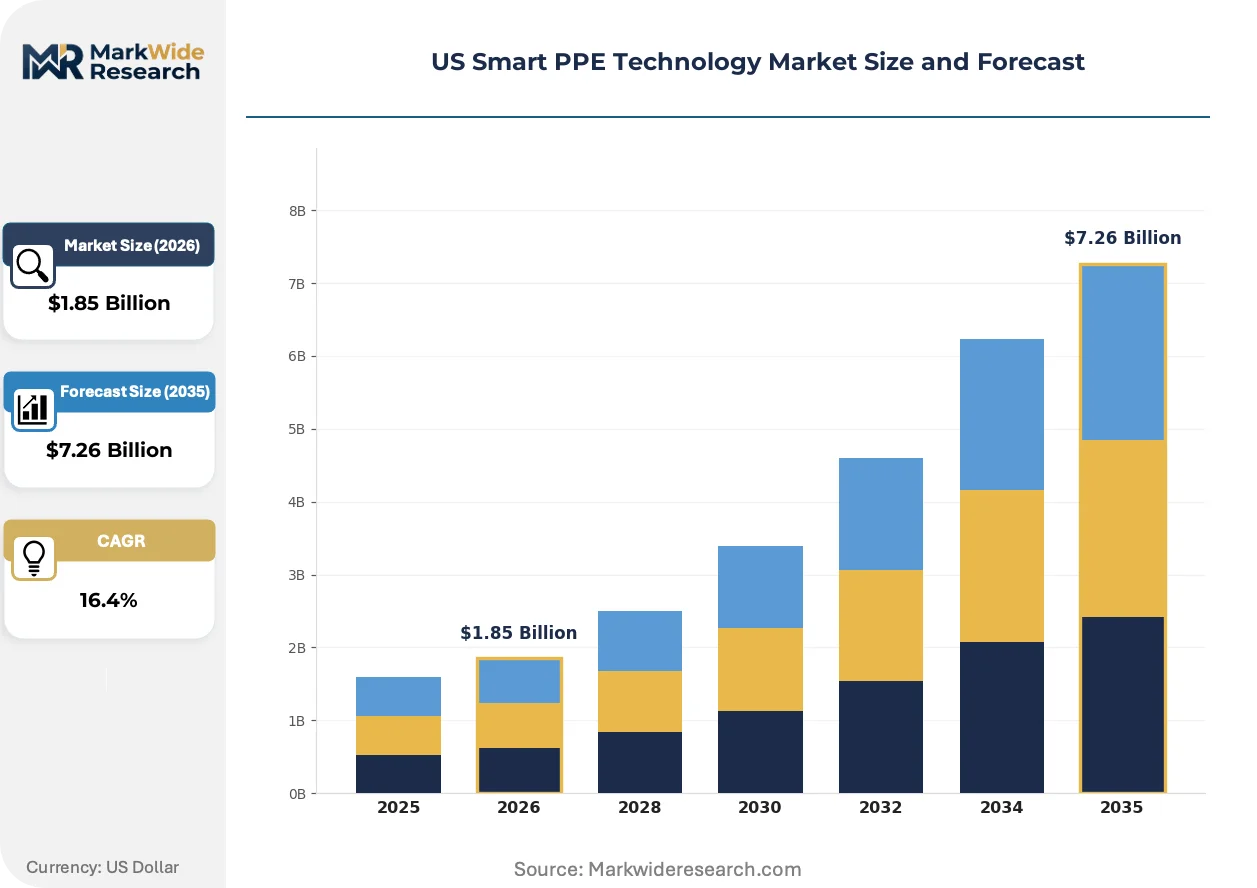
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Connected Vests, Smart Gloves, Wearable Sensors Technology: IoT, Bluetooth, RFID, Augmented Reality End User: Construction, Manufacturing, Healthcare, Oil & Gas Application: Worker Safety, Process Monitoring, Environmental Awareness, Training |
| Companies Covered | Honeywell International Inc., 3M Company, MSA Safety Incorporated, Vuzix Corporation, DuPont de Nemours Inc., Ansell Limited, Uvex Group, Corvex Connected Worker, RealWear Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart PPE Technology Market Trends and Innovations
Sensor fusion architectures are displacing single-function wearables as buyers demand unified platforms that consolidate gas detection, biometric monitoring, and location tracking. Texas and Gulf Coast operators are piloting these converged systems ahead of anticipated EPA multi-pollutant monitoring rules.
Multi-sensor fusion platforms are expanding into standard procurement specifications for large construction and petrochemical employers. General contractors in Houston and Beaumont are specifying hard hats with integrated proximity alarms, physiological strain gauges, and vapor detection in single units. This convergence is compressing vendor margins for standalone device manufacturers while rewarding integrated safety software providers with multi-year enterprise contracts.
OSHA's heat illness prevention initiative is reshaping summer work protocols across southern US states. The agency's emphasis on acclimatization scheduling and real-time monitoring is driving demand for connected vests with core temperature sensors in Texas, Louisiana, and Florida construction markets. Large employers are responding by mandating biometric monitoring for crews working above heat index thresholds, creating pull-through demand for cloud-based analytics dashboards.
Buyer committees are consolidating vendor evaluations around total cost of safety ownership rather than unit equipment pricing. Oilfield services procurement teams in the Permian Basin are bundling hardware, software licenses, and predictive analytics subscriptions into three-year agreements. This behavioral shift is most visible among tier-one contractors with multi-state portfolios, who prioritize interoperability over best-of-breed point solutions.
US Smart PPE Technology Market Segmentation
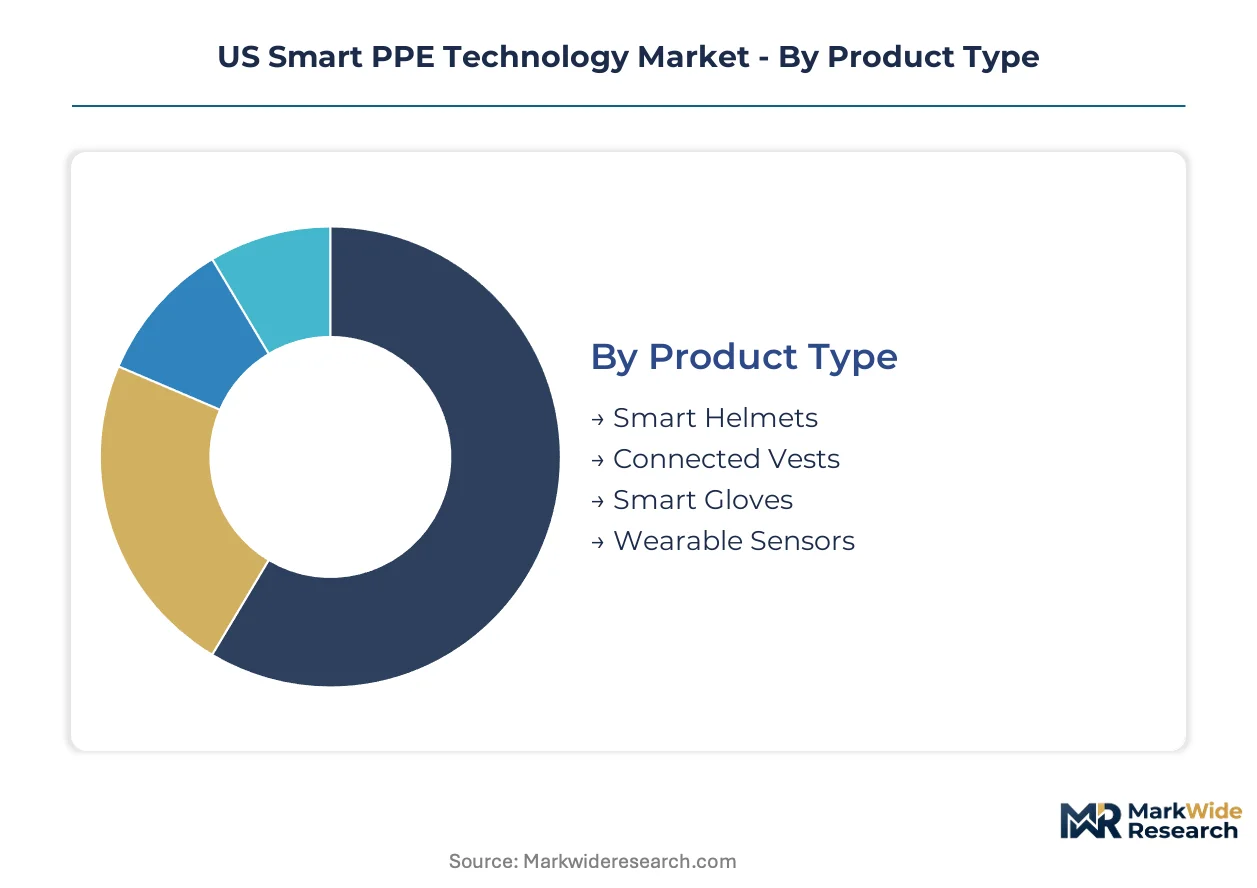
Smart PPE procurement patterns diverge sharply by operational environment, with construction and petrochemical buyers prioritizing integrated platforms while healthcare and manufacturing favor modular, device-specific deployments. Understanding these segment boundaries clarifies where standardization yields economies of scale versus where customization commands premium positioning.
Product Type:
Customization intensity varies from fully integrated head-mounted systems to single-point sensor attachments that retrofit legacy equipment.
- Smart Helmets:Hard-hat form factors embed proximity alarms, gas-detection modules, and biometric strain gauges under NIOSH impact certification. Replacement cycle acceleration in Texas and Gulf Coast petrochemical corridors drives volume concentration as employers face OSHA electronic reporting deadlines for incident documentation.
- Wearable Sensors:Discrete physiological monitors track core temperature, heart rate variability, and exertion indices through fabric-integrated MEMS arrays. Louisiana and Florida construction markets are absorbing these fastest as heat-stress prevention protocols harden under agency enforcement.
- Connected Vests:Garment-embedded sensor networks stream location and environmental data to command centers.
- Smart Gloves:Hand-wearable units deliver haptic feedback and grip-force analytics for precision manufacturing environments.
Most installed capacity flows through Smart Helmets. Expansion is steepest in Wearable Sensors.
Technology:
Connectivity layer selection hinges on latency tolerance, with real-time biometric streaming demanding campus-scale infrastructure that simpler asset-tracking applications can bypass.
- IoT:Industrial-grade wireless sensor networks operating across licensed and unlicensed spectrum bands enable continuous data telemetry from dispersed field crews. Houston and Corpus Christi facilities are deploying private 5G networks to eliminate latency barriers for streaming video and biometric feeds simultaneously.
- Augmented Reality:Voice-controlled head-mounted displays overlay schematic diagrams and remote expert video feeds into the operator's field of view. Permian Basin maintenance workflows are absorbing these units fastest as first-line technicians require hands-free access to procedural guidance during complex equipment interventions.
- Bluetooth:Short-range personal area networking for device-to-smartphone data relay in lower-risk environments.
- RFID:Passive and active tagging systems for zone-based location tracking without continuous telemetry requirements.
IoT carries the largest installed base. Augmented Reality is climbing the fastest as training applications mature into live operational support.
End User:
Buyer sophistication and procurement scale separate enterprise-grade safety programs from departmental pilot deployments.
- Construction:General contractors with multi-state portfolios standardize connected-worker programs across project sites to satisfy OSHA electronic incident reporting mandates. Tier-one firms in Texas, Louisiana, and Florida are consolidating vendor relationships around unified command-center visibility platforms.
- Oil & Gas:Integrated operators and oilfield services firms demand intrinsic safety certifications and multi-sensor fusion for simultaneous gas, thermal, and biometric monitoring. Gulf Coast petrochemical corridors concentrate procurement as EPA chemical-exposure monitoring rules tighten.
- Manufacturing:Brownfield plants with legacy SCADA architectures require middleware development to integrate wearable sensor streams without production disruption.
- Healthcare:Hospital systems pilot biometric monitoring for staff fatigue management in high-stress departments.
Construction absorbs the greatest shipment volume. Oil & Gas presents the steepest expansion trajectory as vapor detection mandates multiply sensor requirements per worker.
Application:
Use-case maturity determines whether deployments focus on reactive incident documentation or predictive intervention protocols.
- Worker Safety:Proximity detection, physiological strain alerting, and fall-notification systems dominate operational expenditure. OSHA heat illness prevention initiatives are mandating real-time biometric monitoring for crews above heat index thresholds across southern US states.
- Process Monitoring:Environmental sensors track vapor, particulate, and thermal conditions to correlate worker exposure with process upsets. Anticipated EPA multi-pollutant rules are pulling through demand for fused detection platforms in Texas and Louisiana refining complexes.
- Environmental Awareness:Situational alerting for zone-based hazards and atmospheric condition changes.
- Training:Augmented-reality simulations and remote expert guidance for skills transfer.
Worker Safety commands the dominant share of deployed units. Process Monitoring is gaining share fastest as regulatory pressure fuses safety and environmental compliance into single procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's connected worker deployments lag US adoption curves by approximately three years, while Mexico's maquiladora sector is leapfrogging directly to biometric monitoring without legacy SCADA transition phases. This divergence reflects distinct regulatory enforcement timelines and industrial infrastructure maturity across North American markets.
Texas Gulf Coast
Petrochemical corridor operators face intensifying OSHA heat illness prevention enforcement across Beaumont, Port Arthur, and Corpus Christi refining complexes. The EPA's emerging chemical-exposure monitoring mandates are pulling through demand for multi-sensor hard hats that fuse vapor detection with physiological strain gauges. Houston facilities are deploying private 5G networks to eliminate latency barriers for streaming augmented-reality maintenance feeds.
Louisiana Chemical Belt
Plant operators in Lake Charles and Baton Rouge are consolidating vendor relationships around unified command-center platforms ahead of anticipated multi-pollutant detection rules. OSHA electronic incident reporting deadlines are compressing procurement cycles for connected vests with core temperature sensors. Shell and Dow facilities are piloting sensor fusion architectures that consolidate gas, thermal, and biometric monitoring in single wearable units.
California Industrial Corridor
Cal/OSHA heat standards exceed federal thresholds, mandating real-time biometric monitoring for agricultural and construction crews in Central Valley and Los Angeles Basin markets. The state's Advanced Clean Trucks regulation is indirectly accelerating connected worker adoption as warehouse and logistics employers modernize fleet-worker interfaces simultaneously. Silicon Valley technology firms are supplying edge computing infrastructure for campus-scale IoT deployments.
Appalachian Shale Basin
Mid-size oilfield services contractors in Pennsylvania and West Virginia remain underpenetrated by connected worker programs, presenting first-mover advantage for modular sensor ecosystems. Marcellus and Utica drilling operations lack the capital intensity of Permian Basin peers but face identical OSHA electronic reporting mandates. Pittsburgh-based safety distributors are building regional service capabilities to support rapid deployment timelines.
Florida Construction Markets
General contractors in Miami-Dade and Orlando metro areas are mandating biometric monitoring for crews working above heat index thresholds under intensifying OSHA enforcement. The state's hurricane reconstruction cycles are accelerating hard-hat replacement rates while embedding proximity detection for crane and heavy equipment interfaces. Tier-one contractors are standardizing connected worker specifications across multi-site portfolios.
US Smart PPE Technology Market Competitive Landscape
US industrial conglomerates anchor one tier; specialized wearable technology firms hold differentiated positions in augmented reality and voice-controlled interfaces. The market exhibits moderate concentration with tier-one construction and oilfield services buyers consolidating vendor relationships around integrated safety stacks. Three strategic archetypes dominate: diversified industrial technology providers with unified software stacks, safety equipment specialists with gas-detection fusion capabilities, and augmented-reality headset manufacturers focused on hands-free field operations. Competitive dynamics center on multi-year enterprise contract capture and sensor fusion platform development.
Within the diversified industrial tier, Honeywell International Inc. and 3M Company exemplify integrated platform providers with enterprise-scale safety software capabilities. MSA Safety Incorporated occupies a specialist position representing the gas-detection fusion archetype, while RealWear Inc. anchors the augmented-reality headset segment for voice-controlled field operations. These three firms illustrate the competitive segmentation between unified command-center visibility, multi-sensor environmental monitoring, and hands-free remote assistance workflows.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| MSA Safety Incorporated |
| Vuzix Corporation |
| DuPont de Nemours Inc. |
| Ansell Limited |
| Uvex Group |
| Corvex Connected Worker |
| RealWear Inc. |
| Others |
Pricing and Supply Chain Analysis
Sensor fusion architectures consolidating gas detection, biometric monitoring, and proximity alerting into single wearable units are compressing margins for standalone device manufacturers while rewarding integrated platform providers with pricing power anchored in multi-year enterprise subscriptions. This technological shift simultaneously elevates R&D amortization costs and concentrates procurement influence among tier-one contractors with multi-state portfolios.
Pricing Analysis
Capacity additions in private 5G network infrastructure across Texas and Louisiana are reshaping price floors for connectivity-dependent platforms. The market operates on a hybrid model combining per-unit hardware procurement with recurring SaaS subscriptions for analytics dashboards. Price differentiation hinges on NIOSH certification tier and software integration depth. Pricing pressure stems from semiconductor supply concentration in East Asian foundries extending lead times for biometric chipsets. Mid-size oilfield services contractors in the Appalachian Basin exhibit highest price sensitivity, while Gulf Coast petrochemical operators prioritize interoperability over unit cost.
Supply Chain Analysis
Refurbishment flows for lithium-ion power packs and sensor modules are emerging as critical reverse-logistics capabilities as enterprise buyers extend hardware refresh cycles. Microprocessor and MEMS sensor fabrication concentrates in Taiwan, South Korea, and China, drawing from rare earth elements processed in China and Australia. The supply chain rests on single-source vulnerability for advanced biometric chipsets. Distribution runs through specialized industrial safety distributors with field service capabilities rather than general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Smart PPE Technology has entered a late-cycle quality phase where buyer committees prioritize total cost of safety ownership over unit equipment pricing, favoring vendors with unified command-center visibility and multi-sensor fusion platforms.
For Market Incumbents: To counter modular sensor ecosystem challengers, anchor enterprise accounts through backward integration into safety software stacks and deepen NIOSH certification pipelines for integrated smart helmets combining gas detection with biometric tracking. Prioritize three-year bundled agreements spanning hardware, software licenses, and predictive analytics subscriptions to lock out best-of-breed competitors. For New Entrants and Emerging Players: Enter via underpenetrated mid-size oilfield services contractors in Pennsylvania and West Virginia, where OSHA electronic reporting mandates are compressing procurement cycles without established vendor relationships. Target modular sensor attachments that retrofit legacy hard hats, leveraging faster certification timelines than integrated platform alternatives. Lead with EPA chemical-exposure monitoring compliance as the go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among augmented-reality headset specialists with voice-controlled field operation capabilities, as training applications mature into live maintenance workflows. Long-term viability favors platforms converging safety oversight with remote expert assistance. Monitor FCC CBRS spectrum licensing velocity in congested metropolitan markets as inflection indicator for multi-site rollout scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Consolidates gas, thermal, and biometric monitoring into single NIOSH-certified units for Gulf Coast petrochemical operators. |
| Private 5G Network Deployment | Eliminates latency barriers for streaming video from augmented-reality headsets in Houston refining complexes. |
| Multi-Sensor Certification Investment | Accelerates NIOSH and ANSI approval timelines for integrated smart helmets with proximity alarms and vapor detection. |
| Backward Integration into Safety Software | Captures recurring SaaS revenue from enterprise command-center analytics subscriptions. |
| Regional Service Capability Buildout | Supports rapid deployment timelines for Appalachian Basin oilfield services contractors facing OSHA deadlines. |
Research Methodology
Bottom-up construction and oilfield services modeling reconciled against top-down semiconductor and industrial IoT component tracking forms the analytical core of this study. Primary interviews with safety directors at tier-one general contractors, procurement leads at integrated petrochemical operators, plant managers at Gulf Coast refineries, and channel partners at industrial safety distributors were cross-validated against secondary sources including OSHA enforcement data, FCC spectrum allocation records, EPA chemical-exposure monitoring rulemakings, and SEC filings from diversified industrial technology providers.
Input-output matrices mapping sensor unit shipments to end-use application intensity across product type, technology layer, and regional regulatory cluster generate volume and value estimates across the projection horizon. Segmentation dimensions include smart helmet versus wearable sensor form factors, IoT versus augmented reality connectivity protocols, and construction versus oil and gas end-use verticals. CAGRs derive from regression analysis against OSHA mandate enforcement schedules and private 5G infrastructure deployment curves, with heat-stress monitoring adoption rates in southern US states serving as key forecast inputs.
The model holds under steady OSHA enforcement timelines and stable East Asian semiconductor supply; deviation in FCC spectrum licensing velocity or geopolitical disruption to MEMS sensor fabrication would shift deployment trajectories. Practitioners should monitor EPA multi-pollutant detection rule finalization and CBRS coordinated access system approval rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market