
 PPE Detection Market | 2026-2036
PPE Detection Market Size, Share, and Industry Trends Forecast 2026-2036
PPE Detection Market Analytics
Construction safety management is rebalancing toward automated oversight as labor-intensive inspection models prove inadequate for large-scale infrastructure projects. Honeywell International Inc leverages its integrated building technologies portfolio to anchor PPE detection within broader safety ecosystems. 3M competes through deep channel control across industrial distribution networks in North America and Europe. Intenseye specializes in AI-native computer vision platforms purpose-built for construction and manufacturing environments.
PPE detection systems employ computer vision algorithms, sensor fusion arrays, and edge computing hardware to identify whether workers wear required protective equipment including helmets, vests, gloves, and harnesses in real time. These systems process video feeds through convolutional neural networks trained on annotated safety gear datasets, triggering alerts when compliance gaps occur. Computer vision technology dominates current deployment value due to mature open-source frameworks and declining camera hardware costs, while sensor fusion represents the fastest-expanding segment as multi-modal detection improves accuracy in low-visibility conditions. Cloud-based deployment captures growing share among mid-sized contractors seeking subscription flexibility, though on-premise systems retain margin concentration in defense-sensitive and data-restrictive facilities.
OSHA workplace safety directives in the United States, combined with EU machinery safety standards and CE marking requirements for industrial automation, create compliance-driven procurement cycles that accelerate replacement of legacy monitoring equipment. Japan's METI industrial safety guidelines and JIS standards further shape product specifications for Asian market entry. Stakeholders must evaluate whether to build proprietary detection models or integrate third-party AI platforms as regulatory thresholds for accuracy and auditability tighten across jurisdictions.
Market Dynamics
Computer vision systems with real-time edge processing are compressing inspection timelines from hours to seconds, forcing legacy manual protocols into obsolescence across high-risk industrial environments. This technological displacement creates asymmetric pressure on safety managers to automate compliance verification or face liability exposure.
Growth Catalysts
- OSHA workplace surveillance mandates:Tightened enforcement across United States construction sites drives procurement of automated detection systems for hard hat and harness compliance verification.
- Sensor fusion arrays:Multi-modal detection combining thermal imaging with visible-spectrum cameras improves accuracy in low-visibility construction scenarios, accelerating replacement of single-sensor legacy equipment.
- EU machinery safety standards:CE marking requirements for industrial automation equipment mandate integrated safety monitoring, creating compliance-driven upgrade cycles in German and French manufacturing facilities.
Market Restraints
- GPU and edge processor supply concentration:Taiwan-based semiconductor fabrication creates input cost volatility and lead time uncertainty for computer vision hardware manufacturers.
- Data residency requirements:GDPR and sector-specific national privacy laws in Germany and France restrict cloud-based video processing, forcing expensive on-premise infrastructure investments.
- Laboratory calibration protocols:Complex certification timelines for AI safety systems under EU AI Act and ISO/IEC standards delay product launches by 12-18 months.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for domestic manufacturing create first-mover advantage for PPE detection vendors establishing local assembly and training operations.
- Wearable sensor convergence:Integration of biometric monitors with computer vision platforms enables predictive fatigue detection, opening premium pricing in mining and heavy construction verticals.
- Subscription-based SaaS channels:Mid-sized contractors in Japan and South Korea demonstrate willingness to adopt monthly-per-camera pricing models, reducing upfront capital barriers.
Industry Challenges
- Computer vision engineer scarcity:Shortage of specialists capable of training convolutional neural networks on annotated safety datasets limits in-house model development for mid-tier vendors.
- Legacy SCADA integration complexity:Proprietary communication protocols in decades-old manufacturing control systems obstruct seamless deployment of modern detection platforms without expensive middleware.
- Cross-jurisdiction certification fragmentation:Divergent accuracy thresholds and auditability requirements between OSHA, EU machinery directives, and Japan METI guidelines force redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PPE Detection Market |
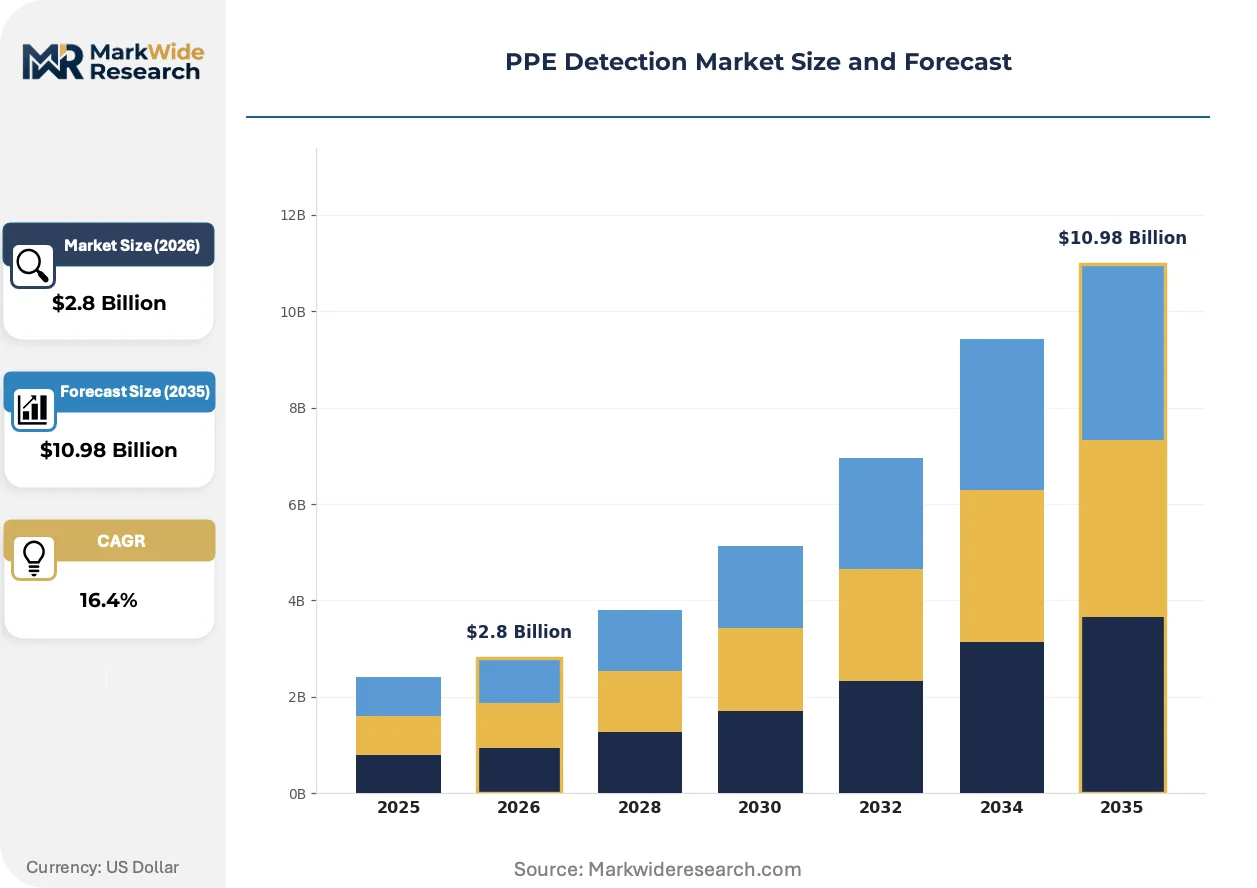
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, RFID, Sensor Fusion, Image Processing Application: Construction, Manufacturing, Healthcare, Oil & Gas End User: Facility Managers, Safety Officers, Contractors, Compliance Teams Deployment: On-Premise, Cloud-Based, Hybrid, Integrated Systems |
| Companies Covered | Honeywell International Inc, 3M, MSA Safety, Axis Communications AB, Intenseye, Wipro Limited, Siemens AG, Bosch Security Systems, Agile Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PPE Detection Market Evolving Landscape
Edge-native AI architectures are redistributing computational load away from centralized servers, enabling millisecond-latency hazard alerts that cloud-dependent systems cannot match. This architectural shift is compressing the competitive window for software-only vendors lacking hardware integration capabilities.
Transformer-based vision models are rewriting accuracy benchmarks for small-object detection in cluttered construction environments. General contractors in United States infrastructure projects are piloting these architectures for harness and lanyard verification at 50-meter ranges. The technology is rewriting procurement criteria, as accuracy guarantees now dominate hardware specifications in vendor selection scorecards.
EU AI Act risk classification requirements are mandating human-in-the-loop verification for high-stakes safety decisions in automated industrial environments. German automotive manufacturers must redesign detection workflows to include operator override capabilities, adding interface complexity and training overhead. French construction conglomerates are responding by establishing dedicated AI ethics review boards ahead of enforcement deadlines.
Mid-sized contractors are consolidating vendor relationships around integrated safety platform providers rather than point-solution specialists. Japanese general contractors now demand bundled offerings combining PPE detection, access control, and incident reporting through single-dashboard subscriptions. This preference consolidation is visible most acutely in Kansai region infrastructure projects, where procurement committees penalize fragmented technology stacks.
PPE Detection Market Segmentation
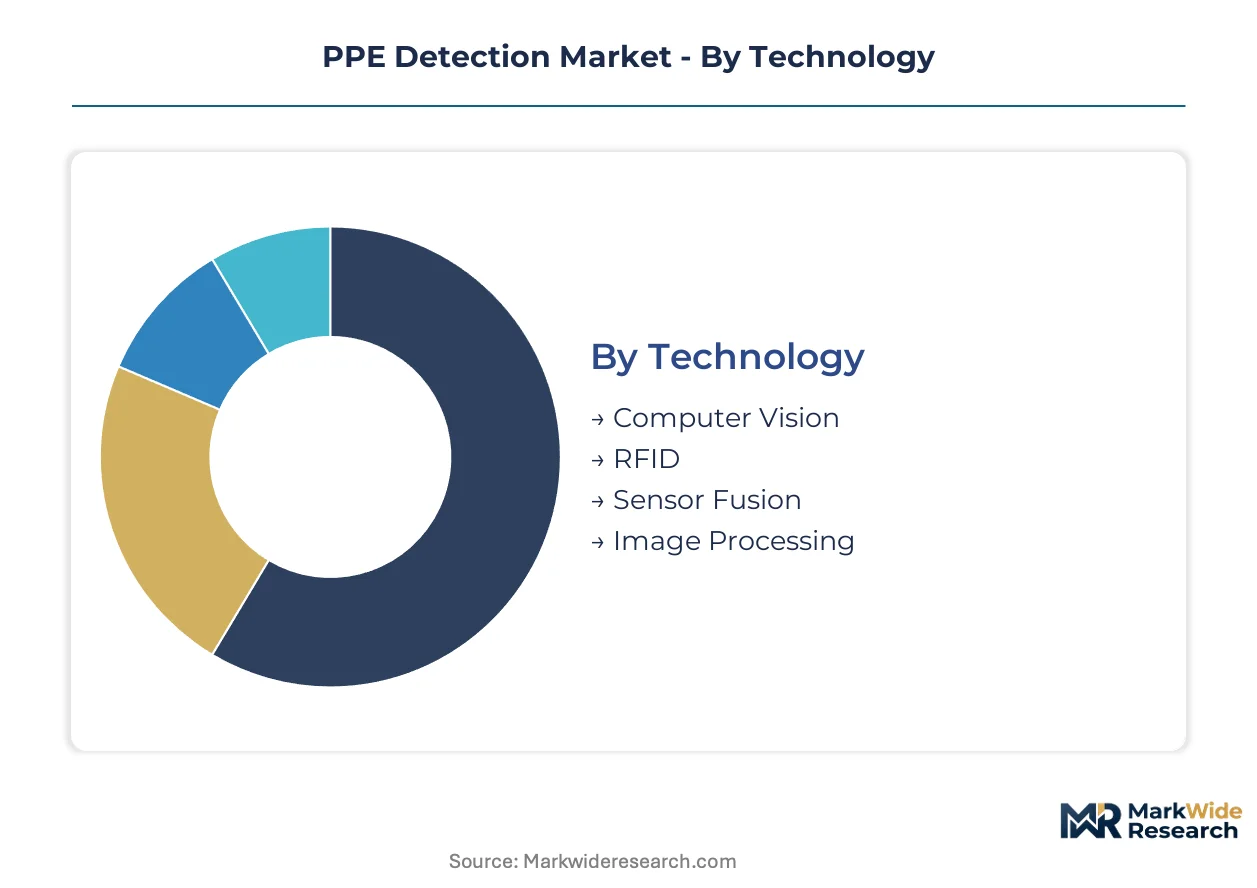
PPE detection procurement patterns diverge sharply between established industrial verticals and emerging compliance environments. Technology selection, deployment architecture, and end-user workflows each reshape vendor competitive positioning across buyer categories.
Technology:
Volume concentration sits with mature single-sensor platforms. Premium expansion concentrates in multi-modal fusion architectures.
- Computer Vision:Convolutional neural networks process visible-spectrum camera feeds to identify helmets, vests, and harnesses in real time. Construction sites across the United States deploy these systems most heavily where OSHA inspection density is highest and camera hardware costs have compressed to sub-$200 per unit.
- Sensor Fusion:Thermal imaging combined with visible cameras and depth sensors enables detection through dust, steam, and low-light industrial conditions. German manufacturing facilities under EU machinery safety mandates drive premium procurement as CE marking requirements tighten for automated monitoring equipment.
- RFID:Proximity-based verification using embedded tags in hard hats and safety vests.
- Image Processing:Rules-based algorithms without deep learning for constrained, high-repeatability environments.
Mature deployment sits with Computer Vision. Newer deployment is concentrated in Sensor Fusion.
Application:
Cost tiering separates project-scale construction from continuous-process manufacturing.
- Construction:Large-scale infrastructure projects with transient workforces and variable site conditions. Japanese general contractors in Kansai region infrastructure developments bundle PPE detection with access control and incident reporting through unified dashboards.
- Manufacturing:Fixed production lines with standardized lighting and predictable worker positioning. French automotive plants under EU AI Act risk classification requirements now mandate human-in-the-loop verification for automated safety decisions.
- Healthcare:Sterile environment compliance and biohazard protection verification in hospital settings.
- Oil & Gas:Explosion-proof hardware requirements and offshore platform connectivity constraints.
Margin concentration rests with Oil & Gas due to hazardous area certification premiums. Volume scaling is fastest in Construction.
End User:
Procurement authority determines feature complexity and integration depth.
- Facility Managers:Building systems integration with HVAC and access control networks. Honeywell's integrated building technologies portfolio anchors PPE detection within broader safety ecosystems for this buyer class.
- Safety Officers:Real-time alert dashboards and incident documentation workflows.
- Contractors:Subscription flexibility and rapid deployment without permanent infrastructure.
- Compliance Teams:Audit trails and regulatory reporting automation for OSHA, EU machinery directives, and Japan METI documentation.
Integration complexity peaks with Facility Managers. Subscription adoption is climbing fastest among Contractors.
Deployment:
Data residency requirements fragment architecture selection across jurisdictions.
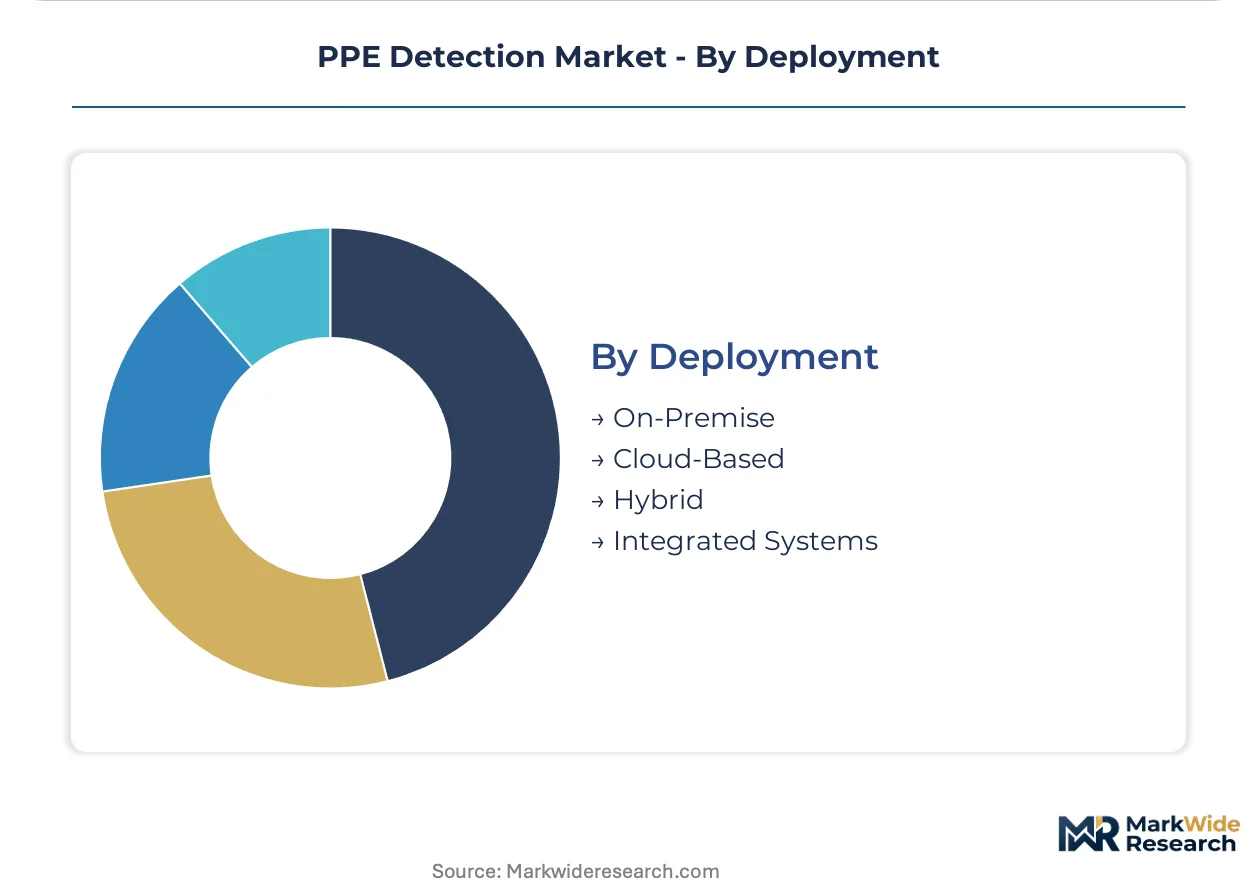
- On-Premise:Local edge processing with no cloud data transmission. German and French facilities under GDPR and sector-specific privacy laws absorb higher capital costs to maintain video data within national boundaries.
- Cloud-Based:Centralized model training and remote dashboard access. Mid-sized contractors in Japan and South Korea demonstrate willingness to adopt monthly-per-camera pricing models.
- Hybrid:Edge inference with cloud-based model updates and analytics aggregation.
- Integrated Systems:Bundled offerings combining PPE detection, access control, and incident reporting through single-dashboard subscriptions.
Regulatory lock-in favors On-Premise in European data-restrictive facilities. Commercial flexibility is expanding fastest in Cloud-Based channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's industrial corridor expansion under the PLI scheme is concentrating PPE detection procurement in domestic manufacturing zones, while construction safety digitization accelerates across United States, Germany, and Japan.
United States
OSHA workplace surveillance mandates drive automated hard hat and harness compliance verification at large-scale infrastructure sites. The Department of Labor's tightened enforcement protocols compress procurement timelines for computer vision systems. Texas and California construction corridors absorb the heaviest deployment volumes as federal infrastructure spending flows through state-level projects.
Germany
EU machinery safety standards and CE marking requirements mandate integrated safety monitoring in automotive and heavy manufacturing facilities. The EU AI Act's risk classification rules force human-in-the-loop verification redesigns for automated detection workflows. Bavarian automotive plants and North Rhine-Westphalia steel complexes lead upgrade cycles for multi-modal sensor fusion platforms.
Japan
METI industrial safety guidelines and JIS standards shape product specifications for construction and manufacturing procurement. Kansai region general contractors bundle PPE detection with access control through unified dashboard subscriptions. Tokyo-Osaka industrial corridors demonstrate strongest adoption of subscription-based SaaS pricing models among mid-sized contractors.
India
PLI scheme incentives for domestic manufacturing create first-mover opportunities for vendors establishing local assembly operations. Central Electricity Authority safety directives and state-level factory inspection digitization accelerate compliance-driven procurement. Gujarat and Maharashtra industrial zones concentrate the fastest deployment growth as foreign contractors enter domestic infrastructure projects.
South Korea
MFDS workplace safety digitization guidelines and construction sector automation subsidies expand addressable market for edge-processing detection systems. Seoul Capital Area contractors show willingness to adopt monthly-per-camera pricing, reducing upfront capital barriers. Busan-Ulsan shipbuilding complexes drive premium demand for explosion-proof hardware in hazardous area certification.
PPE Detection Market Competitive Landscape
Top-tier vendors anchor integrated safety ecosystems, while mid-tier specialists compete on AI-native architectures and regional deployment speed. The market structure tilts toward consolidation as facility managers demand bundled platform offerings over point solutions. Three archetypes dominate: diversified industrial conglomerates with building systems portfolios, pure-play computer vision specialists, and security hardware manufacturers extending into safety analytics. Competitive moves concentrate on strategic partnerships for edge hardware integration and vertical integration into sensor manufacturing to secure supply.
Within the diversified industrial tier, Honeywell International Inc and 3M exemplify platform bundling strategies that embed PPE detection within broader safety and building management ecosystems. Siemens AG occupies a position at the intersection of industrial automation and security infrastructure, leveraging control systems integration capabilities. Among pure-play specialists, Intenseye represents the AI-native archetype purpose-built for construction and manufacturing environments without legacy hardware dependencies.
| Leading Market Players |
|---|
| Honeywell International Inc |
| 3M |
| MSA Safety |
| Axis Communications AB |
| Intenseye |
| Wipro Limited |
| Siemens AG |
| Bosch Security Systems |
| Agile Lab |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between CE-marked sensor fusion systems and uncertified commodity camera hardware manifests in pricing spreads exceeding three-to-one, with supply chain configurations clustering around Taiwanese semiconductor fabs for premium edge processors versus mainland Chinese assembly for economy-tier visible-spectrum units. This divergence concentrates procurement authority among German automotive manufacturers demanding multi-modal accuracy guarantees while compressing margins for construction contractors sourcing sub-$200 per-unit camera hardware.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as GPU and edge processor supply concentration in Taiwanese fabrication creates 16-24 week standard lead times against 4-6 week expedited delivery at 35-50% markups. Three-tier pricing structure across premium sensor fusion, standard computer vision, and economy image processing segments reflects ISO/IEC certification investment differentials. Cost compression in the economy tier intensifies because Chinese camera module oversupply is forcing incumbent vendors to absorb freight and tariff exposure. Subscription-based SaaS channels demonstrate lowest price sensitivity among Japanese mid-sized contractors, while Indian PLI-scheme beneficiaries exhibit highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Dual-sourcing requirements mandated by German and French defense-sensitive facilities are fragmenting procurement across Taiwanese TSMC-fabricated edge processors and South Korean Samsung LSI alternatives to mitigate single-source vulnerability. Geographic supply concentration centers on Taiwan for semiconductors, China for camera module assembly, and Vietnam for enclosure manufacturing. Raw material dependencies include CMOS sensors from Sony and Omnivision, thermal imaging cores from FLIR and Seek Thermal, and aluminum extrusions for hazardous-area housings. Distribution runs through industrial automation distributors in Europe, security integrators in North America, and direct OEM relationships in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is eliminating point-solution specialists as facility managers demand bundled safety ecosystems, forcing sub-scale vendors toward acquisition or exit. This pressure concentrates competitive viability among integrated building technology providers and AI-native architectures with hardware-software convergence.
For Market Incumbents: Cement platform bundling advantages by integrating PPE detection with access control and incident reporting workflows, neutralizing pure-play computer vision specialists lacking building systems integration depth. Accelerate backward integration into edge processor supply through strategic partnerships with Taiwanese foundries, reducing exposure to 16-24 week lead time volatility that is eroding margin capture in competitive tenders.
For New Entrants and Emerging Players: Begin with India's PLI-scheme industrial corridors where domestic assembly requirements and foreign contractor entry create first-mover whitespace absent entrenched vendor relationships. Target mid-sized Japanese contractors through subscription-based SaaS pricing with monthly-per-camera models that reduce upfront capital barriers against incumbent capital equipment vendors.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-native computer vision specialists given EU AI Act compliance requirements forcing human-in-the-loop verification redesigns that favor software-centric architectures over legacy hardware-dependent platforms. Long-term viability favors vendors with demonstrated sensor fusion capabilities and established CE marking pathways. Watch for OSHA enforcement intensity in Texas and California infrastructure corridors as inflection indicator for North American demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Integration Partnership | Secures millisecond-latency alert capabilities against cloud-dependent competitors in German automotive plants. |
| CE Marking Pathway Acceleration | Compresses 12-18 month EU AI Act certification timelines for sensor fusion platforms in French manufacturing. |
| Subscription SaaS Channel Launch | Captures mid-sized contractor demand in Kansai region infrastructure projects through unified dashboard offerings. |
| Indian PLI Assembly Establishment | Qualifies for domestic manufacturing incentives while positioning for Central Electricity Authority safety digitization mandates. |
| Transformer Vision Model Deployment | Enables 50-meter-range harness verification for United States infrastructure contractors rewriting procurement scorecards. |
Research Methodology
OSHA enforcement bulletins, EU machinery directive amendments, and METI industrial safety guideline releases formed the secondary backbone for regulatory trajectory mapping, supplemented by SEC 10-K filings from diversified industrial conglomerates and customs records for edge processor import flows. Primary interviews with construction safety managers, automotive plant engineers, hospital biomedical compliance officers, and industrial automation procurement directors validated technology adoption timelines and pricing sensitivity thresholds. Bottom-up segment sizing across computer vision, sensor fusion, RFID, and image processing technologies triangulated against top-down market aggregation from facility manager IT budget allocations.
Historical trendline analysis of computer vision deployment velocity in United States construction sites established baseline penetration curves, with forward projection incorporating OSHA mandate enforcement intensity, EU AI Act implementation phases, and PLI scheme incentive disbursement schedules across the analysis window. Segmentation dimensions modeled include technology architecture, deployment architecture, end-user procurement authority, and application vertical. CAGRs derived from weighted average of technology-specific adoption curves and regulatory compliance-driven replacement cycles, with explicit incorporation of GPU supply lead time volatility and data residency requirement fragmentation as demand-shaping inputs.
Underlying measurement precision varies by segment; cloud-based deployment and construction application sizing carry tighter precision than on-premise defense-sensitive facilities and oil & gas hazardous area certification tiers. Forecasts reflect assumptions regarding OSHA inspection density maintenance, EU machinery directive harmonization progress, and Taiwanese semiconductor fabrication capacity expansion. Deviation in edge processor supply concentration or GDPR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market