
 Military Protection Glasses Market | 2026-2036
Military Protection Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Military Protection Glasses Market Intelligence
EU Green Deal procurement guidelines for sustainable defense equipment is consolidating military eyewear sourcing toward certified suppliers. Wiley X Inc. leverages its ANSI Z87.1 certification infrastructure to anchor Pentagon contracts. Revision Military Ltd. dominates Canadian and British military tenders through in-house ballistics testing. 3M Company sustains broad channel control across NATO logistics networks.
Military protection glasses are optical devices engineered to withstand high-velocity fragment impacts, typically incorporating polycarbonate or Trivex lenses rated to MIL-PRF-32432 standards for ballistic resistance. Their primary purpose is preserving visual acuity under combat, training, and tactical operations where conventional eyewear would fail. Ballistic goggles capture the largest revenue pool among product types due to full-seal requirements in chemical and desert environments. Polycarbonate material leads volume given its strength-to-weight ratio, though Trivex is gaining share in aviator and special operations applications where optical clarity at thickness matters.
FDA oversees impact-testing methodologies for prescription military lenses, while OSHA workplace standards extend to domestic defense manufacturing facilities. The EU AI Act and MDR frameworks increasingly govern smart eyewear with heads-up displays. Buyers must weigh dual-certification costs against single-standard compliance as procurement rules fragment across the Atlantic.
Market Dynamics
Ballistic eyewear procurement is absorbing dual-certification mandates as NATO defense agencies harmonize MIL-PRF-32432 with EU Green Deal sustainability criteria, forcing suppliers to rebuild testing infrastructure around merged compliance tracks rather than parallel standards.
Growth Catalysts
- US Army PEO Soldier mandate:Stricter impact standards for ground forces are accelerating replacement cycles across active-duty and National Guard units, creating sustained demand for next-generation ballistic lenses.
- Polycarbonate-Trivex hybridization:Advanced lens materials combining impact resistance with optical clarity are penetrating aviator and special operations segments previously limited by weight constraints.
- REACH chemical compliance:EU defense procurement rules now embed sustainable chemistry requirements, redirecting sourcing toward certified suppliers with verified supply chain transparency.
Market Restraints
- Petrochemical input volatility:Polycarbonate resin prices fluctuate with benzene and bisphenol-A feedstock markets, compressing margin predictability for mid-tier manufacturers without long-term supply contracts.
- Testing facility concentration:Ballistics certification infrastructure clusters in the United States and Germany, creating geographic bottlenecks for suppliers seeking NATO-wide qualification.
- Prescription lens complexity:FDA impact-testing protocols for corrective military eyewear extend development timelines by 8-14 months versus plano lenses, limiting rapid product iteration.
Strategic Opportunities
- Smart eyewear convergence:EU AI Act and MDR frameworks are creating regulated pathways for heads-up display integration, opening procurement channels for electro-optical subsystem suppliers.
- Canadian Forces modernization:Underpenetrated relative to US and UK per-capita spending, Canadian defense procurement is expanding ballistic goggle orders for Arctic and chemical warfare training scenarios.
- Direct defense agency contracting:Bypassing traditional distribution layers through GSA schedule and NATO Support and Procurement Agency frameworks is capturing margin previously allocated to channel intermediaries.
Industry Challenges
- Dual-certification engineering:Simultaneous MIL-PRF-32432 and ANSI Z87.1 qualification requires redundant testing protocols, straining R&D bandwidth at smaller specialty manufacturers.
- Optical metrology talent scarcity:Ballistic lens design demands rare combinations of polymer chemistry and ophthalmic optics expertise, with defense-cleared personnel particularly concentrated in New England and Bavaria clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Protection Glasses Market |
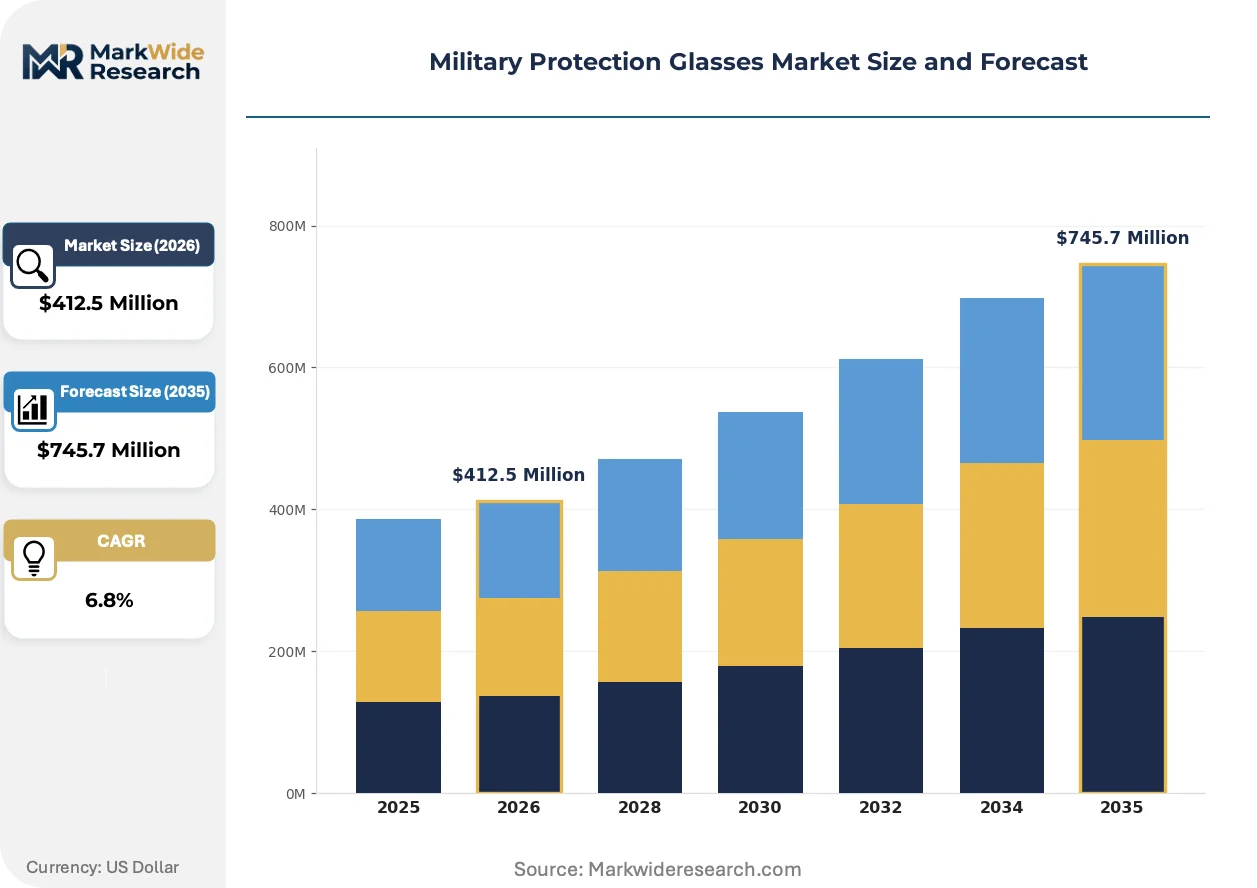
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Goggles, Tactical Glasses, Anti-Fog Glasses, Sunglasses Material: Polycarbonate, Trivex, Glass, Acrylic Technology: Anti-Scratch, Anti-Reflective, UV Protection, Photochromic End User: Military Personnel, Security Forces, Outdoor Enthusiasts, Law Enforcement |
| Companies Covered | Wiley X Inc., 3M Company, Revision Military Ltd., Saint-Gobain Sully, PerriQuest Defense Research Enterprises, Oakley, Inc., Honeywell Safety Products, Smith Optics, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Protection Glasses Market Strategic Shifts & Innovations
Active integration of smart technologies into protective eyewear is compressing traditional product boundaries, while regulatory fragmentation across Atlantic defense procurement is forcing architectural redesigns of compliance systems.
Photocromatic and electrochromic lens technologies are absorbing battlefield variable-light requirements previously addressed by interchangeable lens systems. Special operations units in the United States and Germany are field-testing these solutions for rapid deployment scenarios. The technology is absorbing inventory complexity from logistics chains by collapsing multiple lens tints into single SKUs.
EU AI Act algorithmic transparency mandates are reshaping development roadmaps for heads-up display systems in military eyewear. Manufacturers must now document decision-logic for threat-identification overlays, extending firmware validation cycles. Smart goggle segments targeting chemical and biological detection are most affected, with vendors restructuring software architectures around explainable AI frameworks.
Defense procurement offices are consolidating vendor lists around dual-certified suppliers capable of serving both US and European contract vehicles simultaneously. Traditional single-market specialists face exclusion from multi-national NATO tenders. This concentration is most visible in German and British defense procurement, where framework agreements now prioritize trans-Atlantic compliance breadth over regional cost optimization.
Military Protection Glasses Market Segmentation
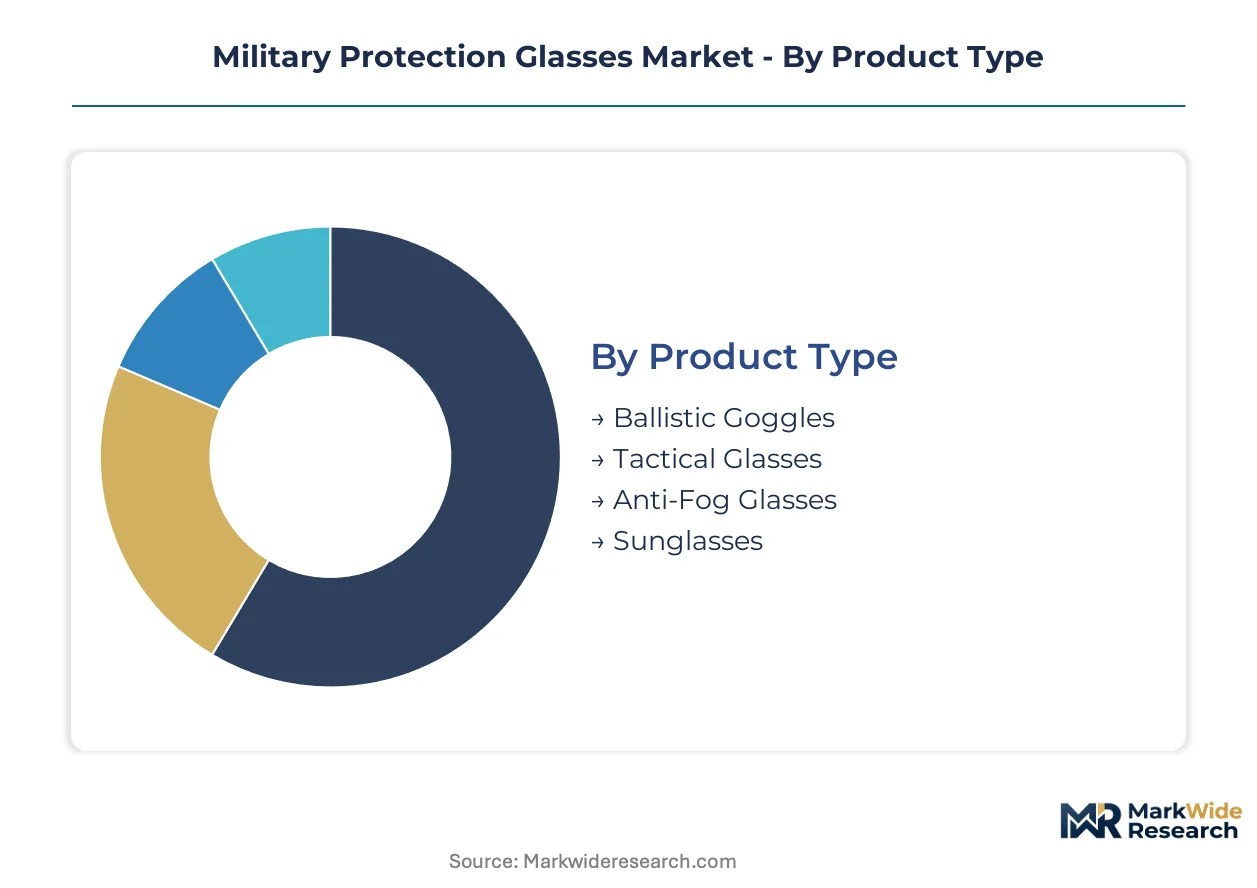
Military eyewear segmentation reflects divergent capital requirements across ballistic certification tiers. Product type and material selections drive testing infrastructure investments, while technology integration and end-user specifications determine R&D allocation priorities.
Product Type:
Ballistic goggles demand the heaviest upfront capital for full-seal molding equipment and chemical warfare compatibility testing. Tactical glasses require lower initial tooling investment but face compressed margins from dual-certification overhead.
- Ballistic Goggles:Full-seal designs incorporate multi-layer ventilation systems rated for MIL-PRF-32432 fragment protection. US Army PEO Soldier program orders concentrate demand for desert and chemical warfare variants where seal integrity is non-negotiable.
- Tactical Glasses:Open-frame configurations prioritize peripheral vision and rapid lens interchange. German Bundeswehr procurement channels favor these for urban combat training scenarios where weight reduction outweighs full environmental sealing.
- Anti-Fog Glasses:Hydrophilic coating lines require cleanroom capital expenditure.
- Sunglasses:Polarized and non-polarized variants serve rear-echelon and training applications.
Ballistic goggles absorb the bulk of installed capacity; tactical glasses are expanding most quickly.
Material:
Raw material selection governs polymer chemistry R&D intensity and optical metrology equipment requirements. Trivex production demands specialized monomer synthesis capabilities that concentrate supplier power.
- Polycarbonate:Bisphenol-A derived resins deliver the highest strength-to-weight ratio for ground force applications. REACH chemical compliance mandates are redirecting European defense procurement toward verified supply chain transparency for this feedstock.
- Trivex:Urethane-based pre-polymer chemistry achieves superior optical clarity at equivalent thickness. Aviator and special operations units in the United States specify Trivex for prescription lens applications where refractive precision matters.
- Glass:Limited to legacy naval and ceremonial applications due to weight penalties.
- Acrylic:Training and simulation markets absorb lower-cost alternatives.
Polycarbonate dominates current volume shipments; Trivex is climbing the fastest among certified military grades.
Technology:
Surface treatment and adaptive optics capabilities separate premium contract tiers from commodity supply. Photochromic integration requires electro-optical subsystem partnerships that extend development timelines.
- Photochromic:Silver halide or naphthopyran chemistry enables rapid tint adjustment across variable battlefield lighting. Special operations field testing in Germany and the United States is collapsing multiple lens SKUs into single adaptive units.
- Anti-Scratch:Diamond-like carbon and silica-based hardcoats extend service life under abrasive conditions.
- Anti-Reflective:Multi-layer vapor deposition reduces signature detection risk.
- UV Protection:Standard additive packages meet baseline occupational health requirements.
Anti-scratch coatings represent the baseline technology installed across all military contracts; photochromic solutions are gaining share fastest among next-generation procurement specifications.
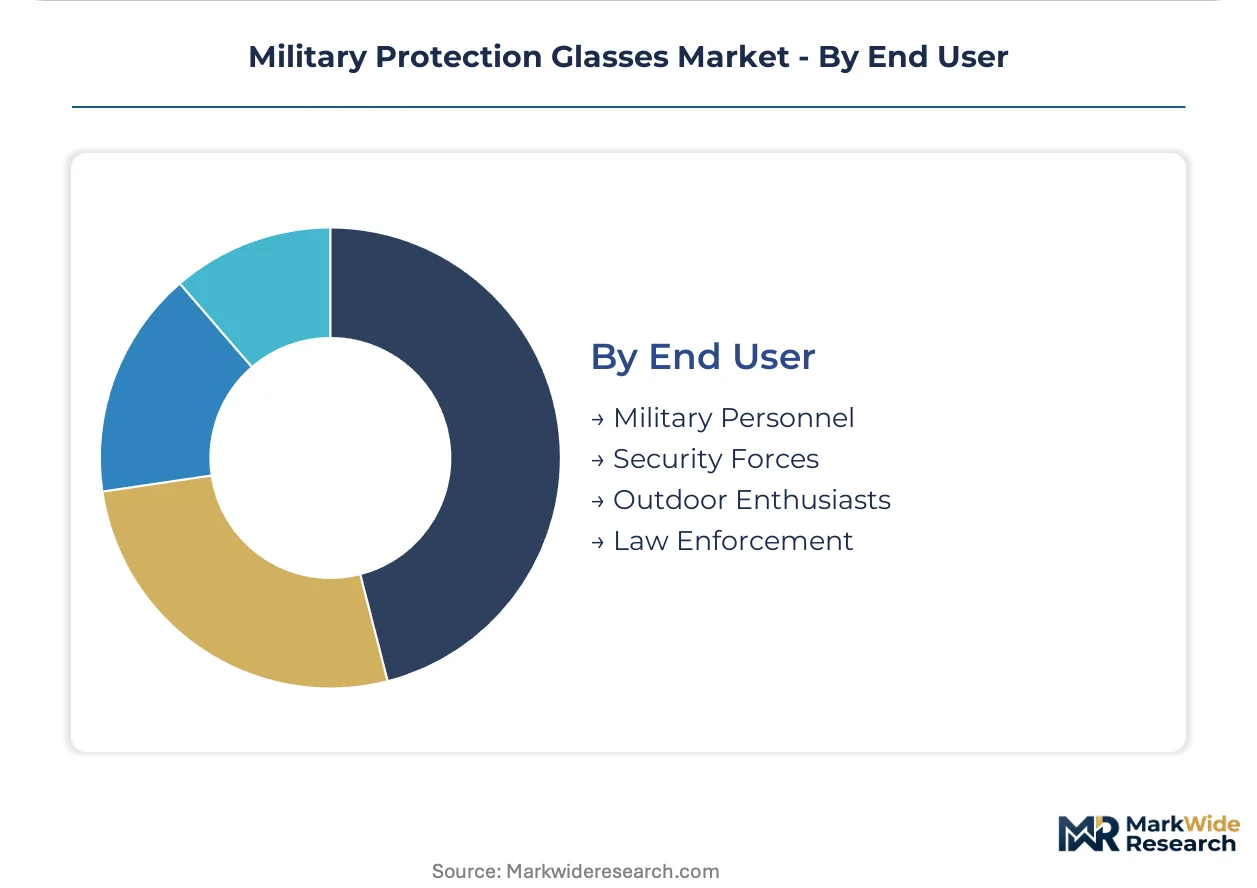
End User:
Customer type determines certification stringency and prescription complexity, with defense agency contracts requiring cleared personnel and specialized optical design expertise.
- Military Personnel:Active-duty specifications mandate MIL-PRF-32432 ballistic rating plus interoperability with helmet and communication systems. FDA impact-testing protocols for prescription variants extend development cycles substantially versus plano alternatives.
- Security Forces:Private military contractors and embassy security details purchase through GSA schedule vehicles with reduced documentation overhead.
- Law Enforcement:SWAT and tactical police units adopt military-surplus specifications with ANSI Z87.1 compliance.
- Outdoor Enthusiasts:Civilian tactical markets absorb commercial variants without defense-grade certification.
Military personnel accounts for the dominant share of certified production capacity; security forces are expanding most quickly as private contracting volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the military protection glasses industry through concentrated ballistics testing infrastructure and defense procurement headquarters. The metropolitan corridor hosts cleared optical metrology talent pools and MIL-PRF-32432 certification facilities serving NATO supply chains.
United States
US Army PEO Soldier program mandates drive replacement cycles for active-duty and National Guard units. FDA impact-testing protocols govern prescription military lens approvals, extending development timelines versus plano alternatives. Boston and New England clusters concentrate defense-cleared optical design personnel and ballistics certification laboratories.
Germany
Bundeswehr procurement channels favor tactical glasses for urban combat training scenarios. EU Green Deal procurement guidelines embed sustainable chemistry requirements through REACH compliance verification. Bavaria hosts specialized polymer chemistry expertise and ophthalmic optics talent concentrated around Munich and Nuremberg industrial zones.
Canada
Canadian Forces modernization expands ballistic goggle orders for Arctic and chemical warfare training scenarios. Health Canada oversees domestic defense manufacturing facility standards extending OSHA-equivalent workplace protections. Revision Military Ltd. dominates Canadian military tenders through in-house ballistics testing capabilities.
United Kingdom
British military tenders concentrate demand for full-seal ballistic goggles meeting desert and chemical warfare specifications. EU AI Act and MDR frameworks increasingly govern smart eyewear with heads-up displays entering service. Framework agreements prioritize trans-Atlantic compliance breadth over regional cost optimization.
France
French defense procurement consolidates vendor lists around dual-certified suppliers capable of serving US and European contract vehicles simultaneously. ANSM and CNIL oversight extends to algorithmic transparency for threat-identification overlay systems. Paris and Île-de-France defense industrial bases absorb electro-optical subsystem integration requirements.
Military Protection Glasses Market Key Industry Players
The competitive structure tilts toward defense-specialized fabricators with cleared personnel and in-house ballistics testing infrastructure. Tiered concentration separates MIL-PRF-32432 certified suppliers from commercial-industrial crossover players. Three archetypes dominate: integrated defense contractors with captive optical divisions, pure-play military eyewear specialists, and diversified safety equipment conglomerates. M&A activity targets prescription lens capabilities and smart eyewear electro-optical subsystems.
Within the defense-specialized tier, Revision Military Ltd. and Wiley X Inc. exemplify archetypes built around cleared testing infrastructure and ANSI Z87.1 certification anchoring. Gentex Corporation occupies a position representing integrated defense contractors with multi-platform helmet and communication system interoperability. These three entities sit within the concentrated vendor base capturing NATO framework agreement volumes.
| Leading Market Players |
|---|
| Wiley X Inc. |
| 3M Company |
| Revision Military Ltd. |
| Saint-Gobain Sully |
| PerriQuest Defense Research Enterprises |
| Oakley, Inc. |
| Honeywell Safety Products |
| Smith Optics |
| Gentex Corporation |
| Others |
Cost & Logistics Intelligence
Benzene spot prices and bisphenol-A futures cascade through polycarbonate resin costs into three distinct procurement tiers for military eyewear, with REACH-compliant European feedstock commanding premium placement against standard-grade Asian-sourced material.
Pricing Analysis
Ballistic certification throughput anchors value-based pricing for military protection glasses, with MIL-PRF-32432 qualification status separating premium contract tiers from commercial-industrial crossover supply. Price differentiation hinges on dual-certification breadth and prescription lens complexity, with FDA-cleared corrective variants capturing substantially higher unit economics than plano alternatives. Cost compression in mid-tier tactical glasses is intensifying because REACH chemical compliance mandates are redirecting European defense procurement toward verified supply chain transparency. Private military contractors purchasing through GSA schedule vehicles exhibit highest price sensitivity, while active-duty defense agencies prioritize certification reliability over procurement cost.
Supply Chain Analysis
MIL-PRF-32432 and ANSI Z87.1 qualification gating concentrates certified lens production in the United States, Germany, and Canada, with ballistics testing infrastructure clustering around Boston and Bavaria industrial zones. Raw material dependencies draw from bisphenol-A derived polycarbonate resins, urethane-based Trivex pre-polymers, and silver halide photochromic chemistry. Single-source vulnerability runs through concentrated ballistics certification laboratories, where cleared optical metrology talent scarcity creates qualification bottlenecks. Distribution runs through NATO Support and Procurement Agency frameworks and GSA schedule vehicles, bypassing traditional channel intermediaries for direct defense agency contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military protection glasses procurement is becoming a vertical-integration race, with in-house ballistics testing capabilities and captive polymer chemistry R&D emerging as the decisive upstream levers separating tier-one defense contractors from excluded specialists.
For Market Incumbents: Anticipate consolidation pressure from electro-optical subsystem suppliers entering smart eyewear segments through EU AI Act compliance pathways. Defend position by deepening backward integration into Trivex monomer synthesis and acquiring prescription lens capabilities to compress FDA validation timelines. Priority investments should center on dual-certification testing infrastructure serving both US and European contract vehicles simultaneously. For New Entrants and Emerging Players: Launch via direct NATO Support and Procurement Agency contracting to bypass entrenched distribution layers and capture margin allocated to channel intermediaries. Canadian Forces modernization for Arctic and chemical warfare training scenarios represents the most penetrable white-space geography, with ballistic goggle orders expanding faster than per-capita spending comparisons suggest. Target electro-optical subsystem partnerships for photochromic integration rather than competing on commodity polycarbonate volume. For Investors and Strategic Acquirers: Distressed-cycle entries favor prescription-capable specialists with FDA-cleared manufacturing infrastructure in New England or Bavaria clusters, where defense-cleared optical design personnel concentrate. Long-term viability over a multi-year horizon hinges on smart eyewear convergence readiness under EU AI Act and MDR frameworks. The signal to watch is framework agreement consolidation toward dual-certified suppliers capable of serving trans-Atlantic procurement simultaneously.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trivex Monomer Synthesis | Captive supply of urethane-based pre-polymer chemistry reduces feedstock price volatility exposure for aviator-grade lens production. |
| Dual-Certification Testing Infrastructure Expansion | Merged MIL-PRF-32432 and ANSI Z87.1 qualification tracks unlock NATO framework agreement access previously blocked to single-market specialists. |
| Prescription Lens Capability Acquisition | FDA-corrective manufacturing compresses 8-14 month development timelines that currently limit rapid product iteration cycles. |
| Electro-Optical Subsystem Partnership | Photochromic and heads-up display integration opens procurement channels under EU AI Act algorithmic transparency mandates. |
| Direct Defense Agency Contracting | GSA schedule and NATO Support and Procurement Agency frameworks capture margin previously allocated to distribution intermediaries. |
Research Approach
Independent corroboration across defense procurement officers, optical design engineers, polymer chemistry R&D directors, and ballistics testing laboratory managers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation from MIL-PRF-32432 certification records, FDA 510(k) filings for prescription military lenses, REACH chemical compliance databases, and NATO Support and Procurement Agency contract award disclosures. Bottom-up unit economics modeling and top-down defense budget allocation analysis were triangulated to establish segmentation boundaries.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics within each product type, material grade, technology tier, and end-user specification. The forecast framework models ballistic goggles, tactical glasses, anti-fog glasses, and sunglasses across polycarbonate, Trivex, glass, and acrylic substrates, with further disaggregation by photochromic, anti-scratch, anti-reflective, and UV protection technology integration. CAGRs were derived from replacement cycle analysis tied to US Army PEO Soldier program mandates and EU Green Deal procurement guideline implementation timelines. Defense budget trajectory assumptions and petrochemical feedstock price elasticity informed scenario-weighted outputs.
Defense procurement cancellation, REACH chemical compliance enforcement variance, and smart eyewear regulatory interpretation shifts are the dominant revision risks to the baseline forecast. A model refresh is warranted upon material change in NATO framework agreement consolidation patterns or dual-certification mandate harmonization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market