
 South America Protective Coating Market | 2026-2036
South America Protective Coating Market Size, Share, and Industry Trends Forecast 2026-2036
South America Protective Coating Market Analytics
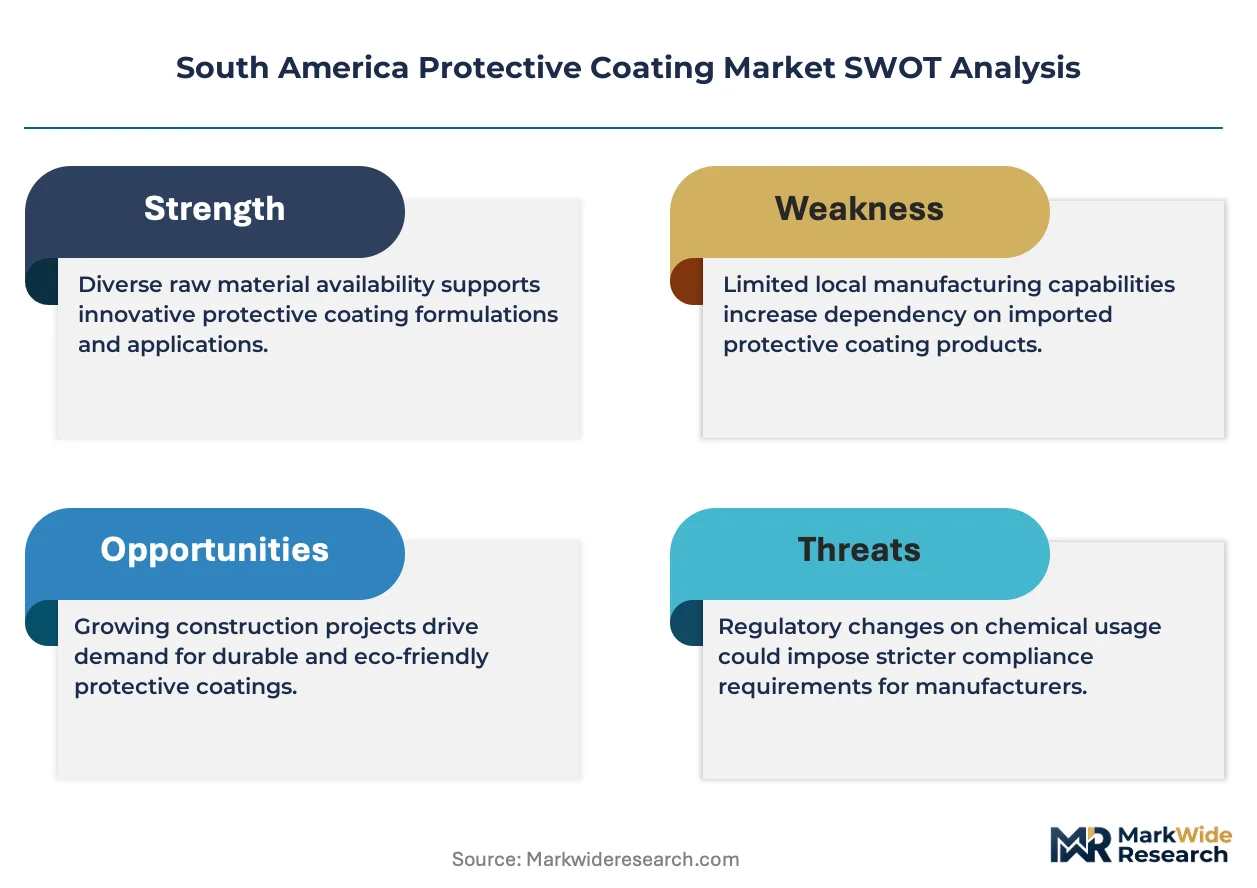
Brazil's southeastern petrochemical corridor is rewriting regional supply dynamics for protective coatings. PPG Industries leverages its Brazilian manufacturing footprint to anchor epoxy and polyurethane supply chains across the Mercosur zone. Akzo Nobel N.V. competes through water-based technology leadership, while Renner Herrmann SA dominates local formulation capabilities for tropical humidity conditions. Axalta Coating Systems LLC extends its automotive refinish presence into industrial protective segments through dedicated Brazilian technical centers.
Protective coatings are engineered barrier systems—typically comprising epoxy resins, polyurethane binders, or acrylic polymers applied at dry film thicknesses of 150–500 microns—designed to prevent substrate degradation from corrosion, chemical attack, and ultraviolet radiation in aggressive environments. Epoxy formulations lead industrial application volumes due to superior adhesion and chemical resistance on steel infrastructure, while water-based technology represents the fastest-growing segment as Brazilian environmental agencies tighten volatile organic compound emission limits for solvent-borne systems. Powder coating occupies a specialized niche in high-durability automotive and appliance components where zero-VOC compliance and thick-film build are simultaneously required.
Brazil's CONAMA resolutions and Argentina's Secretariat of Environment and Sustainable Development enforce progressively stricter VOC thresholds that redirect formulation investments toward compliant water-based and high-solids platforms. ANVISA oversight of chemical substances in industrial coatings adds a secondary compliance layer affecting raw material sourcing decisions for multinationals operating across Mercosur. Stakeholders must monitor regulatory divergence between Brazilian federal standards and emerging provincial frameworks in Argentina to anticipate reformulation costs and local certification timelines.
Market Dynamics
Brazil's CONAMA Resolution 524/2021 and its Argentine equivalent are compressing formulation cycles across the Mercosur zone, forcing solvent-borne epoxy suppliers to retool water-based platforms within 18-month compliance windows or surrender industrial tenders.
Growth Catalysts
- Offshore Platform Maintenance:Brazil's pre-salt oilfields require high-performance marine coatings for riser and hull protection in corrosive Atlantic conditions.
- CONAMA VOC Limits:Brazilian federal emission thresholds accelerate water-based polyurethane adoption across São Paulo state's manufacturing base.
- Southeastern Industrial Corridor Concentration:Petrobras refining complexes and Itaipu hydroelectric infrastructure generate sustained demand for chemical-resistant epoxy systems.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin prices fluctuate with naphtha costs from Brazil's COMPERJ complex delays, squeezing formulation margins.
- Import Dependency for Isocyanates:Polyurethane hardener supply concentrates through Argentine and Chilean ports, exposing coating plants to customs bottlenecks.
- Tropical Cure Limitations:High-humidity application windows restrict solvent-free epoxy deployment during Amazon basin wet seasons.
Strategic Opportunities
- Colombian Infrastructure Gap:Bogotá's TransMilenio expansion and Pacific port upgrades lack qualified protective coating applicators.
- Photovoltaic Array Coatings:Chile's Atacama solar farms require UV-resistant fluoropolymer topcoats for tracker mechanism longevity.
- ANVISA Chemical Registration:Simplified substance notification pathways incentivize multinationals to localize Brazilian R&D facilities.
Industry Challenges
- Certified Applicator Shortage:NACE/SSPC-qualified inspectors remain scarce outside Rio de Janeiro and Santos port zones.
- Legacy Inventory Stranded Costs:Distributors face write-downs on high-VOC solvent stocks as provincial Brazilian environmental agencies accelerate enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Protective Coating Market |
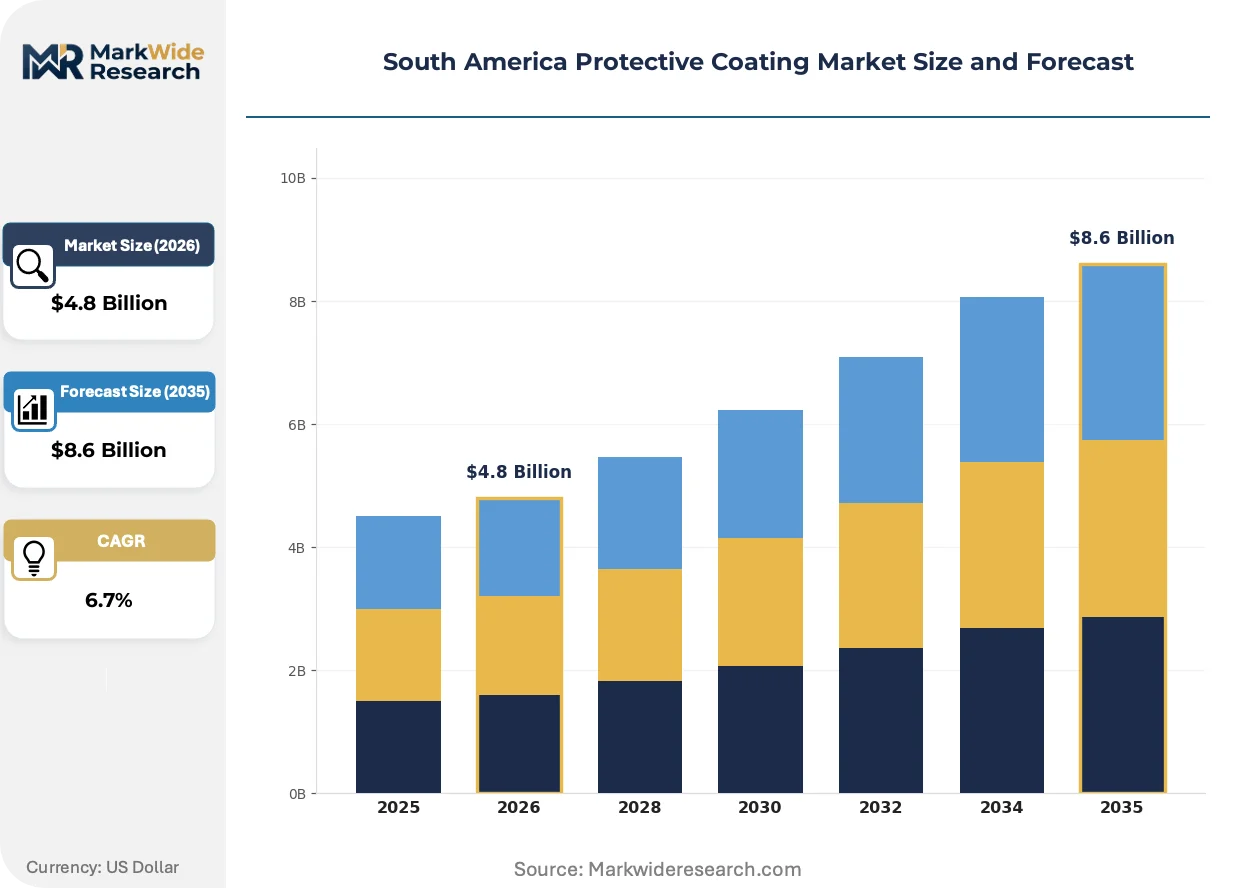
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End User: Construction, Automotive, Marine, Aerospace Application: Industrial, Residential, Commercial, Infrastructure Technology: Water-Based, Solvent-Based, High Solids, Powder Coating |
| Companies Covered | PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, BASF SE, Renner Herrmann SA, Axalta Coating Systems LLC, RPM International Inc., Henkel AG & Company, 3M Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Protective Coating Market Evolving Landscape
Formulation chemistry and application protocols across South America are pivoting toward compliance-first architectures that embed environmental performance into product design rather than treating regulation as a downstream constraint.
Water-borne epoxy systems with hybrid silane-modified backbones are penetrating Brazil's tank lining segment. Petrobras maintenance contractors specify these platforms for crude oil storage refurbishment. Solvent-borne phenolic epoxies are rendering obsolete for internal floating roof applications.
Argentina's Secretariat of Environment and Sustainable Development implemented Resolution 135/2023, aligning VOC thresholds with Brazilian CONAMA standards. This harmonization reduces cross-border formulation complexity for Mercosur suppliers. Paraguayan and Uruguayan industrial buyers now demand dual-certified products.
Asset owners in Chile's mining sector now procure coating systems through total-cost-of-ownership contracts rather than unit-price tenders. Codelco's divisional engineering teams evaluate 15-year lifecycle performance. This procurement evolution concentrates contract awards among suppliers with in-house inspection capabilities.
South America Protective Coating Market Segmentation
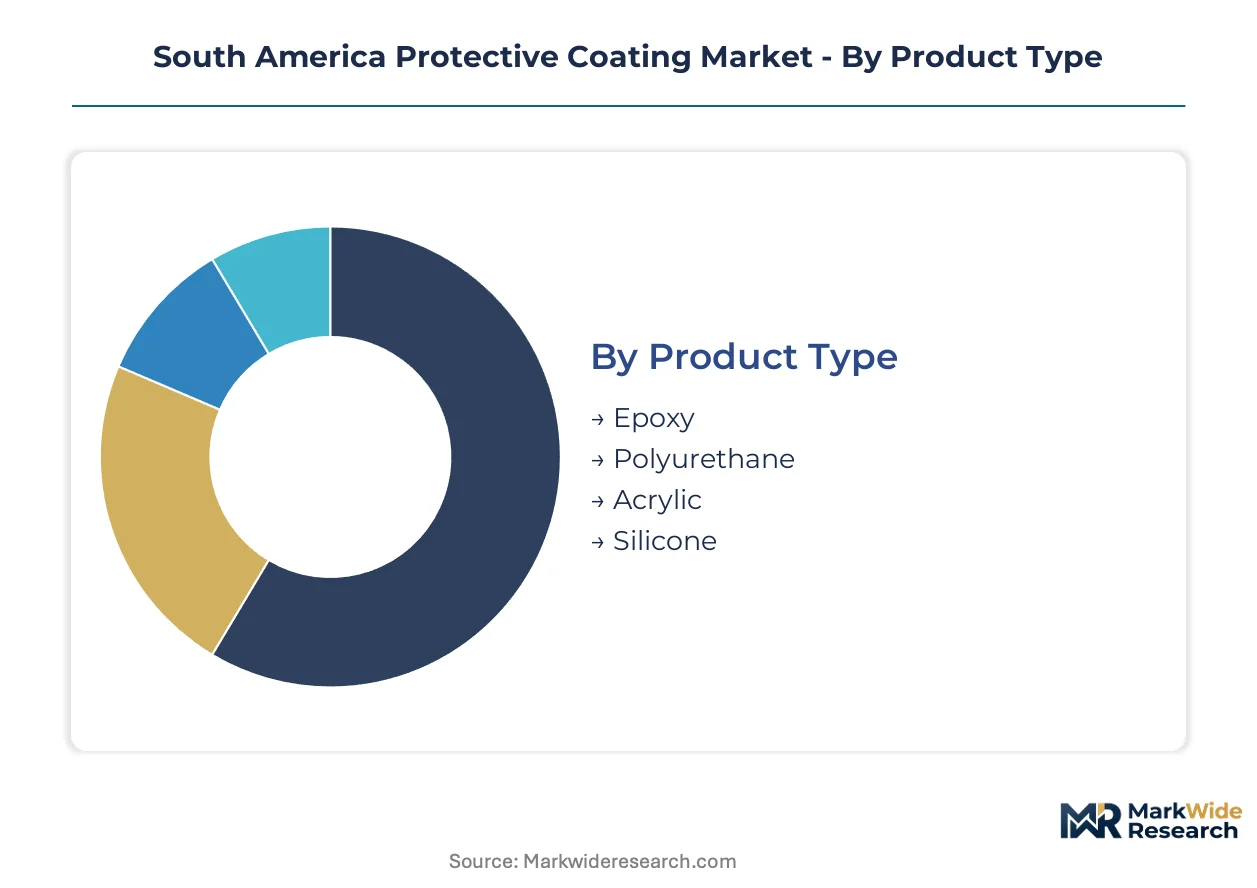
Protective coating procurement across South America fragments across four critical dimensions that determine formulation specifications, compliance requirements, and margin structures. Product chemistry dictates performance ceilings in corrosive environments. End-use verticals impose distinct certification and application protocols. Technology platforms separate compliant suppliers from stranded inventory holders.
Product Type:
Replacement cycles vary dramatically by resin chemistry—epoxy systems demand recoating every 5-7 years in marine exposure, while silicone topcoats extend maintenance intervals beyond 15 years in high-UV applications.
- Epoxy:Two-component thermoset systems combining bisphenol-A resins with polyamine hardeners deliver superior adhesion to blasted steel and chemical resistance against petroleum derivatives. Brazilian Petrobras contractors specify these formulations for offshore platform hull maintenance in Atlantic salt spray conditions, though tropical humidity compresses application windows during wet seasons.
- Polyurethane:Aliphatic and aromatic variants provide flexible, UV-stable topcoats with abrasion resistance for dynamic structural elements. Demand concentrates in São Paulo state's automotive manufacturing corridor, where CONAMA VOC limits are accelerating water-based polyurethane adoption for plant infrastructure protection.
- Acrylic:Thermoplastic emulsions offering rapid dry-to-touch properties and architectural color retention dominate Brazilian commercial building maintenance contracts.
- Silicone:Inorganic-organic hybrid polymers withstand temperature cycling from -50°C to 200°C in Chilean mining smelter exhaust stacks.
Epoxy anchors the volume base while polyurethane gains share at the steepest rate.
End User:
Margin structures diverge sharply by vertical—marine and aerospace command premium pricing for certified applicator networks, while construction tolerates commodity-grade formulations.
- Construction:Reinforced concrete protection and steel structural fireproofing drive specification of intumescent epoxy systems across Brazil's southeastern industrial corridor.
- Automotive:Electrophoretic primers and chip-resistant underbody coatings require OEM-qualified supply chains with ANVISA-registered raw material traceability.
- Marine:Antifouling biocide formulations and cathodic-compatible hull coatings face ANVISA environmental release scrutiny for Brazilian-flagged vessels.
- Aerospace:Chromate-free pretreatments and polyurethane topcoats meeting OEM specifications concentrate maintenance demand at São Paulo's Congonhas and Guarulhos MRO clusters.
Construction absorbs the highest absolute volume while aerospace climbs the fastest on per-kilogram value metrics.
Application:
Application environment determines film thickness requirements, surface preparation standards, and inspection protocols—industrial specifications exceed residential thresholds by 3-5x on dry film thickness.
- Industrial:Tank linings, pipeline exteriors, and processing equipment in Brazilian petrochemical complexes specify 300-500 micron epoxy builds with NACE-certified inspection.
- Residential:Decorative-protective hybrid coatings for metal roofing and fencing emphasize cost efficiency over extended service life in Argentine and Colombian housing markets.
- Commercial:High-traffic floor coatings and facade protection in retail and office developments prioritize rapid cure schedules to minimize tenant disruption.
- Infrastructure:Bridge expansion joint coatings and highway barrier protection in Colombia's Andean road network require flexible polyurethane formulations accommodating thermal movement.
Industrial applications dominate current procurement value while infrastructure contracts are expanding most quickly on public spending acceleration.
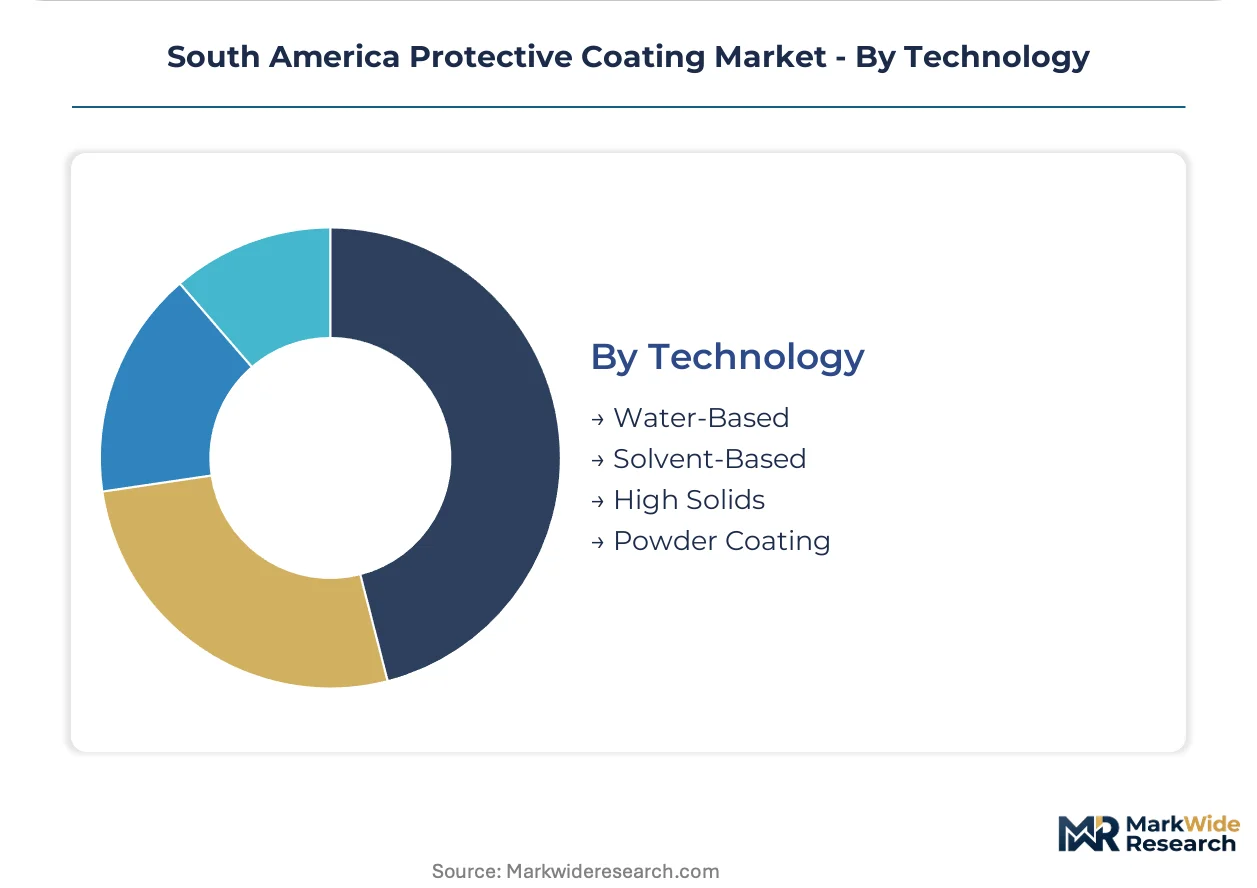
Technology:
Compliance trajectory separates platform viability—water-based systems now meet 80% of former solvent-borne performance specifications while eliminating VOC exposure liability.
- Water-Based:Acrylic and polyurethane dispersions with sub-100 g/L VOC content capture Brazilian manufacturing plant maintenance contracts as CONAMA enforcement tightens.
- Solvent-Based:High-build epoxy and alkyd formulations retain niche positions in field-applied marine maintenance where water sensitivity precludes aqueous systems.
- High Solids:80-90% volume solids epoxy and polyurethane systems bridge compliance and performance for Brazilian tank lining contractors facing wet-season humidity constraints.
- Powder Coating:Thermoset epoxy-polyester hybrids deliver zero-VOC, edge-protected finishes for automotive underhood components and appliance housings in Mercosur manufacturing.
Solvent-based technology retains installed-base maintenance revenue while water-based platforms capture the steepest share gains on new specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epoxy resin formulation capacity clusters along Brazil's southeastern petrochemical corridor, with import-dependent supply chains extending through Argentine ports and Chilean mining districts. Brazilian CONAMA enforcement and Argentine regulatory harmonization are compressing cross-border formulation windows.
Brazil
Petrobras pre-salt offshore maintenance drives marine coating specifications for riser and hull protection in Atlantic salt spray. ANVISA chemical substance oversight adds compliance layers for raw material sourcing decisions. São Paulo and Rio de Janeiro states concentrate demand within the southeastern industrial corridor spanning refining complexes and manufacturing infrastructure.
Argentina
Automotive assembly plants in Córdoba and Buenos Aires provinces specify OEM-qualified coating supply chains with ANVISA-registered traceability. Secretariat of Environment and Sustainable Development Resolution 135/2023 aligned VOC thresholds with Brazilian CONAMA standards. Rosario-Santa Fe petrochemical corridor generates chemical-resistant epoxy demand for agrochemical processing equipment.
Chile
Codelco copper smelter exhaust stacks and Atacama solar farm tracker mechanisms require UV-resistant fluoropolymer topcoats and temperature-cycling silicone systems. Mining sector procurement shifted to total-cost-of-ownership contracts evaluating 15-year lifecycle performance. Antofagasta and Calama mining clusters concentrate contract awards among suppliers with in-house inspection capabilities.
Colombia
Bogotá TransMilenio expansion and Pacific port upgrades face qualified protective coating applicator shortages for bridge expansion joint and highway barrier protection. Andean road network thermal movement demands flexible polyurethane formulations. Barranquilla and Cartagena port industrial zones attract Brazilian formulation suppliers seeking Andean market entry.
Peru
Antamina and Cerro Verde copper concentrate processing facilities specify chemical-resistant tank linings for sulfuric acid exposure. Ministry of Environment VOC enforcement lags Brazilian CONAMA timelines, extending solvent-borne system viability. Lima-Callao industrial corridor imports Brazilian water-based polyurethane platforms for manufacturing plant infrastructure protection.
South America Protective Coating Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on resin and hardener supply. The South America protective coating market structures around three tiers: multinational formulation platforms with Mercosur manufacturing footprints, regional specialists in tropical humidity conditions, and import-dependent distributors serving Andean markets. Archetypes include water-based technology leaders, epoxy-polyurethane hybrid specialists, and powder coating zero-VOC providers. Competitive moves concentrate on water-based platform retooling within 18-month compliance windows and technical center localization to capture ANVISA registration advantages.
Among multinational platforms, PPG Industries, Inc. and Akzo Nobel N.V. exemplify formulation breadth across solvent-to-water technology transitions. Renner Herrmann SA occupies a position as a Brazilian S.A.-structured specialist in tropical condition adaptation. These three anchors represent divergent strategic postures: global platform scale versus localized formulation responsiveness versus regulatory compliance velocity.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| BASF SE |
| Renner Herrmann SA |
| Axalta Coating Systems LLC |
| RPM International Inc. |
| Henkel AG & Company |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazilian epoxy resin production drives raw material premiums and forces formulation plants to absorb margin compression or pass costs to Petrobras contractors. This utilization squeeze concentrates pricing power among Mercosur suppliers with captive resin supply while squeezing independent blenders dependent on Argentine import channels.
Pricing Analysis
CONAMA Resolution 524/2021 dictates the pricing tier structure across Brazilian protective coatings, separating ANVISA-registered water-based platforms from stranded high-VOC solvent inventories. Certification-grade differentiation separates NACE-compliant marine systems from commodity construction coatings, with aftermarket service bundling widening spreads between premium applicator networks and independent distributors. Cost compression in water-based polyurethane runs through São Paulo manufacturing plants as CONAMA enforcement accelerates. Construction end-users exhibit highest price sensitivity, while Petrobras offshore maintenance contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Import dependency for isocyanate hardeners between Argentina and Brazil dominates supply chain risk, exposing polyurethane formulation plants to customs bottlenecks at Rosario and Santos ports. Epoxy resin production centers on Brazil's southeastern petrochemical corridor, while aliphatic isocyanates feed from Chilean and Argentine import channels. Raw material sourcing draws from naphtha derivatives, polyamine hardeners, and titanium dioxide pigments. Single-source vulnerability concentrates in isocyanate supply through Buenos Aires province distributors. Distribution runs through certified applicator networks anchored in Rio de Janeiro and Santos industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based technology disruption is compressing 18-month compliance windows across Mercosur, creating winner-take-most dynamics for suppliers with localized R&D and ANVISA registration capabilities.
For Market Incumbents: Insulate core epoxy-polyurethane margins by securing captive bisphenol-A supply from Brazil's COMPERJ complex and accelerating water-based platform certification ahead of provincial CONAMA enforcement waves. Vertical integration into hardener production hedges Argentine import exposure. For New Entrants and Emerging Players: Build out technical service capabilities in Colombia's Andean infrastructure corridor, where qualified applicator scarcity creates white-space for inspection-certified coating systems. Target Bogotá's TransMilenio expansion and Pacific port upgrades through Brazilian partnership structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among water-based technology platforms with ANVISA-registered formulation libraries and Petrobras maintenance contracts. Five-to-ten year viability favors specialists with tropical humidity application protocols over commodity solvent-borne distributors. Monitor CONAMA provincial enforcement acceleration as inflection signal for stranded inventory write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Platform Retooling | CONAMA compliance deadlines force 18-month formulation cycles or tender exclusion. |
| ANVISA Registration Localization | Brazilian R&D facilities capture simplified substance notification pathways. |
| Applicator Network Certification | NACE-qualified inspection capabilities secure Codelco total-cost-of-ownership contracts. |
| Backward Integration into Resins | Captive bisphenol-A supply hedges COMPERJ complex delay volatility. |
| Andean Market Entry Partnerships | Barranquilla and Cartagena zones offer Colombian infrastructure gap access. |
Research Methodology
Desk research of Brazilian CONAMA regulatory filings, ANVISA chemical substance registries, and Petrobras procurement databases preceded structured interviews with plant managers at formulation facilities, procurement leads at downstream industrial OEMs, technical R&D directors, and NACE-certified inspection contractors. Secondary validation drew from customs trade data, SEC 10-K disclosures of multinational coating suppliers, and ACC regional chemical production reports. Bottom-up volume estimates triangulated against top-down market sizing across resin chemistry segments.
Forecast assumptions held Brazilian CONAMA enforcement timelines and Argentine regulatory harmonization fixed while varying petrochemical feedstock cost trajectories and infrastructure spending acceleration across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, end-use vertical, technology platform compliance status, and regional production hub cluster. CAGRs derived from installed base replacement cycles and new specification adoption curves, with inputs from naphtha derivative pricing and offshore platform maintenance scheduling.
Practitioners should monitor CONAMA provincial enforcement acceleration and COMPERJ complex operational milestones for early signals of reformulation cost spikes or resin supply disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market