
 Chemical Protective Gloves Market | 2026-2036
Chemical Protective Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Protective Gloves Market Analysis
EN 374-5 virus protection certification is unwinding commoditized supply chains as buyers demand verified breakthrough times against aggressive solvents. Ansell Ltd. leverages integrated nitrile polymer sourcing across Southeast Asian manufacturing hubs to sustain margin control. Honeywell International Inc. anchors North American distribution through captive industrial safety channels, while 3M differentiates via proprietary three-layer laminate constructions for extreme chemical environments.
Chemical protective gloves are engineered barrier garments constructed from nitrile, neoprene, or multilayer polymer films, designed to resist permeation by corrosive, toxic, or reactive substances during industrial handling operations. Manufacturing involves controlled dipping processes with specified thickness tolerances, followed by leaching and chlorination to achieve surface integrity and donning performance. Nitrile formulations dominate volume production due to latex allergy mitigation and superior puncture resistance, though neoprene retains premium positioning in petrochemical applications where aromatic solvent exposure is routine. Medical grade specifications command higher unit economics driven by pharmaceutical cleanroom validation requirements, while industrial grade volumes scale through construction and wastewater treatment procurement.
OSHA 29 CFR 1910.138 hand protection standards mandate employer hazard assessment and appropriate glove selection documentation across United States workplaces. ECHA REACH Annex XVII restrictions on carcinogenic substances in glove manufacturing are redirecting formulation chemistry toward accelerator-free nitrile curatives. FDA 21 CFR 880.6250 patient examination glove regulations govern medical grade quality systems for pharmaceutical and laboratory end users. Stakeholders must monitor evolving dual-carbon regulatory frameworks in China and polymer feedstock price volatility as determinants of sourcing strategy and product mix allocation.
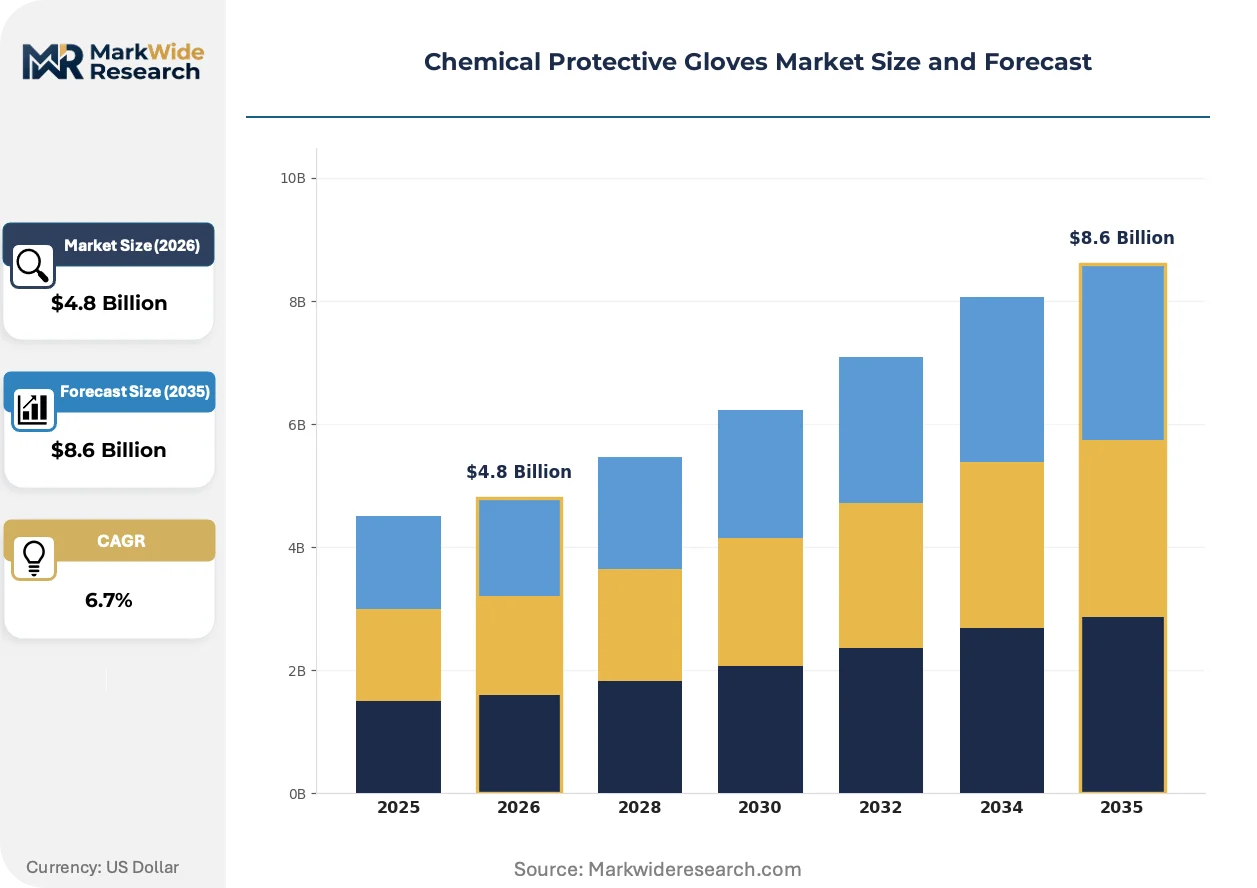
Market Dynamics
Accelerator-free nitrile formulations are forcing reformulation across Southeast Asian manufacturing bases as ECHA REACH Annex XVII restrictions on carcinogenic curatives tighten permeation certification requirements. Buyers now demand verified EN 374-5 virus protection documentation, compressing supplier qualification timelines and elevating testing infrastructure as a competitive gate.
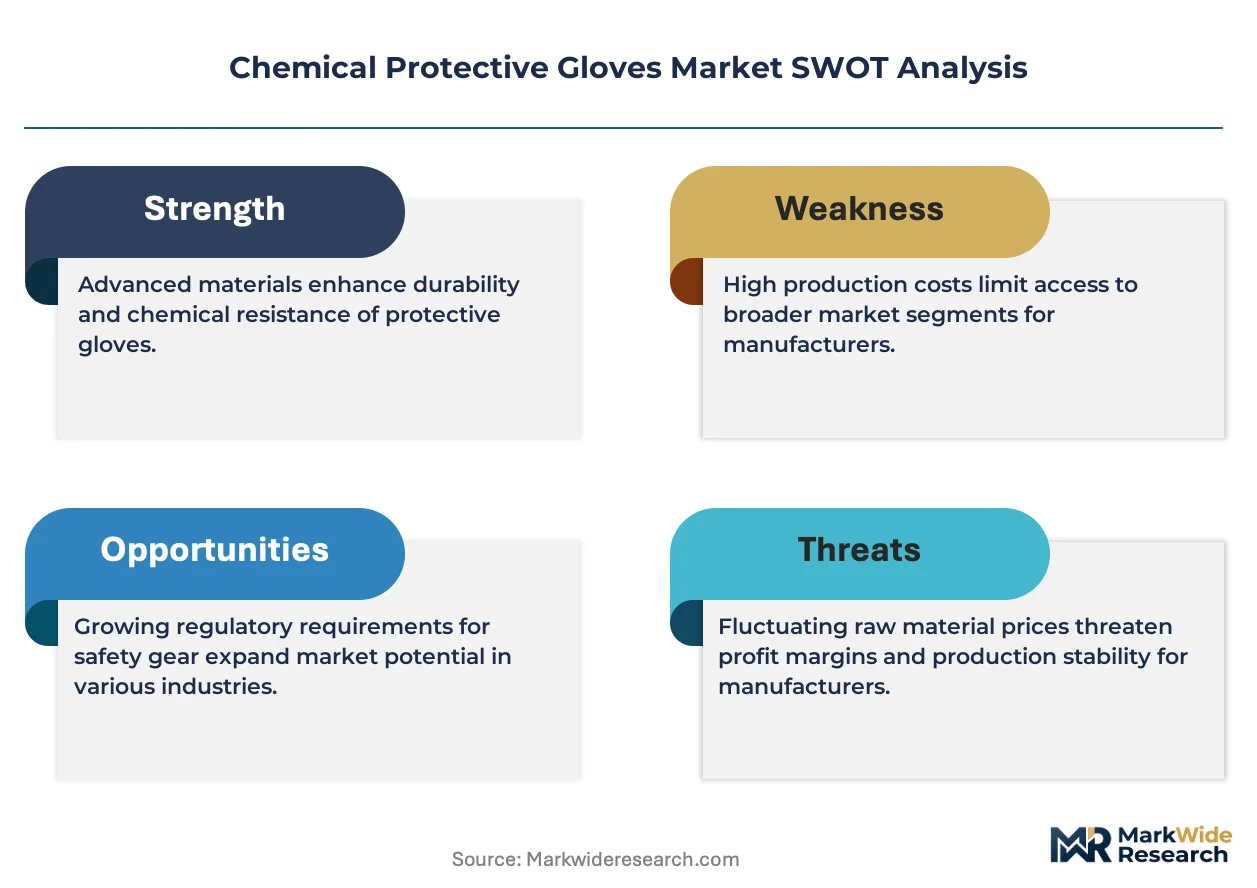
Growth Catalysts
- Pharmaceutical cleanroom validation mandates:Sterility protocols in active pharmaceutical ingredient facilities are expanding medical-grade glove procurement volumes. FDA 21 CFR 880.6250 quality system requirements govern this specification tier.
- OSHA 29 CFR 1910.138 enforcement:Employer hazard assessment documentation requirements are institutionalizing glove selection protocols across United States industrial workplaces. Construction and wastewater treatment sectors show particular compliance acceleration.
- Nitrile polymer feedstock security:Integrated butadiene-acrylonitrile supply chains in Malaysia and Thailand are stabilizing raw material access for volume manufacturers. This geographic concentration supports margin control against petrochemical volatility.
Market Restraints
- Butadiene price volatility:Crude oil-linked feedstock costs swing nitrile glove manufacturing economics unpredictably. Producers lack pricing power to pass through input spikes in commoditized industrial grades.
- Single-source testing infrastructure:EN 374 permeation certification capacity concentrates in German and British laboratories. Bottlenecks extend supplier qualification timelines by 8-14 weeks during demand surges.
- Latex allergy litigation exposure:Natural rubber alternatives retain residual liability risk in United States healthcare procurement. This constrains re-entry of Hevea-based products even where cost advantages exist.
Strategic Opportunities
- India chemical manufacturing cluster expansion:Gujarat and Maharashtra petrochemical corridors are localizing glove demand. BIS certification requirements create first-mover advantages for domestic production investments.
- Three-layer laminate extreme environments:Proprietary polymer film constructions address aromatic solvent exposure in refinery maintenance. Petrochemical applications command 40-60% unit price premiums over standard nitrile.
- E-commerce industrial safety distribution:Direct procurement platforms are compressing distributor markups for mid-size manufacturing accounts. China and Germany show fastest channel migration velocity.
Industry Challenges
- Polymer formulation chemistry expertise:Accelerator-free nitrile curing requires specialized compounding knowledge scarce in traditional latex glove manufacturing regions. Retraining timelines extend 18-24 months.
- Dual-carbon regulatory alignment:China's MEE emission standards and EU CSRD disclosure requirements impose overlapping compliance burdens. Manufacturers serving both markets face divergent carbon accounting methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Protective Gloves Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Latex, Vinyl, Neoprene End User: Healthcare, Construction, Manufacturing, Food Processing Grade: Industrial Grade, Medical Grade, Food Grade, Waterproof Application: Laboratory, Pharmaceutical, Oil & Gas, Waste Management |
| Companies Covered | Ansell Ltd., Honeywell International Inc., 3M, Showa Group, DuPont, MAPA Professional, Kossan, MCR Safety, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Protective Gloves Market Emerging Trajectories
Materials science convergence with digital traceability systems is redefining competitive differentiation beyond barrier performance alone. Certification documentation now travels as data assets alongside physical products.
Chlorination-free surface modification technologies are supplanting traditional halogen-based donning treatments in medical-grade production. European pharmaceutical manufacturers are adopting these processes ahead of ECHA substance restriction timelines. This transition is compressing differentiation windows for suppliers lacking proprietary surface chemistry IP.
ECHA REACH Annex XVII restrictions on N-nitrosamines in rubber articles are redirecting formulation chemistry toward novel curative systems. German chemical manufacturers are accelerating accelerator-free nitrile patent filings. Medical-grade specifications in European pharmaceutical applications face the steepest compliance timeline compression.
Consolidated procurement platforms are aggregating demand from mid-size chemical processors previously served by fragmented distributor networks. German industrial safety cooperatives and Chinese state-owned chemical conglomerates are pioneering volume-direct contracting models. This disintermediation is most advanced in automotive coatings and electronics chemicals verticals.
Chemical Protective Gloves Market Segmentation
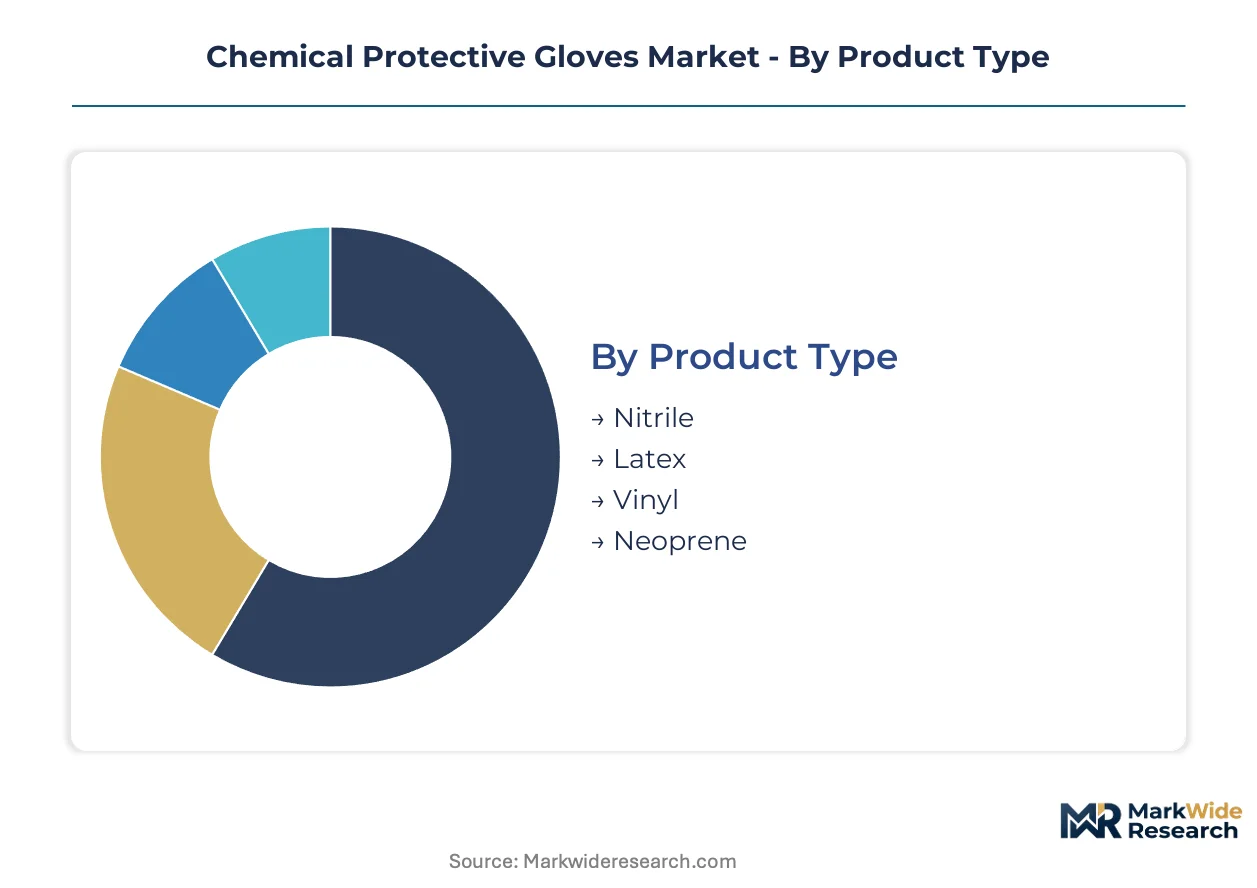
Chemical protective glove procurement patterns diverge sharply across end-use environments, with pharmaceutical cleanrooms demanding validated medical-grade specifications while construction sites prioritize cost-efficient industrial grades. Segmentation discipline separates premium barrier performance from commodity volume plays.
Product Type:
Nitrile formulations dominate export-led manufacturing from Malaysia and Thailand, while neoprene production concentrates in domestic European and North American specialty chemical corridors.
- Nitrile:Synthetic rubber copolymers of butadiene and acrylonitrile deliver superior puncture resistance and eliminate latex protein allergen risks. Active pharmaceutical ingredient facilities in Germany and India are expanding procurement of accelerator-free nitrile variants to meet ECHA REACH Annex XVII compliance timelines. The steepest volume expansion runs through Southeast Asian integrated manufacturing hubs.
- Neoprene:Chloroprene polymer constructions maintain chemical stability against aromatic solvents and petroleum distillates. Refinery maintenance operations in the US Gulf Coast and Rotterdam-Antwerp petrochemical clusters specify neoprene for routine aromatic exposure protocols. Premium unit economics reflect specialized compounding requirements and lower production volumes.
- Latex:Natural rubber formulations from Hevea brasiliensis retain cost advantages in food processing and light industrial applications. Residual litigation exposure in United States healthcare procurement constrains re-entry despite manufacturing efficiency.
- Vinyl:Polyvinyl chloride plastisol constructions serve budget-sensitive janitorial and food service applications. Limited chemical resistance restricts penetration beyond basic splash protection scenarios.
Nitrile commands the established base. The steepest expansion runs through accelerator-free specialty grades.
End User:
Cost tier stratification separates pharmaceutical cleanroom validation requirements from construction site commodity procurement, with manufacturing and food processing occupying intermediate specification bands.
- Healthcare:Hospitals, clinics, and diagnostic laboratories require FDA 21 CFR 880.6250 quality system compliance for patient examination and sterile procedure applications. United States procurement is consolidating through group purchasing organizations demanding lot-level traceability documentation.
- Construction:Masonry, concrete handling, and general contracting operations prioritize abrasion resistance and cost efficiency over chemical permeation certification. OSHA 29 CFR 1910.138 enforcement is institutionalizing minimum specification standards across United States job sites.
- Manufacturing:Automotive coatings, electronics assembly, and metal finishing operations specify task-appropriate barrier protection against solvents, acids, and caustic solutions. German automotive OEMs are driving EN 374-5 virus protection documentation requirements through supplier quality agreements.
- Food Processing:Poultry, meatpacking, and dairy operations require FDA food contact compliance alongside cut and puncture resistance. Accelerator-free formulations are displacing traditional nitrile in European Union facilities ahead of N-nitrosamine restriction implementation.
Healthcare maintains premium pricing power. Manufacturing volume is climbing the fastest.
Grade:
Application maturity separates validated medical-grade quality systems from industrial-grade commodity production, with food grade and waterproof categories occupying emerging specification niches.
- Industrial Grade:General-purpose nitrile and neoprene constructions serve construction, wastewater treatment, and basic manufacturing without cleanroom validation overhead. Volume procurement concentrates through industrial safety distributors and direct e-commerce platforms.
- Medical Grade:Controlled-environment manufacturing with ISO 14644 cleanroom protocols supports pharmaceutical laboratory and sterile procedure applications. FDA 21 CFR 880.6250 quality system requirements govern this specification tier with lot-level sterility assurance testing.
- Food Grade:FDA Title 21 compliance for food contact surfaces combines with HACCP protocol alignment in processing facilities. Migration testing for extractable substances is tightening qualification requirements for imported gloves.
- Waterproof:Extended cuff designs and liquid-tight seam constructions address submerged or high-splash environments in chemical tank cleaning and emergency response. Niche positioning limits volume relative to standard cuff configurations.
Industrial grade captures volume scale. Medical grade is gaining share fastest through pharmaceutical facility expansion.
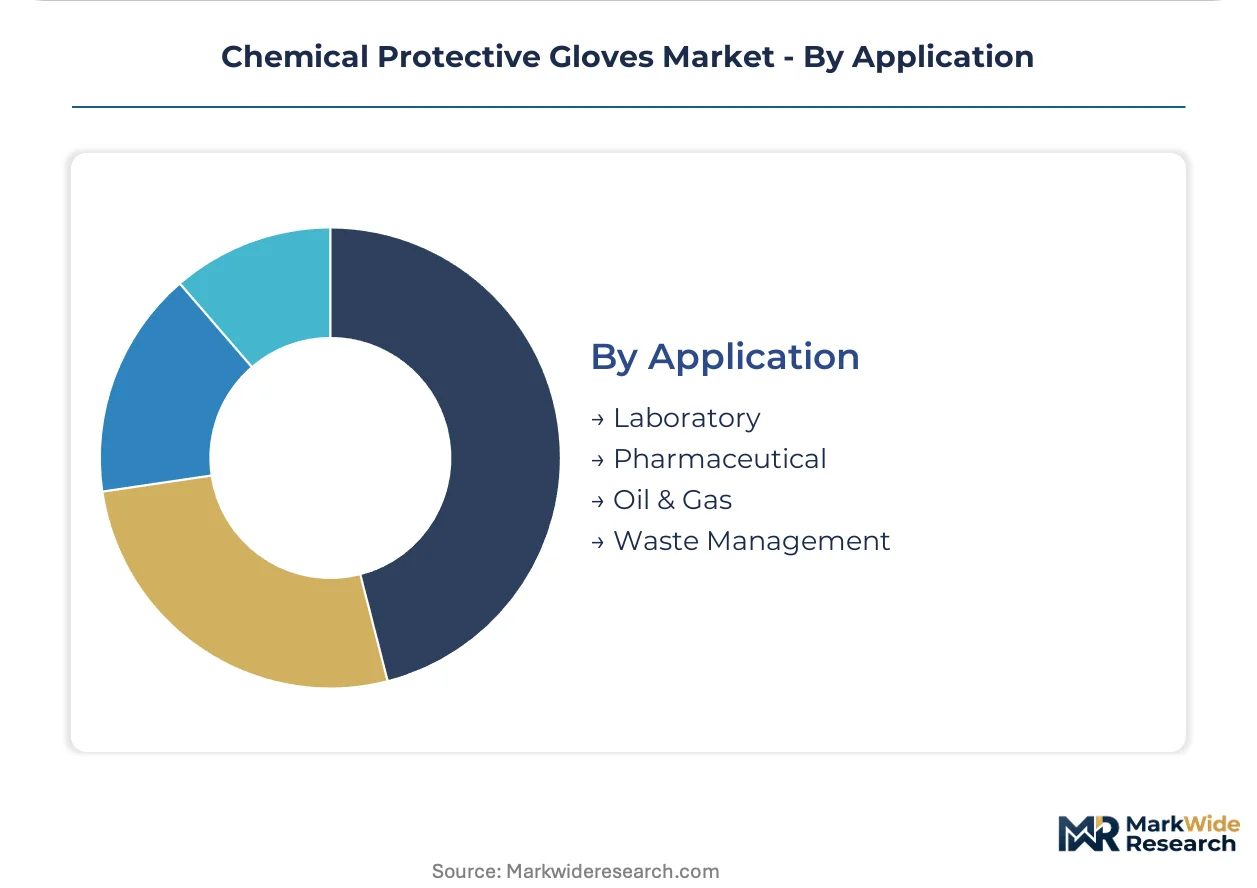
Application:
Customer type differentiation separates laboratory research procurement from heavy industrial maintenance, with pharmaceutical manufacturing and waste management occupying distinct compliance intensity tiers.
- Laboratory:Research and quality control operations require dexterity-optimized thin-wall constructions with verified permeation data against specific reagent libraries. Academic and contract research organizations in Germany and the United States are consolidating procurement through cooperative purchasing agreements.
- Pharmaceutical:Active pharmaceutical ingredient synthesis and sterile formulation operations demand medical-grade specifications with EN 374-5 virus protection certification. Cleanroom validation protocols in India and China are accelerating specification convergence with Western regulatory standards.
- Oil & Gas:Upstream drilling, midstream pipeline maintenance, and downstream refining operations specify multilayer laminates or heavy-duty neoprene for aromatic solvent and petroleum product exposure. Three-layer proprietary constructions command substantial unit price premiums in refinery turnaround contracts.
- Waste Management:Hazardous material handling, landfill leachate management, and infectious waste treatment require chemical and biological barrier protection. United States EPA RCRA training mandates are driving specification standardization across municipal and private sector operators.
Pharmaceutical applications anchor premium tier positioning. Waste management procurement is expanding most quickly through regulatory enforcement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated nitrile manufacturing clusters in Malaysia and Thailand anchor supply-side capacity, while demand concentrates in German pharmaceutical corridors, US Gulf Coast petrochemical complexes, and expanding Indian chemical processing zones. Regulatory divergence between ECHA REACH frameworks and OSHA enforcement patterns is fragmenting procurement qualification protocols across major consuming markets.
United States
Gulf Coast refinery maintenance operations and pharmaceutical manufacturing in New Jersey and North Carolina drive neoprene and medical-grade nitrile procurement. OSHA 29 CFR 1910.138 enforcement acceleration through 2024-2025 is institutionalizing employer hazard assessment documentation across construction and wastewater treatment sectors. Houston and Baton Rouge petrochemical clusters specify multilayer laminates for aromatic solvent exposure protocols.
Germany
Leverkusen and Ludwigshafen chemical manufacturing corridors demand EN 374-5 virus protection certification for pharmaceutical cleanroom applications. ECHA REACH Annex XVII restrictions on N-nitrosamines and carcinogenic curatives are compressing supplier qualification timelines for accelerator-free nitrile formulations. German automotive OEMs in Stuttgart and Munich are driving permeation documentation requirements through tier-one supplier quality agreements.
China
Yangtze River Delta pharmaceutical API synthesis facilities and Shandong petrochemical processing zones are expanding medical-grade glove procurement volumes. MEE dual-carbon emission standards and evolving GB standards for chemical protective equipment are imposing overlapping compliance burdens on manufacturers serving domestic and export markets. Shanghai and Ningbo chemical industrial parks are localizing specification convergence with Western regulatory standards.
India
Gujarat and Maharashtra petrochemical corridors are generating concentrated demand for industrial-grade chemical protective gloves in refinery maintenance and specialty chemical processing. BIS certification requirements for personal protective equipment create structural advantages for domestic production investments over import-dependent supply chains. Mumbai and Vadodara manufacturing clusters are accelerating cleanroom validation protocol adoption for pharmaceutical export compliance.
Malaysia
Integrated butadiene-acrylonitrile supply chains in Penang and Selangor sustain Southeast Asian nitrile glove manufacturing dominance for global export markets. Accelerator-free formulation transitions are forcing specialized compounding investments ahead of ECHA substance restriction timelines. Port Klang logistics infrastructure supports margin control against petrochemical feedstock volatility through captive polymer sourcing.
Chemical Protective Gloves Market Vendor Landscape
Concentration sits with diversified industrial safety conglomerates and integrated polymer manufacturers, creating a tiered structure where scale-driven nitrile producers compete against specialized laminate technology developers. Strategic archetypes include Southeast Asian integrated polymer-to-glove manufacturers, North American captive distribution networks, and European specialty chemical compounders. Competitive dynamics revolve around M&A consolidation of testing infrastructure and backward integration into butadiene feedstock security.
Within the diversified industrial safety tier, Ansell Ltd. and Honeywell International Inc. exemplify contrasting geographic anchoring strategies, with the former representing Southeast Asian manufacturing integration and the latter North American distribution channel control. 3M occupies a position in proprietary materials science, reflecting premium-tier positioning through multilayer polymer film constructions. These three entities collectively illustrate the market's structural divergence between scale-driven commodity supply and technology-differentiated specialty applications.
| Leading Market Players |
|---|
| Ansell Ltd. |
| Honeywell International Inc. |
| 3M |
| Showa Group |
| DuPont |
| MAPA Professional |
| Kossan |
| MCR Safety |
| Kimberly-Clark Corporation |
| Others |
Supply Flow & Price Mechanics
EN 374-5 virus protection certification gates both supplier qualification timelines and price tier separation, compressing margins for manufacturers lacking verified testing infrastructure while rewarding compounders with accelerator-free formulation patents. Buyers in pharmaceutical cleanrooms now treat permeation documentation as a non-negotiable cost of entry, forcing price stratification around certification completeness rather than raw material efficiency alone.
Pricing Analysis
OSHA 29 CFR 1910.138 dictates the pricing tier structure across United States industrial procurement, with construction and wastewater treatment buyers facing compliance-driven specification upgrades. Three-tier pricing structure across medical-grade, industrial-grade, and economy vinyl levels separates pharmaceutical cleanroom validation from basic splash protection. Cost compression in industrial-grade nitrile is intensifying because Malaysian integrated producers pass through butadiene volatility without pricing power. Food processing procurement shows highest price sensitivity due to thin operating margins, while oil and gas maintenance contracts prove least sensitive given aromatic solvent exposure liabilities.
Supply Chain Analysis
Just-in-time inventory preferences dominate pharmaceutical cleanroom procurement, while strategic stockpiling characterizes petrochemical maintenance operations facing turnaround scheduling uncertainty. Manufacturing concentrates in Malaysia, Thailand, and Germany, with nitrile polymerization feeding glove dipping lines through captive butadiene-acrylonitrile supply chains. Raw material sourcing draws from crude oil derivatives, chloroprene monomer, and natural rubber latex estates. Single-source vulnerability concentrates in EN 374 permeation testing capacity locked in German and British laboratories. Distribution runs through industrial safety distributors, direct e-commerce platforms, and group purchasing organizations consolidating hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical protective gloves constitute a regulatory entrenchment moat where EN 374-5 certification infrastructure and REACH-compliant formulation chemistry create switching costs that lock in qualified suppliers. Network effects concentrate in testing laboratory relationships and pharmaceutical buyer consortiums that standardize procurement specifications.
For Market Incumbents: Secure accelerator-free nitrile patent positions ahead of ECHA Annex XVII N-nitrosamine restriction deadlines, while acquiring captive permeation testing capacity to compress supplier qualification timelines. Threats from emerging Indian domestic producers with BIS certification advantages require backward integration into butadiene feedstock security in Malaysian manufacturing corridors. Certification investment represents the priority defensive lever. For New Entrants and Emerging Players: Anchor in Gujarat and Maharashtra petrochemical corridors where BIS requirements disadvantage import-dependent supply chains, targeting refinery maintenance procurement with industrial-grade specifications. Waste management verticals show fastest regulatory enforcement acceleration through EPA RCRA training mandates. Direct e-commerce distribution to mid-size chemical processors bypasses entrenched distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across accelerator-free formulation R&D and chlorination-free surface modification technology. Long-term viability centers on compounders with integrated polymer sourcing and proprietary laminate constructions. Acquisition targets include Southeast Asian manufacturers with captive butadiene supply and European specialty chemical firms with EN 374-5 testing infrastructure. Watch for inflection when ECHA substance restriction timelines accelerate compliance-driven specification turnover.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive acrylonitrile supply in Malaysia stabilizes margin control against crude oil volatility. |
| Accelerator-Free Formulation Patent Filing | German chemical manufacturers are accelerating novel curative system development ahead of REACH deadlines. |
| EN 374-5 Testing Infrastructure Acquisition | Bottlenecks in British and German laboratories extend supplier qualification timelines by 8-14 weeks. |
| Direct E-Commerce Platform Launch | China and Germany show fastest channel migration velocity for mid-size manufacturing accounts. |
| Three-Layer Laminate Construction Scale-Up | Proprietary polymer films command 40-60% unit price premiums in refinery turnaround contracts. |
Methodological Framework
Desk research of customs trade databases, ECHA regulatory filings, and SEC 10-K disclosures preceded structured interviews with plant managers at pharmaceutical API facilities, procurement leads at petrochemical operators, distribution channel partners in industrial safety, and technical R&D directors at polymer compounders. Primary fieldwork combined with secondary validation through FDA 21 CFR quality system documentation and OSHA enforcement pattern analysis. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Variance decomposition separates polymer feedstock price effects, regulatory compliance cost impacts, and end-use demand shifts throughout the forecast period. Segmentation dimensions modeled include material type, grade tier, end-use industry, and regional production hub. CAGRs derived from historical trajectory analysis and scenario-weighted projection. Industry-specific inputs incorporated REACH Annex XVII substance restriction timelines and MEE dual-carbon emission standard implementation patterns.
Material uncertainties — butadiene price volatility, EN 374 testing capacity bottlenecks, and ECHA substance restriction acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement continuity and polymer feedstock supply stability. Revision becomes warranted when dual-carbon regulatory divergence between China and Europe crosses thresholds that fragment qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market