
 Professional Spa Services Market | 2026-2036
Professional Spa Services Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Spa Services Market Analytics
Corporate wellness spending is rotating toward preventive health programs, pulling professional spa services into employer benefit ecosystems. Marriott International leverages its Bonvoy loyalty infrastructure to sustain recurring spa bookings across 500-plus properties. Mandarin Oriental Hotel Group differentiates through physician-supervised wellness programs in Bangkok and Shanghai. Four Seasons Hotels Limited anchors premium pricing through destination spa exclusivity in Maldives and Bora Bora.
Professional spa services encompass therapeutic and aesthetic treatments delivered in licensed facilities by certified practitioners using regulated products and equipment, typically involving hydrotherapy systems operating at 38-40°C, botanical extracts with documented dermatological profiles, and manual or device-assisted tissue manipulation. The primary commercial purpose centers on stress reduction, musculoskeletal recovery, and skin health maintenance for fee-paying clients. Facial Treatments and Massage Therapy command the largest revenue pools due to repeat visit frequency and upselling potential, while Digital Platforms represent the fastest-expanding technology segment as booking engines and personalized wellness apps reduce client acquisition costs. Natural Products are gaining structural share as ingredient transparency becomes a decisive selection criterion for high-spending consumers.
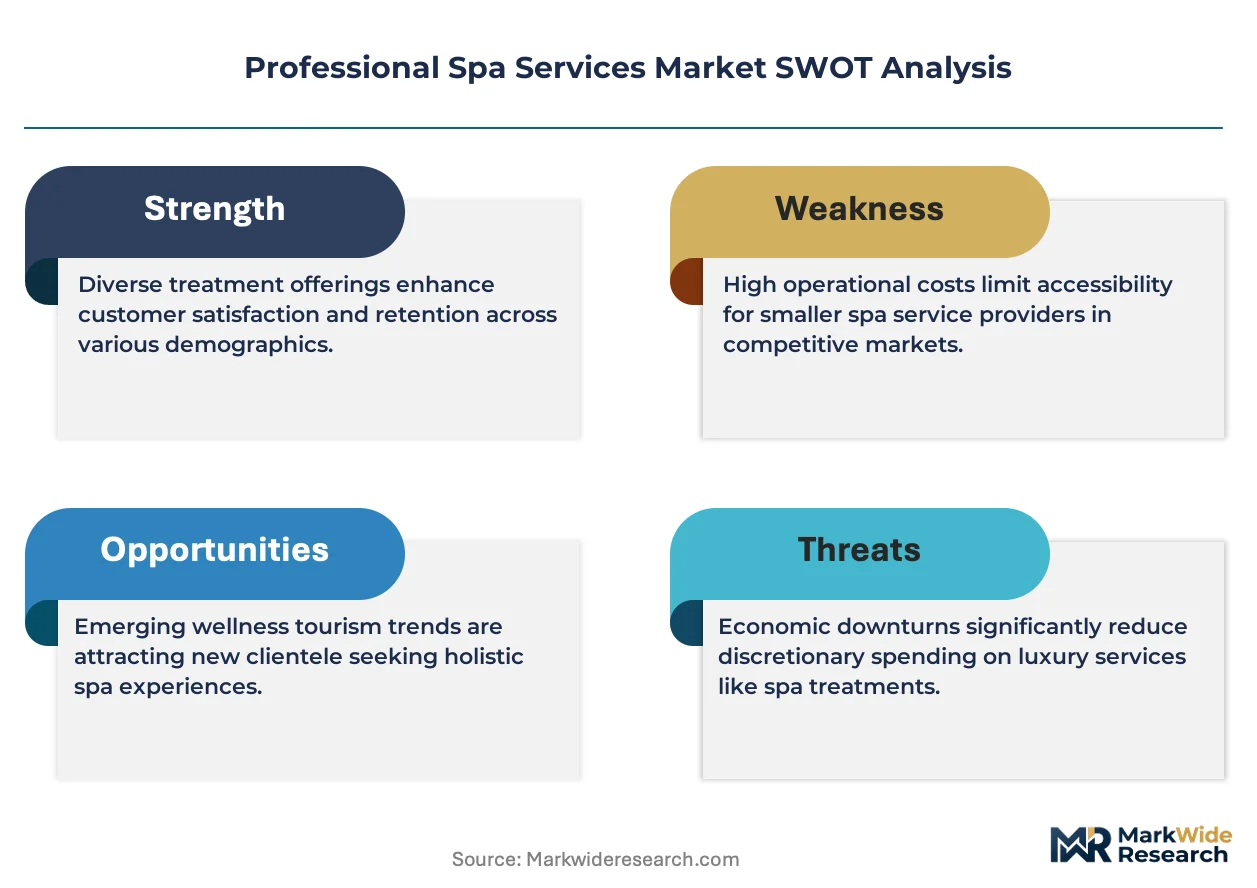
The US FDA regulates topical spa products as cosmetics or drugs depending on therapeutic claims, while the EU REACH framework restricts paraben and formaldehyde-releasing preservatives in treatment formulations. These standards elevate compliance costs for multi-territory operators but also create market access barriers that favor established chains with dedicated regulatory affairs capacity. Stakeholders must monitor evolving state-level licensing requirements for advanced modalities such as laser skin treatments and intravenous nutrient therapy.
Market Dynamics
The EU Green Deal's chemical restrictions on cosmetic ingredients are forcing immediate reformulation across treatment protocols, compressing supplier margins while accelerating plant-based certification programs.
Growth Catalysts
- Corporate Wellness Integration:Employer-sponsored preventive health programs are pulling spa services into benefits ecosystems. Four Seasons and Mandarin Oriental now structure annual contracts with Fortune 500 procurement departments.
- REACH Chemical Restrictions:The EU framework banning paraben and formaldehyde-releasing preservatives is creating first-mover advantage for botanical-formulation specialists. Reformulation compliance costs favor established chains with dedicated regulatory capacity.
- Thailand Destination Clustering:Bangkok, Phuket, and Chiang Mai have concentrated medical-tourism infrastructure. Physician-supervised wellness programs in this corridor attract high-spending international clientele.
Market Restraints
- Licensed Practitioner Scarcity:Advanced modalities including laser skin treatments and intravenous nutrient therapy require state-level certification. Training pipelines lag demand expansion in key markets.
- Hydrotherapy Equipment Concentration:German and Italian manufacturers dominate 38-40°C thermal system supply. Spa operators face extended lead times and currency exposure on euro-denominated contracts.
- DIY Device Substitution:At-home LED masks and percussion massagers are capturing routine maintenance occasions. Professional facilities must differentiate through diagnostic capability and supervised protocols.
Strategic Opportunities
- Digital Platform Convergence:Booking engines integrated with personalized wellness apps are reducing client acquisition costs. Marriott's Bonvoy infrastructure demonstrates recurring revenue potential across property networks.
- Maldives-Bora Bora Exclusivity Positioning:Ultra-premium island destinations command pricing power through scarcity and destination cachet. Limited room inventory supports advance-commitment models.
- FDA Cosmetic-Drug Classification Clarity:US regulatory guidance on therapeutic claims creates compliance roadmap for operators. Clear boundaries between cosmetic and drug categories enable product development confidence.
Industry Challenges
- Multi-Territory Licensing Complexity:Operators spanning US state jurisdictions and EU member states must maintain parallel compliance systems. Laser treatment and IV therapy regulations diverge significantly across markets.
- Botanical Supply Chain Verification:Ingredient transparency demands require documentation of dermatological profiles for plant extracts. Sourcing teams must audit extraction methods and sustainable harvesting credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Spa Services Market |
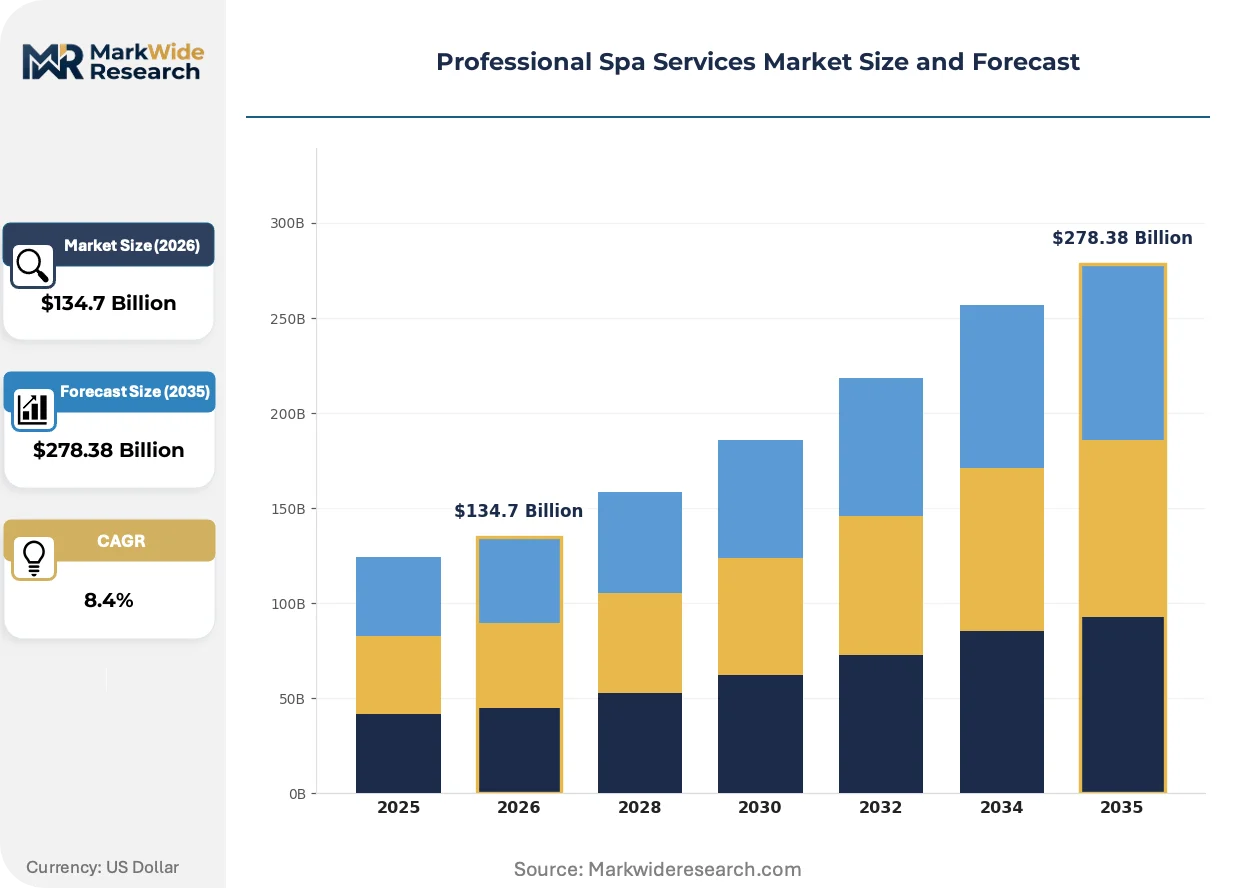
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $278.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Facial Treatments, Massage Therapy, Body Treatments, Nail Services End User: Individuals, Corporate Clients, Wellness Retreats, Hotels Technology: Traditional Techniques, Advanced Equipment, Natural Products, Digital Platforms Pricing Model: Hourly Rates, Package Deals, Membership Plans, Seasonal Promotions |
| Companies Covered | Marriott International, Inc., Four Seasons Hotels Limited, Mandarin Oriental Hotel Group Limited, The Ritz-Carlton Hotel Company, L.L.C., Hyatt Hotels Corporation, Aman Group S.a.r.l., Kempinski Hotels, Banyan Tree Hotels & Resorts, Woodhouse Spas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Spa Services Market Evolving Landscape
Technology-enabled personalization and regulatory chemistry shifts are restructuring how spa services are delivered, priced, and consumed across premium and mass-market tiers.
Artificial intelligence-driven skin analysis systems are supplanting visual consultation methods in facial treatment protocols. High-spending clientele at luxury hotel chains now expect algorithmic product matching based on hydration, pigmentation, and elasticity metrics. This compression of diagnostic time is enabling higher throughput without perceived quality degradation.
The EU Green Deal's chemical restrictions are accelerating reformulation timelines for treatment formulations. Manufacturers must substitute paraben and formaldehyde-releasing preservatives with plant-based alternatives that meet REACH safety thresholds. Natural Products segments are capturing structural share as ingredient transparency becomes decisive for consumer selection.
Corporate procurement departments are consolidating wellness spending under preventive health program budgets. Traditional individual booking models are yielding to annual service contracts with negotiated rate structures and utilization guarantees. This pattern concentrates most visibly in US and European markets where employer-sponsored benefits cover stress reduction and musculoskeletal recovery modalities.
Professional Spa Services Market Segmentation
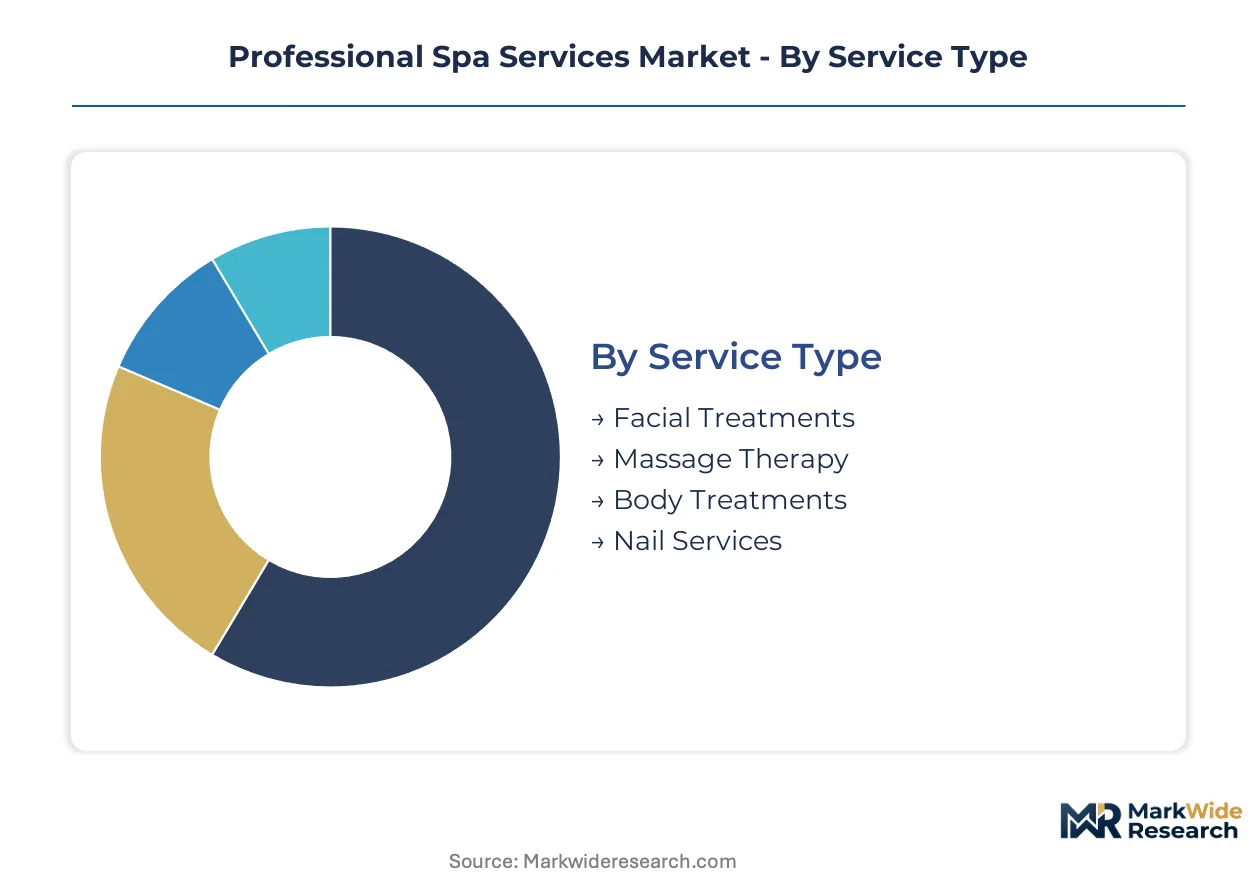
Segmentation in professional spa services determines regulatory exposure, capital intensity, and client acquisition economics. Service type dictates practitioner licensing requirements. Technology selection shapes compliance costs under REACH and FDA frameworks.
Service Type:
Regulatory differentiation separates cosmetic claims from therapeutic claims, with FDA and EU REACH applying distinct safety thresholds to facial protocols versus massage modalities.
- Facial Treatments:Protocols deploy hydrotherapy systems at 38-40°C combined with botanical extracts requiring documented dermatological profiles. Demand concentrates in luxury hotel chains across Thailand's destination wellness corridor, where physician-supervised programs command premium positioning.
- Massage Therapy:Manual and device-assisted tissue manipulation targets stress reduction and musculoskeletal recovery. Corporate wellness spending in the US and Europe is pulling repeat-visit bookings into employer benefit ecosystems with annual contract structures.
- Body Treatments:Wrap and exfoliation protocols using regulated topical formulations.
- Nail Services:Manicure and pedicure offerings with lower regulatory burden than skin-penetrating modalities.
Facial Treatments handles the majority of throughput; Massage Therapy is the fastest mover on share.
End User:
Cost tier separation distinguishes individual discretionary spending from corporate procurement budgets with negotiated rate structures.
- Individuals:Fee-paying clients booking single sessions or small packages through digital platforms. Marriott's Bonvoy infrastructure demonstrates how loyalty systems sustain recurring bookings across property networks.
- Corporate Clients:Fortune 500 procurement departments consolidating preventive health spending under wellness program budgets. Four Seasons and Mandarin Oriental now structure annual contracts with utilization guarantees.
- Wellness Retreats:Multi-day immersive programs at destination facilities.
- Hotels:On-property spa operations integrated with accommodation revenue streams.
Individuals generate the highest visit frequency; Corporate Clients are expanding most quickly as benefits ecosystems absorb spa services.
Technology:
Application focus separates diagnostic-enabled personalization from commodity delivery methods.
- Traditional Techniques:Manual therapy protocols passed through certification pipelines. Licensed practitioner scarcity in laser and IV modalities creates capacity constraints that training programs have not resolved.
- Advanced Equipment:AI-driven skin analysis systems and hydrothermal installations. German and Italian manufacturers dominate 38-40°C thermal system supply, exposing spa operators to euro-denominated currency risk.
- Natural Products:Plant-based formulations substituting paraben and formaldehyde-releasing preservatives under EU Green Deal compliance timelines.
- Digital Platforms:Booking engines and personalized wellness apps reducing client acquisition costs.
Traditional Techniques retains the largest installed base; Digital Platforms shows the steepest expansion trajectory.
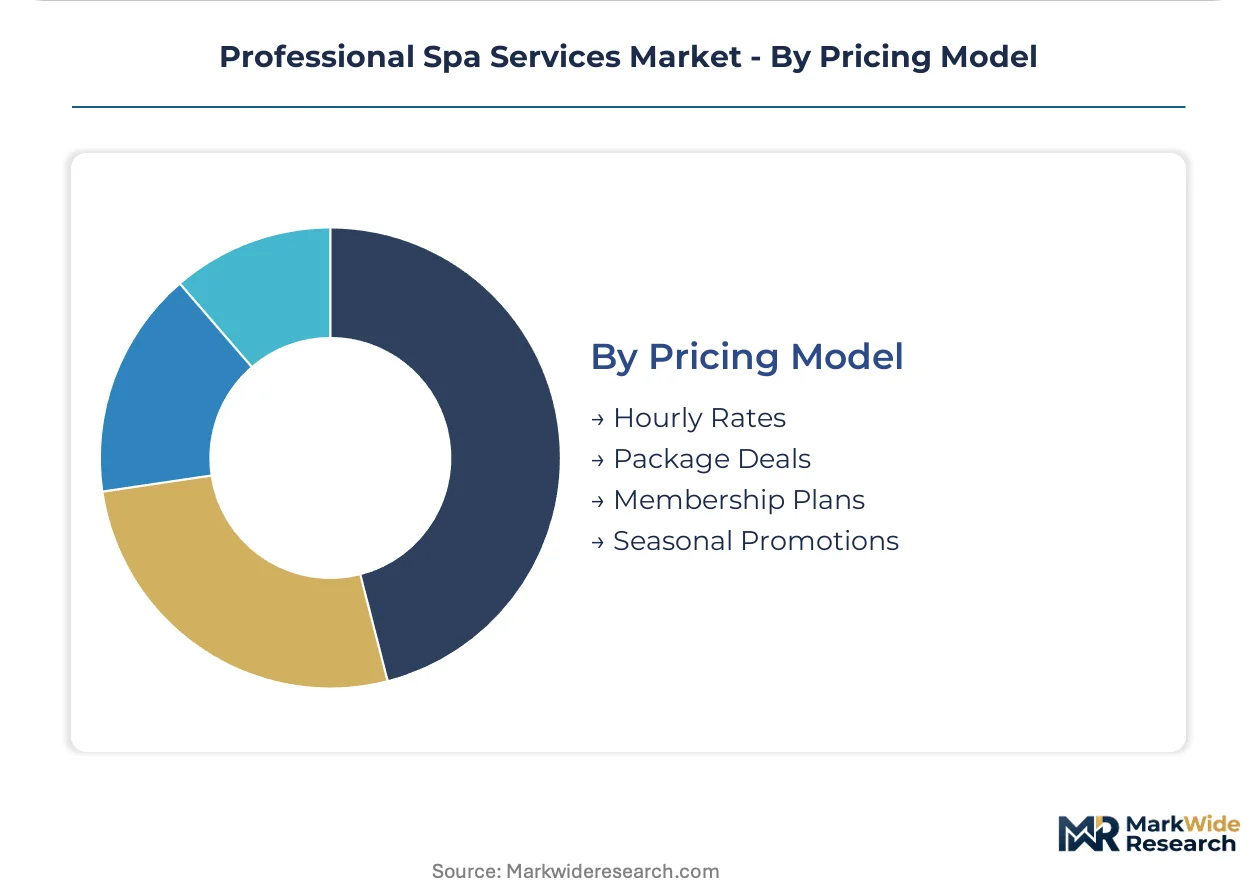
Pricing Model:
Customer type alignment matches transaction structures to visit frequency and commitment depth.
- Hourly Rates:Per-session pricing for walk-in and occasional clientele.
- Package Deals:Bundled session commitments with modest volume discounts.
- Membership Plans:Recurring revenue models with monthly fees and preferred booking access. Maldives and Bora Bora exclusivity positioning supports advance-commitment models through scarcity pricing.
- Seasonal Promotions:Demand-smoothing discounts during low-occupancy periods.
Hourly Rates still dominates transaction volume; Membership Plans is gaining share fastest through loyalty infrastructure integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports destination wellness services to high-spending clientele from China, the United States, and Europe. The country's medical-tourism corridor funnels international visitors into physician-supervised programs. Regulatory alignment with ASEAN harmonization standards eases cross-border practitioner mobility.
United States
Employer-sponsored preventive health budgets absorb massage therapy and stress reduction modalities into corporate benefits ecosystems. FDA cosmetic-drug classification guidance creates compliance roadmaps for topical treatment formulations. Miami and Scottsdale concentrate luxury hotel spa operations targeting domestic wellness tourism.
Germany
EU REACH chemical restrictions on paraben preservatives force immediate reformulation of treatment protocols across licensed facilities. The country's national pharmaceutical regulator enforces strict dermatological safety thresholds for botanical extracts. Baden-Baden and Bavarian spa towns anchor traditional hydrotherapy infrastructure now integrating digital booking platforms.
Thailand
Bangkok, Phuket, and Chiang Mai cluster medical-tourism infrastructure attracting international clientele to physician-supervised wellness programs. ASEAN cosmetic directive harmonization reduces regulatory friction for cross-border service delivery. The destination wellness corridor commands premium positioning through scarcity and clinical credibility.
United Arab Emirates
Dubai and Abu Dhabi hotel chains capture corporate wellness spending from Fortune 500 regional headquarters. MOHAP licensing requirements for advanced modalities including laser treatments create practitioner certification bottlenecks. The emirates position ultra-premium island developments as advance-commitment wellness destinations.
Japan
Metropolitan onsen and hotel spa operations integrate AI-driven skin analysis into facial treatment protocols. METI standards for cosmetic ingredient safety elevate compliance costs for imported botanical formulations. Tokyo and Osaka concentrate demand for technology-enabled personalization in premium service tiers.
Professional Spa Services Market Competitive Landscape
Listed leaders compete with private specialists across loyalty infrastructure and destination exclusivity. The market structures around hotel chain scale, boutique positioning, and digital platform integration. Three archetypes dominate: global hospitality conglomerates with spa networks, regional luxury specialists with physician-supervised programs, and technology-enabled booking platforms. Competitive moves concentrate on loyalty program integration and exclusive destination contracts.
Within the global hospitality tier, Marriott International, Inc. and Four Seasons Hotels Limited exemplify scale-driven positioning through property network breadth and destination cachet. Mandarin Oriental Hotel Group Limited occupies a specialist position emphasizing clinical credibility in Asian wellness corridors. These three anchors represent divergent strategic paths: loyalty infrastructure leverage, ultra-premium scarcity pricing, and medical-tourism integration.
| Leading Market Players |
|---|
| Marriott International, Inc. |
| Four Seasons Hotels Limited |
| Mandarin Oriental Hotel Group Limited |
| The Ritz-Carlton Hotel Company, L.L.C. |
| Hyatt Hotels Corporation |
| Aman Group S.a.r.l. |
| Kempinski Hotels |
| Banyan Tree Hotels & Resorts |
| Woodhouse Spas |
| Others |
Value Network & Pricing Analysis
EU REACH chemical restrictions on paraben and formaldehyde-releasing preservatives simultaneously gate supplier qualification and enable price differentiation through botanical certification tiers. Spa operators must absorb reformulation compliance costs while passing premium positioning to ingredient-transparent protocols.
Pricing Analysis
Current-generation AI-driven skin analysis systems command premium positioning against prior-generation visual consultation methods, while next-generation personalized wellness apps compress acquisition costs. Three-tier pricing structure across premium, standard, and economy levels separates Maldives-Bora Bora exclusivity from urban hotel spa networks and standalone day spa operations. Price differentiation stems from physician-supervised program certification and destination scarcity. Cost compression in mid-tier urban facilities is intensifying because DIY device substitution captures routine maintenance occasions. Individual discretionary buyers show highest price sensitivity; corporate procurement departments with annual contracts demonstrate lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for German and Italian hydrotherapy equipment manufacturers. Thermal system supply concentrates in Germany and Italy, while botanical extract sourcing draws from Thailand and ASEAN corridor harvesting operations. Spa operators face raw material dependencies on 38-40°C thermal installations, AI diagnostic hardware, and REACH-compliant plant formulations. Single-source vulnerability runs through euro-denominated equipment contracts with extended lead times. Distribution runs through hotel chain procurement departments and direct digital platform bookings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment. Multi-territory licensing requirements for laser and IV modalities create compliance barriers that favor established chains with dedicated regulatory affairs capacity.
For Market Incumbents: Fortify position through backward integration into botanical supply chains and captive certification pipelines for advanced modalities. Licensed practitioner scarcity threatens capacity expansion; invest in training infrastructure to secure talent pipelines. Deepen vertical control over plant-based formulation sourcing to secure EU Green Deal compliance margins. For New Entrants and Emerging Players: Differentiate on technology-enabled personalization in underserved metropolitan markets. Corporate wellness integration in US and European employer benefit ecosystems offers most penetrable white space. Pursue direct-to-corporate procurement channel development with annual contract structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across physician-supervised wellness program infrastructure. Long-term viability favors operators with regulatory affairs scale spanning US state jurisdictions and EU member states. Target acquisition archetype: regional luxury specialists with Bangkok-Shanghai corridor positioning. Watch for FDA cosmetic-drug classification guidance clarity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Supply Chain Integration | EU REACH compliance secures formulation access and premium pricing tier qualification. |
| Corporate Wellness Contract Structuring | Fortune 500 procurement integration locks recurring revenue with utilization guarantees. |
| AI Diagnostic Platform Deployment | Algorithmic skin analysis compresses consultation time while maintaining throughput quality. |
| Destination Exclusivity Positioning | Maldives-Bora Bora scarcity supports advance-commitment membership models. |
| Multi-Territory Licensing Investment | Parallel US-EU compliance systems create market access barriers favoring scaled operators. |
Research Methodology
A standing panel of spa operations directors, regulatory affairs specialists, corporate wellness procurement managers, and hydrotherapy equipment distributors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA cosmetic registration databases, EU ECHA substance restriction filings, ASEAN cosmetic directive harmonization texts, and hotel chain SEC disclosures. Bottom-up facility counts triangulated against top-down spending estimates from employer benefits surveys.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling spanned service type, end user category, technology generation, and pricing model commitment depth. CAGRs derived from iterative convergence between demand-side utilization projections and supply-side capacity expansion plans. Industry-specific inputs incorporated hydrotherapy equipment lead time data and botanical extract price indices.
Decision-makers should treat outputs as directional under sustained corporate wellness budget allocation and REACH enforcement continuity assumptions; material deviation would warrant model refresh. Specific risks include DIY device substitution acceleration and licensed practitioner training pipeline failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Global Healthcare Contract Manufacturing Market