
 Audiology Services Market | 2026-2036
Audiology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Audiology Services Market Analysis
ASHA Certificate of Clinical Competence in Audiology is redrawing competitive barriers, elevating practice standards that independent clinics and hospital departments must meet. Sonova leverages its vertically integrated manufacturing network to control device-to-service margins across North American and European clinics. Demant anchors its position through Oticon-branded hearing aid technology paired with diagnostic service partnerships in retail audiology chains.
Audiology services encompass the clinical assessment, diagnosis, treatment, and rehabilitation of hearing and balance disorders using calibrated audiometric equipment, tympanometry, and otoacoustic emission testing to achieve thresholds measured in decibels hearing level. These services restore communication function, prevent occupational hearing loss, and manage pediatric developmental milestones tied to auditory processing. Diagnostic testing commands the largest revenue share due to mandatory newborn hearing screening mandates and workplace compliance protocols, while tele-audiology represents the fastest-expanding delivery channel as remote programming and telehealth reimbursement codes mature. Hearing aids as a service category concentrate margin pools in bundled fitting and follow-up care rather than device margins alone.
FDA oversight of hearing aid classification and the EU Medical Device Regulation reshape product-service bundling, with MDR technical documentation requirements extending to software-enabled fitting systems. The EPA and OSHA jointly govern occupational noise exposure limits that drive industrial audiology demand and hearing conservation program mandates. Stakeholders must monitor reimbursement parity between in-person and remote audiology delivery as telehealth policy stabilizes across Medicare, Medicaid, and commercial payer frameworks.
Market Dynamics
Tele-audiology reimbursement parity under Medicare and Medicaid frameworks is restructuring how audiology services reach patients, compressing the traditional clinic-centric model while expanding remote diagnostic and hearing aid fitting capabilities across rural and underserved catchment areas.
Growth Catalysts
- ASHA Certificate of Clinical Competence:Rising credential requirements for audiologists elevate service quality benchmarks and drive patient traffic toward certified providers in hospital outpatient departments.
- Occupational Noise Exposure Mandates:EPA and OSHA joint enforcement of hearing conservation programs sustains industrial audiology demand across manufacturing, construction, and mining sectors requiring annual audiometric testing.
- Newborn Hearing Screening Protocols:State-mandated universal screening programs generate consistent diagnostic volume for pediatric audiology centers and early intervention referral networks.
Market Restraints
- Device-to-Service Margin Compression:Over-the-counter hearing aid availability under FDA 2022 reclassification reduces bundled fitting revenue for traditional dispensing practices.
- Audiologist Supply Concentration:Limited graduation capacity from Au.D. programs creates talent bottlenecks in rural United States markets and lengthens patient appointment wait times.
- Reimbursement Rate Stagnation:Medicare fee schedule constraints on diagnostic testing codes limit revenue expansion even as service complexity increases.
Strategic Opportunities
- Remote Programming Platforms:Cloud-enabled hearing aid adjustment software creates subscription-based recurring revenue streams independent of device sales cycles.
- Cochlear Implant Candidacy Expansion:Relaxed FDA criteria for single-sided deafness and asymmetric hearing loss broaden the surgical audiology referral pipeline.
- Direct-to-Employer Contracts:Occupational health clinics bypass payer intermediaries by contracting directly with Fortune 500 manufacturing employers for on-site hearing conservation services.
Industry Challenges
- Telehealth Licensing Fragmentation:Interstate practice restrictions and state-level audiology board regulations complicate multi-state tele-audiology service delivery.
- Legacy Equipment Integration:Existing clinic investments in standalone audiometer hardware resist seamless connectivity with cloud-based practice management and remote fitting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audiology Services Market |
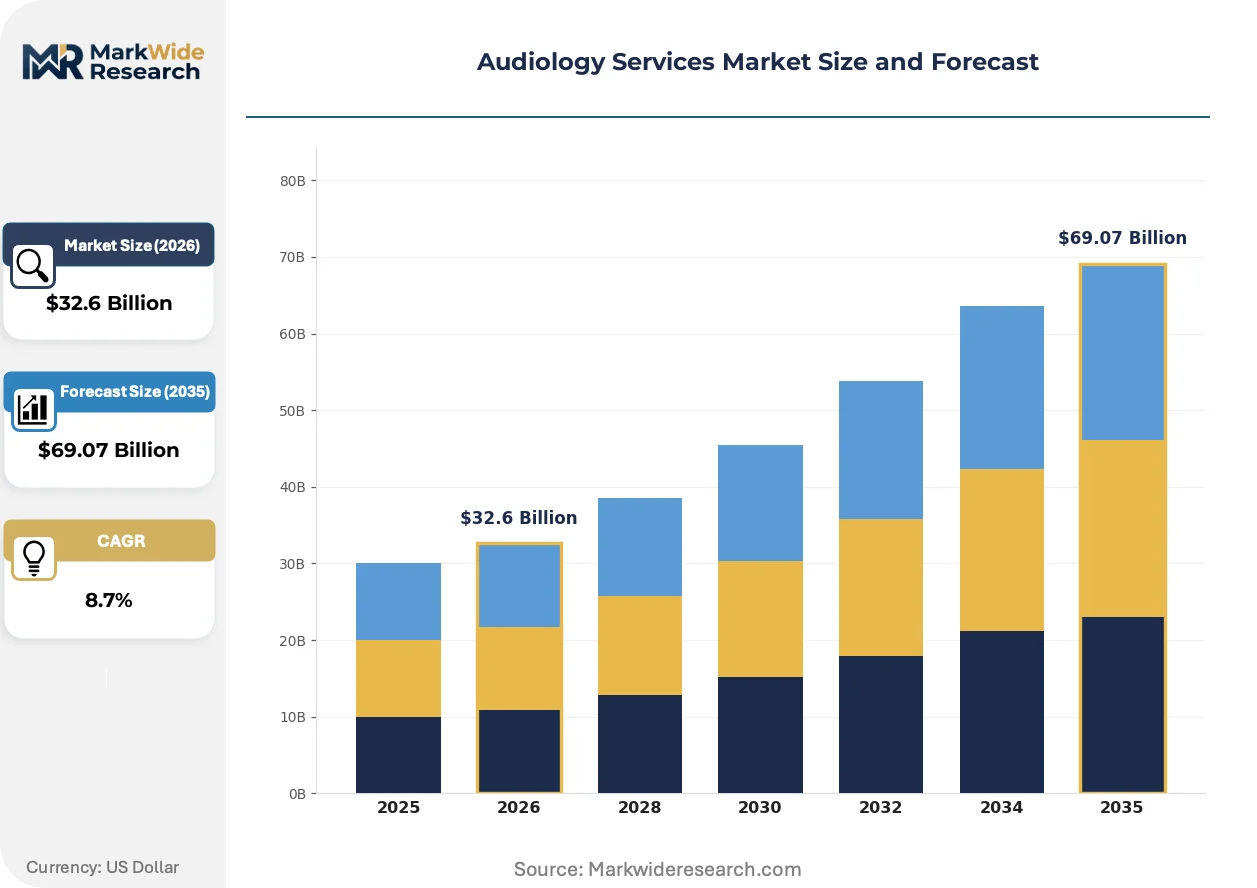
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Testing, Hearing Aids, Rehabilitation, Counseling End User: Hospitals, Clinics, Home Care, Schools Technology: Digital Signal Processing, Bone Anchored Hearing Aids, Cochlear Implants, Assistive Listening Devices Application: Pediatric Audiology, Geriatric Audiology, Industrial Audiology, Tele-Audiology |
| Companies Covered | Sonova, Demant, WS Audiology, GN Hearing, Starkey Hearing Technologies, Cochlear, Amplifon, MED-EL, Oticon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audiology Services Market Emerging Trajectories
Artificial intelligence is penetrating audiology workflows at the diagnostic and rehabilitative layers simultaneously, enabling automated audiogram interpretation and adaptive hearing aid signal processing that reduces clinical labor intensity while improving patient-reported outcomes.
Machine learning algorithms embedded in diagnostic software are decomposing the traditional audiologist-interpreter role by flagging threshold patterns and suggesting differential diagnoses for sensorineural versus conductive pathologies. Hospital audiology departments in the United States and Germany are piloting these tools to accelerate throughput in high-volume screening environments. This capability compression is enabling mid-level technicians to conduct expanded scope testing under reduced supervision, reshaping staffing models and cost structures in high-throughput settings.
The EU Medical Device Regulation technical documentation requirements now extend to hearing aid fitting software and cloud-connected programming interfaces, forcing manufacturers to revalidate legacy platforms under stricter clinical evidence standards. This regulatory expansion delays product launches by 12-18 months for software-enabled devices. European audiology chains are responding by consolidating vendor relationships toward MDR-compliant suppliers with established quality management systems.
Patients are unbundling after-sales service from device acquisition, purchasing hearing aids through direct online channels and seeking à la carte programming and maintenance from local clinics. This disintermediation pressure concentrates in the United States where OTC availability and third-party warranty administrators accelerate the separation of hardware and service transactions. Independent practices are countering by emphasizing diagnostic expertise and custom earmold fabrication as non-commoditized value anchors.
Audiology Services Market Segmentation
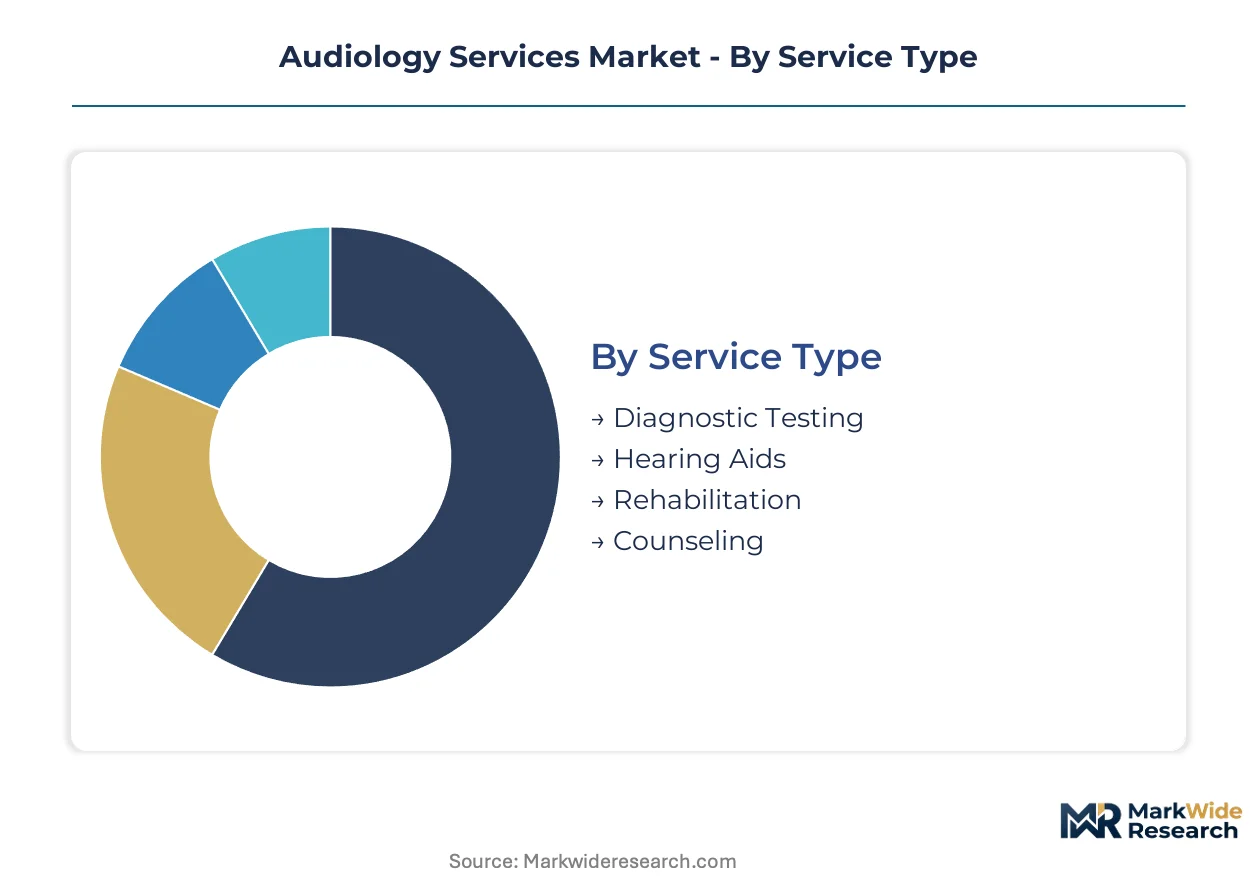
Margin distribution across audiology services favors high-complexity diagnostics and recurring rehabilitation protocols over transactional device sales. Understanding segment-level profitability drivers enables targeted capacity allocation across service delivery models and patient populations.
Service Type:
Diagnostic Testing commands the deepest margin pools due to mandatory newborn screening mandates and workplace compliance testing that insulates pricing from direct consumer price sensitivity. Hearing Aids as a service category concentrates profitability in bundled fitting and follow-up care rather than hardware margins alone.
- Diagnostic Testing:Calibrated audiometric assessment, tympanometry, and otoacoustic emission testing performed in controlled clinical environments. Demand concentrates in hospital outpatient departments across the United States where ASHA-certified audiologists command premium reimbursement rates for threshold documentation required by OSHA hearing conservation programs.
- Hearing Aids:Device selection, custom fitting, real-ear verification, and programmed amplification delivery. Margin pools are rotating toward bundled service contracts in European retail chains as the EU MDR extends technical documentation requirements to software-enabled fitting systems, delaying product launches and favoring established suppliers.
- Rehabilitation:Auditory training, speechreading instruction, and communication strategy counseling for acquired hearing loss patients.
- Counseling:Patient education, device orientation, and psychosocial support services addressing hearing loss stigma and family communication dynamics.
Diagnostic Testing holds installed capacity. Hearing Aids is rotating up the share rankings through recurring revenue from remote programming subscriptions.
End User:
Volume concentration varies sharply by reimbursement environment and regulatory inspection frequency, with hospital-based services benefiting from integrated electronic health record workflows that reduce administrative friction.
- Hospitals:Acute care audiology departments, outpatient diagnostic centers, and surgical cochlear implant programs. Patient traffic concentrates in United States academic medical centers where Medicare Advantage bundling of audiology benefits drives referral volume from primary care networks.
- Clinics:Independent audiology practices, retail hearing aid dispensaries, and franchise audiology chains. Germany's statutory health insurance reimbursement framework supports clinic-based diagnostic volume through defined benefit catalogs that specify audiometric testing frequencies.
- Home Care:Mobile audiometric testing, residential hearing aid fitting, and tele-audiology delivery to homebound patients.
- Schools:Educational audiology services, classroom amplification system management, and pediatric hearing screening in district-based programs.
Hospitals anchor the reimbursement premium tier. Home Care is climbing the fastest as telehealth parity legislation matures.
Technology:
Technology selection determines capital intensity and regulatory pathway complexity, with implantable solutions requiring surgical partnership structures that reshape competitive positioning.
- Digital Signal Processing:Algorithm-driven sound classification, directional microphone beamforming, and adaptive noise reduction in behind-the-ear and in-the-canal devices. Adoption concentrates in United States retail audiology chains where real-ear measurement verification protocols justify premium fitting fees.
- Cochlear Implants:Surgically implanted electrode arrays and external speech processors for severe-to-profound sensorineural hearing loss. Candidacy expansion for single-sided deafness under relaxed FDA criteria is broadening the surgical audiology referral pipeline in major United States metropolitan markets.
- Bone Anchored Hearing Aids:Osseointegrated titanium implants and abutment-mounted sound processors for conductive or mixed hearing loss.
- Assistive Listening Devices:FM systems, infrared receivers, induction loop amplifiers, and personal alerting equipment for situational hearing access.
Digital Signal Processing dominates unit volume. Cochlear Implants is expanding most quickly through expanded FDA candidacy criteria.
Application:
Application-level segmentation reflects demographic targeting and service delivery infrastructure requirements, with pediatric protocols demanding specialized equipment and family-centered care coordination.
- Pediatric Audiology:Behavioral audiometry, visual reinforcement audiometry, and auditory brainstem response testing for infants and children. State-mandated universal newborn hearing screening in the United States generates consistent diagnostic volume for early intervention referral networks.
- Tele-Audiology:Remote diagnostic testing, cloud-based hearing aid programming, and virtual follow-up consultations. Medicare and Medicaid reimbursement parity frameworks are restructuring service delivery across rural United States catchment areas previously underserved by brick-and-clinic infrastructure.
- Geriatric Audiology:Presbycusis management, cognitive screening integration, and long-term care facility services for aging populations.
- Industrial Audiology:Hearing conservation programs, annual audiometric testing, and occupational noise exposure monitoring for regulated employers.
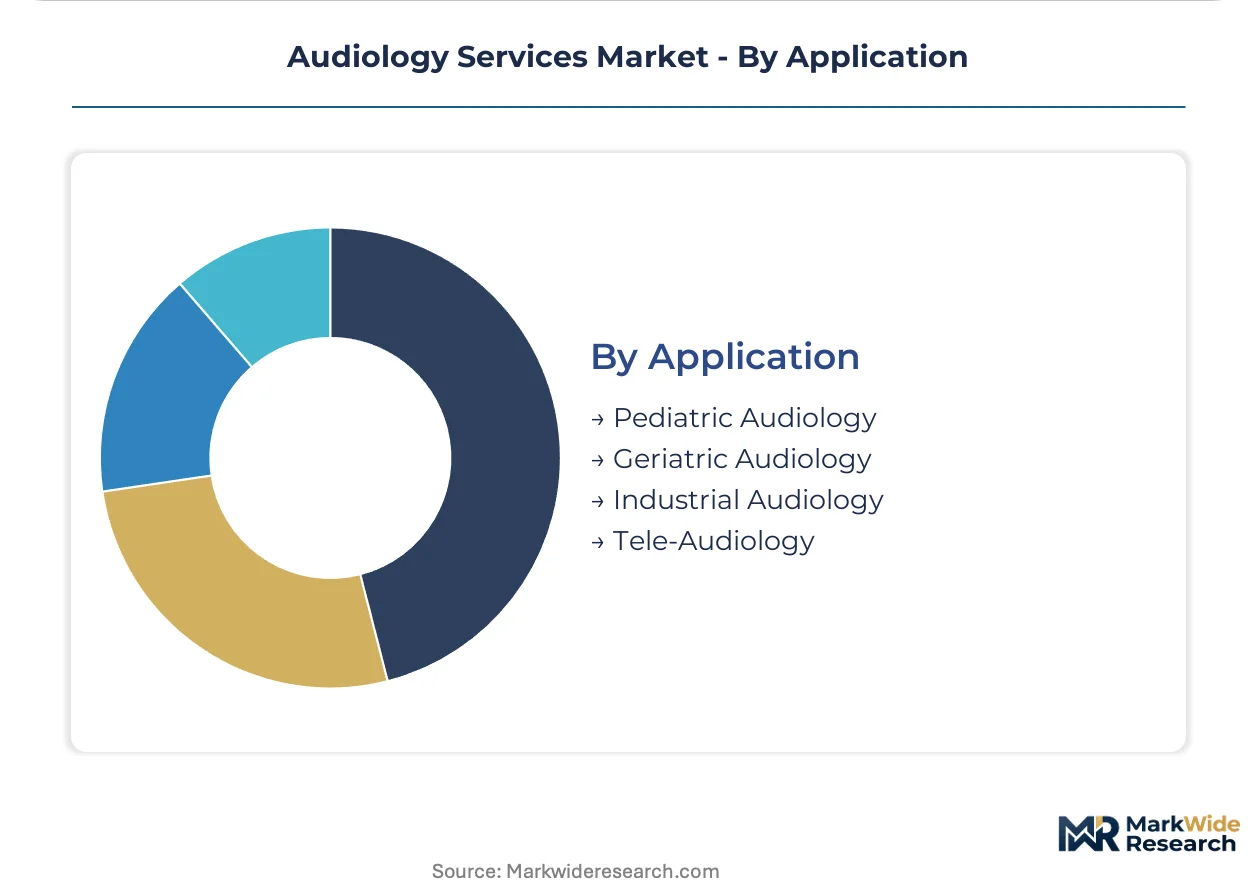
Pediatric Audiology holds regulatory-mandated volume stability. Tele-Audiology is gaining share fastest through reimbursement policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Advantage bundling of audiology benefits and FDA regulatory frameworks for over-the-counter hearing aids are reshaping service delivery economics across mature healthcare markets. Regional concentration reflects reimbursement policy maturity, aging demographic density, and occupational health regulatory enforcement intensity.
United States
Medicare Advantage plans increasingly bundle audiology benefits, driving referral volume from primary care networks into hospital outpatient departments. FDA premarket notification requirements for OTC hearing aids under the 2022 regulatory reclassification continue compressing traditional dispensing margins. Major metropolitan clusters in Boston, New York, and Los Angeles anchor academic medical center audiology programs where ASHA-certified audiologists command premium reimbursement rates.
Germany
Statutory health insurance reimbursement frameworks support clinic-based diagnostic volume through defined benefit catalogs specifying audiometric testing frequencies. EU Medical Device Regulation technical documentation requirements extend to hearing aid fitting software, delaying product launches by established suppliers. The North Rhine-Westphalia and Bavaria regions concentrate retail audiology chain presence where Oticon-branded technology pairs with diagnostic service partnerships.
United Kingdom
National Health Service audiology waiting list pressures are accelerating private sector service expansion alongside NHS outsourcing contracts. Care Quality Commission inspection regimes elevate practice standards that independent clinics must meet to maintain registration. London and Southeast England cluster private audiology capacity where real-ear measurement verification protocols justify premium fitting fees.
Japan
Ministry of Health, Labour and Welfare reimbursement schedules for hearing aid fitting services create stable revenue baselines for clinic operators. METI industrial standards for assistive listening devices in workplace settings sustain occupational audiology demand. The Kanto region around Tokyo concentrates cochlear implant surgical audiology programs where expanded candidacy criteria for single-sided deafness broaden referral pipelines.
Australia
TGA oversight of hearing aid classification aligns with international regulatory convergence, streamlining market entry for software-enabled fitting systems. Workplace health and safety mandates for hearing conservation programs in mining and manufacturing sectors generate consistent industrial audiology volume. New South Wales and Victoria anchor tele-audiology pilot programs as Medicare reimbursement parity for remote services matures.
Audiology Services Market Vendor Landscape
Listed leaders compete with private specialists across device manufacturing and clinical service delivery dimensions. The market structures around vertically integrated hearing aid manufacturers with captive clinic networks, independent retail chains with vendor-agnostic dispensing, and hospital-based departments with diagnostic specialization. Three archetypes dominate: manufacturer-owned service networks controlling device-to-service margins, independent audiology practices emphasizing diagnostic expertise, and occupational health contractors delivering on-site hearing conservation. Consolidation pressures concentrate through acquisition of independent practices by retail chains, while technology licensing partnerships proliferate between diagnostic software developers and clinic management platforms.
Within the manufacturer-integrated tier, Sonova and Demant occupy positions exemplifying vertical control from component production through clinic service delivery. WS Audiology represents the scale-driven archetype formed through merger consolidation. These entities anchor competitive dynamics by bundling hardware with recurring service revenue streams, forcing independent practices toward diagnostic differentiation and custom fabrication capabilities as non-commoditized value anchors.
| Leading Market Players |
|---|
| Sonova |
| Demant |
| WS Audiology |
| GN Hearing |
| Starkey Hearing Technologies |
| Cochlear |
| Amplifon |
| MED-EL |
| Oticon |
| Others |
Supply Flow & Price Mechanics
Cloud-based fitting software displacing standalone hardware simultaneously redistributes manufacturing value toward United States and German software development clusters while compressing capital equipment pricing tiers for traditional audiometer vendors.
Pricing Analysis
Certification level under FDA 510(k) and EU MDR pathways creates the primary spread between premium hospital-grade diagnostics and economy retail dispensing tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ASHA-credentialed providers commanding premium fitting fees while OTC-direct channels erode transactional hardware margins. Cost compression in bundled service contracts is intensifying because patients unbundle device acquisition from after-sales programming. Employer-sponsored occupational health contracts exhibit lowest price sensitivity; direct-to-consumer online channels face highest.
Supply Chain Analysis
Inventory cycles for semiconductor-dependent DSP chips now stretch 18-24 months, forcing audiology manufacturers toward dual-sourcing arrangements. Component production concentrates in Taiwan, South Korea, and Germany. Supply chains draw from rare earth magnet suppliers for receiver assemblies, medical-grade silicones for earmold fabrication, and ASIC foundries for signal processing cores. Single-source vulnerability in Bluetooth Low Energy module supply threatens hearing aid launch schedules. Distribution runs through manufacturer-owned clinic networks, independent retail chains, and hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tele-audiology reimbursement parity under Medicare and Medicaid frameworks signals early-cycle expansion, with remote service penetration still below 15% of addressable clinical volume despite regulatory tailwinds.
For Market Incumbents: Fortify diagnostic service differentiation against OTC device commoditization by deepening real-ear measurement capabilities and custom earmold fabrication expertise. Invest in backward integration into cloud-based programming platforms to capture recurring subscription revenue streams independent of hardware replacement cycles. Prioritize MDR-compliant software validation to defend European market positioning against delayed product launches. For New Entrants and Emerging Players: Anchor in rural United States catchment areas where audiologist supply concentration creates appointment wait-time bottlenecks and telehealth licensing fragmentation has slowed incumbent response. Target industrial audiology contracts with Fortune 500 manufacturing employers seeking on-site hearing conservation program outsourcing. Deploy direct-to-employer sales models bypassing traditional payer intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed audiology retail chains consolidating independent practices into regional platforms. Long-term viability hinges on recurring revenue mix from remote programming subscriptions versus transactional device sales. Watch telehealth licensing harmonization across state audiology boards as inflection indicator for tele-audiology platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Programming Platform Development | Cloud-enabled hearing aid adjustment software creates subscription-based recurring revenue streams independent of device sales cycles. |
| MDR Compliance Investment | EU Medical Device Regulation technical documentation requirements extend to fitting software, delaying product launches for non-compliant suppliers. |
| Direct-to-Employer Contracting | Occupational health clinics bypass payer intermediaries by contracting directly with Fortune 500 manufacturing employers for on-site services. |
| ASHA Certification Expansion | Certificate of Clinical Competence requirements elevate service quality benchmarks and drive patient traffic toward certified hospital providers. |
| Telehealth Licensing Harmonization | Interstate practice restrictions and state-level audiology board regulations complicate multi-state tele-audiology service delivery expansion. |
Methodological Framework
A standing panel of audiology clinic directors, hospital outpatient department managers, hearing aid manufacturing supply chain executives, and Medicare reimbursement specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare fee schedules, and ASHA certification records. Bottom-up service volume estimates triangulated against top-down reimbursement expenditure data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated service type, end-user setting, technology platform, and application area dimensions. CAGRs derived from regression analysis of historical reimbursement trends and audiology workforce graduation rates. Forecast inputs included telehealth parity legislation progression, FDA OTC hearing aid adoption curves, and EU MDR implementation timelines.
Material uncertainties — regulatory delays in tele-audiology licensing harmonization, audiologist workforce supply constraints, and OTC hearing aid penetration rates — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and technology adoption curves. Revision becomes warranted when tele-audiology reimbursement parity crosses 50% of commercial payer contracts or when OTC hearing aid sales volume exceeds bundled fitting service volume in major metropolitan markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Bruxism Management Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Acute Care Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Global Contract Sterilization Market