
 Packaging and Labeling (Healthcare) Services Market | 2026-2036
Packaging and Labeling (Healthcare) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging and Labeling (Healthcare) Services Market Outlook
Biopharmaceutical cold-chain logistics is expanding as the fastest-growing buyer segment for healthcare packaging services. Amcor leverages its global film and foil portfolio to anchor temperature-assured formats for mRNA therapies. Gerresheimer AG specializes in glass-primary containment systems that sustain stringent stability profiles for injectable biologics. CCL Industries dominates serialized label supply, competing directly with compliance-driven mandates across North America and Europe.
Packaging and Labeling (Healthcare) Services encompasses the design, fabrication, and application of protective enclosures and informational markings for pharmaceuticals, biologics, and medical devices, typically employing multi-layer barrier films, desiccant-integrated structures, and tamper-evident closures to ensure product integrity through distribution. Its primary commercial purpose is to satisfy regulatory traceability requirements while preserving sterility, potency, and shelf-life from manufacture through patient administration. Primary packaging occupies the highest-margin pool due to direct drug-contact certification burdens and material science intensity, while serialization and compliance labeling represent the fastest-growing technology segment as regulators mandate unit-level traceability. Digital printing is maturing as a flexible, short-run alternative for clinical-trial batches and personalized medicine formats where changeover speed outweighs unit cost.
FDA DSCSA deadlines and EU MDR traceability requirements are forcing wholesale infrastructure upgrades across the packaging value chain, with both frameworks mandating interoperable serialization databases that reshape vendor qualification criteria. Health Canada and ANVISA have aligned with comparable track-and-trace standards, tightening market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictional serialization formats and decide whether to deploy unified global platforms or region-specific compliance architectures.
Market Dynamics
Serialization mandates across multiple jurisdictions are forcing capital redeployment toward track-and-trace infrastructure, compressing margins for mid-tier contract packagers while advantaging integrated players with pre-certified digital platforms. Cold-chain biologics expansion is simultaneously pulling investment toward temperature-assured primary packaging formats.
Growth Catalysts
- EU MDR Serialization Mandates:The European Union's Medical Device Regulation traceability requirements are compelling healthcare manufacturers to outsource compliant labeling operations to specialized contract service providers.
- mRNA Therapy Cold-Chain Expansion:Biopharmaceutical developers of temperature-sensitive nucleic acid therapies require validated thermal packaging systems that sustain ultra-low temperature profiles through last-mile distribution.
- FDA DSCSA Compliance Deadlines:The Drug Supply Chain Security Act's interoperable database requirements are accelerating vendor consolidation toward serialization-capable packaging partners.
Market Restraints
- Aluminum Foil Supply Concentration:Barrier film laminates depend on concentrated Asian smelter output, exposing converters to input cost volatility and geopolitical supply disruption.
- Specialized Equipment Lead Times:Serialization line installations face 18-24 month delivery cycles from German and Italian machinery builders, constraining capacity expansion velocity.
- Regulatory Divergence Friction:Non-harmonized data matrix formats between FDA DSCSA, EU MDR, and Health Canada requirements force redundant qualification protocols.
Strategic Opportunities
- India Contract Packaging Scale-Up:The country's pharmaceutical manufacturing hub status and PLI scheme incentives are attracting serialization-ready packaging infrastructure investment.
- Digital Printing Convergence:Combination of inkjet deposition and inline verification systems enables economical short-run production for personalized medicine batches.
- Cell and Gene Therapy Formats:Autologous therapy logistics require patient-specific primary containment with integrated temperature monitoring and chain-of-custody documentation.
Industry Challenges
- Serialization Validation Talent Scarcity:Qualified engineers capable of IQ/OQ/PQ protocol execution for track-and-trace line qualification command premium compensation and extended recruitment timelines.
- Legacy ERP Integration Complexity:Brownfield pharmaceutical manufacturing sites face middleware development burdens when connecting aging MES platforms to modern aggregation databases.
- Cross-Border Data Sovereity Compliance:EU GDPR restrictions on patient-identifiable serialization data transfer complicate centralized cloud architecture deployment for multinational packaging networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging and Labeling (Healthcare) Services Market |
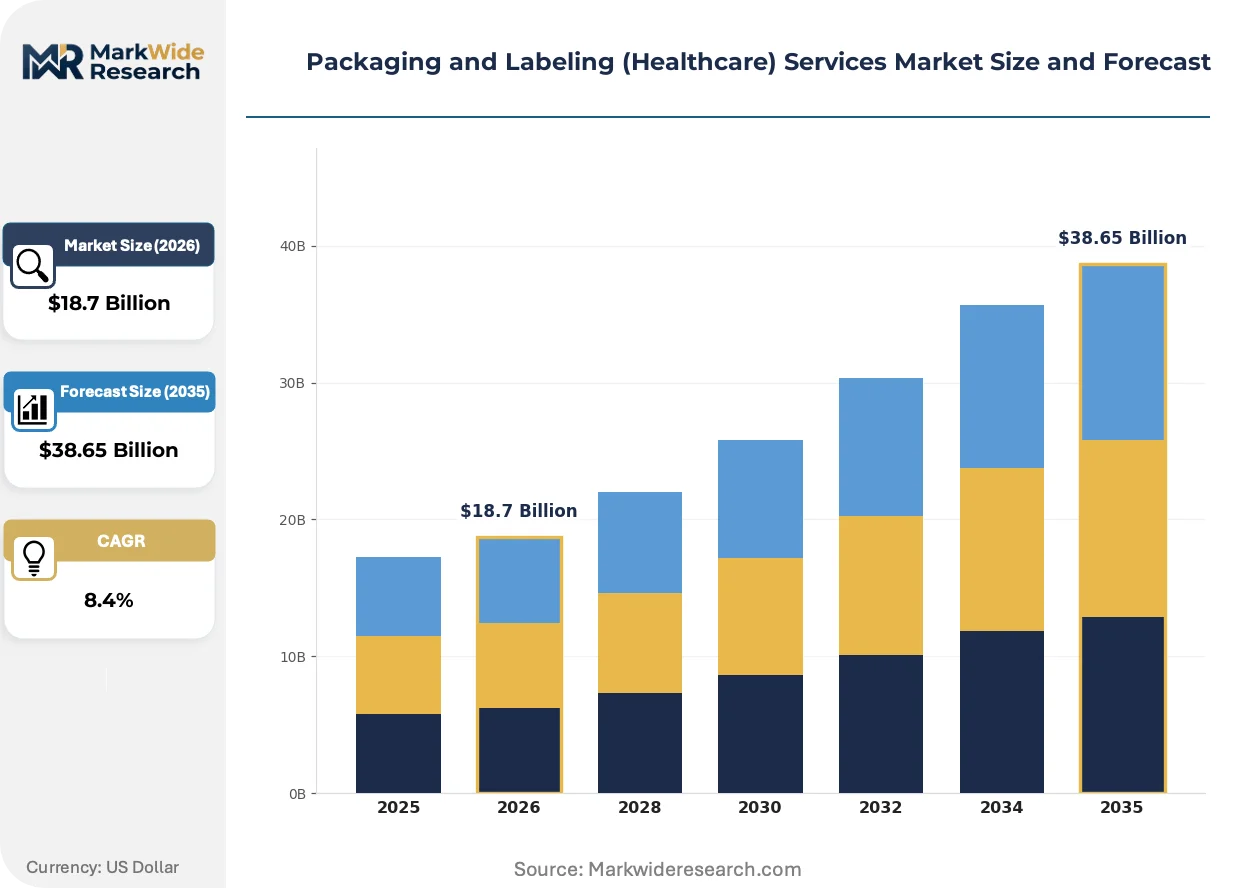
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Packaging, Secondary Packaging, Labeling Solutions, Tamper-Evident Packaging Packaging Type: Blister Packs, Bottles, Sachets, Pouches End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Hospitals Technology: Digital Printing, Automated Packaging, Serialization, Compliance Labeling |
| Companies Covered | CCL Industries, Gerresheimer AG, Amcor, Schott AG, Berry Global, Smurfit WestRock, Graphic Packaging, WestRock Company, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging and Labeling (Healthcare) Services Market Strategic Shifts
Active pharmaceutical ingredient complexity is driving material science investment toward multi-layer barrier systems, while regulatory data requirements are digitizing formerly analog packaging workflows. These forces are compressing traditional equipment replacement cycles and reshaping vendor qualification criteria.
Smart labels incorporating printed electronics and near-field communication chips are absorbing capital from conventional pressure-sensitive adhesive applications. Biologics manufacturers with temperature-critical distribution requirements are adopting these formats at accelerated procurement velocities. The technology is absorbing margin from passive cold-chain indicators by enabling real-time excursion alerts and automated documentation.
EU MDR Article 27 mandates for unique device identification are restructuring European medical device packaging operations. The regulation requires machine-readable labels on all Class III and implantable devices, forcing contract packagers to deploy vision-verified printing systems. German and Irish manufacturing clusters are responding fastest, with Italian device makers trailing due to smaller average enterprise scale.
Biopharmaceutical procurement departments are consolidating vendor panels around full-service packaging partners capable of primary containment, secondary assembly, and serialization under single quality agreements. This behavior compresses the addressable market for single-service converters. The shift is most visible in United States oncology therapy launches, where sponsor companies prioritize speed-to-clinic over unit cost minimization.
Packaging and Labeling (Healthcare) Services Market Segmentation
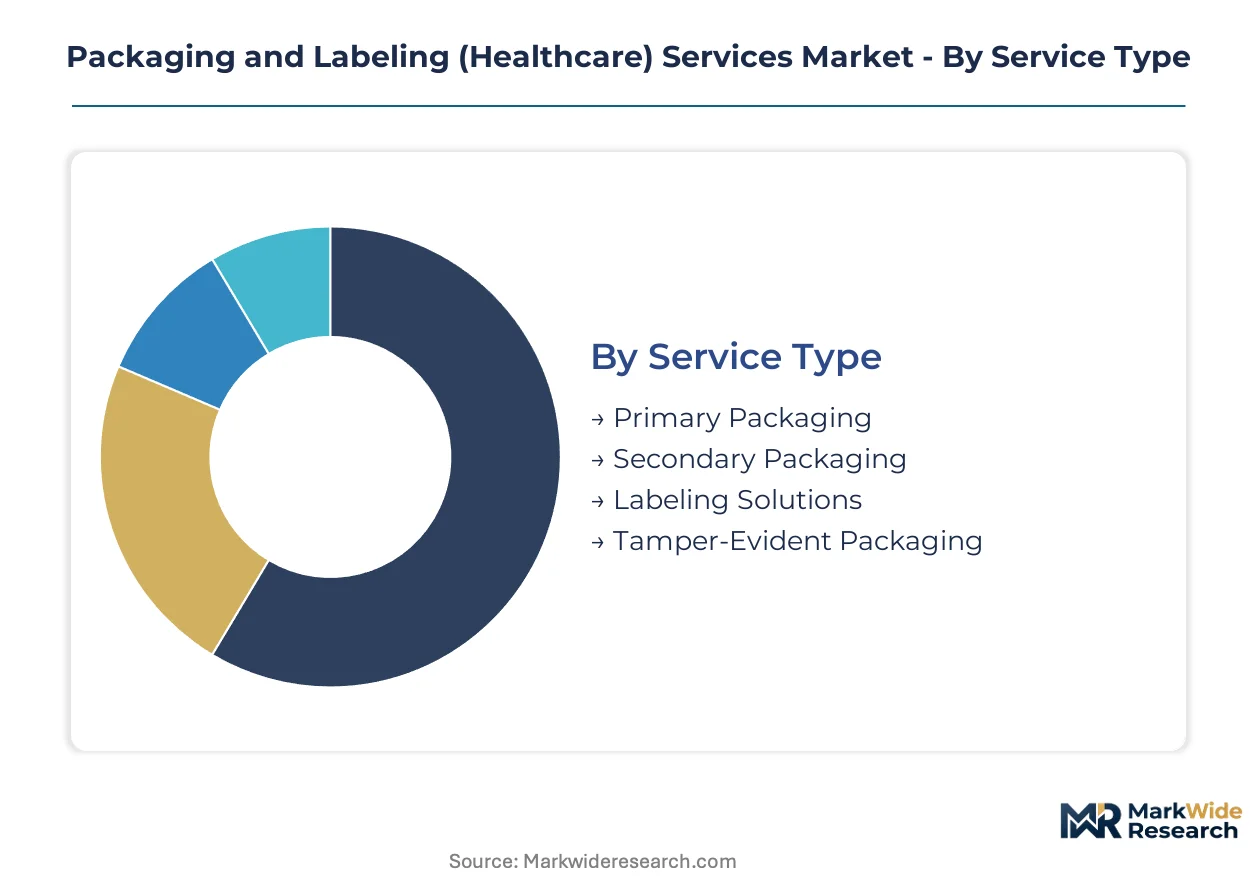
Healthcare packaging services fragment across service depth, material format, and regulatory intensity. Each segment carries distinct margin profiles and capital requirements that reshape vendor selection criteria for pharmaceutical sponsors.
Service Type:
Customization intensity varies from standardized secondary assembly to validated primary containment requiring drug-contact certification.
- Primary Packaging:Direct-contact barrier systems including vials, syringes, and ampoules that maintain sterility and stability profiles for biologics. Demand concentrates among mRNA therapy developers in Germany and the United States seeking validated cold-chain formats with integrated desiccant and oxygen scavenger technologies.
- Secondary Packaging:Cartoning, kit assembly, and bundle collation that protects primary units during distribution. Contract manufacturers in India are scaling secondary capacity fastest to support export-oriented pharmaceutical production under CDSCO oversight.
- Labeling Solutions:Pressure-sensitive and booklet label application with vision-verified placement accuracy. Pharmaceutical companies outsource these operations to navigate EU MDR and FDA DSCSA format requirements without dedicated line investment.
- Tamper-Evident Packaging:Breakable seals, shrink bands, and holographic indicators that signal unauthorized access. Hospitals and retail pharmacies drive procurement for opioid and controlled-substance distribution security.
Leading the category by volume: Secondary Packaging. Growing fastest: Primary Packaging.
Packaging Type:
Material selection tracks dosage form requirements and patient compliance preferences across oral, injectable, and topical delivery routes.
- Blister Packs:Thermoformed PVC or aluminum cavities with lidding foil that deliver unit-dose precision for solid oral dosages. Biotech firms in Switzerland and the United States specify high-barrier cold-form aluminum blisters for moisture-sensitive small molecules.
- Bottles:HDPE and PET containers with child-resistant closures for chronic medication regimens. Pharmaceutical companies in the United States favor bottles for large-volume generics where manufacturing scale outweighs unit-dose convenience.
- Sachets:Flexible single-use pouches for powders, granules, and oral dissolving films. Demand is climbing fastest for pediatric and geriatric formulations in India where cost minimization drives format selection.
- Pouches:Multi-layer stand-up or flat formats for medical devices and combination products. Contract manufacturers deploy pouches for sterilized surgical kits requiring breathable Tyvek panels.
Dominant by revenue: Blister Packs. Expanding most quickly: Sachets.
End User:
Procurement sophistication ranges from centralized vendor management at multinational pharmas to fragmented purchasing at institutional healthcare providers.
- Pharmaceutical Companies:Brand and generic drug developers with internal packaging operations that supplement capacity through contract service agreements. These sponsors prioritize serialization-ready partners capable of supporting FDA DSCSA and EU MDR compliance deadlines.
- Biotech Firms:Venture-backed developers of monoclonal antibodies, cell therapies, and nucleic acid platforms. Cold-chain validation capabilities dominate vendor qualification for these temperature-sensitive biologics.
- Contract Manufacturers:CDMOs and CMOs offering integrated manufacturing and packaging under single quality agreements. These intermediaries consolidate demand across multiple sponsor clients, driving volume concentration at top-tier service providers.
- Hospitals:Health systems and pharmacy chains managing unit-dose repackaging for inpatient administration. These buyers emphasize tamper-evidence and bar-code verification to support medication safety protocols.
Controlling largest share: Pharmaceutical Companies. Gaining share fastest: Biotech Firms.
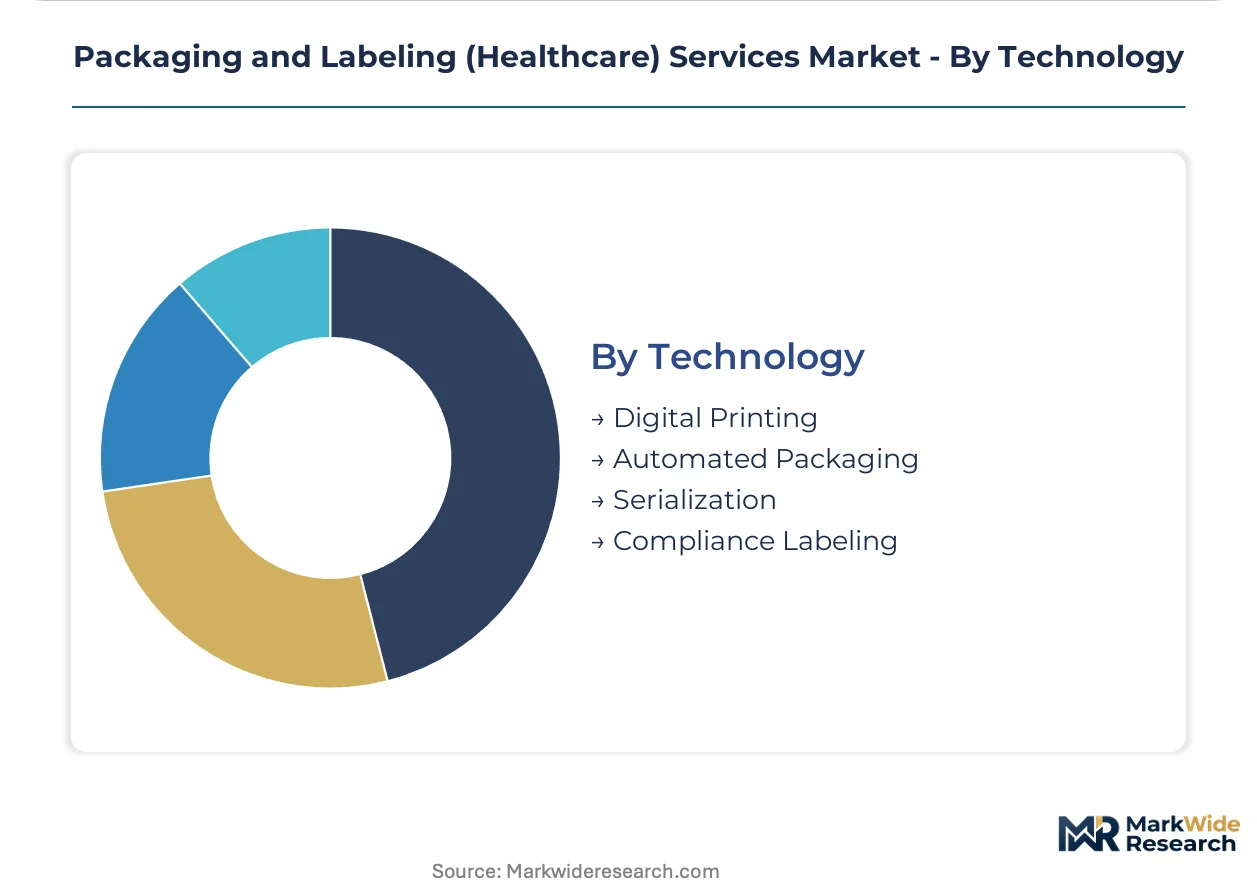
Technology:
Capital intensity escalates from conventional mechanical systems to software-integrated platforms requiring validation documentation and specialized engineering talent.
- Digital Printing:Inkjet and toner-based deposition enabling variable data and short-run flexibility without plate changeover. Clinical trial supply groups leverage this technology for protocol-specific label versioning with rapid turnaround.
- Automated Packaging:Robotic pick-and-place, cartoning, and palletizing systems that reduce labor dependency and human error. Contract manufacturers in Germany deploy these lines to meet pharmaceutical labor cost and quality consistency requirements.
- Serialization:Track-and-trace infrastructure applying unique identifiers with aggregation to case and pallet levels. FDA DSCSA and EU MDR mandates are forcing universal adoption regardless of end-user scale or geographic focus.
- Compliance Labeling:Regulatory-specific formats incorporating 2D data matrices, human-readable lot numbers, and anti-counterfeiting features. Health Canada and ANVISA alignment with international standards is expanding addressable demand for these specialized services.
Highest installed base: Automated Packaging. Steepest expansion trajectory: Serialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Export Zones and Special Economic Zones in Gujarat and Maharashtra concentrate contract packaging capacity for export-oriented drug manufacturers. These zones offer tax holidays and duty exemptions that attract serialization-ready infrastructure investment from multinational service providers.
United States
Oncology therapy launches and mRNA vaccine distribution networks drive demand for temperature-assured primary packaging. FDA DSCSA compliance deadlines force wholesale infrastructure upgrades across pharmaceutical distribution channels. The Greater Boston and San Francisco Bay Area biotech clusters prioritize speed-to-clinic over unit cost when selecting packaging partners.
Germany
Injectable biologics manufacturing and medical device production anchor demand for glass-primary containment systems and UDI-compliant labeling. EU MDR Article 27 mandates reshape packaging operations for Class III and implantable devices. The Rhine-Main and Bavarian industrial corridors deploy vision-verified printing systems fastest to meet regulatory deadlines.
India
Pharmaceutical manufacturing hub status and PLI scheme incentives attract serialization-ready packaging infrastructure for export markets. CDSCO oversight aligns with international track-and-trace standards for regulated destinations. The Baddi-Barotiwala-Nalagarh belt and Hyderabad-Visakhapatnam corridor scale secondary packaging capacity for generic drug exports.
Switzerland
High-value biologics and precision therapeutics require validated cold-chain formats with integrated stability monitoring. Swissmedic regulations enforce stringent quality agreements for drug-contact packaging materials. The Basel region and Lake Geneva biotech cluster concentrate demand for multi-layer barrier systems and patient-specific containment solutions.
Canada
Health Canada alignment with FDA DSCSA and EU MDR traceability standards tightens market access requirements for packaging suppliers. Cannabis-derived pharmaceuticals and biologics cold-chain distribution expand addressable demand. The Toronto-Waterloo corridor and Montreal pharmaceutical manufacturing base upgrade aggregation database capabilities for cross-border supply chains.
Packaging and Labeling (Healthcare) Services Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated players capturing premium positioning in serialization-capable services while regional converters dominate secondary assembly. The market structure concentrates around three tiers: global material science conglomerates with film and foil portfolios, specialized primary containment glass and plastic manufacturers, and digital printing specialists serving compliance labeling mandates. Strategic archetypes include full-service packaging partners qualifying under single quality agreements, technology-focused serialization platform providers, and flexible short-run specialists for clinical trial supply. Competitive moves center on M&A activity consolidating mid-tier contract packagers and capacity expansion into India and Southeast Asian manufacturing hubs.
Among material science and primary containment specialists, Amcor anchors temperature-assured format development through its global film and foil portfolio, while Gerresheimer AG exemplifies the glass-primary containment archetype for injectable biologics stability requirements. CCL Industries occupies a position within the compliance labeling tier, competing across serialized label supply mandates in North America and Europe. These three entities represent distinct strategic positions: integrated barrier material control, drug-contact certification specialization, and regulatory format expertise.
| Leading Market Players |
|---|
| CCL Industries |
| Gerresheimer AG |
| Amcor |
| Schott AG |
| Berry Global |
| Smurfit WestRock |
| Graphic Packaging |
| WestRock Company |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-validated primary containment and standard secondary assembly manifests in both unit economics and supplier qualification burdens. Serialization-capable contract packagers command premium positioning against commodity converters while aluminum foil supply concentration from Asian smelters feeds input cost volatility through the value chain.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent clinical-trial batches from scheduled commercial production, with 18-24 month equipment delivery cycles for German and Italian serialization machinery compressing spot capacity premiums. Three-tier pricing structure across premium, standard, and economy levels tracks validation depth, with FDA drug-contact certification and EU MDR compliance status as primary differentiation drivers. Cost compression in mid-tier secondary packaging is intensifying because sponsor companies consolidate vendor panels around full-service partners. Biotech firms in the United States demonstrate least price sensitivity, prioritizing speed-to-clinic for oncology launches over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for barrier film laminates mandate multi-supplier qualification across German, Italian, and Indian machinery builders to mitigate 18-24 month equipment lead time risks. Geographic supply concentration centers on China for aluminum foil smelting, Germany for precision printing systems, and India for secondary packaging labor pools. Raw material dependencies draw from Asian aluminum output, pharmaceutical-grade glass from Germany and Switzerland, and desiccant chemistries from specialized chemical processors. Single-source vulnerability in serialization equipment creates chokepoint exposure. Distribution runs through contract manufacturer hubs in India, Germany, and the United States with direct-to-sponsor quality agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in qualified serialization engineering talent prop pricing power for pre-certified infrastructure owners across the forecast window.
For Market Incumbents: Anticipate sponsor consolidation toward full-service partners by deepening backward integration into barrier film production and expanding India-based secondary capacity under CDSCO oversight. Defensive positioning requires pre-emptive EU MDR Article 27 compliance investment before 2026 enforcement deadlines tighten vendor qualification criteria. For New Entrants and Emerging Players: Price-point gaps between premium serialization-ready primary containment and economy secondary assembly create entry space for digital printing specialists serving clinical-trial batch flexibility demands. White-space targets include patient-specific cell therapy formats and short-run personalized medicine labels where changeover speed outweighs scale economies. Go-to-market positioning should emphasize inkjet deposition with inline verification for protocol-specific versioning. For Investors and Strategic Acquirers: Re-rating potential sits with serialization-platform specialists given FDA DSCSA and EU MDR compliance deadline acceleration forcing wholesale infrastructure replacement. Long-term viability across the analysis window favors targets with pre-certified aggregation databases and established pharmaceutical quality agreements. Watch Health Canada and ANVISA track-and-trace alignment announcements as inflection indicators for North American capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Deployment | FDA DSCSA and EU MDR deadlines force interoperable database investment across contract packaging networks. |
| India Contract Packaging Scale-Up | PLI scheme incentives attract serialization-ready capacity for export-oriented pharmaceutical manufacturing. |
| Digital Printing Platform Integration | Inkjet deposition with inline verification enables economical short-run production for clinical trial supply. |
| Cold-Chain Format Validation | mRNA therapy developers require temperature-assured primary containment with integrated stability monitoring. |
| Backward Integration into Barrier Films | Amcor-style material science control anchors margin capture in temperature-assured packaging formats. |
Study Parameters
Document review covered FDA DSCSA guidance documents, EU MDR technical specifications, and pharmaceutical trade association serialization standards, complemented by interviews with contract packaging operations directors, regulatory affairs leads at biopharmaceutical sponsors, CDSCO officials, and machinery builder sales engineers. Secondary validation drew from SEC filings of listed packaging converters, EMA submission databases, and Indian Pharmaceutical Export Zone investment disclosures. Bottom-up capacity modeling triangulated against top-down pharmaceutical production forecasts.
Market size outputs and growth trajectories were generated through segmented demand modeling across service type, packaging format, end-user category, and technology platform dimensions. CAGRs were derived from regression analysis of historical contract packaging revenue against pharmaceutical pipeline expansion and regulatory compliance investment cycles. Forecast inputs incorporated serialization equipment installation lead times, aluminum foil price indices, and biopharmaceutical cold-chain distribution growth assumptions.
Underlying measurement precision varies by segment; primary packaging and serialization technology carry tighter precision than secondary assembly due to visible equipment procurement patterns. Forecasts reflect documented assumptions regarding regulatory deadline adherence and sponsor outsourcing propensity. Deviation in EU MDR enforcement timing or FDA DSCSA interoperability requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Outpatient Clinics Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market