
 Americas Reusable Gloves Market | 2026-2036
Americas Reusable Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Reusable Gloves Market Analytics
Multi-source procurement toward regional suppliers is recalibrating supply chain resilience across the Americas reusable gloves landscape. Ansell leverages its manufacturing scale to anchor industrial channel dominance in North America. Showa Group competes through specialized neoprene formulations targeting chemical resistance applications. Kimberly-Clark sustains brand strength in healthcare end-use through direct distribution to hospital networks.
Reusable gloves in the Americas encompass hand protection equipment engineered from nitrile, latex, PVC, or neoprene with thickness ratings typically spanning 4–15 mil and designed for multiple decontamination cycles before retirement. These products serve critical functions in healthcare infection control, industrial chemical handling, and food safety compliance where barrier integrity must survive repeated laundering or sterilization. Nitrile formulations command the deepest margin pools due to latex allergy mitigation and superior puncture resistance across healthcare and laboratory settings. Industrial applications represent the most mature volume segment with established procurement rhythms tied to manufacturing output cycles. Healthcare end users, particularly clinics and outpatient surgical centers, generate the fastest expansion trajectory as infection prevention budgets widen post-pandemic.
OSHA mandates glove hazard assessments under 29 CFR 1910.138 while FDA classifies medical-grade reusable gloves as Class I devices subject to quality system regulation, creating dual compliance pathways that shape product development priorities. EPA chemical resistance testing protocols further determine material selection for industrial applications, particularly in petrochemical and agricultural chemical handling. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could impose end-of-life collection obligations on manufacturers and distributors.
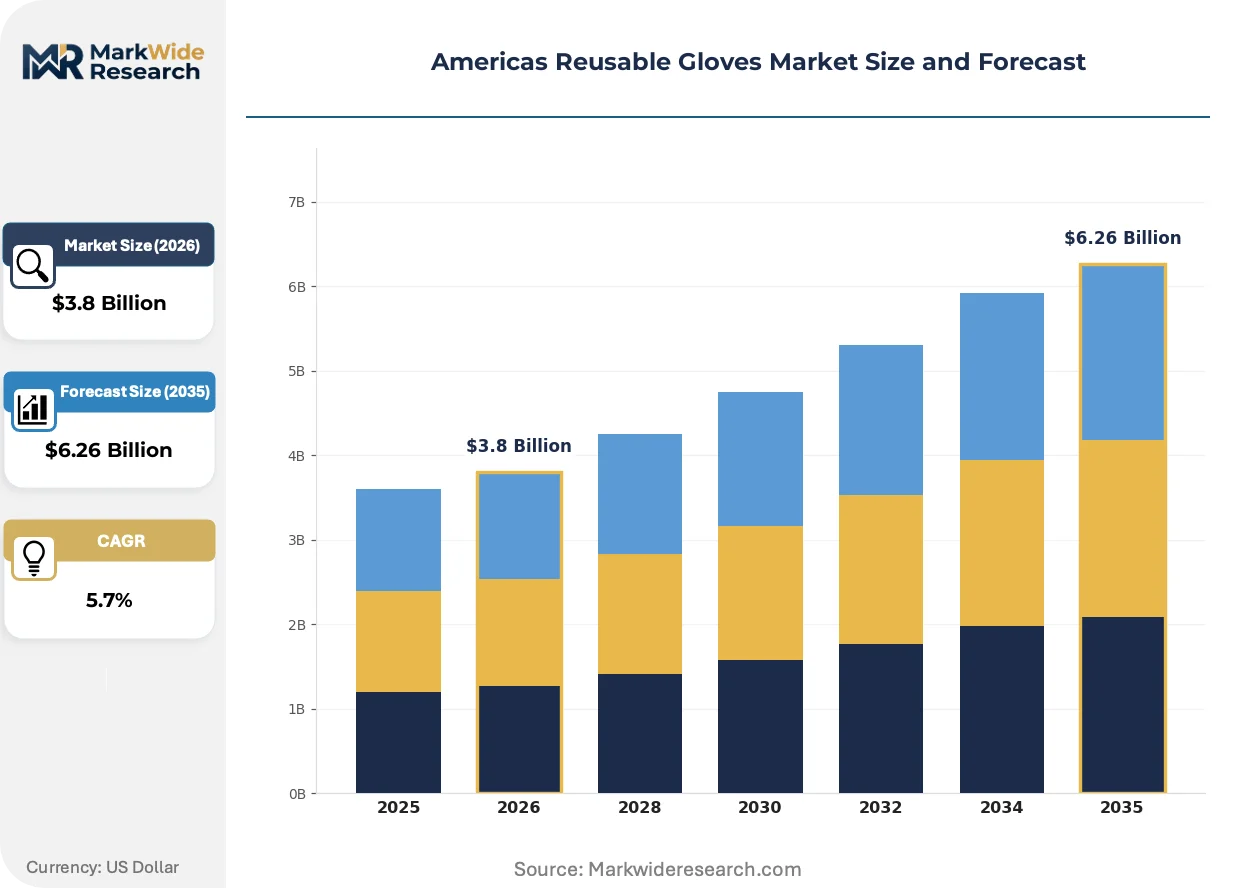
Market Dynamics
OSHA workplace safety mandates and FDA guidance updates are compressing product lifecycles across the Americas reusable gloves landscape. Manufacturers must now engineer for dual compliance pathways while maintaining cost discipline amid raw material volatility.
Growth Catalysts
- OSHA 29 CFR 1910.138:Mandatory hand hazard assessments in U.S. manufacturing facilities are expanding glove replacement cycles and specification rigor across automotive and chemical processing plants.
- Nitrile formulation advances:Puncture resistance improvements are displacing latex in healthcare procurement protocols, particularly in outpatient surgical centers managing allergy liability exposure.
- Great Lakes manufacturing corridor:Concentrated automotive and petrochemical output sustains bulk industrial consumption with predictable volume contracts.
Market Restraints
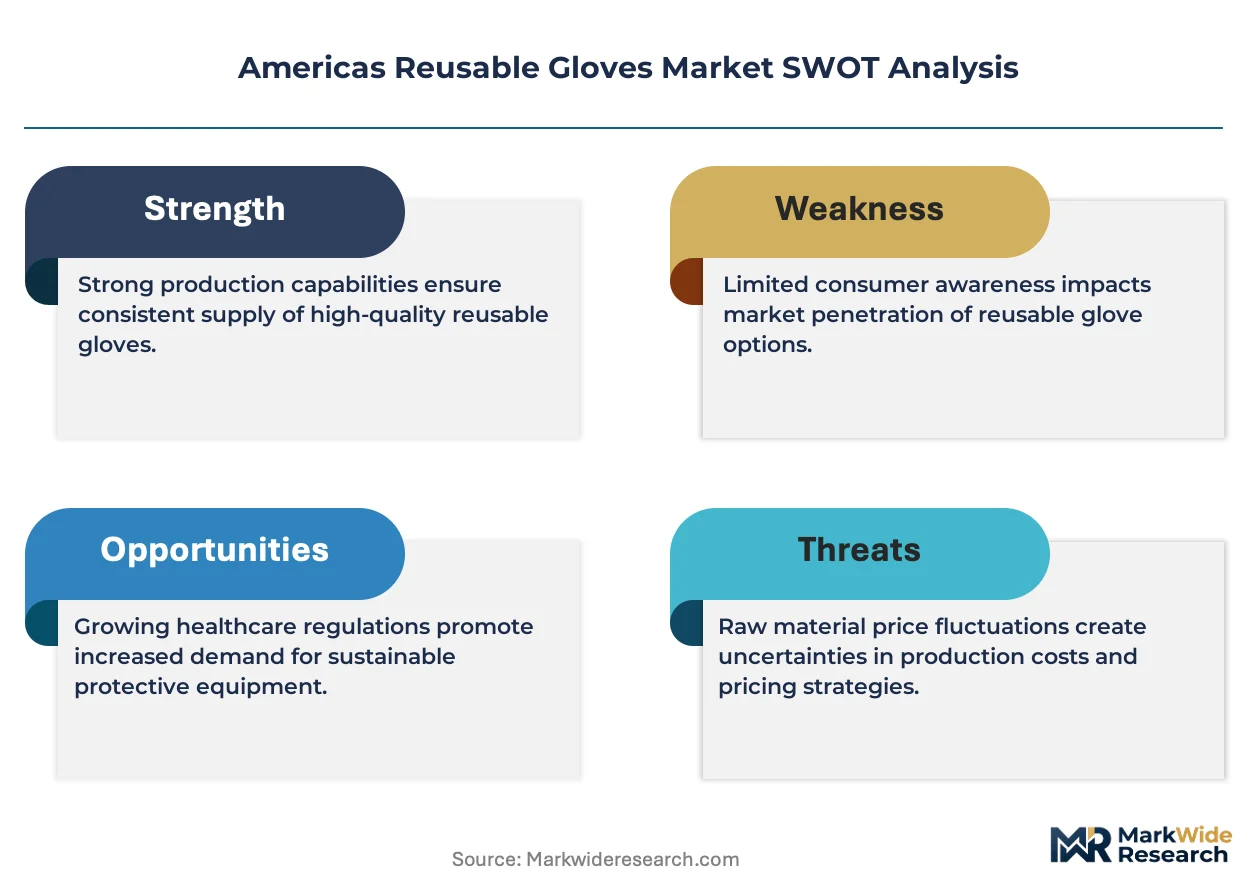
- Acrylonitrile price volatility:Nitrile glove feedstock costs fluctuate with petrochemical derivatives, squeezing margin pools for non-integrated compounders.
- Single-region supply concentration:Southeast Asian nitrile butadiene rubber production creates geographic vulnerability for Americas-based converters.
- Decontamination durability limits:Current 15-mil maximum thickness ratings cap reuse cycles before barrier integrity degradation forces retirement.
Strategic Opportunities
- Brazilian industrial expansion:Underpenetrated chemical processing and agrochemical handling sectors present volume expansion potential beyond North American saturation.
- State extended producer responsibility frameworks:Emerging U.S. state-level collection mandates will favor early movers establishing reverse logistics infrastructure.
- Neoprene-nitrile hybrid formulations:Converging chemical resistance and tactile sensitivity properties open laboratory and precision manufacturing applications.
Industry Challenges
- ISO 374 chemical permeation certification:Multi-month testing timelines delay new product commercialization and freeze R&D capital allocation.
- Legacy inventory systems:Hospital network procurement platforms require manual integration with automated glove tracking technologies, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Reusable Gloves Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Latex, PVC, Neoprene Application: Healthcare, Food Service, Industrial, Household End User: Clinics, Restaurants, Manufacturing, Cleaning Services Size: Small, Medium, Large, Extra Large |
| Companies Covered | Honeywell, 3M, Ansell, Showa Group, MCR Safety, Lakeland Industries, Kimberly-Clark, DuPont, Cardinal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Reusable Gloves Market Evolving Landscape
Material science advances and regulatory compression are forcing simultaneous innovation across formulation chemistry, sterilization compatibility, and supply chain traceability. Competitive differentiation increasingly depends on technical documentation depth rather than commodity volume.
Modular glove systems with interchangeable liner and outer shell configurations are modularizing procurement economics for multi-hazard environments. Chemical processing plants in Texas and Louisiana are piloting these systems to reduce SKU complexity while maintaining OSHA compliance across shifting task profiles. The technology is modularizing supplier relationships by decoupling shell replacement from full glove retirement.
EPA chemical resistance testing protocol revisions are expanding permeation testing requirements for agricultural chemical handling applications. Industrial safety managers must now specify gloves against broader chemical suites, forcing compounders to reformulate or withdraw SKUs. Agricultural cooperatives across the U.S. Midwest are consolidating procurement around suppliers with pre-validated expanded chemical portfolios.
Direct distributor relationships are displacing traditional medical supply intermediaries in healthcare glove procurement. Hospital networks in the U.S. Southeast are negotiating volume commitments with compounders for guaranteed nitrile allocation and lot traceability. This channel compression is most visible in outpatient surgical centers where infection control documentation requirements favor transparent supply chain relationships.
Americas Reusable Gloves Market Segmentation
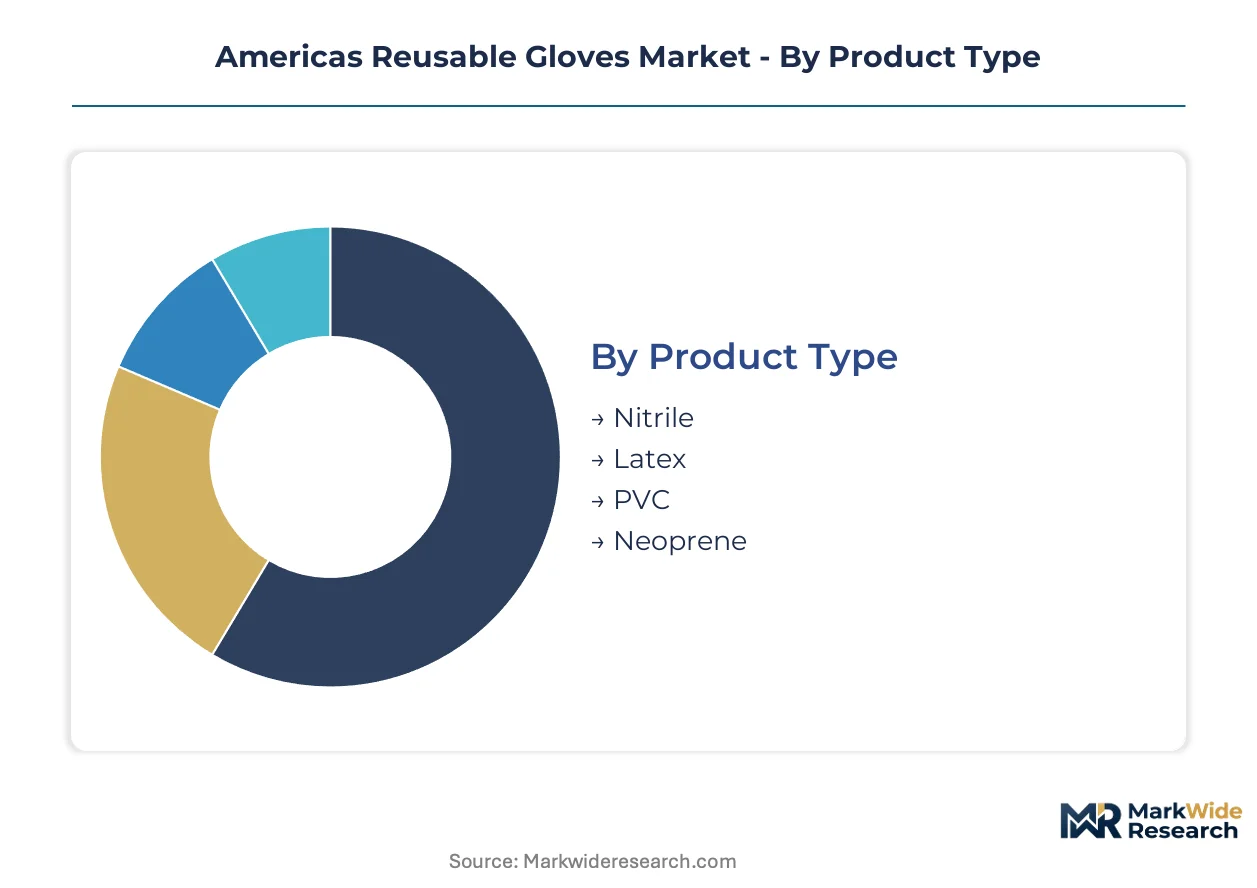
Reusable gloves in the Americas exhibit distinct performance and compliance profiles across material chemistry, use environment, and user scale. Procurement patterns diverge sharply between healthcare systems prioritizing FDA-compliant barrier documentation and industrial buyers optimizing cost-per-cycle economics.
Product Type:
Capital intensity concentrates in nitrile compounding infrastructure, where acrylonitrile-butadiene rubber processing requires dedicated polymerization and dipping lines. Latex and PVC operations leverage more standardized equipment, while neoprene formulations demand specialized chloroprene handling systems.
- Nitrile:Synthetic rubber copolymer delivering puncture resistance ratings 3-5x superior to latex alternatives. Demand concentrates in U.S. outpatient surgical centers and clinical laboratories where FDA Class I device compliance and allergy liability mitigation drive specification. OSHA 29 CFR 1910.138 hand hazard assessments in chemical processing plants are expanding nitrile procurement beyond healthcare into industrial channels.
- Latex:Natural rubber formulations offering superior tactile sensitivity and elasticity for precision handling tasks. Procurement contracts in food service and household segments sustain volume despite healthcare displacement, particularly in Latin American markets where cost sensitivity outweighs allergy protocol rigor.
- PVC:Polyvinyl chloride compounds provide chemical resistance at lower unit economics for bulk industrial applications. Manufacturing plants in the U.S. Great Lakes corridor specify PVC for routine material handling where puncture risk remains minimal.
- Neoprene:Chloroprene-based synthetic rubber engineered for broad chemical resistance and thermal stability. Chemical processing facilities in Texas and Louisiana specify neoprene for petrochemical handling where permeation resistance across aromatic and aliphatic compounds is mandatory.
Most installed capacity flows through nitrile. Expansion is steepest in neoprene as hybrid formulations penetrate laboratory environments.
Application:
Volume scale separates mature industrial procurement from emerging healthcare specifications, with food service occupying a mid-tier position characterized by standardized compliance requirements and price-sensitive replenishment cycles.
- Healthcare:Infection control protocols in U.S. hospital networks and outpatient surgical centers mandate reusable gloves capable of withstanding autoclave or gamma sterilization cycles. FDA quality system regulation and Joint Commission accreditation standards drive documentation depth and lot traceability requirements that favor direct manufacturer relationships over distributor intermediaries.
- Industrial:Chemical handling, automotive assembly, and petrochemical operations constitute the most mature volume segment with established replacement rhythms tied to manufacturing output cycles. EPA chemical resistance testing protocols under FIFRA determine material selection for agricultural chemical handling in the U.S. Midwest.
- Food Service:USDA and FDA food contact substance regulations govern material composition for restaurant and food processing applications. Cleaning and sanitation protocols in quick-service restaurant chains drive predictable replacement demand with lower specification complexity than healthcare.
- Household:Consumer retail channels supply cleaning and maintenance applications with minimal regulatory overlay. Price elasticity in this segment constrains premium material penetration.
Industrial channels absorb the highest absolute volume. Healthcare applications are climbing the fastest as infection prevention budgets widen post-pandemic.
End User:
Customer type determines procurement sophistication, with clinics and manufacturing facilities operating formal specification processes while restaurants and cleaning services rely on distributor recommendations and price-tier selection.
- Clinics:Outpatient surgical centers and diagnostic laboratories in the U.S. Southeast and Southwest are consolidating procurement around compounders offering guaranteed nitrile allocation and lot-level traceability. OSHA bloodborne pathogen standards and CDC hand hygiene protocols drive specification rigor.
- Restaurants:Quick-service and casual dining chains specify reusable gloves for back-of-house sanitation and limited food contact tasks. Procurement typically flows through broadline foodservice distributors with limited technical documentation requirements.
- Manufacturing:Automotive assembly plants in Michigan and Ohio, petrochemical facilities on the Gulf Coast, and agricultural chemical handlers across the Midwest sustain bulk contract volumes with predictable replacement schedules tied to production shifts.
- Cleaning Services:Commercial and institutional janitorial contractors specify reusable gloves for chemical exposure protection during sanitation operations. Price sensitivity in this segment favors PVC and latex alternatives over premium nitrile formulations.
Manufacturing end users command the largest contract values. Clinics are gaining share fastest as ambulatory surgical center construction accelerates.
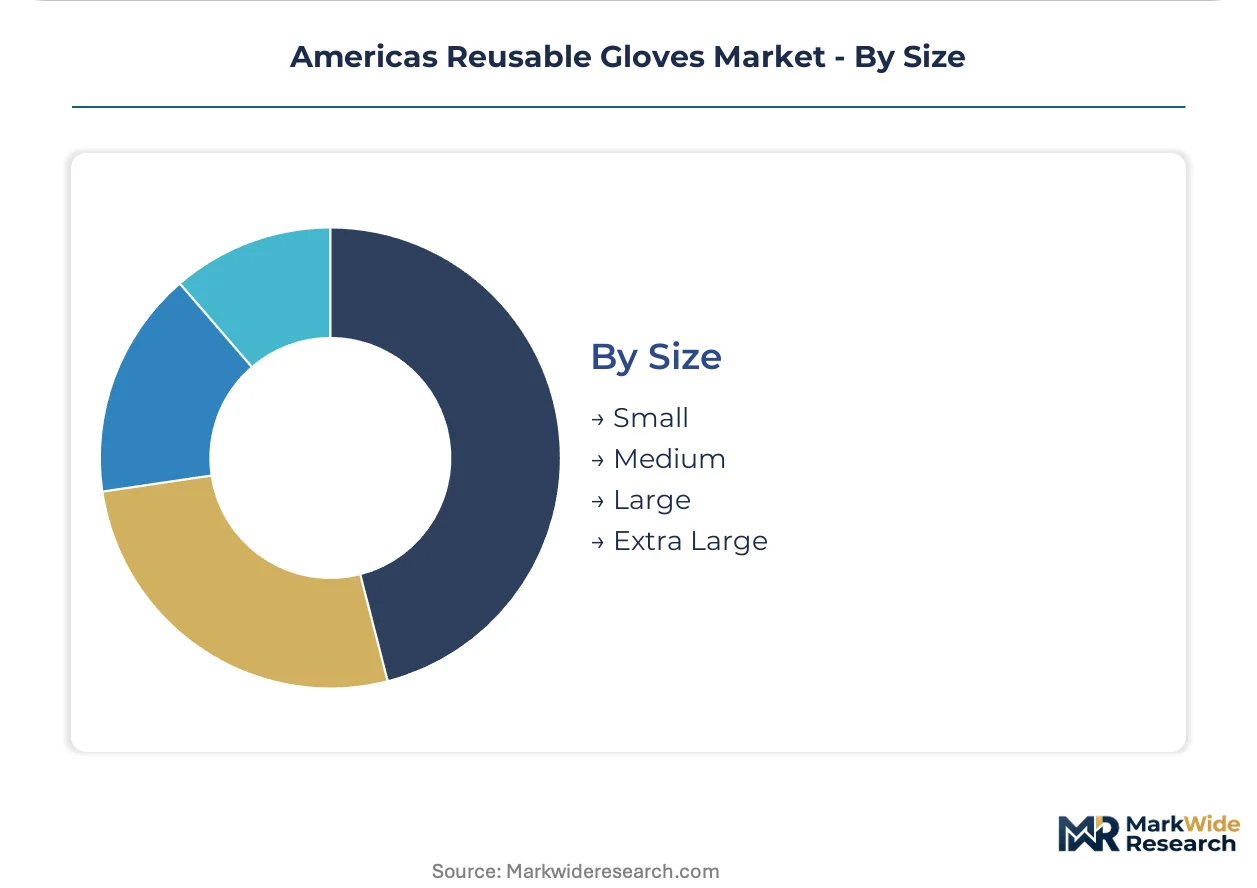
Size:
SKU proliferation across dimensional ranges reflects ergonomic requirements and regulatory accommodation mandates rather than meaningful price differentiation.
- Small:Sized for hand circumferences below 7 inches, serving healthcare and laboratory workforces with higher female participation rates. OSHA accommodation requirements in U.S. facilities mandate small-size availability as a condition of compliant hazard assessment.
- Medium:The most commonly specified dimension across all end-use segments, representing baseline procurement volumes for distributor stocking programs.
- Large:Industrial applications with male-skewed workforces concentrate demand in this category, particularly in manufacturing and chemical processing environments.
- Extra Large:Limited volume segment addressing outlier ergonomic requirements, with availability constraints occasionally forcing industrial buyers into custom order cycles.
Medium sizes dominate inventory investment. Extra Large shows the steepest relative expansion as obesity demographics shift workforce anthropometrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors Americas reusable gloves demand through concentrated automotive and chemical processing activity. Brazil's industrial expansion and Mexico's maquiladora growth are redrawing procurement gravity southward. Regulatory divergence between OSHA-driven North America and evolving Latin American workplace standards shapes regional competitive positioning.
United States
OSHA 29 CFR 1910.138 mandates hand hazard assessments across Michigan and Ohio automotive plants. FDA Class I device regulations govern medical-grade glove procurement for hospital networks. The Gulf Coast petrochemical cluster in Texas and Louisiana sustains neoprene specification for aromatic chemical handling.
Brazil
Agrochemical handling and chemical processing sectors drive underpenetrated industrial demand beyond North American saturation. ANVISA medical device regulations are tightening barrier documentation requirements for healthcare procurement. São Paulo state manufacturing corridors anchor volume expansion for both industrial safety and clinical applications.
Canada
Health Canada and PMRA chemical resistance protocols determine agricultural chemical handling specifications across Prairie Provinces. Alberta oil sands operations sustain heavy-duty industrial glove replacement cycles. Ontario automotive assembly in Windsor and Oshawa maintains cross-border supply chain integration with U.S. Great Lakes facilities.
Mexico
Maquiladora manufacturing in Nuevo León and Baja California generates OSHA-aligned procurement for export-oriented automotive and electronics assembly. Mexican labor law amendments are accelerating formal workplace safety compliance in previously informal sectors. Mexico City metropolitan area concentrates healthcare demand for infection control equipment.
Colombia
Petrochemical processing in Barrancabermeja and agricultural chemical distribution across the Magdalena River valley sustain industrial safety procurement. The national pharmaceutical regulator is aligning medical device standards with U.S. FDA frameworks to facilitate import substitution. Bogotá clinical laboratory networks are consolidating nitrile specification for diagnostic applications.
Americas Reusable Gloves Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and channel access dimensions. Market structure concentrates around three to five integrated compounders controlling nitrile supply chains, with mid-tier converters filling specialty niches. Strategic archetypes include scale-driven industrial suppliers, healthcare-focused compliance specialists, and hybrid formulation innovators. Competitive moves center on backward integration into acrylonitrile-butadiene rubber compounding and direct distributor relationship compression.
Among North American industrial safety suppliers, Honeywell and 3M occupy positions as diversified conglomerates with cross-category PPE portfolios. Ansell represents the integrated compounder archetype with captive nitrile production infrastructure. These anchors demonstrate how manufacturing scale and regulatory documentation depth separate tier-one positioning from commodity conversion competition.
| Leading Market Players |
|---|
| Honeywell |
| 3M |
| Ansell |
| Showa Group |
| MCR Safety |
| Lakeland Industries |
| Kimberly-Clark |
| DuPont |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Nitrile-latex-PVC grade divergence separates FDA-validated medical tiers from commodity industrial specifications, with that bifurcation manifesting in both contract pricing structures and raw material sourcing footprints across the Americas. Premium nitrile compounders command captive acrylonitrile-butadiene rubber supply chains while PVC converters tap spot polymer markets, creating divergent margin stability profiles.
Pricing Analysis
Acrylonitrile-butadiene rubber feedstock pass-through dominates nitrile glove contract structures, with compounders indexing quarterly adjustments to petrochemical derivative benchmarks. Three-tier pricing structure across premium, standard, and economy levels tracks FDA Class I certification status and ISO 374 chemical permeation validation tiers. Cost compression in standard-grade nitrile is intensifying because Southeast Asian NBR supply concentration limits Americas-based converters' negotiating leverage. Food service distributors exhibit highest price sensitivity, while hospital networks accepting long-term volume commitments for lot traceability show lowest elasticity.
Supply Chain Analysis
Domestic-content mandates in U.S. federal procurement contracts are reshaping sourcing patterns, with Buy America provisions requiring 55% domestic component thresholds for hospital system eligibility. Manufacturing concentrates in Malaysia, Thailand, and Indonesia for nitrile butadiene rubber polymerization, with Americas-based converters operating dipping and finishing lines. Supply chains draw from acrylonitrile monomer, butadiene, and chloroprene feedstocks. Single-source vulnerability in Southeast Asian NBR production creates geographic concentration risk. Distribution runs through direct manufacturer relationships with hospital networks and industrial safety distributors serving manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in nitrile formulation premiumization and decontamination cycle extension, with acrylonitrile cost stabilization enabling compounders to capture value from FDA-validated barrier documentation.
For Market Incumbents: Lock in backward integration into acrylonitrile-butadiene rubber compounding or secure long-term offtake agreements with Malaysian and Thai polymer suppliers to defend against feedstock volatility. Expand ISO 374 certification portfolios to preempt regulatory compression in chemical handling applications. Channel control through direct hospital network relationships represents the critical lever for margin defense against distributor disintermediation. For New Entrants and Emerging Players: Begin with Brazilian agrochemical handling and outpatient surgical center construction in the U.S. Southeast as the most penetrable white-space targets. Neoprene-nitrile hybrid formulations for laboratory environments offer technical differentiation without requiring captive nitrile infrastructure. A go-to-market angle anchored to state extended producer responsibility compliance services can accelerate trust-building with sustainability-conscious procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack captive polymer supply and face margin compression from both feedstock volatility and certification cost inflation. Acquisition targets with FDA quality system regulation infrastructure and existing direct hospital relationships offer strongest long-term viability through the projection horizon. The signal to watch is ANVISA alignment progress in Brazil, which would trigger import substitution capital deployment by global compounders seeking South American manufacturing footholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into NBR Compounding | Captive acrylonitrile supply insulates margins from Southeast Asian petrochemical volatility. |
| ISO 374 Chemical Permeation Certification Expansion | Pre-validated portfolios capture agricultural cooperative procurement consolidation in the U.S. Midwest. |
| Direct Hospital Network Distribution | Lot traceability capabilities satisfy Joint Commission accreditation and displace medical supply intermediaries. |
| Neoprene-Nitrile Hybrid Formulation Development | Converging chemical resistance and tactile sensitivity opens precision manufacturing and laboratory segments. |
| Brazilian Manufacturing Footprint Establishment | ANVISA alignment enables import substitution positioning in underpenetrated agrochemical handling sectors. |
Research Methodology
Multiple input streams — primary interviews with industrial safety managers, hospital procurement directors, and glove compounder technical leads; secondary validation through OSHA regulatory filings, FDA 510(k) databases, and ACC chemical trade data; plus customs import records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification requirements across automotive assembly plants in Michigan and Ohio, petrochemical facilities on the Gulf Coast, and outpatient surgical centers in the U.S. Southeast. Secondary sources included EPA chemical resistance testing protocols, hospital GPO contract databases, and Brazilian ANVISA medical device registration records.
Historical volume trajectories were cross-referenced against panel input from procurement executives to model demand across the projection horizon. Segmentation dimensions included material chemistry tier, application environment, end-user scale, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, ambulatory surgical center construction pipelines, and manufacturing output correlations. Industry-specific forecast inputs incorporated OSHA 29 CFR 1910.138 enforcement intensity indices and FDA guidance update timelines.
Caveats apply where acrylonitrile price volatility, Southeast Asian supply disruptions, or state-level extended producer responsibility framework acceleration could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement continuity and hospital capital expenditure patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market