
 Ship Life-Saving Equipment Market | 2026-2036
Ship Life-Saving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Life-Saving Equipment Market Insights
Aftermarket service revenue is narrowing toward inspection, recertification, and fleet refurbishment contracts as original equipment margins compress. VIKING Life-Saving Equipment A/S dominates the European service network through owned recertification centers. Survitec Group Limited anchors its position with deep stockholding of SOLAS-mandated replacement intervals across multiple flag states.
Ship life-saving equipment encompasses engineered survival systems designed to protect personnel during vessel abandonment, including inflatable life rafts rated for specific capacity and temperature zones, inherently buoyant or inflatable life jackets meeting minimum buoyancy standards, insulated immersion suits preventing hypothermia in cold water, and throwable or mounted lifebuoys with attached retrieval lines. The primary commercial purpose centers on regulatory compliance with international maritime safety conventions while reducing liability exposure for vessel operators across commercial, passenger, and offshore sectors. Life rafts command the largest installed base due to mandatory carriage requirements on all SOLAS-class vessels, though immersion suits generate premium pricing in polar and North Atlantic routes where thermal protection regulations are most stringent. Life jackets represent the highest-volume replacement category as foam degradation and automatic inflation mechanism expiration drive predictable refresh cycles across cargo shipping fleets.
The International Maritime Organization's SOLAS convention establishes minimum equipment carriage and performance standards, while the US Coast Guard enforces additional type-approval requirements for vessels calling at United States ports. The European Union's Marine Equipment Directive harmonizes conformity assessment across member states, creating a single market access pathway for certified manufacturers. Stakeholders must monitor pending amendments to the Polar Code and evolving flag-state interpretations of remote inspection technologies that could reshape service delivery models and compliance documentation requirements.
Market Dynamics
Offshore platform operators in the North Sea cluster are accelerating replacement cycles for legacy survival fleets as SOLAS amendments tighten thermal performance mandates for cold-water operations.
Growth Catalysts
- Polar Code Revisions:The International Maritime Organization's updated polar code mandates enhanced immersion suit specifications for vessels operating in Arctic and Antarctic waters, forcing fleet-wide equipment upgrades across ice-class shipping.
- Offshore Energy Expansion:Norway's North Sea oil and gas sector drives concentrated demand for self-righting life rafts and advanced thermal protection systems as platform operators face stricter abandonment drills.
- Self-Inflating Mechanisms:Hydrostatic release unit improvements in automatic life jacket inflation systems reduce false-trigger rates and extend service intervals, lowering total ownership costs for cargo fleet managers.
Market Restraints
- Hypalon Coating Volatility:Life raft fabric costs fluctuate with chlorosulfonated polyethylene resin supply tightness, compressing margins for manufacturers dependent on Asian chemical feedstock.
- Recertification Concentration:European service networks cluster around VIKING-owned facilities in Denmark and Norway, creating bottleneck risks for fleet operators requiring rapid turnaround on mandatory inspections.
- Manual Inflation Reliability:Oral tube valve degradation in legacy life raft designs limits service life extension options, forcing premature replacement despite intact buoyancy chambers.
Strategic Opportunities
- Brazilian Offshore Growth:Pre-salt oil development off Brazil's southeastern coast creates demand for tropical-grade life rafts with enhanced UV resistance and shorter inspection cycles.
- Remote Inspection Technologies:Video-based life raft cylinder examination protocols under consideration by flag states in Singapore and Panama could reduce vessel downtime and shift service revenue toward software-enabled compliance documentation.
- Smart Buoyancy Integration:Convergence of GPS beacons with inflatable life jacket inflation triggers enables real-time crew location tracking during mass abandonment scenarios.
Industry Challenges
- Marine Surveyor Scarcity:Qualified inspectors capable of certifying advanced immersion suits to SOLAS thermal performance standards remain concentrated in Northern European maritime academies.
- Multi-Flag Certification Complexity:Vessel operators serving both US Coast Guard and EU Marine Equipment Directive jurisdictions face divergent type-approval documentation requirements for identical life-saving equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Life-Saving Equipment Market |
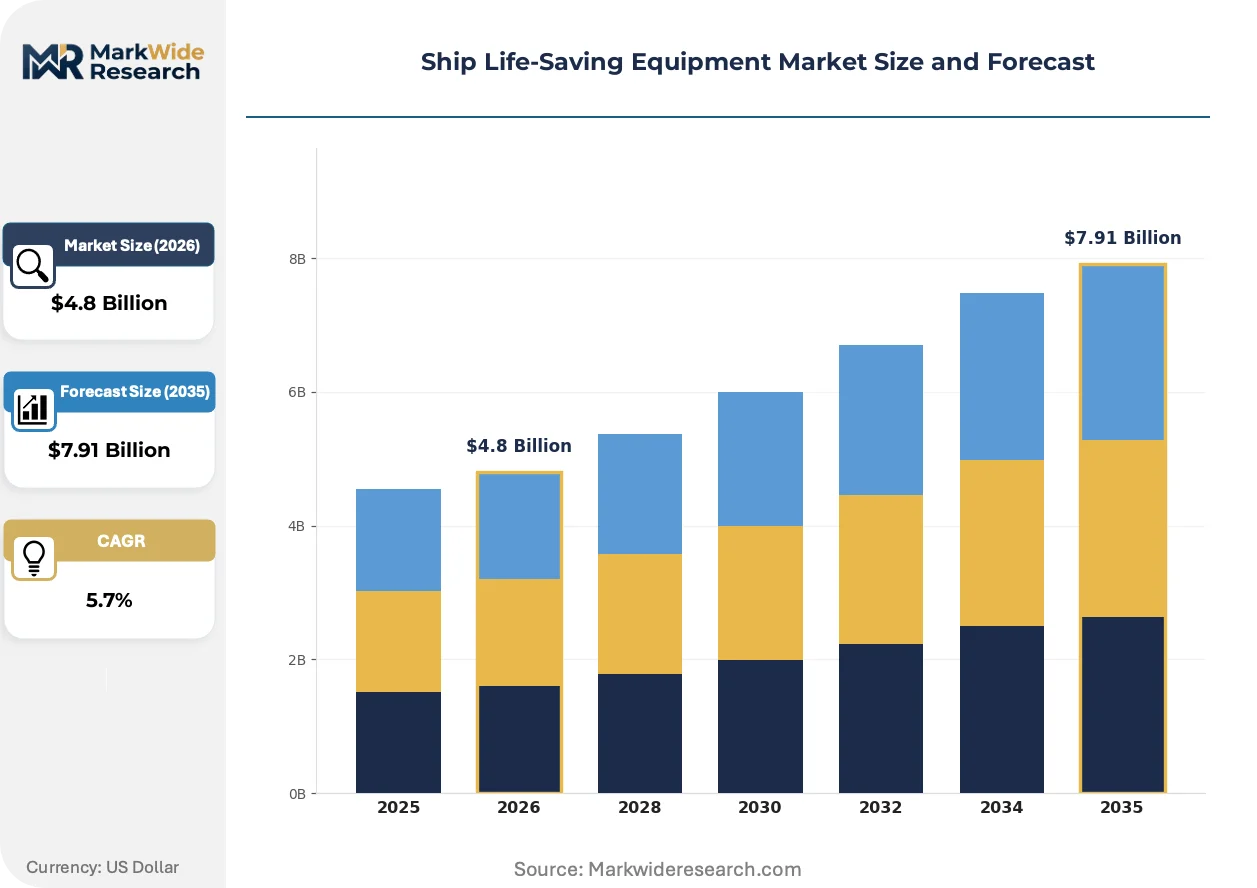
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Rafts, Life Jackets, Immersion Suits, Lifebuoys End User: Cruise Lines, Cargo Shipping, Fishing Vessels, Offshore Platforms Certification: ISO, SOLAS, USCG, EC Medical Device Regulations Deployment: Onboard, Coastal, Offshore, Emergency Response |
| Companies Covered | VIKING Life-Saving Equipment A/S, Survitec Group Limited, Lifesaving Systems Corporation, Palfinger Marine, New Marine Lifesaving Equipment, Norsafe, DSB Engineering, Zodiac Milpro, Willard Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Life-Saving Equipment Market Trends and Innovations
Digital compliance documentation and connected safety systems are restructuring how ship operators manage life-saving equipment certification cycles and crew readiness protocols.
Embedded sensor networks in inflatable life rafts are virtualizing traditional inspection workflows. Norwegian offshore operators now deploy pressure-monitoring transducers that transmit cylinder integrity data to shore-based maintenance systems. This virtualization compresses the interval between physical recertification visits while flag state authorities in Oslo and Copenhagen pilot remote audit acceptance frameworks.
The European Union's Marine Equipment Directive harmonization process is tightening conformity assessment procedures for life jacket automatic inflation mechanisms. Manufacturers must now submit extended salt-spray corrosion testing data to notified bodies in Germany and France. Small-scale suppliers in Mediterranean shipbuilding clusters face capital barriers to upgraded testing facilities, consolidating procurement options for major fleet operators.
Charter party agreements increasingly specify brand-level life-saving equipment compliance as a fixture in vessel hire rates. Greek and Singaporean ship managers now bundle SOLAS-mandated replacement intervals into multi-year operating leases. This unbundling of equipment ownership from vessel operation concentrates purchasing authority with specialized marine service integrators rather than traditional shipowners.
Ship Life-Saving Equipment Market Segmentation
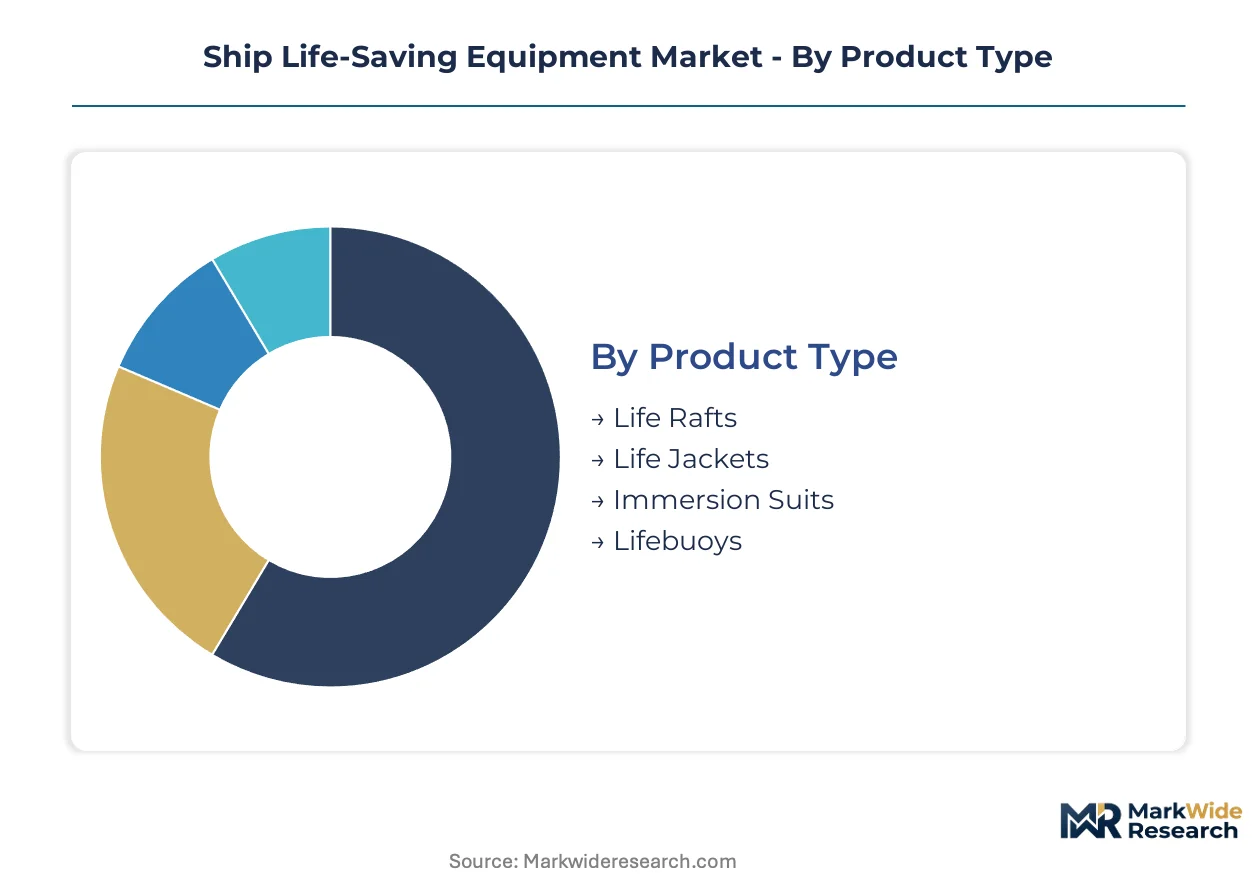
Ship life-saving equipment segmentation reflects divergent regulatory intensity across vessel types and operating zones. Procurement patterns split between high-frequency replacement categories and capital-intensive survival systems with extended service intervals.
Product Type:
Mature inflatable platforms dominate installed base volumes while emerging thermal protection technologies command premium positioning in polar routes.
- Life Rafts:Inflatable survival platforms constructed from coated fabric with hydrostatic release mechanisms and self-righting capabilities. SOLAS mandates drive replacement cycles in Norway's offshore cluster as operators abandon legacy fleets for cold-water certified models.
- Life Jackets:Foam-filled or inflatable personal flotation devices with automatic inflation triggers and retro-reflective tape. Cargo shipping fleets in Singapore and Rotterdam generate highest-volume demand as foam degradation forces predictable refresh intervals.
- Immersion Suits:Neoprene or membrane-based thermal protection systems preventing hypothermia in sub-zero water temperatures.
- Lifebuoys:Ring-shaped throwable flotation devices with attached retrieval lines and mounting brackets.
Life rafts retain volume leadership; immersion suits hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive offshore installations from price-sensitive coastal fishing operations.
- Cruise Lines:High-capacity evacuation systems with passenger-facing aesthetics and multilingual deployment instructions. Mediterranean and Caribbean operators prioritize rapid-deployment slides and marine evacuation chutes over traditional davit-launched rafts.
- Cargo Shipping:Standardized SOLAS-minimum configurations with emphasis on crew-only capacity and minimal maintenance overhead. Greek and German container fleets drive consolidation toward single-supplier service contracts covering multiple vessel classes.
- Fishing Vessels:Compact survival craft with manual inflation options and reduced inspection frequency requirements.
- Offshore Platforms:Self-righting life rafts with enhanced thermal protection and helicopter pickup compatibility.
Cargo shipping dominates unit volumes; offshore platforms generate the highest per-vessel expenditure.
Certification:
Geographic scope of vessel operations determines which approval frameworks govern procurement decisions.
- ISO:International standards harmonizing baseline performance criteria across flag states. ISO 9650 liferaft specifications gain traction in Asian shipbuilding yards seeking multi-jurisdiction acceptance without redundant testing.
- SOLAS:International Maritime Organization convention establishing minimum carriage requirements and equipment performance standards. Amendments to thermal protection mandates accelerate fleet-wide replacement in North Atlantic and polar routes.
- USCG:United States Coast Guard type-approval requirements for vessels calling at American ports.
- EC Medical Device Regulations:European Union conformity assessment for first-aid and medical equipment integrated into survival systems.
SOLAS retains universal applicability; ISO certifications are expanding most quickly in emerging shipbuilding centers.
Deployment:
Application context shapes equipment specification from routine standby to emergency-only activation scenarios.
- Onboard:Permanently installed survival systems with monthly inspection protocols and integrated alarm triggers. Norwegian offshore platforms deploy pressure-monitoring transducers transmitting cylinder integrity data to shore-based maintenance systems.
- Coastal:Short-range rescue craft with reduced capacity and simplified deployment mechanisms. Fishing cooperatives in Spain and Portugal favor manually launched options over automatic hydrostatic systems.
- Offshore:Extended-duration survival platforms with desalination kits, thermal protection, and helicopter-compatible canopies.
- Emergency Response:Rapid-deployment systems for search-and-rescue organizations and salvage operators.
Onboard installations anchor replacement revenue; offshore deployments show the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian offshore operators deploy immersion suits rated for sub-zero North Atlantic conditions, while Singaporean cargo fleets prioritize high-volume life jacket replacement cycles. Brazilian pre-salt development drives tropical-grade survival craft procurement with enhanced UV resistance.
Norway
North Sea oil and gas platforms mandate self-righting life rafts with helicopter-compatible canopies under Petroleum Safety Authority Norway regulations. Oslo-based operators now integrate pressure-monitoring transducers transmitting cylinder integrity data to shore-based maintenance systems, compressing physical inspection intervals.
United States
Gulf of Mexico offshore installations drive demand for extended-duration survival platforms with desalination kits under US Coast Guard type-approval requirements. Houston-headquartered drilling contractors face divergent documentation burdens when vessels rotate between USCG and EU Marine Equipment Directive jurisdictions.
Singapore
Container shipping fleets generate highest-volume demand for foam-filled life jackets as tropical humidity accelerates foam degradation cycles. The Maritime and Port Authority of Singapore pilots video-based life raft cylinder examination protocols that could reduce vessel downtime and reshape service delivery models.
Brazil
Pre-salt oil development off the southeastern coast creates concentrated demand for tropical-grade life rafts with shorter inspection cycles. Rio de Janeiro-based platform operators procure enhanced UV-resistant fabrics as ANVISA-equivalent marine safety standards tighten abandonment drill requirements.
Germany
Notified bodies in Hamburg and Bremen enforce extended salt-spray corrosion testing for automatic life jacket inflation mechanisms under EU Marine Equipment Directive harmonization. Container fleet operators in the Port of Rotterdam corridor consolidate procurement toward single-supplier service contracts spanning multiple vessel classes.
Ship Life-Saving Equipment Market Competitive Landscape
Capability concentration sits with specialized service integrators; scale advantage sits with diversified marine safety conglomerates. The vendor base splits between vertically integrated manufacturers controlling recertification networks and asset-light distributors dependent on third-party inspection capacity. Two strategic archetypes dominate: Nordic-origin specialists leveraging proximity to North Sea offshore demand, and British-Danish conglomerates anchoring positions through deep stockholding across multiple flag states. Competitive moves center on owned service network expansion and charter party agreement bundling that unbundles equipment ownership from vessel operation.
Within the Nordic specialist tier, VIKING Life-Saving Equipment A/S and Norsafe exemplify proximity-based competitive positioning. Survitec Group Limited occupies a position among British-domiciled conglomerates with diversified flag-state coverage. These three entities represent contrasting approaches to aftermarket capture—owned recertification infrastructure versus distributed stockholding models.
| Leading Market Players |
|---|
| VIKING Life-Saving Equipment A/S |
| Survitec Group Limited |
| Lifesaving Systems Corporation |
| Palfinger Marine |
| New Marine Lifesaving Equipment |
| Norsafe |
| DSB Engineering |
| Zodiac Milpro |
| Willard Marine |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Singapore container corridor channels life-saving equipment freight costs through concentrated North Sea manufacturing hubs, compressing margins for distributors while amplifying pricing power among vertically integrated producers commanding captive recertification networks.
Pricing Analysis
Long-term offtake contracts dominate procurement between major fleet operators and Nordic manufacturers, locking in volume commitments across multi-year replacement cycles. Three-tier pricing structure across SOLAS-certified premium, ISO-baseline standard, and coastal-fishing economy levels reflects divergent certification burdens and thermal performance specifications. Pricing pressure stems from chlorosulfonated polyethylene resin volatility in Asian chemical feedstock markets, squeezing fabric-intensive life raft production. Cargo shipping fleets exhibit highest price sensitivity due to standardized SOLAS-minimum configurations, while offshore platform operators absorb premium positioning for helicopter-compatible self-righting systems.
Supply Chain Analysis
Chlorosulfonated polyethylene resin and neoprene membrane feedstock production centers on China, Japan, and Germany, with coating compound formulation concentrated in Danish and Norwegian specialty chemical facilities. Raw material procurement draws from Asian petrochemical complexes for base polymers, European textile weavers for high-tenacity fabrics, and Baltic states for inflation mechanism components. Single-source vulnerability runs through hydrostatic release unit suppliers serving automatic life jacket triggers, creating bottleneck exposure for manufacturers without dual-qualified vendors. Distribution runs through owned recertification centers in Denmark and Norway, supplemented by third-party marine service integrators in Singapore and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital compliance documentation and remote inspection technologies threaten traditional recertification revenue streams, forcing incumbents to defend service-anchored positions against asset-light software entrants.
For Market Incumbents: Pre-empt disintermediation by embedding sensor networks into inflatable life raft cylinders before flag states normalize video-based examination protocols. Acquire independent marine surveyor training capacity in Brazil and Southeast Asia to offset Northern European inspector scarcity. Lock in charter party agreement bundling that ties equipment replacement intervals to multi-year vessel operating leases.
For New Entrants and Emerging Players: Brazilian pre-salt platform operators lacking established Nordic supplier relationships represent the most penetrable entry point for tropical-grade life rafts with enhanced UV resistance. Remote inspection software development for Singapore-flag and Panama-flag vessel registries offers lower capital barriers than manufacturing scale-up. Partner with regional marine service integrators to bypass VIKING-owned recertification network density in Europe.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified marine safety conglomerates with deep stockholding across multiple flag states over pure-play hardware manufacturers. Long-term viability hinges on regulatory arbitrage capture as SOLAS amendments and Polar Code revisions force fleet-wide replacement waves. Watch for ANVISA-equivalent standard harmonization in Brazil as the signal indicating acceleration in tropical-grade procurement authority consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Owned Recertification Network Expansion | VIKING's Denmark and Norway facilities create captive service revenue streams independent of equipment sales cycles. |
| Remote Inspection Technology Development | Singapore's Maritime and Port Authority pilots reduce vessel downtime and shift compliance documentation toward software-enabled models. |
| Charter Party Agreement Bundling | Greek and Singaporean ship managers concentrate purchasing authority with specialized marine service integrators rather than traditional shipowners. |
| Sensor-Enabled Life Raft Integration | Norwegian offshore operators deploy pressure-monitoring transducers transmitting cylinder integrity data to shore-based maintenance systems. |
| Multi-Flag Certification Investment | Survitec's deep stockholding across USCG and EU Marine Equipment Directive jurisdictions reduces documentation burden for rotating vessel fleets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers at Greek and Singaporean container lines, marine surveyors certifying immersion suits to SOLAS thermal standards, procurement leads at Norwegian offshore platform operators, and technical directors at Danish and British life-saving equipment manufacturers. Secondary validation drew from International Maritime Organization convention amendment filings, US Coast Guard type-approval databases, EU Marine Equipment Directive notified body assessments, and customs trade data tracking chlorosulfonated polyethylene resin flows. Bottom-up equipment replacement cycle modeling triangulated against top-down fleet composition analysis across commercial shipping registers.
Calibration against historical replacement intervals in Norway's North Sea cluster and Singapore's container shipping corridor anchored volume projections across the analysis window. Segmentation dimensions modeled include product type hierarchy, end-user cost tier stratification, certification jurisdiction scope, and deployment application context. CAGRs derived from regression analysis of regulatory mandate timing and fleet age distribution patterns, with specific inputs from Polar Code revision implementation schedules and ANVISA-equivalent standard development in Brazil.
Practitioners should monitor flag state adoption of remote inspection technologies and chlorosulfonated polyethylene resin supply tightness for early signals requiring forecast revision. Cross-checking against Lloyd's Register vessel equipment renewal databases and Petroleum Safety Authority Norway abandonment drill compliance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market