
 Electrical Safety Products Market | 2026-2036
Electrical Safety Products Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Safety Products Market Analysis
The widening performance gap between IEC-certified arc flash systems and basic commodity PPE is repositioning procurement strategies across heavy industries. Schneider Electric leverages integrated digital-twin platforms to anchor premium positioning in smart monitoring deployments. ABB Ltd competes through captive supply of medium-voltage breakers, while Eaton Corporation dominates North American utility channels with specialized ground fault protection systems.
Electrical safety products encompass engineered devices and personal protective equipment designed to prevent electrocution, arc flash injuries, and equipment damage in energized environments, typically rated for specific voltage classes and incorporating materials such as dielectric rubber, thermoset composites, or microprocessor-based trip units. Circuit breakers and arc flash technology command the deepest margin pools due to embedded software complexity and replacement cycle predictability, while smart monitoring represents the fastest-expanding technology segment as facilities retrofit legacy distribution networks with IoT-enabled predictive maintenance capabilities.
OSHA's electrical safety standards, the EU's MDR for PPE certification, and India's BIS voltage rating mandates collectively tighten compliance thresholds and reshape supplier qualification requirements across multiple geographies. The EPA's emerging rules on SF6 emissions from switchgear are additionally redirecting R&D investment toward vacuum interruption and solid insulation alternatives. Stakeholders must weigh certification portability against regional manufacturing incentives when structuring supply footprints for the next phase of electrification infrastructure buildout.
Market Dynamics
Industrial electrification mandates across heavy manufacturing are compressing replacement cycles for legacy protection equipment while forcing simultaneous compliance with divergent regional certification regimes. This dual pressure is fragmenting supplier qualification pipelines and concentrating procurement authority among buyers with multi-site standardization capabilities.
Growth Catalysts
- EU Green Deal industrial mandates:Binding electrification targets for steel and cement plants are mandating arc flash system upgrades across integrated facilities, pulling medium-voltage PPE procurement forward by several years.
- Data center cluster expansion:Northern Virginia, Frankfurt, and Singapore hyperscale builds are specifying integrated smart monitoring with every circuit breaker installation, elevating technology specifications across procurement templates.
- SF6 phase-down regulations:The EPA's emerging restrictions and the EU F-Gas Regulation are redirecting switchgear investment toward vacuum interruption and solid insulation alternatives, opening replacement demand in utility substations.
Market Restraints
- Copper and rare earth input volatility:Price swings in conductive materials and permanent magnets for smart trip units are compressing margins on medium-voltage breaker production, particularly affecting European manufacturers with limited hedging capacity.
- Dielectric rubber supply concentration:Malaysia and Thailand dominate nitrile and natural rubber compound production for insulated gloves, creating geographic single-point-of-failure exposure for PPE certification continuity.
- IEC-UL certification divergence:Non-harmonized testing protocols between European and North American standards are forcing redundant product development cycles, extending time-to-market for unified product platforms.
Strategic Opportunities
- Brazil utility privatization wave:Southeast regional distribution asset sales are concentrating capital expenditure authority among private operators with standardized safety procurement protocols, creating vendor consolidation windows.
- Predictive maintenance convergence:Integration of thermal imaging with arc flash detection algorithms is enabling subscription-based monitoring services, shifting revenue from hardware sales to recurring software contracts.
- India BIS voltage rating harmonization:Centralized certification alignment with IEC standards is reducing import friction for multinational suppliers, opening distribution channel partnerships in Maharashtra and Gujarat industrial corridors.
Industry Challenges
- Arc flash engineering talent scarcity:Qualified incident energy calculation specialists and NFPA 70E-certified trainers are in short supply relative to audit demand, delaying compliance verification timelines for multi-site industrial operators.
- Legacy breaker integration complexity:Retrofitting IoT-enabled monitoring onto 1980s-vintage air-magnetic breakers requires custom sensor mounting and communication protocol bridging, inflating deployment costs and failure rates.
- CE-MDR PPE recertification backlog:European notified body capacity constraints are extending insulated glove and face shield approval timelines, disrupting inventory planning for construction and utility seasonal hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Safety Products Market |
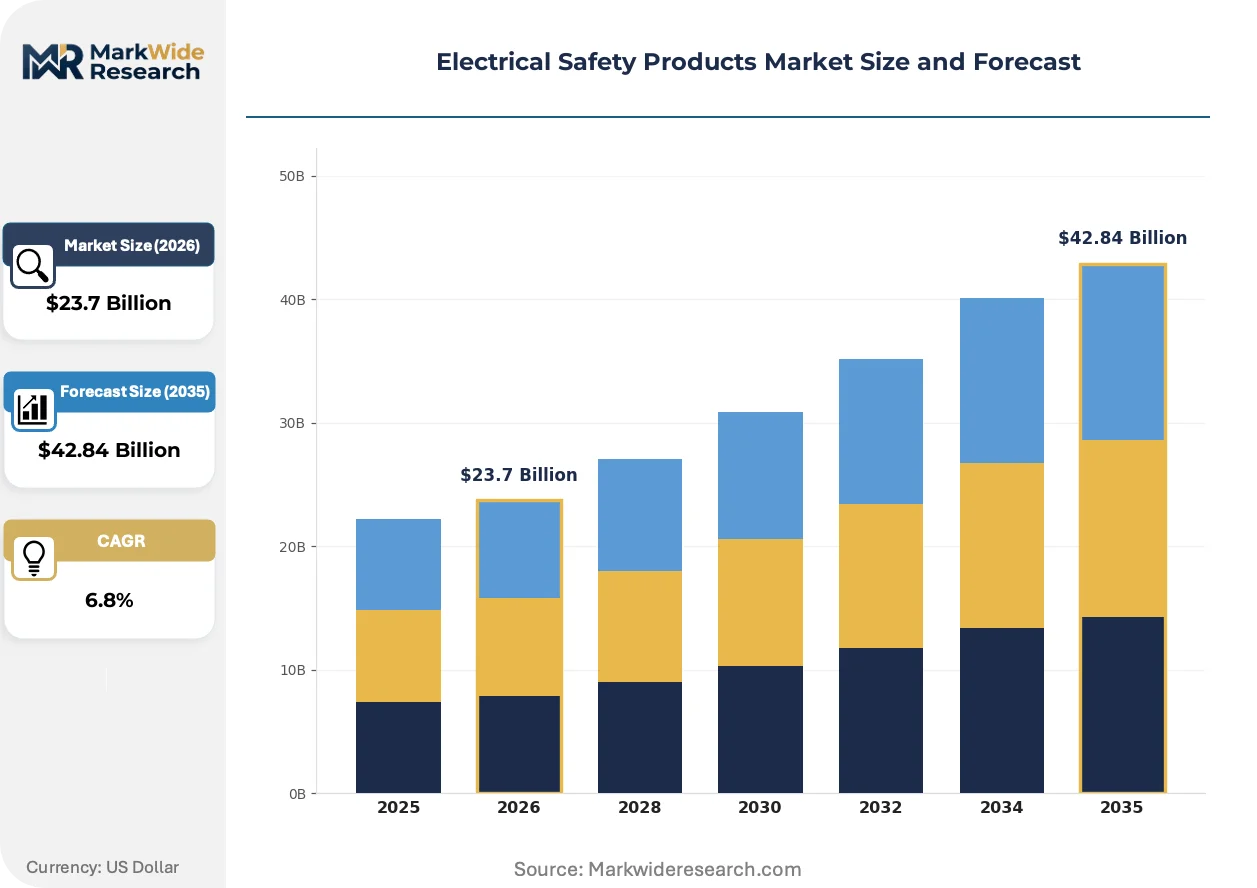
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Gloves, Circuit Breakers, Safety Switches, PPE End User: Construction, Manufacturing, Utilities, Residential Application: Electrical Maintenance, Power Distribution, Equipment Protection, Voltage Testing Technology: Smart Monitoring, Ground Fault Protection, Arc Flash Technology, Voltage Regulation |
| Companies Covered | Schneider Electric, ABB Ltd, Honeywell International Inc., Siemens, Eaton Corporation, 3M Company, Ansell Ltd, General Electric, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Safety Products Market Emerging Trajectories
Digital-twin modeling of electrical distribution networks is compressing the design-validation loop for protection system upgrades, enabling predictive arc flash hazard assessment before equipment energization. This capability is repositioning safety product vendors as engineering partners rather than commodity suppliers.
Thermographic sensors embedded within circuit breaker housings are converging with edge-computing analytics to enable real-time temperature trending and contact-wear prediction. Oil and gas facility operators in the US Gulf Coast are deploying these integrated systems at scale, replacing scheduled maintenance with condition-based intervention. The technology is converging with cloud-based asset management platforms, forcing traditional breaker manufacturers to develop software competencies or cede margin to digital-native competitors.
The EPA's anticipated SF6 emissions reporting requirements for switchgear are accelerating vacuum interruption R&D investment while triggering premature replacement of gas-insulated equipment in coastal utility zones. European regulators through the F-Gas Regulation have already banned SF6 in new medium-voltage installations, creating export market pressure for North American manufacturers to develop alternative platforms. Utility procurement teams in Germany and California are now specifying solid-insulation switchgear as default, compressing demand for conventional gas-insulated systems.
Consolidated procurement through integrated facility management providers is displacing direct OEM relationships for arc flash PPE and portable testing equipment. Large manufacturing conglomerates in Japan and South Korea are centralizing safety product purchasing through Metabo and facility service contracts, reducing supplier count and demanding volume-based pricing transparency. This concentration is most visible in automotive battery plant construction, where EPC contractors specify approved vendor lists that exclude specialized regional PPE brands.
Electrical Safety Products Market Segmentation
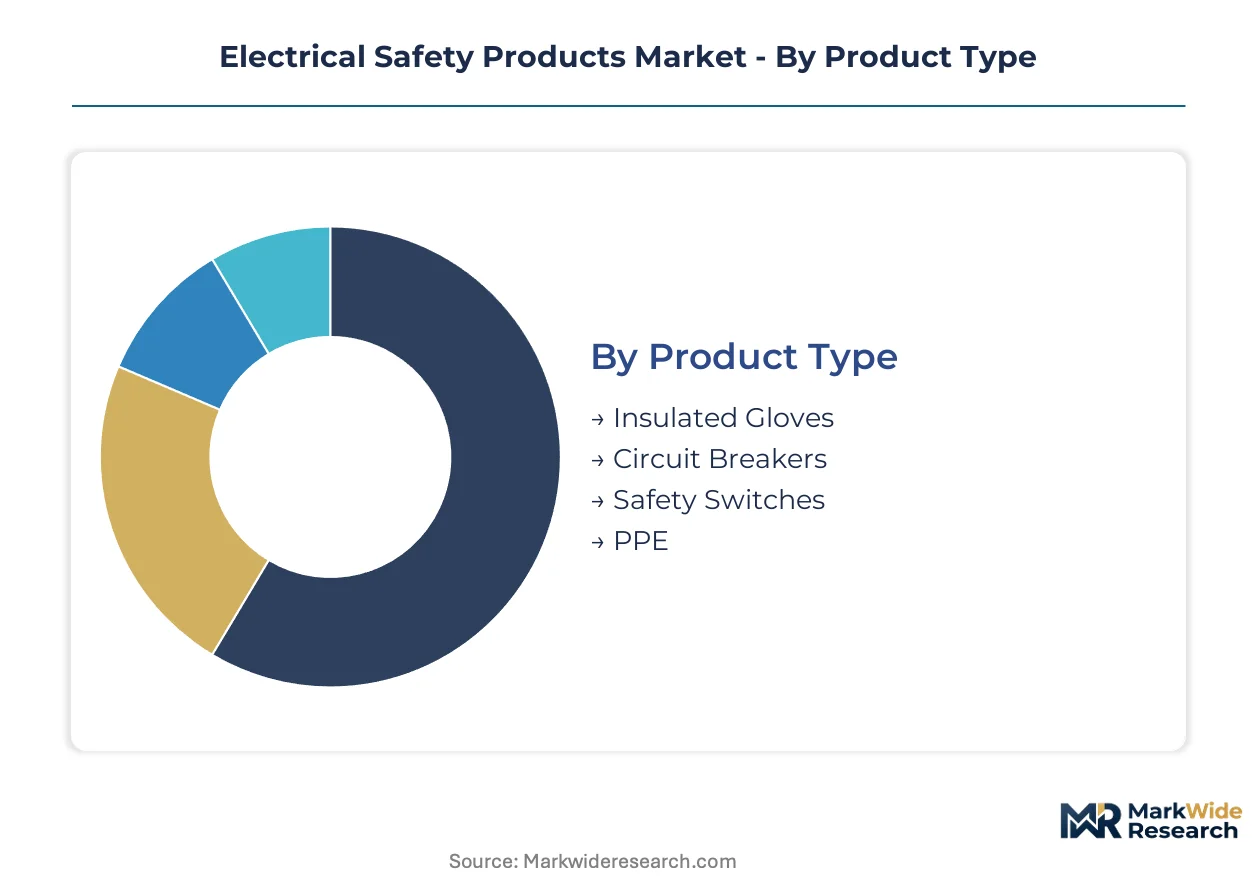
Electrical safety product procurement fractures along voltage class, end-use risk exposure, and certification complexity. Supplier qualification pipelines diverge sharply between commodity PPE and engineered protection systems, creating distinct margin architectures within each segment cluster.
Product Type:
Supply concentration for dielectric materials and breaker assemblies varies dramatically across protection categories, with captive rubber compounding and semiconductor trip unit sourcing determining competitive moats.
- Circuit Breakers:Microprocessor-based trip units with embedded arc flash detection algorithms dominate medium-voltage infrastructure. Data center construction in Northern Virginia and hyperscale builds across Singapore are pulling procurement toward integrated smart monitoring configurations with every panel installation.
- Arc Flash Technology:Systems combining incident energy calculation software with relay coordination hardware command premium positioning. EU Green Deal industrial electrification mandates for steel and cement plants are compressing replacement cycles for legacy protection across integrated facilities.
- Insulated Gloves:Nitrile and natural rubber compounds rated for specific voltage classes, with Malaysia and Thailand dominating feedstock supply.
- Safety Switches:Disconnect devices for lockout-tagout procedures in commercial and industrial maintenance workflows.
- PPE:Face shields, arc-rated clothing, and voltage-rated tools for energized work compliance.
Circuit breakers absorb the bulk of installed capacity; arc flash technology is expanding most quickly.
End User:
Procurement authority concentrates differently across customer types, with utility privatization waves and EPC contractor vendor lists reshaping supplier access.
- Utilities:Transmission and distribution operators with standardized safety protocols and capital expenditure cycles. Brazil's Southeast regional distribution asset sales are concentrating demand among private operators with consolidated procurement functions.
- Manufacturing:Heavy industrial facilities with NFPA 70E compliance obligations and multi-site standardization requirements. Automotive battery plant construction in Japan and South Korea is centralizing purchasing through integrated facility management contracts.
- Construction:Project-based procurement with seasonal hiring cycles and CE-MDR recertification backlogs disrupting inventory planning.
- Residential:Consumer-grade circuit protection through retail and electrical contractor channels.
Utilities command the deepest replacement cycles; manufacturing is climbing the fastest on electrification mandates.
Application:
Functional use cases determine technology specification intensity, with predictive maintenance convergence favoring sensor-integrated solutions over passive protection.
- Power Distribution:Medium-voltage switchgear and substation protection with SF6 phase-down regulations redirecting investment toward vacuum interruption. German and California utility procurement teams now specify solid-insulation switchgear as default configuration.
- Electrical Maintenance:Portable testing equipment and temporary protective grounds for energized work procedures.
- Equipment Protection:Motor control centers and generator interconnection with ground fault detection.
- Voltage Testing:Verification instruments for de-energization confirmation prior to maintenance access.
Power distribution anchors capital deployment; electrical maintenance is gaining share fastest on predictive service models.
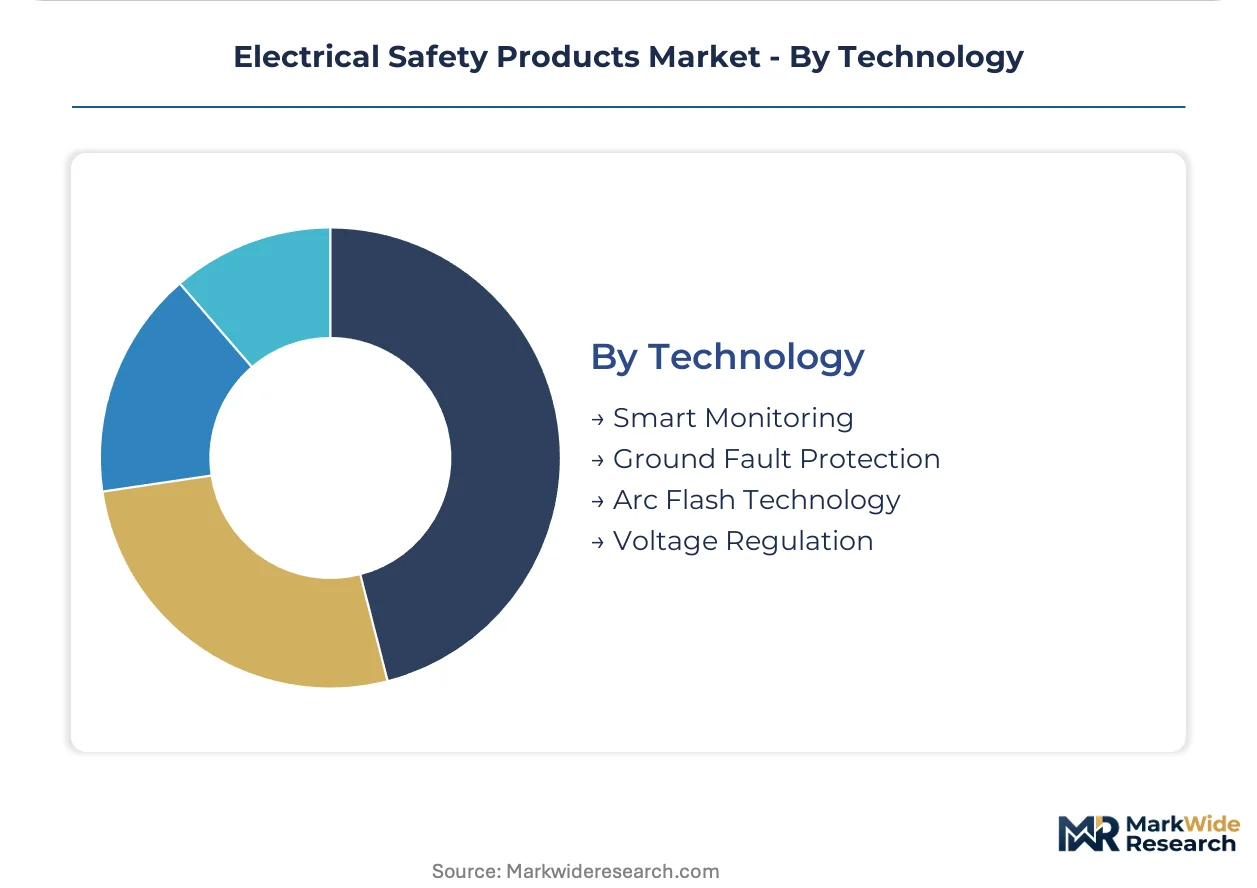
Technology:
Software-embedded differentiation separates premium positioning from commodity replacement, with digital-twin modeling repositioning vendors as engineering partners.
- Smart Monitoring:IoT-enabled thermal sensors and edge-computing analytics for condition-based intervention. Oil and gas operators across the US Gulf Coast are deploying these systems at scale, replacing scheduled maintenance with real-time temperature trending.
- Ground Fault Protection:Specialized detection systems for high-impedance fault identification in utility distribution networks.
- Arc Flash Technology:Relay coordination and incident energy reduction systems with embedded hazard assessment software.
- Voltage Regulation:Tap-changing and compensation equipment for power quality management.
Smart monitoring shows the steepest expansion trajectory; ground fault protection holds the most stable installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscale data center corridor commands the densest concentration of arc flash protection procurement in North America, with Ashburn and Loudoun County driving integrated smart monitoring specifications across every new substation installation.
United States
OSHA's electrical safety standards and the EPA's emerging SF6 emissions rules are compressing replacement cycles for legacy switchgear. Texas and California utility procurement teams now specify solid-insulation configurations as default, redirecting capital expenditure toward vacuum interruption platforms in coastal substations.
Germany
The EU F-Gas Regulation and Green Deal industrial electrification mandates are forcing arc flash system upgrades across Ruhr steel plants and Bavarian cement facilities. Munich-based industrial operators are consolidating PPE procurement through integrated facility management contracts, reducing supplier counts by half.
China
Dual carbon goals and MIIT industrial electrification directives are accelerating medium-voltage breaker replacement in Yangtze River Delta manufacturing zones. Shanghai's automotive battery plant construction is centralizing safety product purchasing through EPC contractor vendor lists that exclude regional PPE brands.
Brazil
ANVISA regulatory alignment with IEC standards and the Southeast regional utility privatization wave are concentrating insulated glove and circuit breaker demand among São Paulo-based private operators. Rio de Janeiro distribution asset sales are standardizing procurement protocols across consolidated capital expenditure functions.
India
BIS voltage rating harmonization with IEC standards is reducing import friction for multinational suppliers in Maharashtra and Gujarat industrial corridors. The CEA's centralized certification framework is opening distribution channel partnerships for smart monitoring deployments in Bangalore's technology manufacturing zones.
Electrical Safety Products Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and software-embedded differentiation. The vendor base stratifies into three tiers: integrated digital-twin platform providers, captive medium-voltage component manufacturers, and specialized PPE compounders. Consolidation pressure concentrates among buyers with multi-site standardization capabilities. Dominant competitive moves include backward integration into dielectric rubber compounding and strategic partnerships for predictive maintenance software licensing.
Within the integrated platform tier, Schneider Electric and ABB Ltd exemplify archetype positioning through engineering partnership repositioning rather than commodity supply. Eaton Corporation occupies a distinct channel position in North American utility verticals. Honeywell International Inc. and 3M Company represent diversified industrial conglomerates with safety product divisions sitting within broader portfolio architectures. Siemens and General Electric anchor European and US-origin industrial electrification legacies respectively.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB Ltd |
| Honeywell International Inc. |
| Siemens |
| Eaton Corporation |
| 3M Company |
| Ansell Ltd |
| General Electric |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth permanent magnets feed from upstream mining operations through three distinct pricing tiers before reaching circuit breaker manufacturers. Malaysia's nitrile rubber compounds and Thailand's natural rubber feedstocks anchor insulated glove production costs, with freight differentials separating premium IEC-certified PPE from economy-grade alternatives in European and North American distribution channels.
Pricing Analysis
Uptime guarantees and arc flash incident energy reduction outcomes anchor value-based pricing for smart monitoring deployments. Three-tier pricing structure across premium, standard, and economy levels separates digital-twin integrated platforms from basic relay hardware and commodity replacement breakers. Cost compression in medium-voltage breaker production is intensifying because copper price volatility outpaces hedging capacity at European manufacturers. Utility procurement teams show lowest price sensitivity due to standardized safety protocols, while construction contractors face acute budget constraints during seasonal hiring cycles.
Supply Chain Analysis
Ocean freight rates from Southeast Asian rubber compounders to European PPE finishers determine landed cost spreads across certification tiers. Malaysia, Thailand, and Indonesia concentrate dielectric rubber feedstock supply for insulated gloves and face shields. Semiconductor trip units and thermoset composite housings rest on Taiwan and South Korea component flows. Single-source vulnerability in nitrile compound certification creates inventory disruption risk during CE-MDR recertification backlogs. Distribution runs through integrated facility management providers consolidating multi-site manufacturing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial electrification mandates and SF6 phase-down regulations are forcing sub-scale PPE compounders and legacy breaker assemblers toward exit or acquisition, concentrating vendor relationships among buyers with multi-site standardization capabilities.
For Market Incumbents: Hedge against copper and rare earth input volatility through backward integration into scrap copper recovery or long-term offtake agreements with Australian and Chilean mining operations. Defend premium positioning in smart monitoring by embedding predictive maintenance algorithms directly into circuit breaker firmware, preventing margin capture by software-native competitors. For New Entrants and Emerging Players: Enter via Brazil's Southeast utility privatization corridor, where ANVISA-IEC alignment has reduced certification friction for foreign suppliers without established local presence. Target arc flash engineering services as the most penetrable segment, given qualified NFPA 70E trainer scarcity relative to audit demand. Pursue EPC contractor vendor list inclusion through volume-based pricing transparency and rapid CE-MDR approval timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap arc flash technology specialists with captive relay coordination software in Germany and California, where SF6 phase-down regulations have stranded conventional gas-insulated switchgear inventories. Long-term viability hinges on subscription revenue conversion from hardware sales. Watch EPA emissions reporting rule finalization as the signal for accelerated vacuum interruption R&D investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Rubber Compounding | Captive supply of nitrile compounds insulates margin from Malaysia-Thailand feedstock concentration. |
| Predictive Maintenance Software Licensing Partnership | Recurring revenue conversion from thermal imaging-arc flash algorithm integration displaces hardware-only competitors. |
| CE-MDR Notified Body Capacity Expansion | Reduced insulated glove approval timelines capture construction and utility seasonal hiring windows. |
| Vacuum Interruption Platform Development | EPA SF6 restrictions and EU F-Gas Regulation redirect utility procurement toward solid-insulation alternatives. |
| EPC Contractor Vendor List Consolidation | Centralized automotive battery plant purchasing in Japan and South Korea excludes fragmented regional PPE brands. |
Methodological Framework
Document review covered SEC 10-K filings, EU F-Gas Regulation impact assessments, and OSHA electrical safety standard updates, complemented by interviews with utility capital expenditure directors, EPC contractor procurement leads, arc flash engineering consultants, and integrated facility management executives. Secondary validation drew from customs trade data, BIS voltage rating harmonization notices, and ANVISA regulatory alignment documentation. Bottom-up product segmentation triangulated against top-down electrification infrastructure spend estimates.
Segment-level outputs across voltage class, end-use risk exposure, and technology intensity were modeled over the projection horizon. The analytical framework incorporated circuit breaker replacement cycle predictability, arc flash system upgrade timelines under EU Green Deal mandates, and smart monitoring retrofit penetration rates. CAGRs were derived from weighted average growth assumptions across data center cluster expansion, utility privatization waves, and manufacturing electrification compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes and CE-MDR notified body capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market