
 Intrinsic Safety Modules Market | 2026-2036
Intrinsic Safety Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Intrinsic Safety Modules Market Outlook
Silicon carbide is recalibrating isolation barrier economics by enabling higher temperature ratings and reduced component counts in compact module designs. Eaton leverages its integrated electrical portfolio to anchor hazardous area solutions across North American energy infrastructure. Pepperl+Fuchs Inc. specializes in sensor-interface isolation technology, sustaining its position in process automation channels. R. STAHL AG dominates European certification depth for Ex-rated equipment, competing on regulatory coverage breadth.
Intrinsic safety modules are engineered electrical interfaces that limit energy transfer into hazardous zones to levels incapable of igniting explosive gas or dust mixtures, typically achieving this through resistive current limiting, zener voltage clamping, and galvanic isolation rated to IEC 60079-11 spark-energy thresholds. Their primary industrial purpose is protecting instrumentation loops in classified locations while maintaining signal integrity for process control systems. Isolator configurations command premium positioning due to their elimination of grounding dependencies and superior noise immunity in long cable runs. Digital technology adoption is accelerating fastest among greenfield petrochemical installations, while analog architectures retain entrenched positions in legacy refinery retrofit budgets. Wireless variants remain niche but occupy strategic importance for remote tank farm monitoring where cabling costs dominate project economics.
FDA oversight of pharmaceutical manufacturing environments shapes module specifications for cleanroom-adjacent hazardous zones, while IECEx and ATEX certification frameworks govern product access across European and Asia-Pacific industrial markets. OSHA process safety management requirements in the United States mandate documented intrinsic safety verification for covered chemical facilities, creating compliance-driven replacement cycles. NHTSA and FMCSA regulations for battery-electric vehicle maintenance bays are emerging as adjacent demand catalysts as electrification expands hazardous area classifications. Stakeholders must monitor how evolving hydrogen economy infrastructure codes redefine zone classification boundaries and module performance thresholds.
Market Dynamics
Silicon carbide isolation barriers are compressing module footprints while IEC 60079-11 certification timelines lengthen, forcing manufacturers to front-load regulatory investment before design finalization.
Growth Catalysts
- Zone 0/1 reclassification:Expanding hazardous area classifications in hydrogen refueling infrastructure are mandating higher-density intrinsic safety deployments across German chemical processing clusters.
- ATEX enforcement tightening:EU member states are accelerating inspection cycles for legacy installations, compressing replacement timelines for analog barrier systems in refineries.
- Wireless instrumentation adoption:Tank farm operators are eliminating cable trenching costs through battery-powered wireless transmitters requiring compact isolation modules rated for extended temperature ranges.
Market Restraints
- Silicon carbide substrate shortages:Wafer supply concentration among Japanese and German producers creates input cost volatility for high-temperature-rated barrier designs.
- Certification fragmentation:Divergent IECEx, ATEX, and OSHA interpretation protocols force redundant testing cycles, extending time-to-revenue for multi-jurisdictional product launches.
- Galvanic isolator cost premium:Transformer-based isolation remains three to four times the cost of zener barrier equivalents, constraining adoption in budget-constrained brownfield retrofits.
Strategic Opportunities
- Battery-electric vehicle service bays:NHTSA and FMCSA are drafting hazardous area classifications for high-voltage maintenance facilities, opening adjacent demand for compact isolation modules in automotive aftersales infrastructure.
- Pharmaceutical cleanroom integration:FDA-adjacent hazardous zones in sterile manufacturing are creating specification requirements for corrosion-resistant barrier housings with sanitary surface finishes.
- Digital twin convergence:Module manufacturers embedding diagnostic telemetry are converging with asset management platforms, enabling predictive replacement contracts that displace transactional component sales.
Industry Challenges
- Ex-rated firmware validation:Software-configurable safety parameters require documented verification against spark-energy thresholds, extending engineering headcount requirements for product development teams.
- Legacy loop compatibility:4-20mA analog architectures in decades-old refinery distributed control systems resist digital isolator integration without signal conditioning intermediaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrinsic Safety Modules Market |
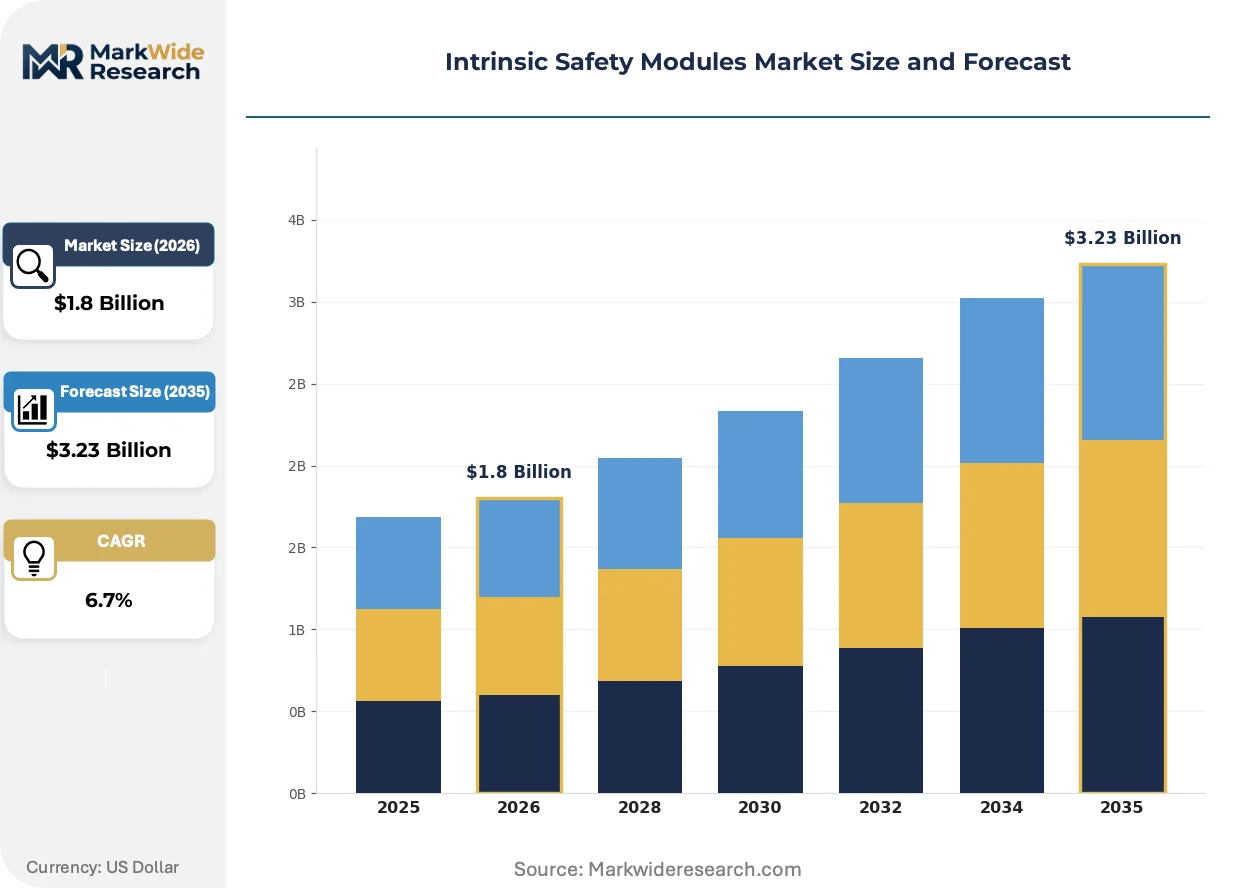
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Modules, Zener Barriers, Isolators, Controllers Application: Oil & Gas, Mining, Chemical Processing, Laboratories Technology: Digital, Analog, Hybrid, Wireless End User: Manufacturing, Telecommunications, Energy, Pharmaceuticals |
| Companies Covered | Eaton, Siemens AG, Pepperl+Fuchs Inc., Schneider Electric, Rockwell Automation, R. STAHL AG, ABB, Extronics, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrinsic Safety Modules Market Strategic Shifts
Module architectures are bifurcating between compact silicon carbide designs for greenfield installations and retrofit-compatible form factors preserving legacy signal integrity.
Silicon carbide power semiconductors are enabling 175°C ambient ratings in isolation barriers previously limited to 85°C thresholds. Offshore platform operators in the North Sea are specifying these modules for topside instrumentation exposed to solar loading and engine room proximity. This thermal headroom is converging with reduced cooling infrastructure requirements, compressing total installed cost for compact skids.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate sulfur hexafluoride from hermetically sealed relay modules used in high-voltage isolation circuits. Industrial valve and actuator suppliers are redesigning positioner interfaces to accommodate vacuum-insulated alternatives with equivalent dielectric strength. German chemical processors are absorbing prototype qualification costs to secure ATEX compliance ahead of 2030 bans.
Specification authority is migrating from plant engineering contractors to owner-operator technical standards departments, compressing approved vendor lists. EPC firms in Middle Eastern petrochemical developments are losing discretion over barrier selection as Saudi Aramco and ADNOC centralize procurement around pre-qualified module families. This concentration is displacing regional distributor influence with direct manufacturer-account relationships requiring localized technical support capabilities.
Intrinsic Safety Modules Market Segmentation
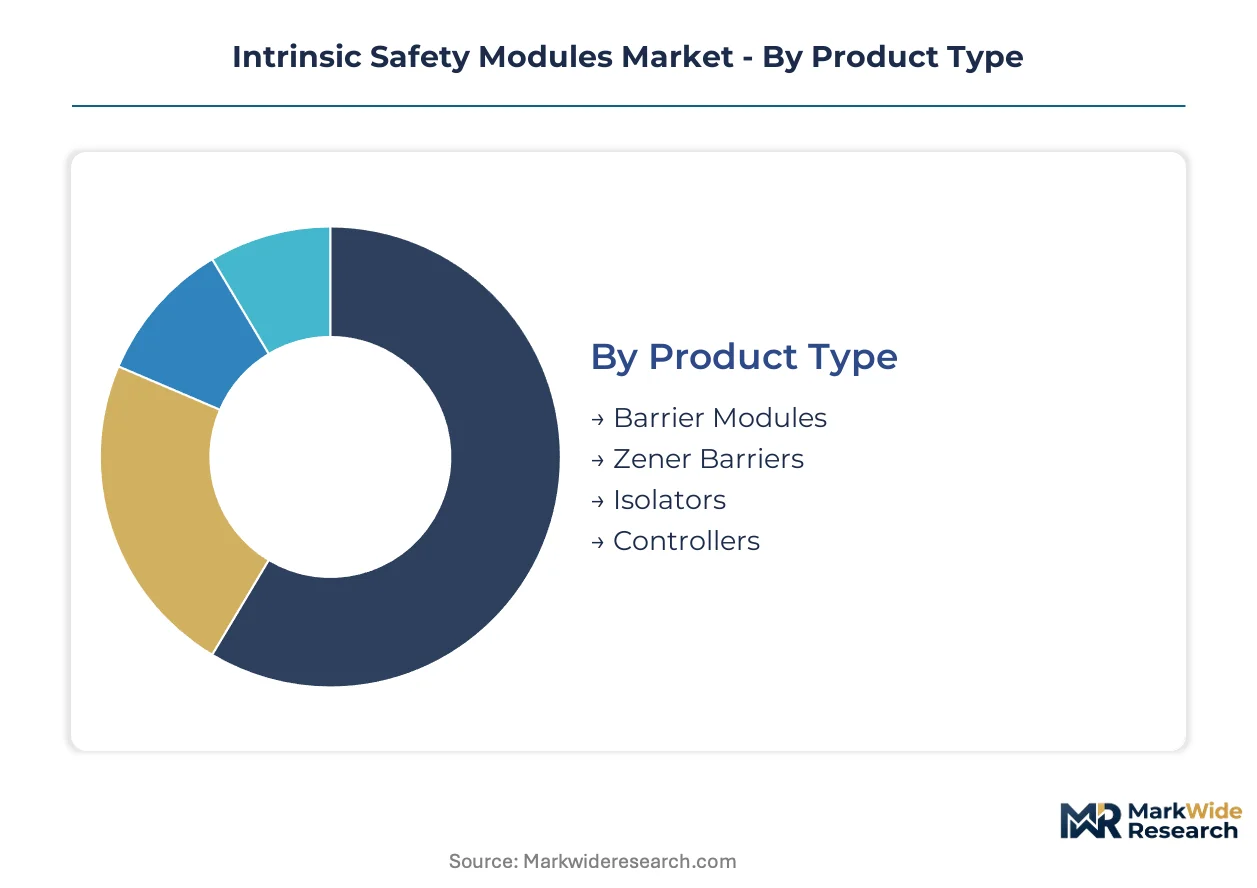
Intrinsic safety module procurement decisions hinge on zone classification severity, legacy infrastructure compatibility, and total installed cost across hazardous area lifecycles. Segmentation reveals how technology choices cascade through certification requirements, maintenance protocols, and replacement economics in regulated industrial environments.
Product Type:
Buyers prioritize galvanic isolation performance against grounding constraints and cable run distances in classified zones.
- Barrier Modules:Resistive current-limiting architectures clamp energy transfer through precision resistor networks rated to IEC 60079-11 spark-energy thresholds. German chemical processors specify these for high-density marshalling cabinets in Zone 1 environments where grounding topology permits shared earth references. Module footprint compression drives silicon carbide adoption in greenfield installations.
- Isolators:Transformer-based galvanic isolation eliminates grounding dependencies entirely, delivering superior noise immunity across kilometer-scale cable runs in offshore platform topside instrumentation. North Sea operators absorb three-to-four-fold cost premiums to avoid signal degradation in 4-20mA process loops. Dielectric strength ratings determine competitive positioning in high-voltage isolation circuits.
- Zener Barriers:Voltage-clamping designs using zener diodes and fuses achieve cost minima for Zone 2 applications with established equipotential bonding infrastructure.
- Controllers:Integrated safety logic modules consolidate multiple barrier functions with diagnostic telemetry for asset management platform convergence.
Isolators lead on scale; barrier modules lead on momentum.
Application:
Zone classification stringency and inspection cycle frequency determine replacement urgency across verticals.
- Oil & Gas:Offshore platform topside instrumentation and onshore refinery distributed control systems demand explosion protection across Zone 0/1/2 hierarchies. North Sea operators specify 175°C-rated silicon carbide barriers for solar-loaded engine room proximity. Hydrogen refueling infrastructure expansion is reclassifying former safe areas into Zone 0 territories.
- Chemical Processing:German industrial clusters anchor European demand through ATEX enforcement tightening and dense petrochemical infrastructure. Corrosion-resistant housings with sanitary surface finishes address FDA-adjacent cleanroom requirements in pharmaceutical manufacturing adjacencies.
- Mining:Underground coal operations and metal extraction sites deploy barriers against methane and combustible dust atmospheres with severe ingress protection requirements.
- Laboratories:Research facilities handling pyrophoric reagents require compact isolation for analytical instrumentation in confined fume hood environments.
Oil & gas commands installed base; chemical processing climbs the fastest.
Technology:
Signal integrity requirements and legacy infrastructure age bifurcate adoption trajectories between analog preservation and digital migration.
- Analog:4-20mA current loop architectures retain entrenched positions in decades-old refinery retrofit budgets where distributed control system replacement is capital-constrained. Signal conditioning intermediaries bridge compatibility gaps when digital isolators encounter legacy loop impedances. Brownfield project economics favor zener barrier cost structures over galvanic isolation premiums.
- Digital:Greenfield petrochemical installations specify software-configurable safety parameters with embedded diagnostic telemetry for predictive replacement contracts. Ex-rated firmware validation against spark-energy thresholds extends engineering headcount requirements but enables asset management platform convergence.
- Hybrid:Mixed-signal architectures preserve analog loop compatibility while adding digital communication overlays for incremental upgrade paths.
- Wireless:Battery-powered transmitter isolation modules eliminate cable trenching costs in remote tank farm monitoring applications with extended temperature range requirements.
Analog leads on scale; digital gains share fastest.
End User:
Regulatory inspection intensity and process safety management documentation mandates drive compliance-driven replacement cycles.
- Energy:Oil supermajors and national oil companies centralize procurement around pre-qualified module families, compressing approved vendor lists and displacing regional distributor influence. EPC firms in Middle Eastern developments lose barrier selection discretion as Saudi Aramco and ADNOC technical standards departments consolidate specification authority.
- Pharmaceuticals:FDA oversight of sterile manufacturing environments shapes module specifications for corrosion-resistant barrier housings with sanitary surface finishes in cleanroom-adjacent hazardous zones. Process safety management documentation requirements mandate intrinsic safety verification with replacement cycle predictability.
- Manufacturing:General industrial automation deploys barriers across paint finishing, solvent handling, and powder coating operations with ATEX and IECEx certification requirements.
- Telecommunications:Battery-electric vehicle service bay infrastructure requires compact isolation modules for high-voltage maintenance facility hazardous area classifications under emerging NHTSA and FMCSA regulations.
Energy leads on scale; pharmaceuticals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processing clusters anchor demand concentration for intrinsic safety modules, with dense petrochemical infrastructure and stringent ATEX enforcement compressing replacement cycles across Zone 0/1 hazardous area classifications.
Germany
BASF Ludwigshafen and Bayer Leverkusen drive specification authority for corrosion-resistant barrier housings in cleanroom-adjacent pharmaceutical manufacturing. EU F-Gas Regulation phase-down schedules force sulfur hexafluoride elimination from hermetically sealed relay modules by 2030. North Rhine-Westphalia's Ruhr industrial corridor concentrates brownfield retrofit demand for analog-compatible isolator designs.
United States
OSHA process safety management mandates documented intrinsic safety verification for covered chemical facilities in the Gulf Coast petrochemical corridor. NHTSA and FMCSA are drafting hazardous area classifications for battery-electric vehicle service bays. Houston's refinery complex sustains entrenched positions for 4-20mA analog architectures in legacy distributed control systems.
China
SINOPEC and PetroChina expand offshore platform topside instrumentation across the Bohai Bay and South China Sea developments. GB standards alignment with IEC 60079-11 spark-energy thresholds accelerates domestic certification capacity. Yangtze River Delta chemical processors absorb silicon carbide barrier prototypes for 175°C ambient ratings in compact skid installations.
Saudi Arabia
Saudi Aramco centralizes procurement around pre-qualified module families for Jubail and Yanbu petrochemical city developments. SFDA oversight of pharmaceutical manufacturing shapes specification requirements for sterile processing environments. Eastern Province industrial clusters displace regional distributor influence with direct manufacturer-account relationships.
United Kingdom
North Sea offshore operators specify 175°C-rated silicon carbide barriers for solar-loaded topside instrumentation in aging platform infrastructure. HSE inspection cycle tightening compresses replacement timelines for legacy analog barrier systems. Aberdeen's energy services cluster concentrates technical support capabilities for direct manufacturer engagement.
Intrinsic Safety Modules Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers compress approved vendor lists through integrated electrical offerings. The vendor base stratifies across three tiers: diversified industrial conglomerates with hazardous area solution portfolios, specialized explosion protection houses with deep certification expertise, and component suppliers focused on sensor-interface isolation. Strategic archetypes include certification-depth competitors competing on regulatory coverage breadth, and integrated-solution providers anchoring cross-product hazardous area infrastructure. Capacity expansion and technology licensing represent the dominant competitive vectors.
Among diversified industrial conglomerates, Eaton and Siemens AG exemplify integrated-solution positioning across hazardous area electrical infrastructure. R. STAHL AG occupies a specialist tier focused on European certification depth for Ex-rated equipment. These three anchors represent divergent strategic postures: scale-driven portfolio breadth versus regulatory-coverage specialization versus geographic concentration in enforcement-stringent jurisdictions.
| Leading Market Players |
|---|
| Eaton |
| Siemens AG |
| Pepperl+Fuchs Inc. |
| Schneider Electric |
| Rockwell Automation |
| R. STAHL AG |
| ABB |
| Extronics |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Certified Ex-equipment engineering talent concentration in Germany's Ruhr industrial corridor compresses labor-cost differentials between premium isolator and economy barrier tiers, widening pricing spreads as ATEX compliance complexity escalates.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer supply volatility flows unevenly across product tiers, with transformer-based isolators absorbing margin compression while zener barrier producers maintain cost structures through legacy resistor networks. Pricing stratifies across ATEX-certified premium modules, IECEx-standard mid-tier offerings, and economy zener designs for Zone 2 grounding-permissive applications. Cost compression in isolator segments is intensifying because Japanese and German substrate producers concentrate supply. Budget-constrained brownfield retrofit buyers exhibit highest price sensitivity, while offshore platform operators in the North Sea absorb premiums for 175°C thermal ratings.
Supply Chain Analysis
Local-content-rule enforcement in Saudi Arabia's Jubail and Yanbu petrochemical cities and China's Yangtze River Delta chemical clusters is reshaping sourcing patterns toward domestic assembly partnerships. Manufacturing gravity centers on Germany, Japan, and the United States for precision resistor networks and transformer cores. Raw material dependencies rest on silicon carbide wafers, copper magnet wire, and hermetic sealing ceramics. Single-source vulnerability concentrates in Japanese substrate producers. Distribution runs through direct manufacturer-account relationships with owner-operator technical standards departments, displacing regional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intrinsic safety modules market functions as a stable compounder, with IEC 60079-11 certification renewal cycles generating predictable replacement revenue across regulated industrial facilities.
For Market Incumbents: Cement certification-depth moats by accelerating ATEX and IECEx pre-qualification ahead of 2030 EU F-Gas phase-down deadlines. Prioritize backward integration into silicon carbide substrate supply through Japanese partnership structures to defend margin position against input cost volatility. Channel control through localized technical support capabilities in Saudi Arabia and Germany displaces distributor intermediation. For New Entrants and Emerging Players: Battery-electric vehicle service bay operators represent an underserved buyer archetype as NHTSA and FMCSA hazardous area classifications emerge. Target pharmaceutical cleanroom-adjacent hazardous zones requiring corrosion-resistant sanitary housings with limited incumbent specialization. Pursue digital twin diagnostic telemetry integration as the go-to-market angle for predictive replacement contracts. For Investors and Strategic Acquirers: Industrial electrical conglomerates seeking hazardous area portfolio completeness are the most active acquirer in this space, with Eaton and Siemens anchoring integrated-solution positioning. Five-to-ten year viability rests on regulatory enforcement intensity rather than technology disruption. Acquisition targets should display deep IECEx/ATEX certification libraries and direct relationships with Saudi Aramco or ADNOC technical standards departments. Monitor hydrogen refueling infrastructure zone reclassification velocity as the inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Acceleration | ATEX and IECEx front-loading secures access to Saudi Aramco and ADNOC procurement centralization. |
| Silicon Carbide Integration Partnership | Japanese substrate supplier alliances compress thermal rating cost premiums for North Sea offshore specifications. |
| Diagnostic Telemetry Embedding | Asset management platform convergence enables predictive replacement contracts displacing transactional sales. |
| Pharmaceutical Sanitary Housing Development | FDA-adjacent cleanroom requirements create specification moats in sterile manufacturing environments. |
| Direct Technical Support Localization | German and Saudi Arabian engineering presence captures owner-operator specification authority migration. |
Study Parameters
Direct dialogue with plant engineering contractors, hazardous area certification engineers, petrochemical procurement directors, and offshore platform instrumentation managers anchored qualitative grounding. Secondary validation drew from IEC 60079-11 technical committee documentation, ATEX notified body certification registers, OSHA process safety management enforcement records, and SEC filings from diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Segment-level value outputs emerged from modeling across product type, zone classification severity, signal technology architecture, and end-user regulatory intensity dimensions throughout the forecast period. CAGRs were derived from replacement cycle analysis tied to inspection frequency mandates and brownfield retrofit capital allocation patterns. Hydrogen economy infrastructure code evolution and battery-electric vehicle service bay classifications served as demand scenario inputs.
Underlying measurement precision varies by segment; oil and gas application forecasts carry tighter precision than emerging telecommunications applications. Projections reflect assumptions regarding IECEx and ATEX enforcement continuity and silicon carbide substrate supply stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Barricade Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market