
 Medical Safety Goggles Market | 2026-2036
Medical Safety Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Safety Goggles Market Insights
A shortage of trained infection control specialists is unwinding supply chain responsiveness across the protective eyewear sector. 3M leverages its integrated filtration expertise to sustain dominant hospital channel control. Honeywell International Inc. anchors industrial-to-medical crossover demand with ANSI-rated product lines. Mölnlycke Health Care AB specializes in single-use surgical protocols that compete directly with reusable alternatives.
Medical safety goggles are tight-fitting eye protectors constructed from optical-grade polycarbonate with indirect ventilation ports, designed to shield against bloodborne pathogens, chemical splashes, and impact hazards in healthcare environments. Polycarbonate technology dominates lens formulations due to its balance of optical clarity and impact resistance exceeding glass alternatives. Disposable goggles represent the fastest-growing product category as hospitals prioritize cross-contamination elimination over per-unit economics. Anti-fog coatings command premium positioning in surgical procedures where optical clarity directly affects operative outcomes. Emergency services applications remain structurally underpenetrated relative to clinical settings, creating latent volume pools.
OSHA bloodborne pathogen standards and FDA device classification rules jointly determine minimum performance thresholds for market entry in the United States. ANSI Z87.1 certification requirements from the American National Standards Institute shape procurement specifications across hospital systems and laboratory networks. Stakeholders must weigh European MDR compliance investments against domestic margin structures as regulatory divergence between FDA and notified body pathways widens.
Market Dynamics
OSHA's updated bloodborne pathogen enforcement is compressing procurement cycles across hospital systems, forcing rapid standardization of eye protection specifications and favoring suppliers with integrated certification documentation.
Growth Catalysts
- ANSI Z87.1 Compliance Mandates:Hospital procurement departments now require certified impact resistance ratings for all surgical eyewear, eliminating uncertified suppliers from vendor lists.
- Polycarbonate Optical Clarity:Lens technology advances enable thinner, lighter designs without sacrificing impact protection, accelerating replacement of older acetate-based inventory.
- United States Surgical Volume Concentration:Ambulatory surgical centers in Florida, Texas, and California generate disproportionate demand for premium anti-fog configurations.
Market Restraints
- Petrochemical Feedstock Volatility:Polycarbonate resin prices fluctuate with benzene and phosgene markets, compressing margins for molded lens manufacturers.
- Single-Source Ventilation Component Suppliers:Indirect vent port assemblies concentrate among three Taiwanese injection molders, creating geographic concentration risk.
- European MDR Documentation Burden:Extended technical file preparation timelines delay product launches by 18-24 months versus FDA 510(k) pathways.
Strategic Opportunities
- Emergency Medical Services Underpenetration:Paramedic and fire-rescue units in Germany, France, and Italy still rely on industrial-grade alternatives rather than medical-specific designs.
- Anti-Fog Nanocoating Convergence:Hydrophilic surface treatments combined with photochromic lens technology enable premium positioning in ophthalmic surgery suites.
- Group Purchasing Organization Consolidation:Premier and Vizient contracting leverage in the United States creates channel access for compliant mid-tier manufacturers.
Industry Challenges
- Infection Control Specialist Shortage:Hospital-based certification expertise gaps slow product evaluation and approval workflows.
- ISO 18526-1 Testing Backlogs:Optical quality verification queues at accredited laboratories extend time-to-market for new lens formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Safety Goggles Market |
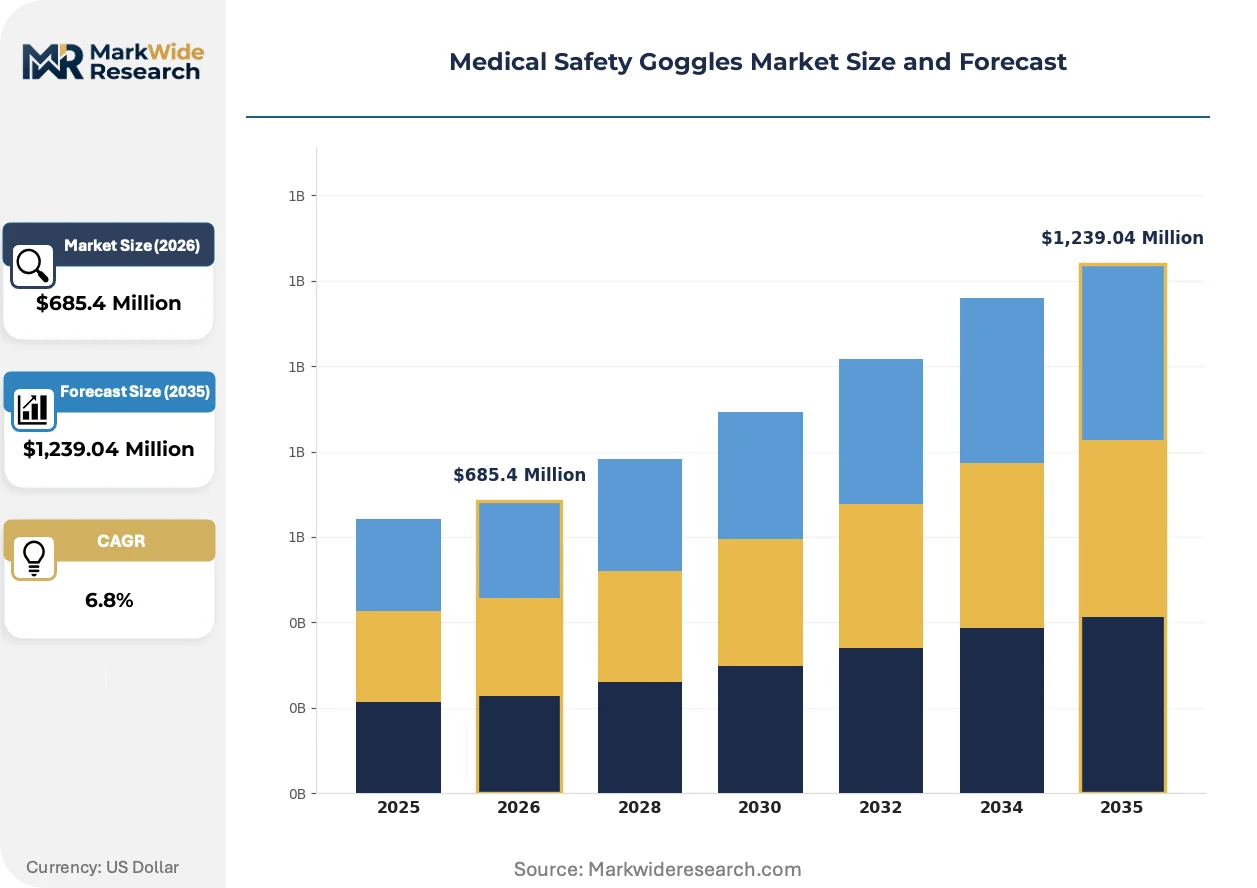
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Goggles, Disposable Goggles, Anti-Fog Goggles, Chemical-Resistant Goggles Application: Clinical Use, Laboratory Use, Emergency Services, Surgical Procedures End User: Hospitals, Clinics, Laboratories, Emergency Response Teams Technology: Polycarbonate Technology, Anti-Reflective Coating, UV Protection, Ventilation Systems |
| Companies Covered | 3M, Honeywell International Inc., Mölnlycke Health Care AB, TIDI Products, Xiamen Jiayu Optical Co., Ltd, Bollé Safety, G.F. Health Products, Cardinal Health, UNIVET S.R.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Safety Goggles Market Trends and Innovations
Material science advances and regulatory documentation requirements are restructuring competitive advantage around in-house optical testing capabilities and rapid certification turnaround.
Photochromic polycarbonate formulations are decomposing the traditional separation between indoor surgical eyewear and outdoor emergency response equipment. United States trauma centers in Arizona and Nevada have adopted dual-purpose designs at twice the rate of northeastern hospitals. This convergence is compressing SKU proliferation and favoring manufacturers with flexible coating deposition lines.
European MDR technical documentation requirements are forcing redesign of legacy product families to meet biocompatibility testing standards for extended skin contact. Manufacturers must now submit cytotoxicity and sensitization data for frame materials previously exempt under the Medical Device Directive. German and Dutch notified bodies are processing these submissions fastest, creating regulatory arbitrage opportunities for firms with established European Authorized Representative infrastructure.
Hospital supply chain directors are consolidating protective eyewear procurement under infection control committees rather than general medical-surgical buyers. This shift elevates clinical performance specifications over per-unit cost in vendor selection criteria. The transition is most advanced in United States academic medical centers, where value-analysis committees now mandate anti-fog performance testing data prior to contract approval.
Medical Safety Goggles Market Segmentation
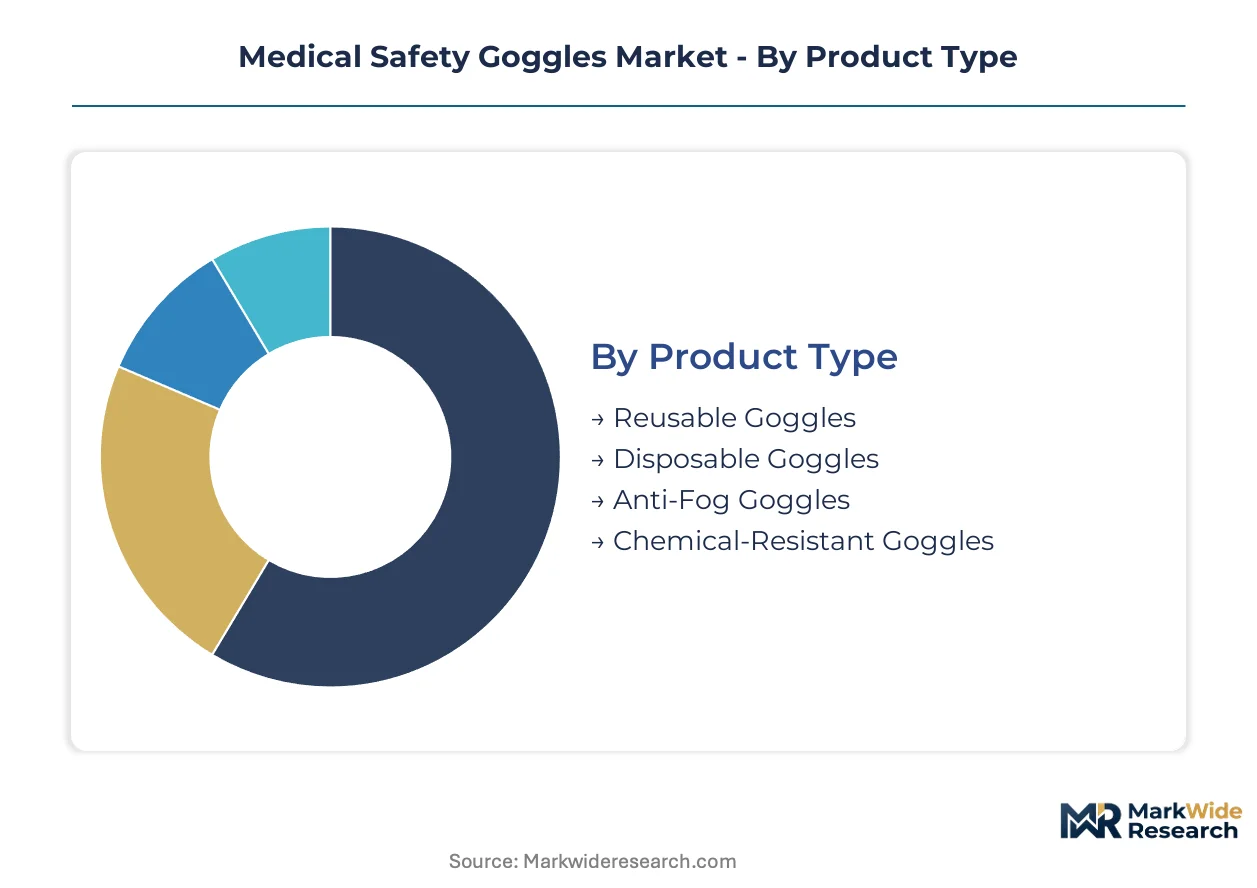
Segmentation in medical safety goggles reveals how substitution pressures and regulatory mandates reshape procurement priorities across healthcare settings. Product type and application dimensions expose the deepest fault lines between cost-driven standardization and performance-critical specialization.
Product Type:
Reusable designs face intensifying substitution pressure from single-use alternatives as hospitals prioritize cross-contamination elimination over per-unit economics.
- Reusable Goggles:Optical-grade polycarbonate construction with autoclavable frames supports extended service life in high-throughput surgical suites. Demand concentrates in United States academic medical centers where value-analysis committees amortize capital costs across multi-year procurement cycles. ANSI Z87.1 recertification requirements every 24 months create compliance friction.
- Disposable Goggles:Single-use polypropylene frames with pre-assembled polycarbonate lenses eliminate sterilization logistics. Ambulatory surgical centers in Florida and Texas drive volume as these facilities lack central sterile processing infrastructure. OSHA bloodborne pathogen enforcement accelerates replacement of reusable inventory.
- Anti-Fog Goggles:Hydrophilic surface coatings maintain optical clarity across temperature differentials in operating rooms.
- Chemical-Resistant Goggles:Butyl rubber seals and fluoropolymer lens treatments protect against cytotoxic drug exposure in oncology compounding.
Reusable Goggles retains volume leadership; Disposable Goggles holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity clinical deployment from premium surgical specifications where optical precision commands price multiples.
- Clinical Use:General patient care and diagnostic procedures require basic impact protection without specialized coatings. United States community hospitals in the Midwest standardize on ANSI Z87.1 baseline models to satisfy OSHA mandates at lowest procurement cost. Bulk purchasing through Premier and Vizient contracts compresses margins.
- Surgical Procedures:Microsurgery and ophthalmic interventions demand anti-fog performance validated to ISO 18526-1 optical quality standards. Concentrated demand in California and Arizona trauma centers reflects adoption of dual-purpose photochromic designs. Surgeon preference data increasingly gates contract approval.
- Laboratory Use:Research and pathology settings prioritize chemical splash protection with indirect ventilation.
- Emergency Services:Paramedic and fire-rescue units in Germany and France still rely on industrial-grade alternatives rather than medical-specific designs.
Clinical Use dominates procurement volume; Surgical Procedures generates the highest margin realization.
End User:
Customer type concentration determines channel strategy, with hospital system consolidation favoring suppliers with integrated certification documentation and GPO access.
- Hospitals:Integrated delivery networks in the United States consolidate protective eyewear procurement under infection control committees rather than general medical-surgical buyers. This elevates clinical performance specifications over per-unit cost in vendor selection. Academic medical centers mandate anti-fog testing data prior to contract approval.
- Laboratories:Independent reference labs and hospital-affiliated pathology units require chemical-resistant configurations for cytotoxic handling.
- Clinics:Physician office laboratories in Texas and Florida generate disproportionate demand for disposable configurations.
- Emergency Response Teams:Municipal fire-rescue and ambulance services remain structurally underpenetrated relative to clinical settings.
Hospitals anchor procurement volume; Emergency Response Teams present the largest latent expansion opportunity.
Technology:
Supply concentration in lens formulations and coating deposition creates technology leadership moats around in-house optical testing capabilities.
- Polycarbonate Technology:Optical-grade resin formulations balance impact resistance exceeding glass alternatives with weight reduction for extended wear comfort. United States surgical volume concentration in ambulatory centers drives specification standardization. Petrochemical feedstock volatility in benzene and phosgene markets compresses molded lens margins.
- Anti-Reflective Coating:Multi-layer vapor deposition reduces glare in microscope-integrated procedures. Demand concentrates in ophthalmic surgery suites where optical clarity directly affects operative outcomes.
- UV Protection:Ultraviolet-blocking additives serve outdoor emergency response and dermatology laser applications.
- Ventilation Systems:Indirect vent port assemblies concentrate among three Taiwanese injection molders, creating geographic concentration risk.
Polycarbonate Technology underpins baseline volume; Anti-Reflective Coating expands most quickly in premium surgical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States hospitals prioritize ANSI-certified surgical configurations, while European facilities emphasize MDR-compliant single-use protocols, and Asian markets balance industrial crossover demand with nascent medical-specific procurement standards.
United States
OSHA bloodborne pathogen enforcement compresses procurement cycles across hospital systems, forcing rapid standardization of eye protection specifications. FDA device classification rules determine minimum performance thresholds for market entry. Ambulatory surgical centers in Florida, Texas, and California generate disproportionate demand for premium anti-fog configurations.
Germany
European MDR technical documentation requirements force redesign of legacy product families to meet biocompatibility testing standards for extended skin contact. German notified bodies process cytotoxicity and sensitization submissions fastest, creating regulatory arbitrage opportunities. Industrial-to-medical crossover demand anchors procurement in the Ruhr industrial corridor.
France
ANSM oversight shapes compliance frameworks for protective eyewear distribution across hospital networks. Emergency services applications remain structurally underpenetrated relative to clinical settings, creating latent volume pools for paramedic and fire-rescue units. Paris-region academic medical centers mandate anti-fog performance testing data prior to contract approval.
China
NMPA medical device registration requirements govern market access for imported and domestic protective eyewear manufacturers. Polycarbonate lens manufacturing concentrates in coastal provinces with established petrochemical feedstock infrastructure. Xiamen-based optical fabricators supply molded lens assemblies to regional hospital procurement networks.
Japan
PMDA quality management system audits enforce stringent optical clarity standards for surgical eyewear deployment. METI industrial policy supports domestic manufacturing of high-performance polymer formulations. Tokyo-Osaka hospital corridor procurement elevates clinical performance specifications over per-unit cost in vendor selection criteria.
Medical Safety Goggles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital channel access through bundled certification documentation and the lower tier competing on coating specialization and regional manufacturing proximity. Market structure favors suppliers with in-house optical testing capabilities and rapid FDA 510(k) or European MDR turnaround. Three archetypes dominate: diversified industrial-healthcare conglomerates, single-use surgical protocol specialists, and optical coating technology boutiques. Competitive moves concentrate on strategic partnerships with group purchasing organizations and geographic expansion through European Authorized Representative infrastructure.
Among diversified industrial-healthcare conglomerates, 3M and Honeywell International Inc. occupy positions anchored by integrated filtration expertise and ANSI-rated product lines respectively. Mölnlycke Health Care AB exemplifies the single-use surgical protocol specialist archetype, competing directly with reusable alternatives through sterilization logistics elimination. These three entities represent the dominant competitive positioning vectors: conglomerate scale, industrial crossover capability, and disposable protocol specialization.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Mölnlycke Health Care AB |
| TIDI Products |
| Xiamen Jiayu Optical Co., Ltd |
| Bollé Safety |
| G.F. Health Products |
| Cardinal Health |
| UNIVET S.R.L. |
| Others |
Pricing and Supply Chain Analysis
ANSI Z87.1 certification requirements simultaneously gate supplier qualification and stratify price tiers across hospital procurement networks, compressing uncertified manufacturers into commodity segments while elevating compliant vendors to premium contracting positions.
Pricing Analysis
Long-term offtake agreements with United States group purchasing organizations anchor volume pricing for mid-tier manufacturers, while spot purchasing dominates ambulatory surgical center procurement where inventory turns matter more than contract fidelity. Price differentiation separates anti-fog surgical configurations from baseline clinical models through ISO 18526-1 optical testing validation and coating durability guarantees. Pricing pressure stems from petrochemical feedstock volatility in benzene and phosgene markets, compressing molded lens margins. Community hospitals in the Midwest exhibit highest price sensitivity, prioritizing OSHA-compliant baseline models over premium specifications.
Supply Chain Analysis
Taiwan anchors indirect vent port assembly production, with three injection molders concentrating geographic supply risk for critical ventilation components. China and South Korea feed polycarbonate resin formulations and anti-reflective coating deposition equipment into downstream fabrication. Raw material dependencies rest on optical-grade polycarbonate pellets, hydrophilic nanocoating chemicals, and butyl rubber seal compounds. Single-source vulnerability in Taiwanese vent port manufacturing exposes supply chains to regional disruption. Distribution runs through hospital group purchasing organizations and infection control committee procurement channels in United States academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 18526-1 optical testing capability scarcity constrains new product introduction velocity, creating defensive moats for manufacturers with in-house certification infrastructure and accredited laboratory partnerships.
For Market Incumbents: Fortify hospital channel control through bundled ANSI Z87.1 and FDA 510(k) documentation packages that accelerate procurement committee approval workflows. Deepen backward integration into polycarbonate resin compounding to buffer petrochemical price volatility. Prioritize anti-fog coating R&D investment as surgeon preference data increasingly gates contract renewal decisions against emerging coating technology boutiques. For New Entrants and Emerging Players: Anchor in emergency medical services applications across Germany, France, and Italy where industrial-grade alternatives still dominate paramedic and fire-rescue procurement. Exploit regulatory arbitrage through German notified body relationships for fastest European MDR technical documentation processing. Pursue European Authorized Representative infrastructure partnerships to bypass 18-24 month launch delays facing direct FDA pathway competitors. For Investors and Strategic Acquirers: European MDR enforcement reshapes the acquisition landscape toward targets with established cytotoxicity and sensitization testing data libraries for frame materials. Long-term viability favors optical coating technology boutiques with hydrophilic surface treatment patents and flexible deposition line configurations. Monitor ISO 18526-1 testing backlog durations at accredited laboratories as inflection indicator for certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed approval timelines secure hospital procurement committee placement ahead of MDR-delayed European competitors. |
| European Authorized Representative Partnership | Established infrastructure in Germany and Netherlands bypasses technical documentation bottlenecks at slower notified bodies. |
| Anti-Fog Nanocoating R&D Investment | Surgeon preference validation in ophthalmic surgery suites commands price multiples over baseline clinical configurations. |
| Hospital System GPO Contracting | Premier and Vizient channel access locks out mid-tier competitors lacking integrated certification documentation. |
| Backward Integration into Resin Compounding | In-house polycarbonate formulation buffers margin compression from benzene and phosgene market volatility. |
Research Methodology
Cross-validation between primary interviews with hospital infection control specialists, GPO contracts managers, and biomedical engineers and secondary sources including FDA 510(k) filings, ANSI certification databases, and hospital procurement records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing through polycarbonate resin consumption data and protective eyewear import statistics. Secondary validation draws from OSHA enforcement action reports, European MDR technical documentation timelines, and ambulatory surgical center construction permits.
Sensitivity analysis across petrochemical feedstock price scenarios, certification backlog durations, and GPO contract renewal cycles informs projection robustness. Segmentation dimensions span product type, application, end user, and technology with regional regulatory cluster overlays distinguishing FDA, MDR, and PMDA pathway markets. CAGR derivation incorporates surgical volume growth trajectories, OSHA enforcement intensity indices, and disposable-to-reusable substitution elasticities specific to ambulatory versus inpatient settings.
Underlying assumptions cover stable ANSI Z87.1 enforcement intensity, continued polycarbonate optical dominance, and GPO consolidation trajectories, with deviation risk concentrated in European MDR documentation timeline extensions and Taiwanese supply chain disruptions. Recalibration cycles align with material shifts in OSHA enforcement patterns, MDR notified body processing speeds, and photochromic lens technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market