
 Earmuffs Market | 2026-2036
Earmuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Earmuffs Market Analysis
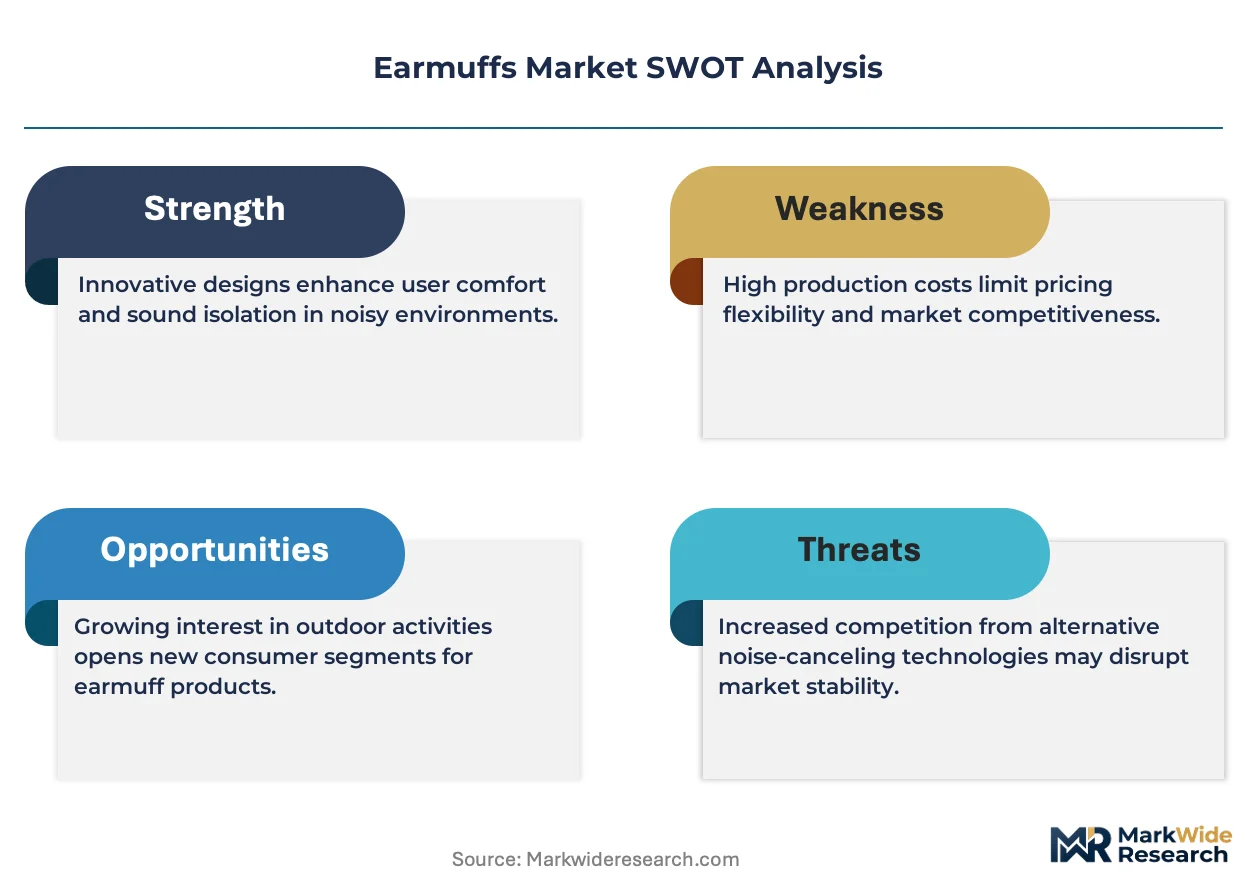
China is narrowing its cost advantage in earmuff assembly as Southeast Asian facilities scale die-cutting and acoustic foam molding operations. 3M leverages its dual-earcup architecture patents to sustain premium positioning across industrial channels. Honeywell anchors North American distribution through safety supply house partnerships, while MSA Safety competes in firefighter and emergency responder segments with integrated communications-enabled headgear.
Earmuffs are acoustic personal protective equipment comprising rigid thermoplastic cups, viscoelastic foam cushions, and adjustable headbands designed to attenuate environmental noise by 15–35 decibels across frequency spectra. Injection-molded ABS or polypropylene shells encase multi-layer damping materials, with electronic variants adding microphones, amplifiers, and circuit boards for situational awareness in hazardous workplaces. Passive earmuffs dominate volume in heavy manufacturing and construction due to zero power dependency and lower unit costs, while electronic earmuffs command margin premiums in hunting and tactical applications where ambient sound detection prevents accidents. Safety earmuffs certified to higher attenuation ratings concentrate procurement value among petrochemical and metal fabrication end users.
OSHA mandates in the United States and REACH compliance obligations in Europe shape material selection and labeling requirements for hearing protection sold through industrial distributors. The EU PPE Regulation and ANSI S3.19 testing protocols create divergent certification pathways that manufacturers must navigate for cross-border market access. Stakeholders should monitor evolving battery safety standards for electronic variants and track whether emerging economies adopt harmonized noise exposure limits that would expand addressable demand.
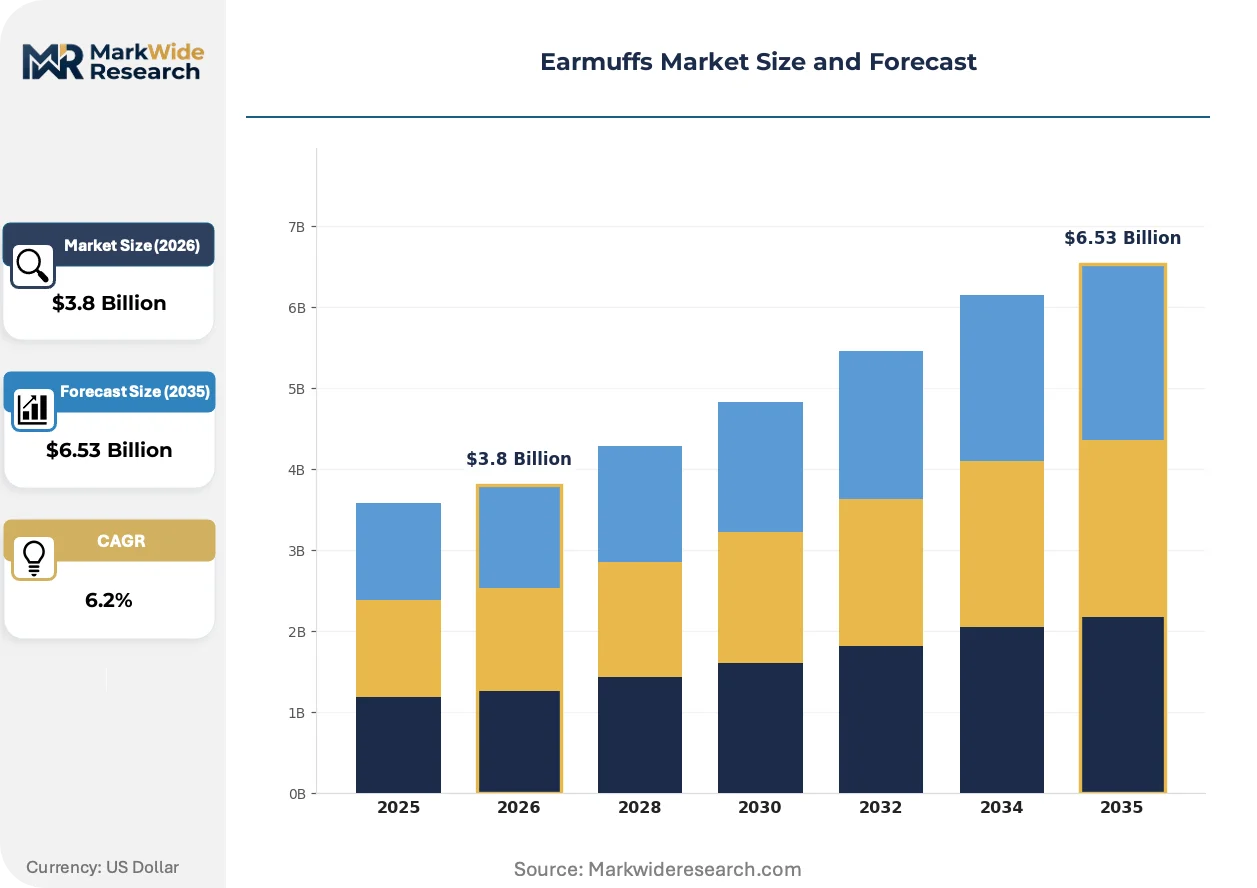
Market Dynamics
Industrial safety mandates across manufacturing hubs are compressing replacement cycles for certified hearing protection, while electronic variants with situational awareness capabilities are capturing margin premiums in tactical and recreational segments.
Growth Catalysts
- OSHA Hearing Conservation Amendments:Stricter noise exposure limits in United States metal fabrication and petrochemical facilities are accelerating bulk procurement of high-attenuation passive earmuffs through industrial distributors.
- Electronic Situational Awareness Integration:Amplified sound detection capabilities are displacing passive designs among construction supervisors and hunting enthusiasts who require ambient noise monitoring for accident prevention.
- Southeast Asian Assembly Scale-Up:Vietnamese and Thai facilities are expanding die-cutting and acoustic foam molding capacity, reducing landed costs for volume buyers in European industrial channels.
Market Restraints
- Petrochemical Input Volatility:ABS and polypropylene shell prices fluctuate with crude oil indices, compressing margins for manufacturers locked into annual supply contracts with construction distributors.
- Single-Source Battery Dependencies:Electronic earmuff amplifiers rely on concentrated lithium-cell supply from East Asian refiners, exposing production schedules to export control disruptions.
- Passive Design Substitution Ceiling:Zero-power passive earmuffs face technical limitations in delivering both high attenuation and wearer comfort during extended shifts exceeding eight hours.
Strategic Opportunities
- Indian Industrial Safety Enforcement:State-level factory inspectorates in Maharashtra and Gujarat are implementing hearing conservation protocols that mirror OSHA frameworks, creating first-mover advantages for certified importers.
- Firefighter Communications Integration:Bluetooth-enabled headgear combining hearing protection with radio interoperability addresses unmet needs in emergency responder segments currently served by separate equipment layers.
- EU PPE Regulation Harmonization:Converging CE marking requirements across member states simplify cross-border distribution for manufacturers holding modular certification covering both passive and electronic variants.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Finite pools of specialists capable of tuning multi-layer damping materials across frequency spectra are concentrating at established industrial safety firms, constraining new entrant R&D velocity.
- ANSI S3.19 Testing Bottlenecks:Limited accredited laboratories in North America extend certification timelines for electronic variants, delaying market entry for products incorporating new amplifier circuit designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earmuffs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Earmuffs, Electronic Earmuffs, Noise-Cancelling Earmuffs, Safety Earmuffs Application: Industrial Use, Hunting, Aviation, Music Events End User: Construction Workers, Musicians, Hunters, General Consumers Material: Foam, Plastic, Metal, Fabric |
| Companies Covered | Protective Industrial Products, Delta Plus, 3M, ADCO Hearing Products, Centurion Safety Products, Honeywell, Moldex-Metric, Radians, MSA Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earmuffs Market Emerging Trajectories
Digital signal processing and wireless connectivity are redefining what hearing protection delivers beyond noise attenuation, compressing the boundary between safety equipment and communication systems.
Directional microphone arrays with programmable gain control are virtualizing the traditional trade-off between protection and situational awareness. Hunters in the United States and tactical operators in Germany are adopting these systems fastest, replacing separate hearing protection and communication headsets with unified headgear that attenuates hazardous impulse noise while amplifying critical ambient cues.
REACH compliance obligations are forcing reformulation of viscoelastic foam cushion chemistries across European supply chains. Manufacturers serving German automotive and French aerospace end-users are accelerating migration to isocyanate-free polyurethane alternatives ahead of 2025 substance restriction deadlines, with passive earmuff lines facing the steepest retooling requirements.
Certification-driven specification tightening is altering how industrial buyers evaluate suppliers. Petrochemical facilities in Texas and Louisiana are unbundling after-sales fit-testing services from equipment procurement, contracting third-party occupational audiologists to verify real-world attenuation performance rather than relying solely on laboratory NRR ratings.
Earmuffs Market Segmentation
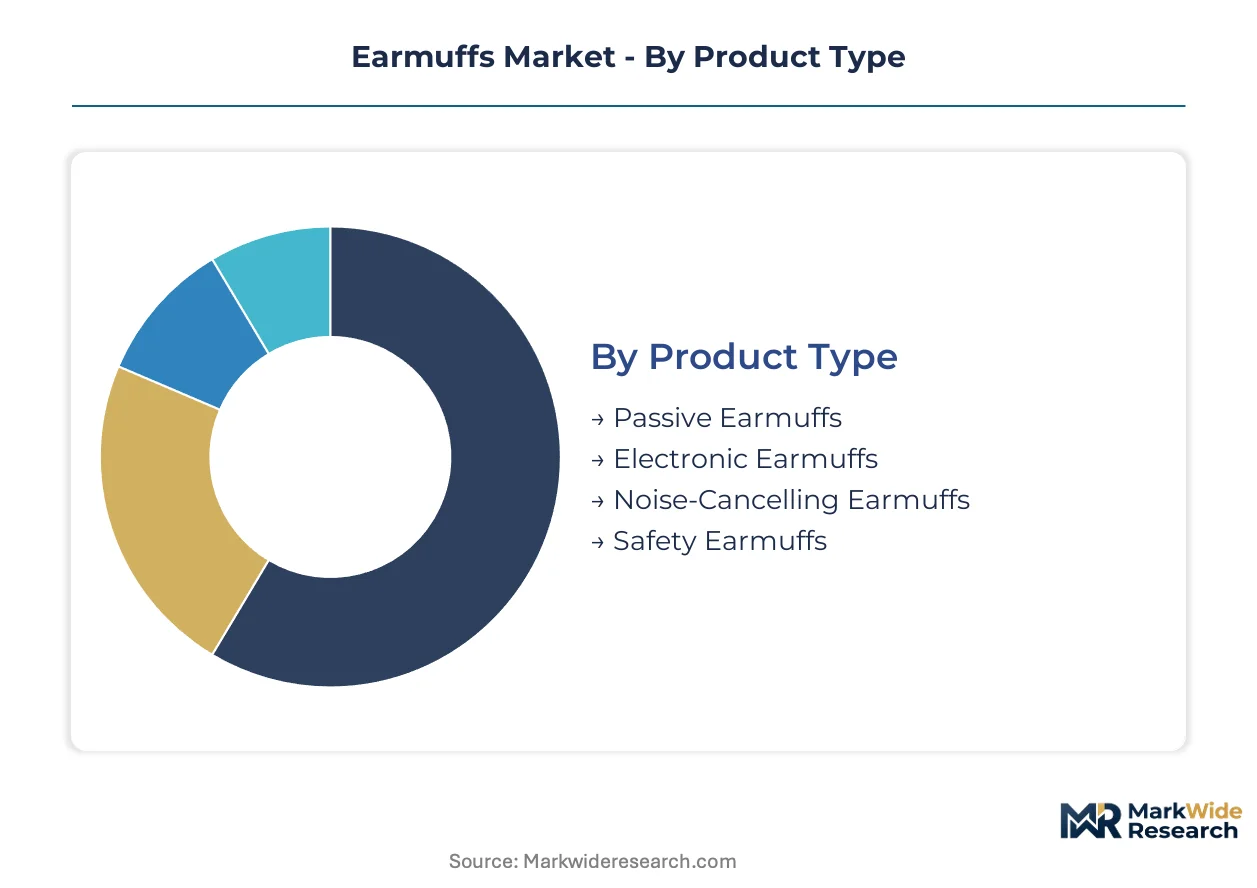
Segmentation in the earmuffs market determines procurement pathways, certification requirements, and margin structures. Industrial buyers prioritize attenuation ratings and regulatory compliance, while recreational users weigh situational awareness features against comfort metrics. Understanding these divides enables targeted positioning across divergent sales channels.
Product Type:
After-sales-service intensity varies sharply across product types, with electronic variants requiring firmware updates, battery replacement programs, and amplifier recalibration services that passive designs never demand.
- Passive Earmuffs:Rigid thermoplastic cups encase multi-layer acoustic foam without electronic components, delivering 15–35 decibel attenuation through purely mechanical damping. Demand concentrates among petrochemical facilities in Texas and Louisiana where OSHA mandates drive bulk procurement of zero-power-dependent protection for extended shifts.
- Electronic Earmuffs:Microphone arrays, amplifiers, and circuit boards enable ambient sound detection while blocking hazardous impulse noise. Hunters in the United States and tactical operators in Germany are displacing passive designs fastest, requiring programmable gain control for accident prevention in variable acoustic environments.
- Noise-Cancelling Earmuffs:Active circuitry generates inverse sound waves to cancel low-frequency drone, adding battery dependency and electronic complexity. Aviation ground crews and music production professionals specify these for sustained exposure to predictable noise signatures.
- Safety Earmuffs:Certified to higher attenuation ratings with reinforced headbands and replaceable cushions for industrial compliance. Metal fabrication facilities specify these through safety supply houses that bundle fit-testing services with equipment procurement.
Passive Earmuffs holds the largest share; momentum sits with Electronic Earmuffs.
Application:
Cost tier stratification separates premium electronic systems from commodity passive protection, with application-specific feature sets determining price positioning across industrial, recreational, and professional audio segments.
- Industrial Use:Heavy manufacturing and construction sites mandate certified hearing protection with documented attenuation performance. REACH compliance obligations in European automotive plants are accelerating migration to isocyanate-free foam chemistries ahead of substance restriction deadlines.
- Hunting:Amplified sound detection prevents accidents while protecting against firearm impulse noise. United States enthusiasts are adopting directional microphone arrays with wireless connectivity fastest, replacing separate communication headsets with unified headgear.
- Aviation:Ground crew and cockpit applications require active noise cancellation for sustained low-frequency exposure. German aerospace end-users specify modular certification covering both passive and electronic variants to simplify cross-border procurement.
- Music Events:High-fidelity attenuation preserves sound quality while reducing decibel exposure for performers and technical staff. Musicians prioritize comfort during multi-hour performances over maximum noise reduction ratings.
Industrial Use commands the greatest volume; Music Events is climbing the fastest as festival safety standards tighten.
End User:
Customer type determines distribution channel selection, with construction workers procuring through industrial safety distributors and general consumers accessing retail and direct-to-consumer platforms.
- Construction Workers:Supervisors specify electronic variants for situational awareness while crews wear passive protection for cost efficiency. OSHA Hearing Conservation Amendments are compressing replacement cycles for certified equipment across United States metal fabrication sites.
- Musicians:Custom-molded and high-fidelity attenuating designs address hearing preservation without compromising performance monitoring. French aerospace and German automotive supply chains are unbundling third-party occupational audiologist services from equipment procurement.
- Hunters:Bluetooth-enabled headgear combining hearing protection with radio interoperability addresses unmet needs currently served by separate equipment layers. Emergency responder segments in firefighter and tactical applications are adopting integrated communications-enabled designs.
- General Consumers:Price-sensitive demand concentrates in lawn care and DIY applications with lower attenuation requirements. Southeast Asian assembly scale-up in Vietnamese and Thai facilities is reducing landed costs for volume buyers in European channels.
Construction Workers represent the dominant segment; Hunters are gaining share fastest through electronic feature adoption.
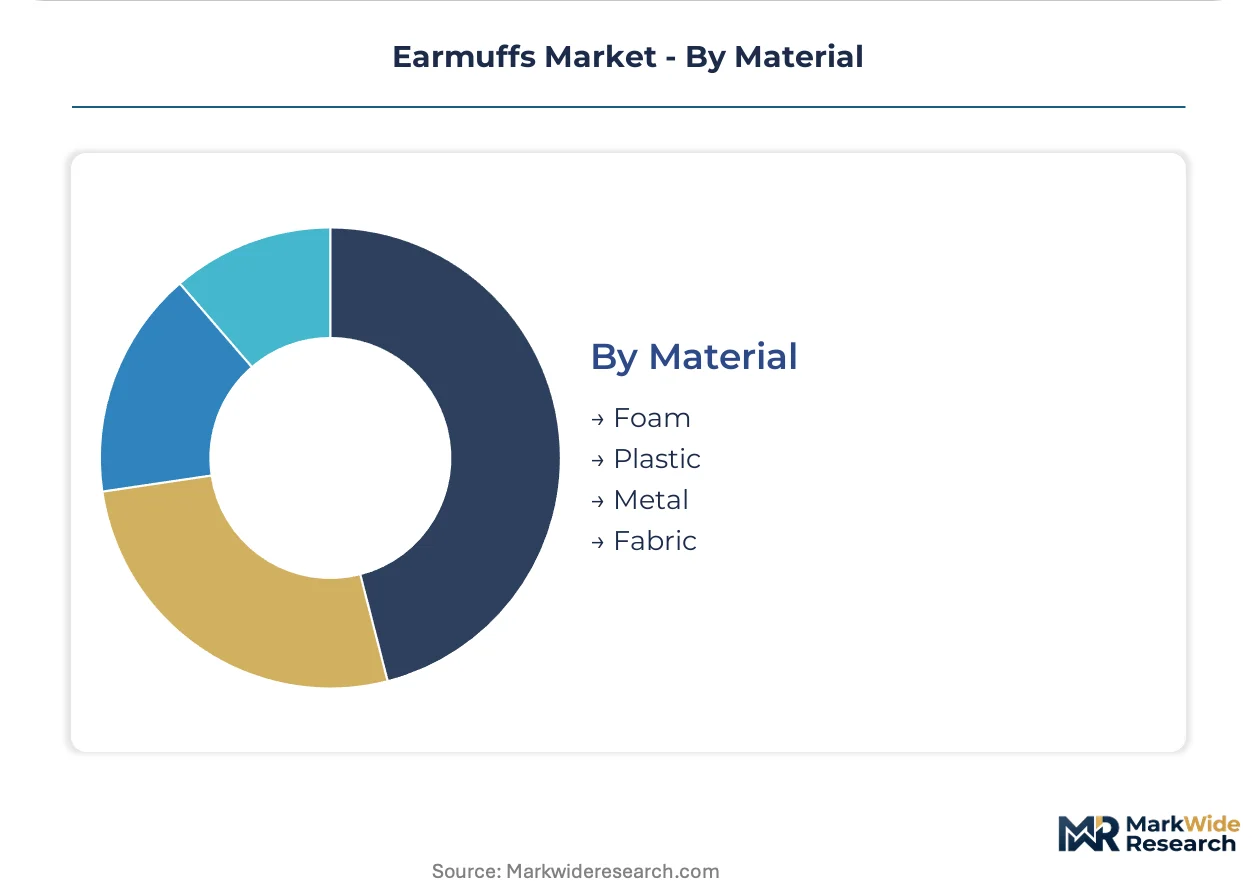
Material:
Supply concentration for acoustic foam and thermoplastic shells directly shapes manufacturing economics, with REACH-driven chemistry reformulation altering competitive positioning across European supply chains.
- Foam:Viscoelastic polyurethane cushions provide the primary acoustic seal and comfort interface. Reformulation to isocyanate-free alternatives is accelerating ahead of regulatory deadlines, with passive earmuff lines facing steepest retooling requirements.
- Plastic:Injection-molded ABS or polypropylene shells encase damping materials and define structural durability. Petrochemical input volatility in crude oil-linked resin prices compresses margins for manufacturers locked into annual supply contracts.
- Metal:Reinforced headband components and adjustment mechanisms deliver mechanical longevity for industrial applications. Firefighter and emergency responder segments specify metal-reinforced designs for integrated communications headgear.
- Fabric:Moisture-wicking covers and replaceable hygiene kits extend wearable life in high-perspiration environments. Southeast Asian facilities are expanding die-cutting and fabric lamination capacity to serve volume European industrial channels.
Foam dominates material value; Plastic is expanding most quickly as electronic variant housing demand rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injection-molded shell production concentrates in East Asian facilities, while certification testing and high-attenuation specification development remain anchored in North American and European industrial safety corridors.
United States
OSHA Hearing Conservation Amendments drive bulk procurement of certified passive earmuffs across Texas and Louisiana petrochemical corridors. The agency mandates documented attenuation performance for metal fabrication facilities exceeding 85 decibel exposure limits. Houston industrial distributors bundle third-party occupational audiologist services with equipment contracts to verify real-world noise reduction ratings.
Germany
REACH compliance obligations accelerate reformulation of viscoelastic foam chemistries ahead of substance restriction deadlines. ECHA substance restrictions force migration to isocyanate-free polyurethane alternatives across automotive supply chains. Bavarian aerospace end-users specify modular CE marking certification covering both passive and electronic variants to simplify procurement across EU member states.
China
Domestic manufacturing hubs scale die-cutting and acoustic foam molding capacity while narrowing cost advantages against Southeast Asian competitors. GB standards for personal protective equipment establish testing protocols that diverge from ANSI and CE frameworks. Yangtze River Delta facilities supply volume buyers in European industrial channels with injection-molded ABS shell components.
India
State-level factory inspectorates in Maharashtra and Gujarat implement hearing conservation protocols mirroring OSHA frameworks. BIS certification requirements for industrial safety equipment create compliance barriers for uncertified imports. Mumbai-Pune manufacturing clusters generate first-mover procurement advantages for suppliers holding valid test reports under harmonized noise exposure limits.
Vietnam
Assembly facilities expand fabric lamination and cushion molding operations to serve European volume buyers seeking landed cost reductions. The country's national standards body develops PPE technical regulations aligned with EU market access requirements. Ho Chi Minh City industrial zones attract die-cutting equipment transfers from Chinese manufacturers facing margin compression.
Earmuffs Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying acoustic foam, injection-molded shells, and amplifier circuit boards. The vendor base organizes around three strategic archetypes: diversified industrial safety conglomerates with cross-product certification leverage, mid-scale specialists concentrating on single-use-case designs, and contract manufacturers serving private-label distributors. Consolidation pressure concentrates among electronic variant developers seeking amplifier engineering talent, while passive earmuff production fragments across Southeast Asian assembly facilities. Competitive moves center on dual-earcup architecture patent licensing and safety supply house distribution partnerships.
Among diversified industrial safety conglomerates, 3M and Honeywell occupy positions spanning passive and electronic product architectures, while MSA Safety represents the integrated communications-enabled headgear specialist tier. These entities exemplify contrasting approaches to certification-driven market access: 3M leverages dual-earcup patent portfolios for premium positioning, Honeywell anchors North American distribution through safety supply house relationships, and MSA Safety concentrates on firefighter and emergency responder segments requiring radio interoperability.
| Leading Market Players |
|---|
| Protective Industrial Products |
| Delta Plus |
| 3M |
| ADCO Hearing Products |
| Centurion Safety Products |
| Honeywell |
| Moldex-Metric |
| Radians |
| MSA Safety |
| Others |
Supply Flow & Price Mechanics
Ho Chi Minh City industrial zones are absorbing die-cutting equipment transfers from Chinese manufacturers facing margin compression, concentrating acoustic foam molding capacity that feeds downstream pricing power to European volume buyers. This geographic shift compresses landed costs for passive earmuff assemblies while electronic variants retain premium positioning through amplifier circuit complexity.
Pricing Analysis
OSHA Hearing Conservation Amendments dictate the pricing tier structure across United States industrial channels, separating certified high-attenuation passive designs from commodity lawn-care alternatives. Three-tier pricing structure across premium electronic, standard certified passive, and economy unbranded levels reflects certification grade and after-sales fit-testing bundling. Cost compression in standard passive tiers is intensifying because Vietnamese assembly scale-up reduces labor-component differentials. Petrochemical facilities in Texas and Louisiana exhibit least price sensitivity due to mandated procurement budgets, while general consumers in DIY segments drive volume at thin margins.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for ABS shell injection molders serving North American distributors. Manufacturing concentrates in China, Vietnam, and Thailand for acoustic foam molding and fabric lamination operations. Raw material dependencies rest on polypropylene resin, lithium-cell amplifiers for electronic variants, and isocyanate-free polyurethane cushion chemistries. Single-source vulnerability concentrates in East Asian lithium refiners supplying electronic earmuff batteries. Distribution runs through industrial safety supply houses in North America and specialized PPE distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from integrated communications-enabled headgear that combines hearing protection with radio interoperability, collapsing separate equipment layers into unified systems.
For Market Incumbents: Insulate certified product lines by deepening backward integration into acoustic foam molding in Vietnamese facilities to match Southeast Asian cost structures. Accelerate ANSI S3.19 pre-certification testing for electronic variants to compress market entry timelines against amplifier engineering talent scarcity. Patent licensing for dual-earcup architectures remains a defendable moat against commoditization. For New Entrants and Emerging Players: Establish a beachhead in Indian industrial safety channels by securing BIS certification ahead of state-level factory inspectorate enforcement in Maharashtra and Gujarat. Target firefighter communications integration segments where Bluetooth-enabled headgear addresses unmet radio interoperability needs currently served by separate equipment layers. Partner with European safety supply houses for modular CE marking distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because industrial safety mandate expansion across emerging economies creates durable demand for certified hearing protection. Acquisition targets should emphasize electronic variant developers with captive amplifier engineering talent and existing ANSI laboratory relationships. Watch for harmonized noise exposure limit adoption in Indian state regulations as the inflection signal for addressable demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acoustic Foam Molding | Vietnamese capacity absorption reduces landed cost exposure for European volume buyers. |
| ANSI S3.19 Pre-Certification Investment | Limited North American laboratory capacity creates bottlenecks for electronic variant market entry. |
| Bluetooth Communications Integration | Firefighter and tactical segments currently layer separate radio equipment atop passive protection. |
| BIS Certification Advancement | Indian state-level factory inspectorates in Maharashtra and Gujarat mirror OSHA enforcement frameworks. |
| Isocyanate-Free Chemistry Migration | REACH substance restrictions force reformulation of viscoelastic foam cushions ahead of deadlines. |
Methodological Framework
Operator-level perspectives from safety procurement managers at petrochemical facilities, industrial distributors, acoustic foam molders, and occupational audiologists anchored the qualitative base. Primary interviews combined with secondary validation from OSHA enforcement databases, EU PPE Regulation filings, customs trade records for ABS resin and lithium-cell imports, and BIS certification registries. Bottom-up unit economics for passive and electronic variant bill-of-materials were triangulated against top-down market sizing from industrial safety distributor revenue disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying discrete year endpoints. Segmentation dimensions modeled include product architecture, application environment, end-user occupational category, material chemistry compliance tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates, with electronic variant adoption curves and industrial safety mandate enforcement timelines as key industry-specific inputs.
Stress conditions across petrochemical input volatility, lithium-cell export control disruptions, and REACH substance restriction acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization adoption rates and substitution elasticity between passive and electronic designs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Ship Life-Saving Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market