
 Light Therapy Glasses Market | 2026-2036
Light Therapy Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Light Therapy Glasses Market Foresight
Aftermarket service revenue is rewriting profit expectations across the light therapy glasses value chain. Philips sustains its position through backward integration into LED component sourcing. Luminette differentiates via specialized prescription-grade optics for circadian rhythm disorders. Carex Health Brands competes on volume manufacturing scale for non-prescription retail channels.
Light therapy glasses are wearable photobiomodulation devices that emit calibrated luminous flux, typically within the 480 nm blue-enriched or broad-spectrum white range, to modulate melatonin suppression and circadian phase alignment. These devices serve clinical and consumer markets seeking non-pharmacological intervention for seasonal affective disorder, delayed sleep phase syndrome, and jet lag recovery. Wearable formats command the dominant margin pool due to all-day convenience and discrete form factors, while LED technology anchors volume production through thermal efficiency and spectral tunability. Prescription segments occupy the premium tier as clinicians increasingly validate light dosing protocols for patient-specific circadian pathologies.
FDA regulates light therapy glasses as Class II medical devices when marketed for diagnosed mood or sleep disorders, while the FCC governs embedded wireless connectivity for companion apps. ISO 13485 certification shapes supplier qualification for brands seeking hospital and clinic procurement channels. Stakeholders must monitor evolving reimbursement codes for digital therapeutics as payors reassess coverage for non-invasive neuromodulation devices.
Market Dynamics
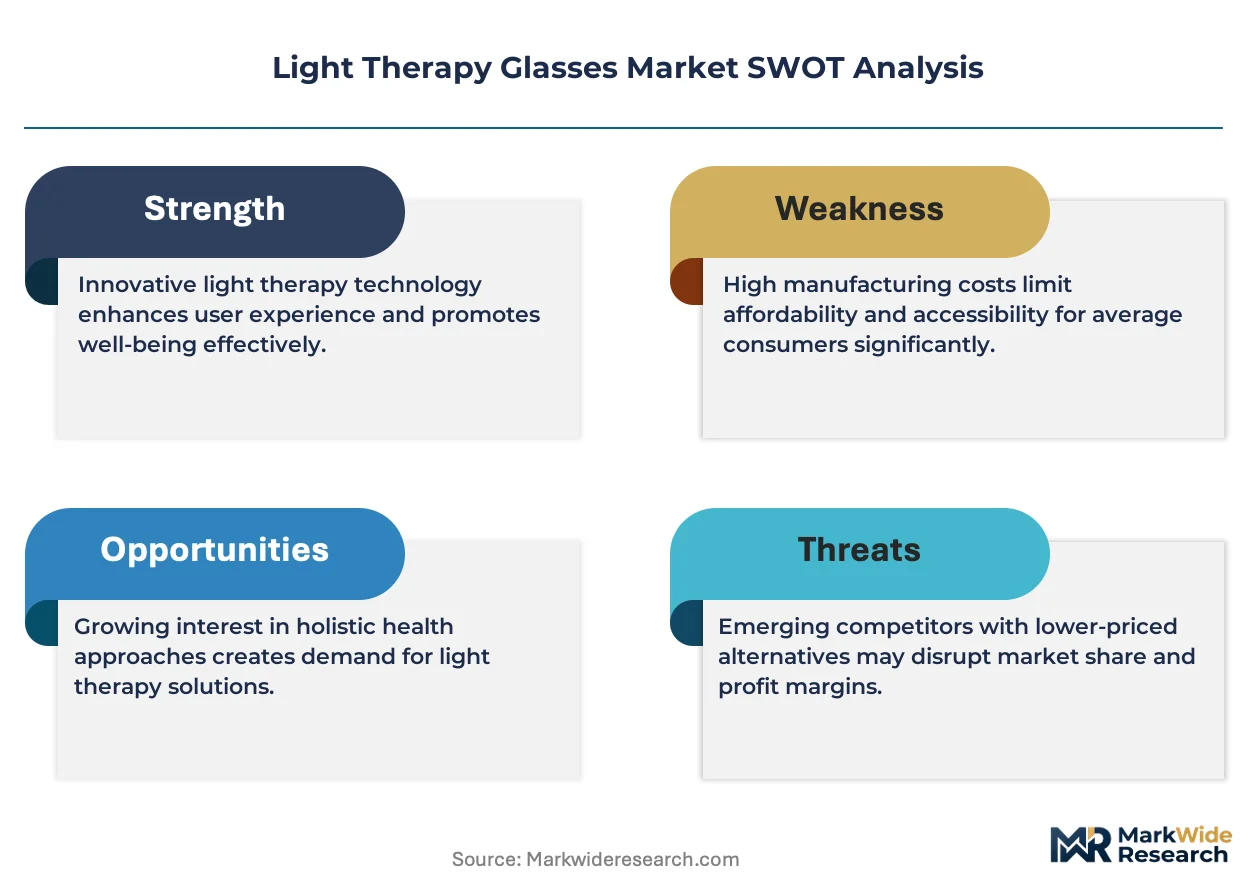
FDA's bifurcated classification regime—treating wellness claims separately from diagnosed disorder indications—is fragmenting go-to-market strategies and forcing dual-track development pipelines across the light therapy glasses sector.
Growth Catalysts
- Shift Worker Sleep Disorder Protocols:Occupational health programs at logistics hubs and healthcare systems are embedding circadian light intervention into fatigue management frameworks, expanding reimbursable prescription pathways.
- ISO 13485 Certification Expansion:Hospital procurement departments are mandating quality management system compliance for wearable photobiomodulation devices, elevating supplier qualification barriers that favor established manufacturers.
- Blue-Enriched LED Efficiency Gains:Thermal management improvements in 480 nm emitter arrays are reducing form factor constraints and enabling all-day wearable designs without skin temperature elevation risks.
Market Restraints
- Blue Light Hazard Uncertainty:Retinal phototoxicity research gaps are generating precautionary labeling requirements from France's ANSM and Germany's BfArM, complicating consumer marketing claims.
- GaN Substrate Supply Concentration:High-brightness LED fabrication depends on gallium nitride wafer supply chains concentrated in East Asian foundries, exposing manufacturers to input cost volatility and allocation constraints.
- Reimbursement Code Fragmentation:CPT and HCPCS coding inconsistencies across US commercial payors and Medicare Advantage plans are delaying patient access and compressing pricing power for prescription-grade devices.
Strategic Opportunities
- Jet Lag Management for Aviation Crews:FAA-mandated fatigue risk management systems are creating institutional procurement channels for circadian alignment wearables at major US and European carriers.
- Digital Therapeutic Convergence:Integration with sleep tracking algorithms and companion apps is enabling outcome-based contracting models with self-insured employers seeking measurable absenteeism reductions.
- Japan's Aging Demographics:METI's Silver Innovation initiatives are subsidizing non-pharmacological intervention adoption in eldercare facilities, opening volume channels for simplified operation designs.
Industry Challenges
- Clinical Validation Talent Scarcity:Recruitment of circadian chronobiologists and photobiology specialists for protocol design is constraining trial timelines for 510(k) submissions.
- Multi-Jurisdiction Registration Burden:Simultaneous FDA Class II, CE MDR, and PMDA filings are stretching regulatory affairs bandwidth and delaying commercial launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Therapy Glasses Market |
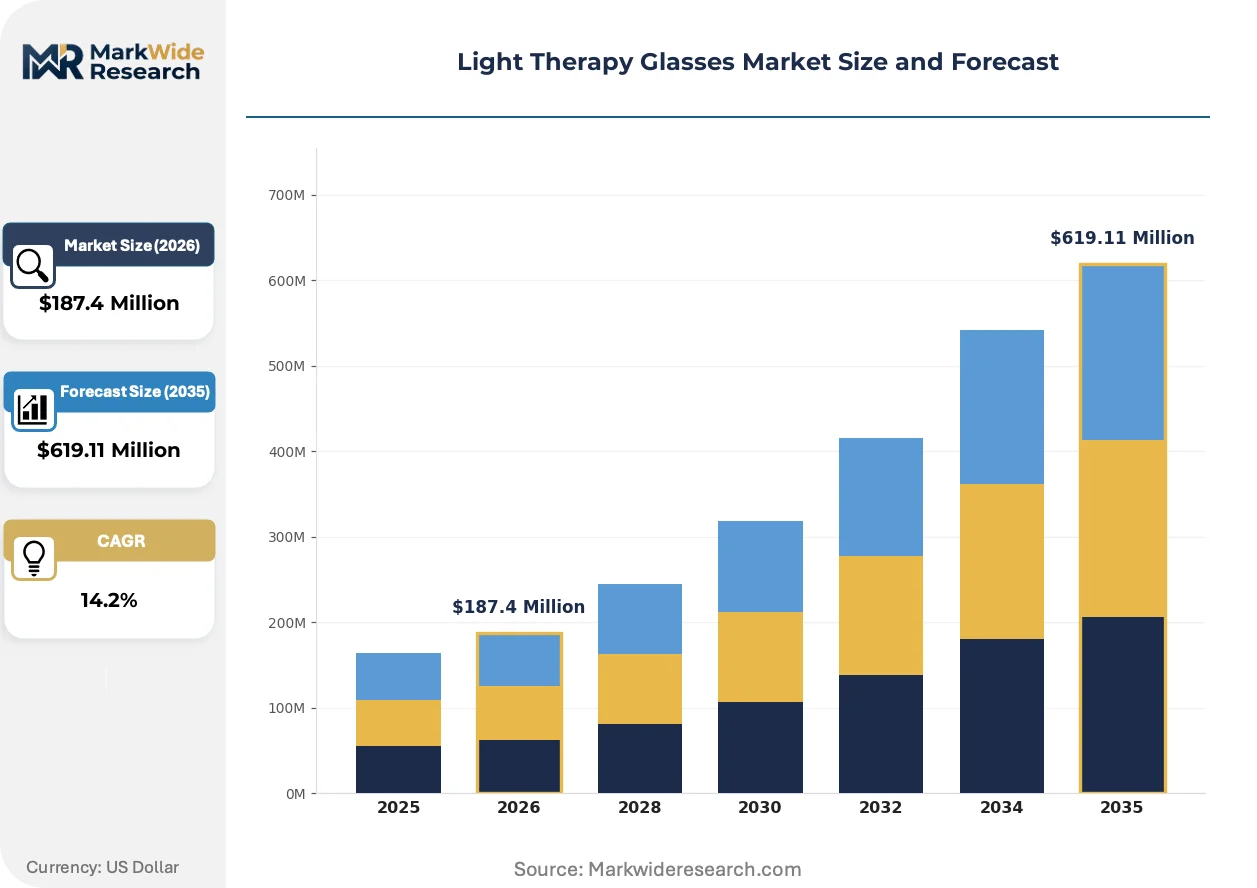
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Portable, Prescription, Non-Prescription Technology: LED, OLED, Fluorescent, Infrared Application: Sleep Disorders, Mood Enhancement, Skin Treatments, Pain Relief End User: Individuals, Clinics, Hospitals, Wellness Centers |
| Companies Covered | Verilux, Northern Light Technologies, Philips, Re-Timer, Luminette, Circadian Optics, Carex Health Brands, CareWear, Beurer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Therapy Glasses Market Shifts & Advancements
Spectral tunability and embedded biometric feedback are converging to transform light therapy glasses from passive irradiance delivery systems into closed-loop circadian intervention platforms with measurable adherence tracking.
Micro-LED emitter arrays with pixel-level spectral control are digitizing dosing precision for personalized chronotherapy protocols. Sleep medicine clinics and occupational health departments are piloting these systems for patient-specific phase response curve calibration. The technology is digitizing what was previously analog light exposure, enabling software-defined treatment parameter adjustment without hardware replacement cycles.
EU MDR's tightened clinical evidence requirements for wearable medical devices are extending technical documentation timelines and mandating post-market surveillance infrastructure. Manufacturers are restructuring quality management systems to accommodate periodic safety updates and vigilance reporting obligations. Prescription-grade product categories face the steepest compliance cost escalation, accelerating consolidation among firms with established notified body relationships.
Direct-to-clinic distribution models are displacing traditional durable medical equipment channels as sleep centers and neurology practices seek margin capture on device dispensing. Specialty distributors with clinical education capabilities are capturing volume from generalist medical supply houses. Germany and Japan exhibit the most pronounced channel restructuring, where physician dispensing laws facilitate point-of-care revenue models.
Light Therapy Glasses Market Segmentation
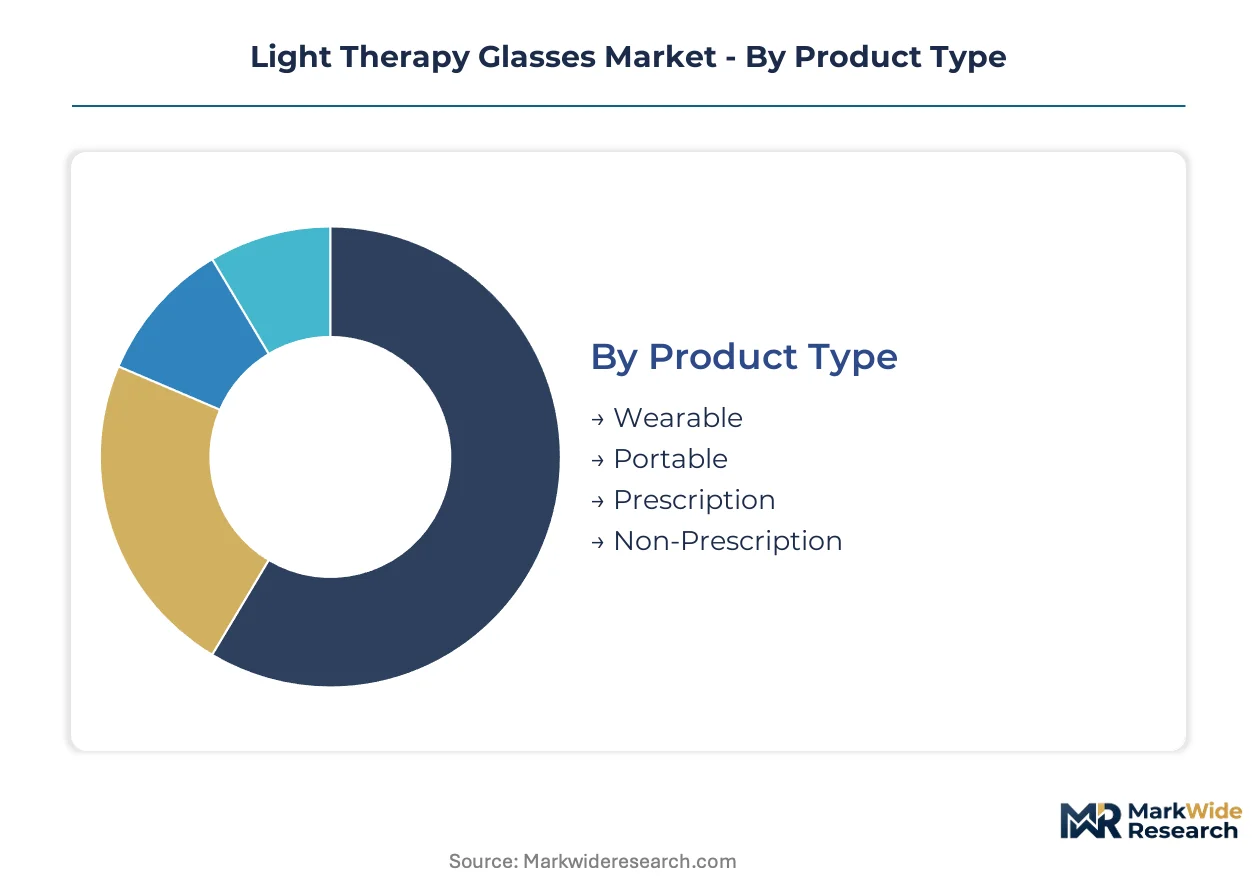
Segmentation in light therapy glasses reveals how clinical validation tiers, emitter technologies, and distribution channels partition margin pools. Product positioning decisions hinge on whether devices target reimbursable prescription pathways or direct-to-consumer wellness markets.
Product Type:
Cost tier differentiation separates disposable income accessibility from institutional procurement budgets across the four product formats.
- Wearable:Wrist-mounted and frame-integrated designs embed 480 nm blue-enriched emitters with lithium-polymer power management. Shift workers at logistics hubs in Germany and Japan drive volume as occupational health programs subsidize circadian intervention devices.
- Portable:Desktop and travel-oriented units with adjustable stands deliver higher luminous flux for clinical-grade dosing protocols. Sleep medicine clinics in the United States concentrate procurement as physicians seek reimbursable treatment modalities for delayed sleep phase syndrome.
- Prescription:FDA Class II devices with 510(k) clearance for diagnosed mood or sleep disorders command premium positioning through physician dispensing channels.
- Non-Prescription:Wellness-claim devices bypass regulatory scrutiny for jet lag and seasonal mood support, competing on retail shelf placement and direct-to-consumer marketing.
Wearable holds installed capacity. Prescription is rotating up the share rankings.
Technology:
Emitter maturity and spectral precision define competitive positioning across the four illumination technologies.
- LED:Gallium nitride-based arrays dominate volume production through thermal efficiency and 20,000-hour operational lifespans. East Asian foundries supply the substrate wafers, creating input cost exposure for manufacturers without captive sourcing arrangements.
- OLED:Organic emitter layers enable conformal surface illumination for curved frame designs. Premium eyewear brands in Japan pilot these systems for aesthetic differentiation in consumer wellness channels.
- Fluorescent:Legacy tube-based systems persist in clinical installations requiring broad-spectrum white output for photobiomodulation research protocols.
- Infrared:Near-infrared wavelengths target dermal penetration for skin treatment applications, occupying niche positioning within aesthetic medicine practices.
LED holds installed capacity. OLED is climbing the fastest.
Application:
Clinical indication breadth determines reimbursement eligibility and regulatory pathway complexity for each therapeutic target.
- Sleep Disorders:Circadian phase alignment for shift work disorder and delayed sleep phase syndrome represents the most validated indication with expanding CPT code coverage. Hospital sleep centers in the United States and Germany anchor institutional procurement volume.
- Mood Enhancement:Seasonal affective disorder intervention commands prescription-grade device requirements in jurisdictions with formalized light therapy protocols. Nordic healthcare systems subsidize winter treatment programs.
- Skin Treatments:Photobiomodulation for acne and anti-aging applications competes in aesthetic medicine channels with less stringent regulatory barriers than neurological indications.
- Pain Relief:Near-infrared penetration for musculoskeletal discomfort occupies experimental positioning with limited clinical trial infrastructure supporting reimbursement claims.
Sleep Disorders holds installed capacity. Mood Enhancement is gaining share fastest.
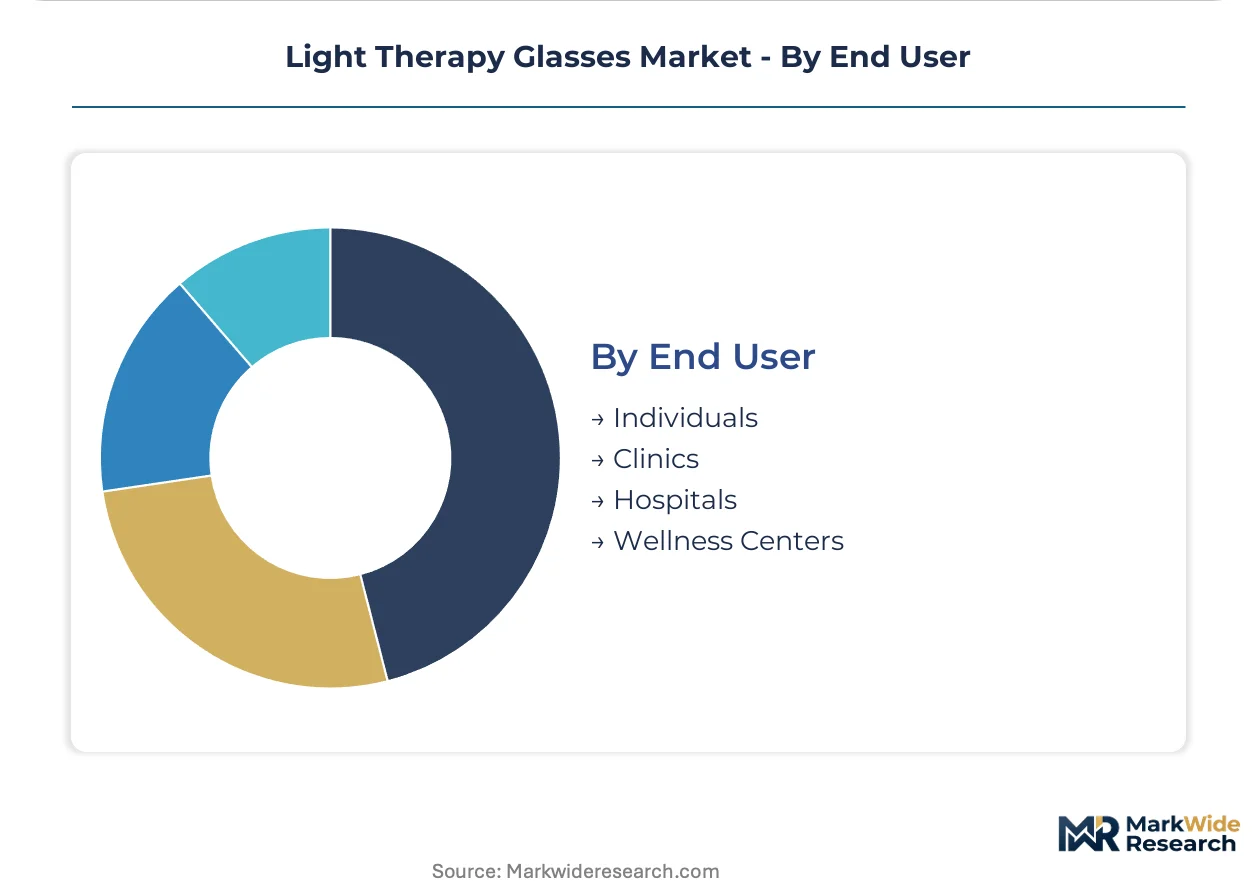
End User:
Customer type segmentation maps to divergent purchasing cycles, price sensitivity, and post-sale service expectations.
- Individuals:Direct-to-consumer purchasers prioritize discrete form factors and companion app integration for adherence tracking. Online retail channels in the United States and Japan capture the highest transaction velocity.
- Clinics:Sleep medicine and neurology practices seek margin capture through physician dispensing models enabled by specialty distributors with clinical education capabilities.
- Hospitals:Procurement departments mandate ISO 13485 quality management certification and post-market surveillance infrastructure for wearable medical device categories.
- Wellness Centers:Corporate fatigue management programs and eldercare facilities in Japan source simplified operation designs through METI-subsidized Silver Innovation procurement channels.
Individuals holds installed capacity. Clinics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German hospital procurement departments demand ISO 13485-certified devices at volume discounts, while Japanese consumers accept premium positioning for discrete wearable designs. United States buyers split between institutional reimbursement channels and direct-to-consumer wellness markets with divergent willingness-to-pay thresholds.
United States
FAA-mandated fatigue risk management systems at major carriers are creating institutional procurement channels for circadian alignment wearables. FDA's bifurcated classification regime treats wellness claims separately from diagnosed disorder indications, fragmenting go-to-market strategies. Sleep medicine clinics in Boston and Stanford anchor prescription-grade device dispensing for shift worker populations.
Germany
Occupational health programs at logistics hubs subsidize circadian intervention devices for warehouse and healthcare shift workers. BfArM precautionary labeling requirements for blue light hazard uncertainty complicate consumer marketing claims. The Ruhr industrial corridor concentrates manufacturing scale for LED-based volume production serving European hospital procurement channels.
Japan
METI's Silver Innovation initiatives subsidize non-pharmacological intervention adoption in eldercare facilities, opening volume channels for simplified operation designs. PMDA filings stretch regulatory affairs bandwidth for wearable medical device categories. The Kanto region around Tokyo drives premium consumer demand for aesthetic-integrated wearable formats with companion app functionality.
United Kingdom
NHS sleep centers pilot reimbursable light therapy protocols for seasonal affective disorder in winter treatment programs. MHRA alignment with EU MDR tightened clinical evidence requirements extends technical documentation timelines. London-based specialty distributors with clinical education capabilities capture volume from generalist medical supply houses.
France
ANSM precautionary labeling requirements for retinal phototoxicity research gaps generate marketing constraints for blue-enriched LED devices. Occupational health programs at Paris-Charles de Gaulle hub airlines embed circadian light intervention into crew fatigue management frameworks. The Île-de-France region concentrates demand for prescription-grade optics through physician dispensing channels.
Light Therapy Glasses Market Competitive Landscape
Vertically integrated health technology conglomerates and specialized photobiomodulation developers split the market between volume manufacturing scale and clinical validation depth. The vendor base concentrates around three strategic archetypes: LED component backward integrators securing gallium nitride wafer supply chains, prescription-grade optics specialists targeting reimbursable medical channels, and direct-to-consumer wellness brands competing on retail shelf placement. Dominant competitive moves include ISO 13485 certification expansion for hospital procurement qualification and companion app integration enabling outcome-based contracting with self-insured employers.
Among North American health technology developers, Verilux and Northern Light Technologies occupy positions within the wellness-channel archetype, while Philips anchors the vertically integrated tier through captive LED component sourcing. Luminette represents the prescription-grade specialization vector with physician dispensing channel focus. These three named entities exemplify how competitive positioning stratifies across regulatory pathway selection and distribution model architecture rather than product specification alone.
| Leading Market Players |
|---|
| Verilux |
| Northern Light Technologies |
| Philips |
| Re-Timer |
| Luminette |
| Circadian Optics |
| Carex Health Brands |
| CareWear |
| Beurer |
| Others |
Supply & Pricing Matrix
East Asian gallium nitride wafer foundries anchor upstream supply for LED emitter arrays, concentrating margin capture among manufacturers with captive sourcing arrangements while forcing price-sensitive assemblers toward spot-market volatility. This substrate dependency stratifies downstream pricing power between vertically integrated health technology conglomerates and assembly-dependent wellness brands competing on retail velocity.
Pricing Analysis
Aftermarket service revenue streams including extended calibration contracts and companion app subscriptions now drive lifetime value for prescription-grade device portfolios. Three-tier pricing structure across premium prescription, standard clinical, and economy wellness levels separates FDA-cleared 510(k) devices from CE-marked general wellness units. Cost compression in the non-prescription tier intensifies as direct-to-consumer brands crowd retail shelves with undifferentiated 480 nm emitter specifications. Hospital procurement departments in Germany and Japan exhibit lowest price sensitivity due to reimbursable pathway anchoring, while individual consumers in online channels demonstrate highest elasticity to promotional discounting.
Supply Chain Analysis
Supplier-financing facilities extended by East Asian substrate producers are restructuring working capital requirements for mid-tier LED array assemblers. GaN wafer fabrication concentrates in Taiwan, South Korea, and China, with lithium-polymer cell production feeding from Japanese and South Korean chemical suppliers. Single-source vulnerability in 480 nm blue-enriched emitter specification creates allocation risk during foundry capacity constraints. Distribution runs through specialty clinical distributors with ISO 13485 certification for hospital procurement channels, bypassing generalist medical supply houses in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital procurement departments and occupational health programs at major logistics carriers, fragmenting pricing leverage for device manufacturers without institutional contracting scale.
For Market Incumbents: Build regulatory moat through simultaneous FDA 510(k), CE MDR, and PMDA filing infrastructure to compress competitor launch timelines by 18-24 months. Deepen backward integration into GaN substrate sourcing to insulate margin from East Asian foundry allocation cycles. ISO 13485 certification expansion represents the critical lever for hospital procurement qualification against emerging wellness-channel entrants lacking quality management systems. For New Entrants and Emerging Players: Build out direct-to-clinic distribution capabilities with embedded clinical education services to capture physician dispensing margin pools in Germany and Japan where dispensing laws facilitate point-of-care revenue models. Jet lag management protocols for aviation crew fatigue systems represent the most penetrable white-space application, with FAA-mandated risk management frameworks creating institutional procurement channels at major US and European carriers. Companion app integration with sleep tracking algorithms enables outcome-based contracting entry with self-insured employers seeking absenteeism reduction metrics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wellness-device assemblers lacking clinical validation infrastructure for prescription pathway migration. Five-to-ten year viability hinges on reimbursement code consolidation for digital therapeutics as payors reassess coverage for non-invasive neuromodulation. The signal to watch is CPT and HCPCS coding harmonization across US commercial payors and Medicare Advantage plans, which would unlock patient access expansion and pricing power recovery for prescription-grade portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Hospital procurement departments in Germany and Japan mandate quality management compliance for wearable medical device categories. |
| Companion App Development | Integration with sleep tracking algorithms enables outcome-based contracting with self-insured employers seeking measurable absenteeism reductions. |
| Multi-Jurisdiction Regulatory Filing | Simultaneous FDA, CE MDR, and PMDA submissions compress competitor commercial launch windows by 18-24 months. |
| Direct-to-Clinic Distribution Buildout | Specialty distributors with clinical education capabilities capture volume from generalist medical supply houses in physician dispensing markets. |
| GaN Substrate Backward Integration | Captive sourcing arrangements insulate LED emitter manufacturing from East Asian foundry allocation volatility and cost spikes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with sleep medicine clinicians, hospital procurement managers, occupational health directors at logistics carriers, biomedical engineers, and regulatory affairs specialists at device manufacturers. Secondary validation drew from FDA 510(k) filings, PMDA submission databases, CE MDR technical documentation, hospital GPO contract records, and airline fatigue risk management system procurement disclosures. Bottom-up emitter array production estimates triangulated against top-down reimbursable device dispensing volume across US, German, and Japanese channels.
Calibration across the projection horizon employed scenario-weighted probability distributions for regulatory pathway timelines and reimbursement code adoption curves. Segmentation dimensions modeled included product format tier, prescription versus wellness regulatory classification, emitter technology maturity, clinical indication breadth, and end-user procurement archetype. CAGRs derived from installed base growth rates adjusted for replacement cycle compression in wearable formats and spectral tunability upgrade demand. Industry-specific inputs incorporated shift worker population expansion at logistics hubs and METI Silver Innovation subsidy allocation for eldercare facility adoption.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier assemblers or sudden CPT coding harmonization would shift outcomes materially. Macroeconomic contraction in consumer health technology spending, retinal phototoxicity regulatory restriction expansion by ANSM or BfArM, or GaN substrate supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
North America Vision Care Market